
 Global Automotive Active Window Display Market | 2026-2036
Global Automotive Active Window Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Active Window Display Market Intelligence
A shift from outsourced component sourcing to in-house system development is consolidating the value chain. Large Tier-1 suppliers like Continental AG leverage their established relationships with OEMs to integrate these displays into broader cockpit electronics. Robert Bosch GmbH specializes in the underlying control units and software that power the display functionality. Meanwhile, MicroVision, Inc. differentiates through its expertise in projection display technologies, a key area of innovation.
Automotive active window displays are transparent electronic panels integrated into vehicle glass, such as windshields. These systems project dynamic information using technologies like OLEDs, requiring precise control over luminance to ensure driver visibility. Their purpose is to deliver augmented reality navigation and safety alerts. Projection displays represent the fastest-growing product type, while adoption in autonomous vehicles is creating new use cases for passenger-facing infotainment and external communication systems.
Safety standards from regulators like the U.S. National Highway Traffic Safety Administration (NHTSA) and compliance with UNECE regulations on driver distraction govern system design. In China, GB standards for automotive electronics dictate market access and interoperability requirements. These frameworks mandate specific brightness levels and limit the type of content displayed to prevent cognitive overload. Stakeholder success depends on navigating these fragmented regulatory requirements while scaling manufacturing to meet OEM cost targets.
Market Dynamics
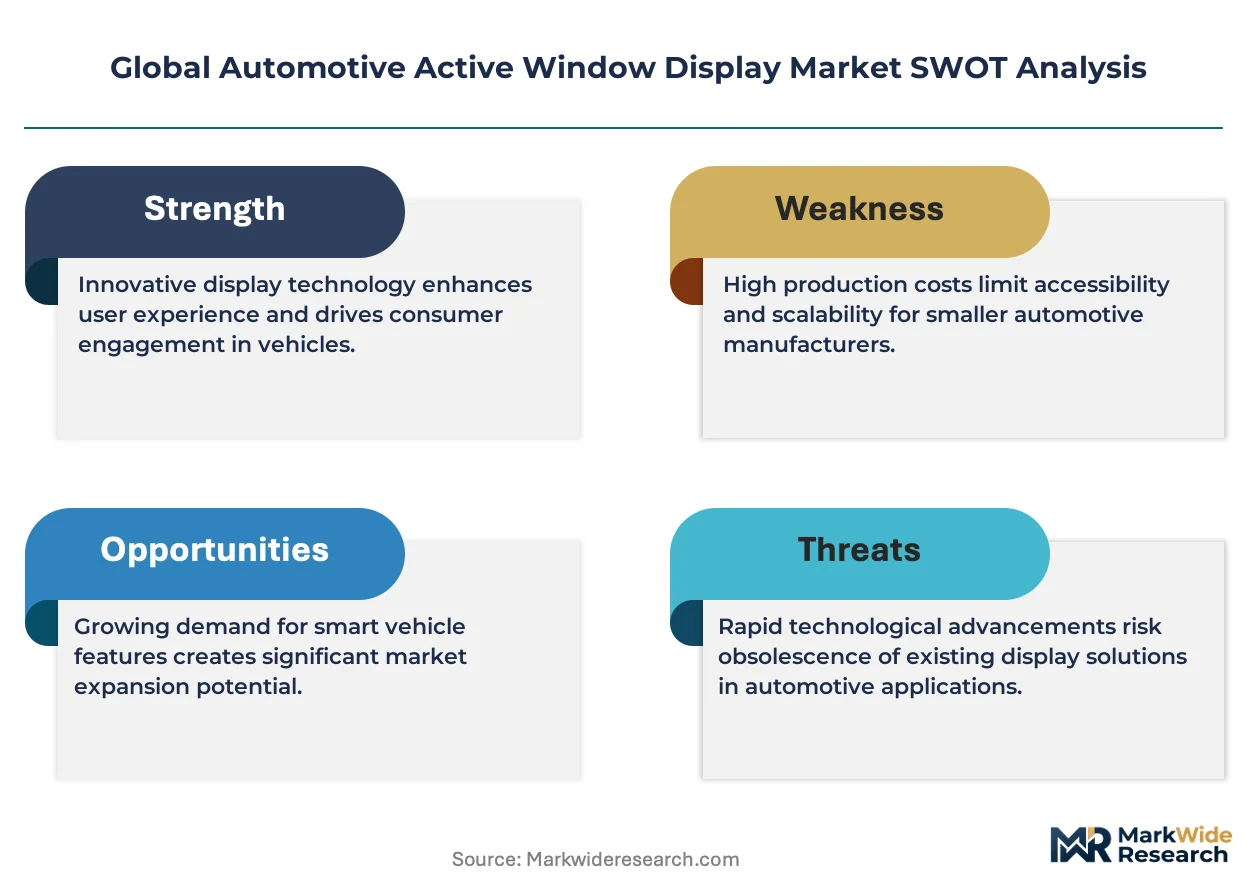
The market's central dynamic is the tension between rapid technological advancement in projection and Micro-LED displays and the fragmented, strict safety regulations governing their use, forcing a delicate balance between innovation and compliance for all stakeholders.
Growth Catalysts
- Electric Vehicle Integration:Demand from the EV segment for advanced human-machine interfaces to differentiate user experience and communicate vehicle status is a primary catalyst for adoption.
- Micro-LED Technology Maturation:Advances in Micro-LEDs enable brighter, more energy-efficient displays suitable for the variable lighting conditions of automotive environments, improving performance over legacy technologies.
- Premium Segment Demand:Automakers in Germany are integrating active window displays into new premium vehicle platforms, establishing them as a key feature for augmented reality navigation and safety alerts.
Market Restraints
- High System Cost:The production cost for large-format transparent OLED and Micro-LED panels remains a significant barrier to adoption in mass-market vehicle segments, limiting initial deployment to premium models.
- Technical Performance Trade-offs:Achieving sufficient luminance for clear daytime visibility while maintaining optical transparency for the driver presents a persistent engineering challenge for all display technologies.
- Regulatory Fragmentation:Disparate safety standards from the U.S. NHTSA, Europe's UNECE, and China's GB framework create complex compliance hurdles and increase development costs for global suppliers.
Strategic Opportunities
- Autonomous Vehicle Infotainment:The development of Level 4 and Level 5 autonomous vehicles creates a significant opportunity for large-format, passenger-facing window displays for entertainment and productivity.
- External Communication Systems:Vehicle-to-pedestrian communication applications, where displays on vehicle glass signal intent to pedestrians and other road users, represent a new use case for autonomous shuttles.
- Commercial Fleet Aftermarket:Retrofit projection display systems for commercial trucks and vans offer a channel to provide advanced navigation and safety alerts to a large, underpenetrated vehicle segment.
Industry Challenges
- Software Integration Complexity:Ensuring seamless, low-latency integration of display control units with diverse vehicle computing architectures and legacy network protocols is a major operational hurdle for suppliers.
- Manufacturing Scale-Up:Scaling the manufacturing of large, automotive-grade transparent display panels to meet OEM cost targets and volume requirements while maintaining high yields is a significant capital challenge.
- Thermal Management Design:Effectively dissipating heat from high-brightness projection units or integrated displays within the confined spaces of a vehicle's cockpit requires sophisticated thermal engineering solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Active Window Display Market |
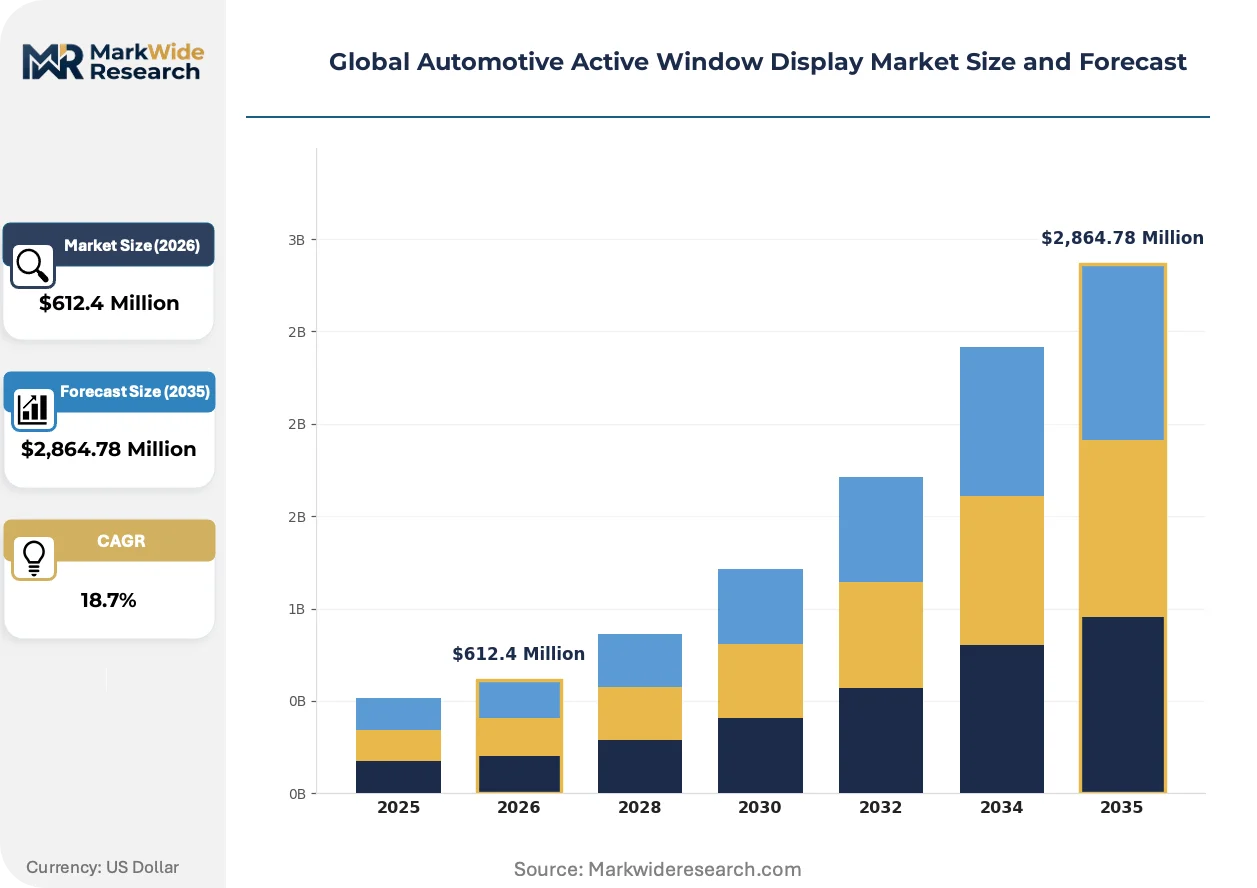
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Display, LCD Display, OLED Display, Projection Display Technology: Electrochromic, Liquid Crystal, Micro-LED, Electroluminescent Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | HARMAN International, MicroVision, Inc., Continental AG, Delphi Automotive Plc, Yazaki Corporation, Robert Bosch GmbH, TomTom International BV, Merck KGaA, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Active Window Display Market Strategic Shifts & Innovations
The convergence of advanced display hardware with sophisticated software frameworks is pushing active window systems beyond simple information projection. This evolution is transforming them into fully integrated augmented reality platforms that redefine the driver-vehicle interaction model.
Micro-LED technology provides the high brightness, deep contrast, and durability required for automotive-grade transparent displays. Premium automakers, particularly in Germany, are the earliest adopters for next-generation cockpit designs. This advancement is electrifying the human-machine interface, enabling complex, real-time augmented reality overlays for navigation and hazard warnings that were previously unachievable.
Harmonization efforts around UNECE regulations on driver distraction are influencing global system design principles. These frameworks mandate specific limits on the type of content shown and define maximum brightness levels to prevent cognitive overload. Consequently, system developers are prioritizing the delivery of safety-critical information for driver-facing systems over more complex infotainment features.
A shift from sourcing discrete components toward procuring fully integrated digital cockpit systems from Tier-1 suppliers is changing the supply chain. This model challenges smaller, specialized display manufacturers who lack the resources to develop the underlying software and control units. The trend is most pronounced in Europe, where OEMs partner with major suppliers on entire vehicle platform development.
Global Automotive Active Window Display Market Segmentation
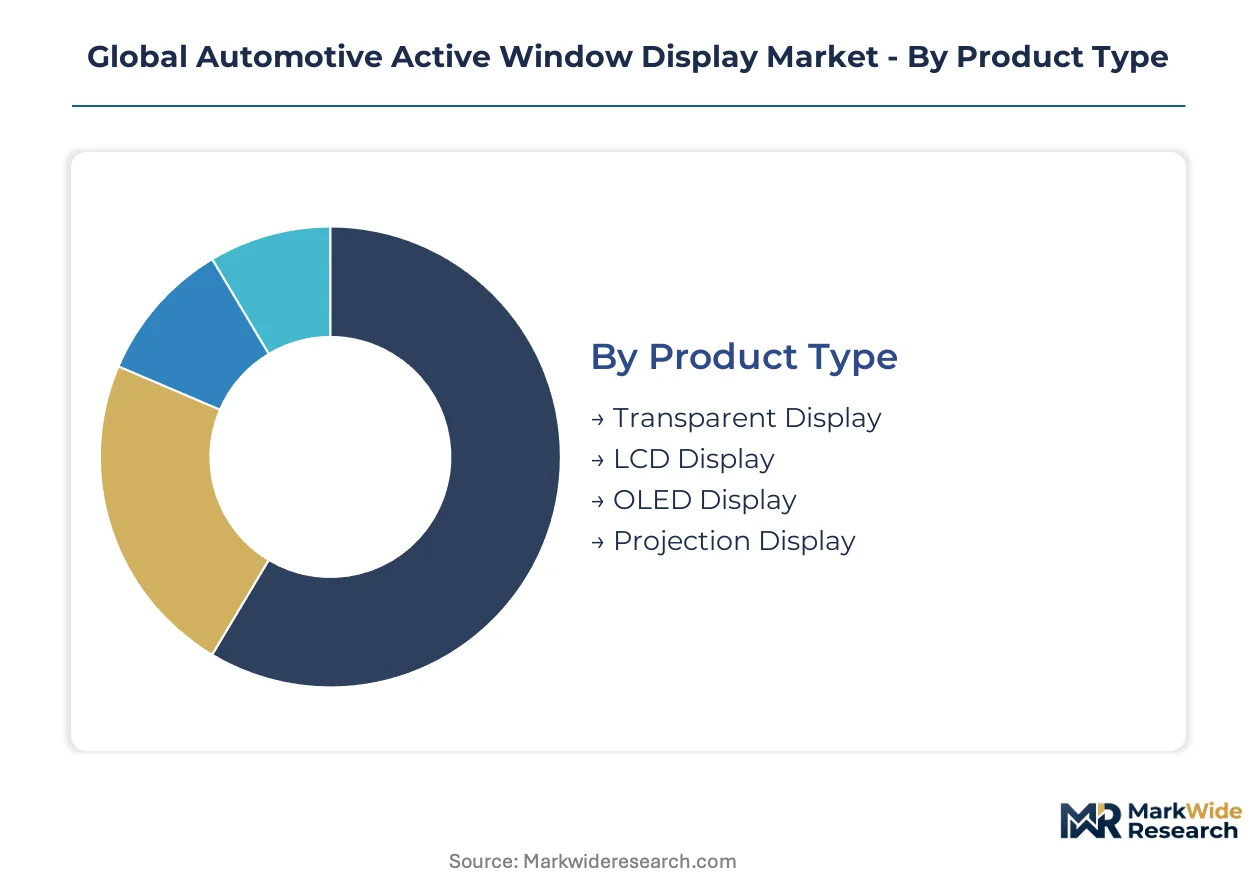
The global automotive active window display market segments reflect distinct technological advancements and varied application demands. Understanding these classifications is crucial for stakeholders to identify areas of concentrated investment and emerging growth trajectories within the rapidly evolving vehicle display landscape.
Product Type:
The upgrade cycle for automotive display components often drives shifts in product type adoption, with newer technologies offering enhanced performance and integration capabilities.
- Projection Display:These systems utilize advanced optics to project dynamic information directly onto transparent surfaces, such as windshields, creating augmented reality overlays. Demand for projection displays is expanding rapidly in advanced driver-assistance systems and navigation applications, particularly in Germany's premium automotive sector.
- OLED Display:Organic Light-Emitting Diode displays offer high contrast ratios and true black levels, making them suitable for visually rich information delivery within vehicle interiors. The cost of large-format transparent OLED panels currently restricts their widespread deployment to high-end vehicle models.
- Transparent Display:These panels allow light to pass through while simultaneously rendering digital content, serving as foundational technology for active window applications.
- LCD Display:Liquid Crystal Displays offer a mature and cost-effective solution for displaying information, though they typically require backlighting, impacting transparency in active window applications.
Volume placements concentrate in Transparent Displays; the faster expansion belongs to Projection Display.
Technology:
The cost tier of various display technologies significantly influences their integration into different vehicle segments, balancing performance with manufacturing expenses.
- Micro-LED:This technology leverages microscopic LEDs to create displays with exceptional brightness, energy efficiency, and durability, crucial for variable automotive lighting conditions. Premium automakers are adopting Micro-LEDs for next-generation cockpit designs due to their superior performance and longevity.
- Electroluminescent:These displays generate light through the application of an electric field to a phosphorescent material, offering good visibility and solid-state construction. Electroluminescent technology finds use in specific automotive lighting and display applications requiring robust performance.
- Electrochromic:Electrochromic technology allows for dynamic control over transparency and tint, typically used in smart glass applications that can integrate simple display elements.
- Liquid Crystal:Liquid crystal technology forms the basis for many transparent displays, offering a balance of transparency and information display capabilities through precise light modulation.
The market's primary revenue driver is Micro-LED, while Electroluminescent technology is gaining share fastest in specialized applications.
Application:
Application-specific demands dictate the functional requirements and integration strategies for active window displays, from driver assistance to passenger entertainment.
- Electric Vehicles:EV manufacturers integrate active window displays to differentiate user experience, communicate vehicle status, and provide advanced human-machine interfaces. The rapid growth of the EV segment in China and Europe is a primary catalyst for display adoption.
- Autonomous Vehicles:These vehicles create new use cases for large-format, passenger-facing window displays, supporting infotainment, productivity, and external communication systems. Development of Level 4 and Level 5 autonomous capabilities expands the scope for immersive display integration.
- Passenger Vehicles:Traditional passenger vehicles integrate active window displays primarily for augmented reality navigation and safety alerts, enhancing driver awareness.
- Commercial Vehicles:Commercial trucks and vans can utilize retrofit projection display systems to provide advanced navigation and safety alerts to professional drivers.
The largest segment by volume is Passenger Vehicles, with Autonomous Vehicles experiencing the steepest expansion trajectory.
End User:
Customer type influences supply chain dynamics, with established relationships and integration capabilities defining success for various end-users in the automotive display ecosystem.
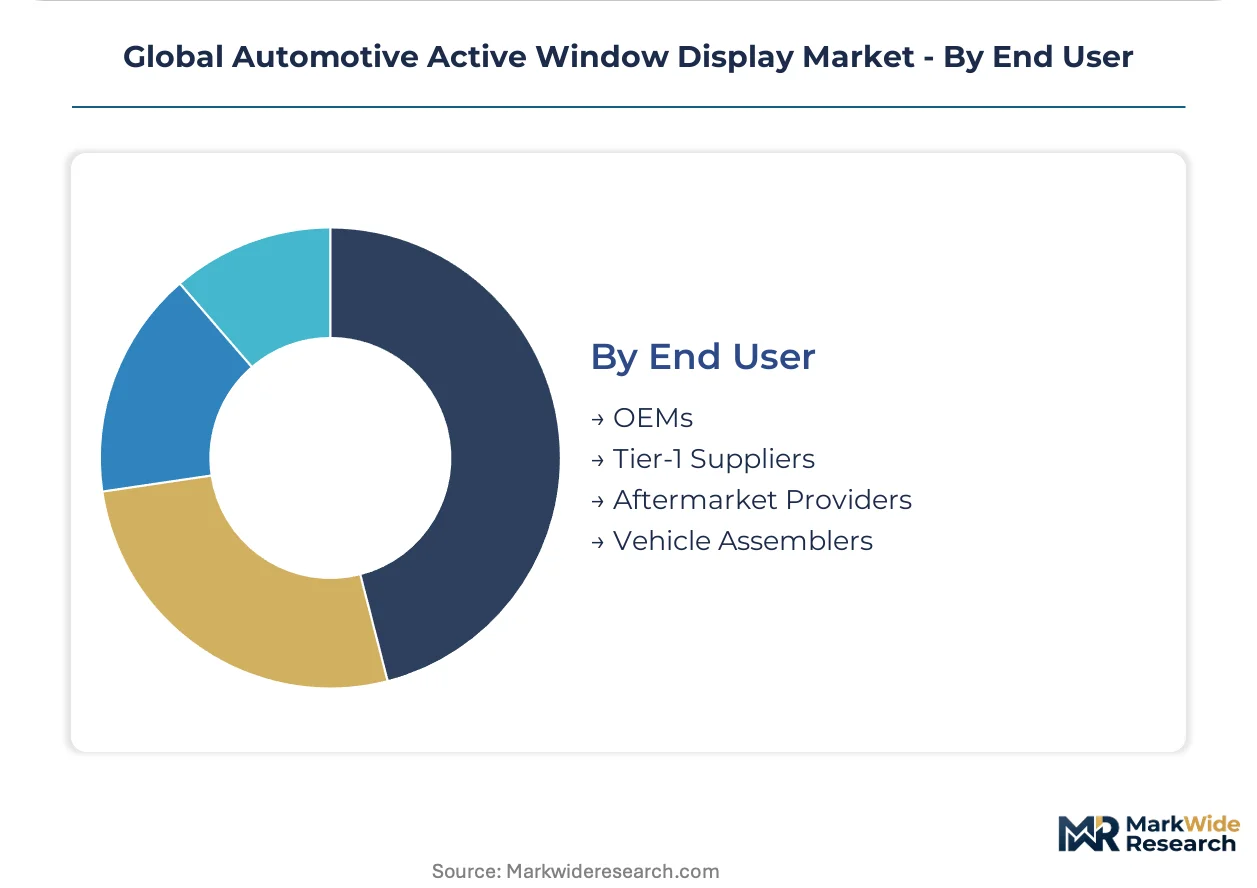
- OEMs:Original Equipment Manufacturers integrate active window displays directly into new vehicle platforms, often collaborating with Tier-1 suppliers for full system development. German automakers are prominent OEMs driving early adoption of these advanced display technologies.
- Tier-1 Suppliers:Large Tier-1 suppliers like Continental AG and Robert Bosch GmbH develop and integrate complete active window display systems, including hardware, software, and control units, into broader cockpit electronics. These suppliers leverage established relationships with OEMs for system integration.
- Aftermarket Providers:Aftermarket companies offer retrofit solutions, particularly projection display systems, for existing vehicles, targeting commercial fleets and specialty applications.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, incorporating components and systems supplied by OEMs and Tier-1 partners.
Demand is concentrated among OEMs, while Tier-1 Suppliers are experiencing robust growth in system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, a primary center for premium automotive manufacturing, anchors the global demand for active window displays. Its established carmakers integrate these advanced systems into new vehicle platforms, setting industry trends. This concentration of innovation influences adoption patterns across other major automotive markets worldwide.
Germany
German premium automakers drive demand for sophisticated active window displays, particularly for augmented reality navigation. Compliance with UNECE regulations on driver distraction heavily influences system design and content. Bavaria and Baden-Württemberg host major automotive R&D centers, integrating these displays into next-generation cockpit designs.
China
China's expanding electric vehicle segment fuels substantial demand for advanced active window displays, especially for passenger infotainment. GB standards for automotive electronics mandate specific interoperability and safety requirements across the market. Major EV production hubs in the Yangtze River Delta actively integrate large-format transparent displays into new vehicle models.
United States
The United States sees strong demand for active window displays from autonomous vehicle development and advanced safety alert systems. NHTSA safety standards govern the design and deployment of these displays to prevent driver distraction. Silicon Valley and Detroit are key centers for integrating projection displays into self-driving prototypes and commercial vehicles.
Japan
Japan's automotive industry drives demand for active window displays through its focus on advanced driver-assistance systems and innovative human-machine interfaces. METI industrial policies encourage the development of cutting-edge automotive electronics and display technologies. The Tokyo and Nagoya regions house major automotive manufacturers and Tier-1 suppliers, advancing transparent display applications.
South Korea
South Korea exhibits significant demand for active window displays, driven by consumer electronics integration and early adoption of Micro-LED technology. The country's national automotive regulations influence display component quality and performance. The Seoul metropolitan area, with its robust display panel industry, pioneers advanced transparent display solutions for automotive applications.
Global Automotive Active Window Display Market Key Industry Players
Strategic partnerships dominate the current landscape, as companies seek to integrate complex display technologies into broader vehicle systems. The market structure is moderately consolidated, with large Tier-1 suppliers holding significant influence over OEMs. Three strategic archetypes emerge: integrated system providers, specialized display technology developers, and aftermarket retrofit solution providers. Beyond partnerships, consistent portfolio diversification and targeted technology licensing represent dominant competitive moves.
Within the integrated system provider archetype, Continental AG and Robert Bosch GmbH exemplify established Tier-1 suppliers. These German-based entities represent comprehensive system integrators, leveraging deep OEM relationships for full cockpit electronics development and software control units. Meanwhile, MicroVision, Inc., a US-based company, anchors the specialized display technology developer segment, focusing on projection display innovations that drive new use cases. These prominent players contribute significantly to the market's technological evolution and system integration capabilities, shaping the future of automotive display solutions.
| Leading Market Players |
|---|
| HARMAN International |
| MicroVision, Inc. |
| Continental AG |
| Delphi Automotive Plc |
| Yazaki Corporation |
| Robert Bosch GmbH |
| TomTom International BV |
| Merck KGaA |
| DENSO Corporation |
| Others |
Cost & Logistics Intelligence
Micro-LED panel production costs, driven by specialized material sourcing from Asia, significantly influence the final system price for premium automotive OEMs in Germany. This cost structure then propagates downstream, affecting the affordability and adoption rate across various vehicle segments.
Pricing Analysis
Warranty and service bundling often differentiate offerings for automotive active window displays, particularly for complex integrated systems. The dominant pricing structure for OEMs is project-based, reflecting extensive customization and integration efforts. Price differentiation stems from performance tiers, such as display brightness and transparency, and the level of software integration. Pricing pressure intensifies due to the high capital expenditure required for manufacturing scale-up. Aftermarket providers exhibit higher price sensitivity compared to premium automotive OEMs.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume demand for integrated active window display systems, primarily through established Tier-1 suppliers. Geographic supply concentration for advanced display components, including Micro-LEDs and specialized optical films, centers heavily in South Korea, Japan, and China. Raw material dependencies include gallium nitride (GaN) for Micro-LEDs and various rare earth elements. A structural supply chain risk involves single-source vulnerability for critical display technologies. Distribution for aftermarket solutions typically runs through specialized automotive electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive active window display market is a vertical-integration race, with major players pursuing in-house software development to control the user experience.
For Market Incumbents: Cement established OEM relationships through co-development of next-generation cockpit platforms. Deepen software integration capabilities to counter emerging specialized display technology firms. Secure long-term supply agreements for critical Micro-LED components to mitigate supply chain risks. Invest in R&D for advanced augmented reality algorithms to maintain technological leadership against new entrants.
For New Entrants and Emerging Players: Begin with targeting underserved commercial fleet aftermarket segments for retrofit solutions. Focus on niche autonomous shuttle applications where display requirements are less stringent than premium passenger vehicles. The most penetrable segment is commercial vehicles seeking cost-effective safety and navigation enhancements. Partner with existing fleet management software providers to leverage established distribution channels and accelerate market entry.
For Investors and Strategic Acquirers: Micro-LED manufacturing yield improvements are the leading indicator that scalable production is achievable. Long-term viability is strong, driven by the sustained growth of electric and autonomous vehicles over the next decade. Acquisition targets should be specialized display technology developers with strong intellectual property in optics, advanced materials, or low-latency software integration. Successful pilot programs for external communication displays in public transport signal market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| In-house Software Development | Controls the human-machine interface and differentiates user experience for OEMs. |
| Micro-LED Manufacturing Scale-Up | Reduces high system costs, enabling broader adoption beyond premium vehicle segments. |
| Global Regulatory Compliance Centers | Navigates fragmented safety standards from NHTSA and UNECE, accelerating market access. |
| Autonomous Vehicle Infotainment Solutions | Captures new revenue streams from passenger-facing displays in Level 4 vehicles. |
| Aftermarket Projection System Partnerships | Expands market reach into commercial vehicle segments with advanced navigation. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with OEM platform engineers, Tier-1 suppliers, display technology R&D directors, and aftermarket distributors validated these findings. Bottom-up data aggregation and top-down market sizing provided robust triangulation.
Reconciling diverse data streams informed the quantitative framework for market projections. The analytical framework modeled market dynamics across the analysis window, segmenting by product type, technology, application, and geographic region. Compound annual growth rates were derived from historical trends and projected technological adoption. Key inputs included EV production forecasts and Micro-LED cost curves.
Underlying measurement precision varies by segment; Passenger Vehicles and Autonomous Vehicles carry tighter precision than others. Forecasts reflect assumptions regarding technological maturity and regulatory evolution. Geopolitical shifts or unforeseen supply chain disruptions could revise these outlooks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Automotive Steer-By-Wire System (Sbw) Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Remote Car Starter Market