
 Automotive High-Precision Positioning System Market | 2026-2036
Automotive High-Precision Positioning System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive High-Precision Positioning System Market Insights
Modular sensor fusion kits are rebalancing buyer choice away from standalone GNSS modules toward integrated positioning stacks. Robert Bosch GmbH leverages its MEMS fabrication depth to anchor in-house IMU production for OEM programs. Qualcomm Technologies, Inc. competes through its Snapdragon Ride platform, which combines GNSS, camera, and radar inputs into unified localization outputs. Trimble Inc. differentiates in agricultural and construction autonomy, where RTK-GPS correction networks sustain premium pricing.
An automotive high-precision positioning system combines multi-frequency GNSS receivers, inertial measurement units, and sensor fusion algorithms to deliver sub-30-centimeter localization accuracy for vehicle navigation and automated control. These systems process signals from GPS, GLONASS, Galileo, and BeiDou constellations alongside dead-reckoning data to maintain position fixes in urban canyons and tunnels. IMU and sensor fusion segments command the deepest margin pools because silicon-level integration reduces bill-of-materials complexity while improving fault tolerance. GPS unit demand remains volume-heavy but price-pressured as commoditization spreads across entry-level navigation applications. Autonomous driving use cases absorb the fastest-growing share of positioning system value as Level-2+ and Level-3 programs multiply validation miles.
The US NHTSA and FAA jointly shape demand through autonomous vehicle testing protocols and drone integration mandates that require certified positioning integrity. Europe's EMA and EU AI Act intersect with automotive positioning where health-monitoring algorithms trigger emergency responses based on vehicle location data. China's SAMR enforces GB standards for functional safety and cybersecurity in connected positioning modules. Stakeholders must monitor how regulator fragmentation across these jurisdictions fragments certification requirements and extends product development cycles.
Market Dynamics
Sensor fusion architectures are compressing procurement cycles as OEMs abandon discrete GNSS modules in favor of integrated positioning stacks that combine IMU, camera, and LiDAR inputs into unified localization outputs.
Growth Catalysts
- MIIT GB Standards:China's mandate for centimeter-level positioning in Level-3 autonomous vehicles creates certified demand for RTK-GNSS receivers with BeiDou constellation support.
- Highway Pilot Systems:Level-2+ programs at passenger vehicle OEMs are accelerating validation miles and absorbing multi-frequency receiver volumes.
- Real-Time Kinematic Networks:Dense RTK correction infrastructure in agricultural and construction autonomy sustains premium pricing for positioning services.
Market Restraints
- MEMS Foundry Concentration:IMU die production clusters in East Asian fabrication facilities expose supply chains to geographic concentration risk.
- Multi-Constellation Licensing:Patent pools for GLONASS and Galileo signal processing inflate royalty stacks for receiver manufacturers.
- Silicon Cost Volatility:300mm wafer pricing fluctuations transmit directly to GNSS SoC and IMU bill-of-materials.
Strategic Opportunities
- V2X Positioning Mandates:US NHTSA testing protocols for connected vehicle infrastructure create pull for certified integrity receivers.
- EU AI Act Intersection:Health-monitoring algorithms triggering emergency responses based on vehicle location data expand addressable market for high-integrity modules.
- IMU-Camera Convergence:Tight coupling of inertial dead-reckoning with computer vision pipelines enables urban canyon navigation without RTK dependency.
Industry Challenges
- Functional Safety Certification:UN ECE regulations demand ISO 26262 ASIL-D processes that extend product development cycles by 18-24 months.
- Sensor Calibration Talent:Scarcity of engineers capable of tuning multi-sensor fusion algorithms across temperature and vibration envelopes constrains program scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive High-Precision Positioning System Market |
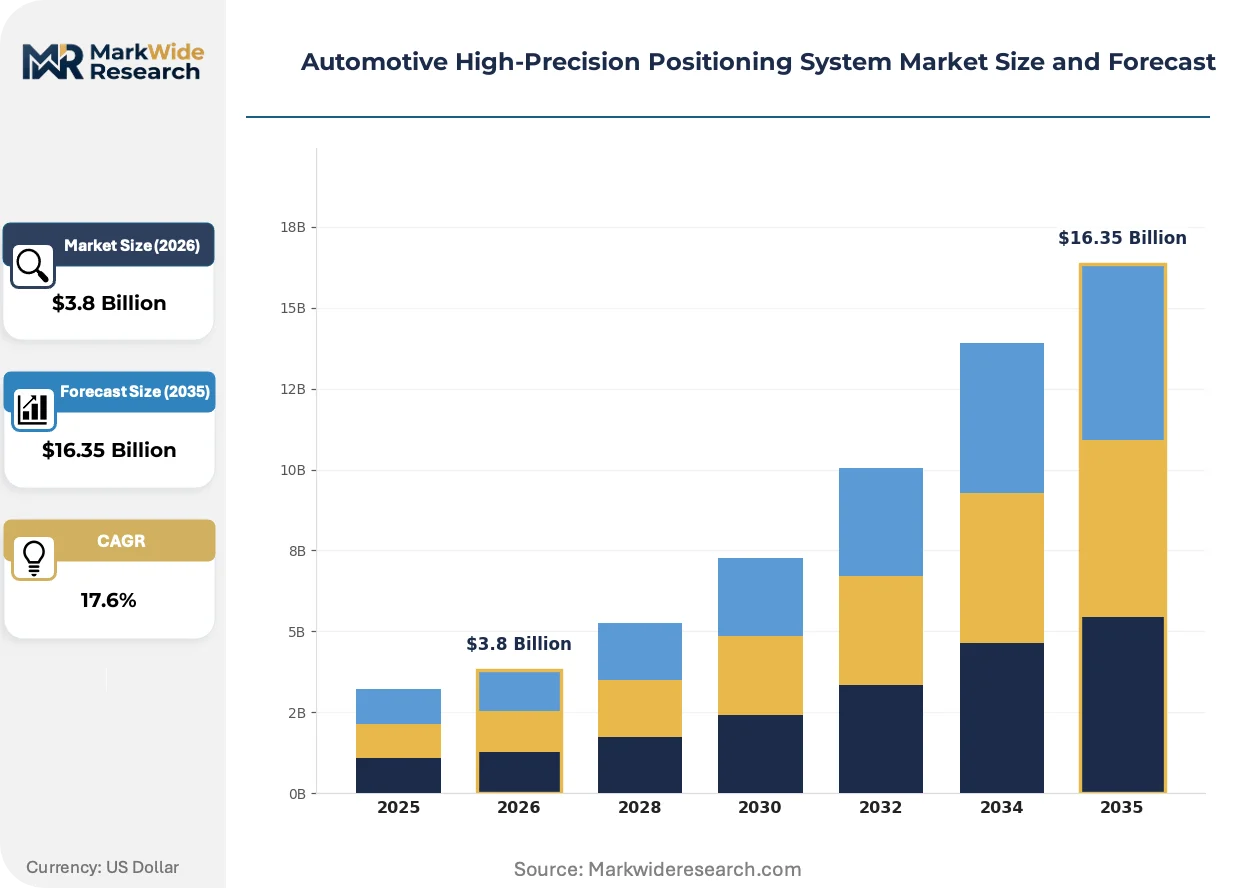
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Units, Inertial Measurement Units, Radar Systems, Ultrasonic Sensors Use Case: Autonomous Driving, Lane Keeping Assistance, Collision Avoidance, Navigation End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: GNSS, LiDAR, Computer Vision, Sensor Fusion |
| Companies Covered | Robert Bosch GmbH, Continental AG, Trimble Inc., u-blox Holding AG, Hexagon AB, Denso Corporation, NXP Semiconductors N.V., Qualcomm Technologies, Inc., Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive High-Precision Positioning System Market Trends and Innovations
Multi-constellation receiver integration is compressing the boundary between navigation and perception layers, forcing component suppliers to reposition around software-defined positioning rather than hardware-centric GNSS modules.
Multi-frequency GNSS receivers with L1/L2/L5 band support are electrifying highway pilot architectures by enabling ionospheric error correction without dual-receiver redundancy. Tier-1 suppliers are embedding these receivers directly into domain controllers rather than standalone modules. This consolidation is electrifying the competitive landscape around software stack differentiation rather than RF front-end performance.
Germany's KBA enforcement of UN ECE functional safety certifications is restructuring supplier qualification requirements for European OEM programs. The regulation mandates traceable fault detection for positioning integrity in automated lane-keeping systems. German premium manufacturers are responding by requiring ASIL-D certified IMUs from approved component lists.
Fleet operators are unbundling positioning hardware from service contracts, purchasing RTK correction subscriptions separately from receiver hardware. This disintermediation is visible most acutely in North American agricultural autonomy, where Trimble and John Deere operators mix hardware generations with network-agnostic correction services. The shift compresses hardware replacement cycles while expanding recurring revenue pools for correction network providers.
Automotive High-Precision Positioning System Market Segmentation
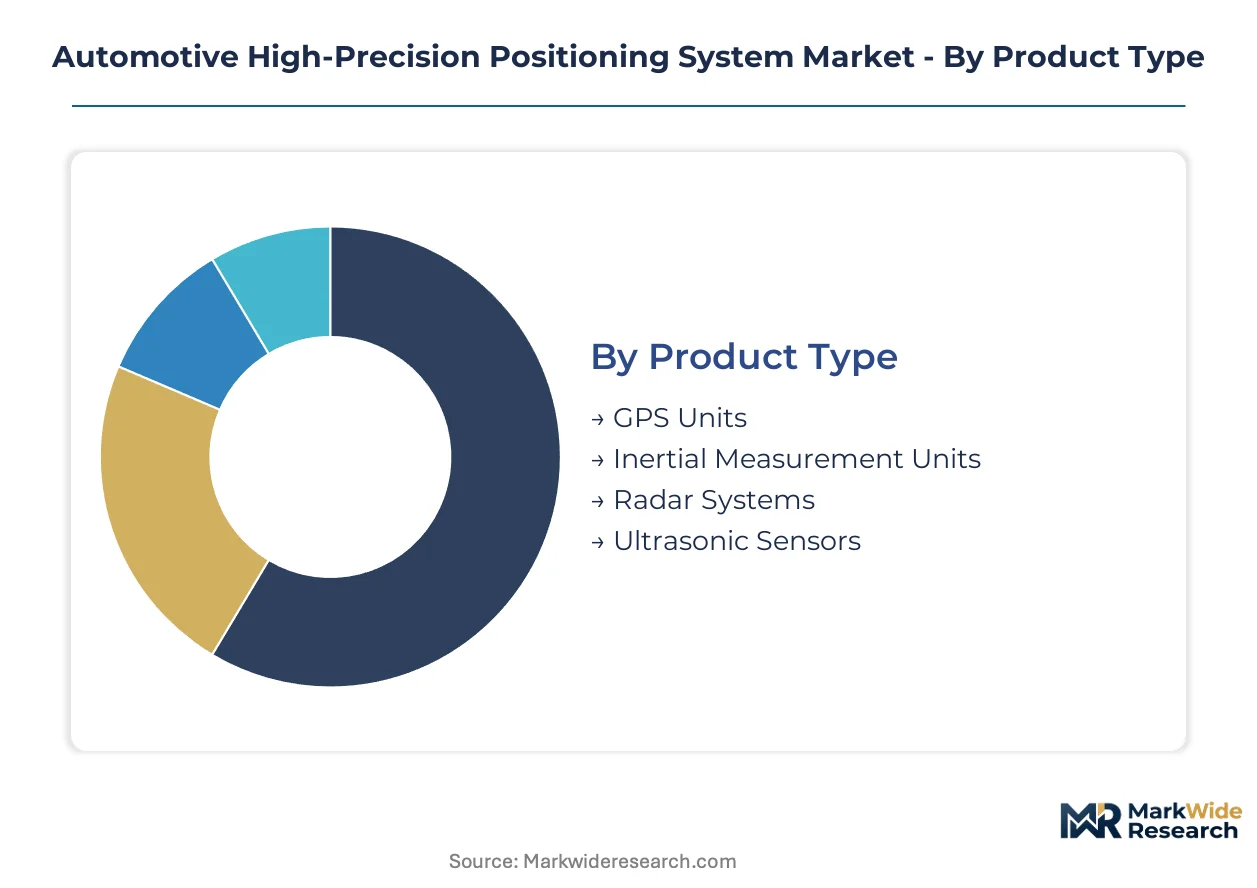
Automotive high-precision positioning systems fragment across hardware layers, software stacks, and buyer archetypes. Each segmentation axis reveals distinct margin profiles and certification requirements that reshape supplier positioning.
Product Type:
Component architecture determines integration depth with vehicle domain controllers and sensor fusion pipelines.
- GPS Units:Multi-frequency GNSS receivers process L1/L2/L5 signals with BeiDou, Galileo, and GLONASS constellation support. Entry-level navigation programs in mass-market passenger vehicles absorb volume, though commoditization compresses margins for standalone modules lacking RTK correction.
- Inertial Measurement Units:MEMS-based accelerometer and gyroscope arrays enable dead-reckoning position fixes during GNSS signal outages. Highway pilot systems at German premium OEMs require ASIL-D certified IMUs, creating certified demand that sustains premium pricing against unqualified alternatives.
- Radar Systems:77GHz and 79GHz automotive radar complements positioning with velocity and object detection data.
- Ultrasonic Sensors:Short-range acoustic positioning for parking assistance and low-speed maneuvering.
GPS Units lead on scale; Inertial Measurement Units lead on momentum.
Use Case:
Application maturity spans from validated production systems to emerging autonomy programs with extended development horizons.
- Autonomous Driving:Level-2+ and Level-3 programs fuse multi-constellation GNSS with LiDAR and camera inputs for sub-30-centimeter localization. China's MIIT GB standards mandate centimeter-level accuracy, accelerating validation cycles for RTK-GNSS receivers with domestic BeiDou support.
- Lane Keeping Assistance:Camera-dominant systems with GNSS waypoint validation for highway corridor navigation.
- Collision Avoidance:Radar and ultrasonic sensor arrays providing proximity positioning independent of satellite signals.
- Navigation:Consumer-grade route guidance with meter-level accuracy requirements and minimal functional safety certification burden.
Navigation leads on scale; Autonomous Driving climbs the fastest.
End User:
Procurement authority concentrates with vehicle manufacturers while service-based models emerge among fleet operators.
- OEMs:German, Japanese, and US vehicle manufacturers specify positioning stacks at platform level, requiring ASIL-D certification and multi-constellation support. Direct sourcing of IMU die and GNSS SoC components is expanding as OEMs backward-integrate into silicon selection.
- Tier-1 Suppliers:Bosch, Continental, and Denso integrate positioning modules into ADAS domain controllers for multiple OEM programs.
- Aftermarket Providers:Retrofit high-precision receivers for commercial vehicle fleet upgrades and agricultural autonomy conversions.
- Fleet Operators:North American agricultural and mining fleets unbundle hardware from RTK correction subscriptions, purchasing network-agnostic services separately.
OEMs lead on scale; Fleet Operators lead on momentum.
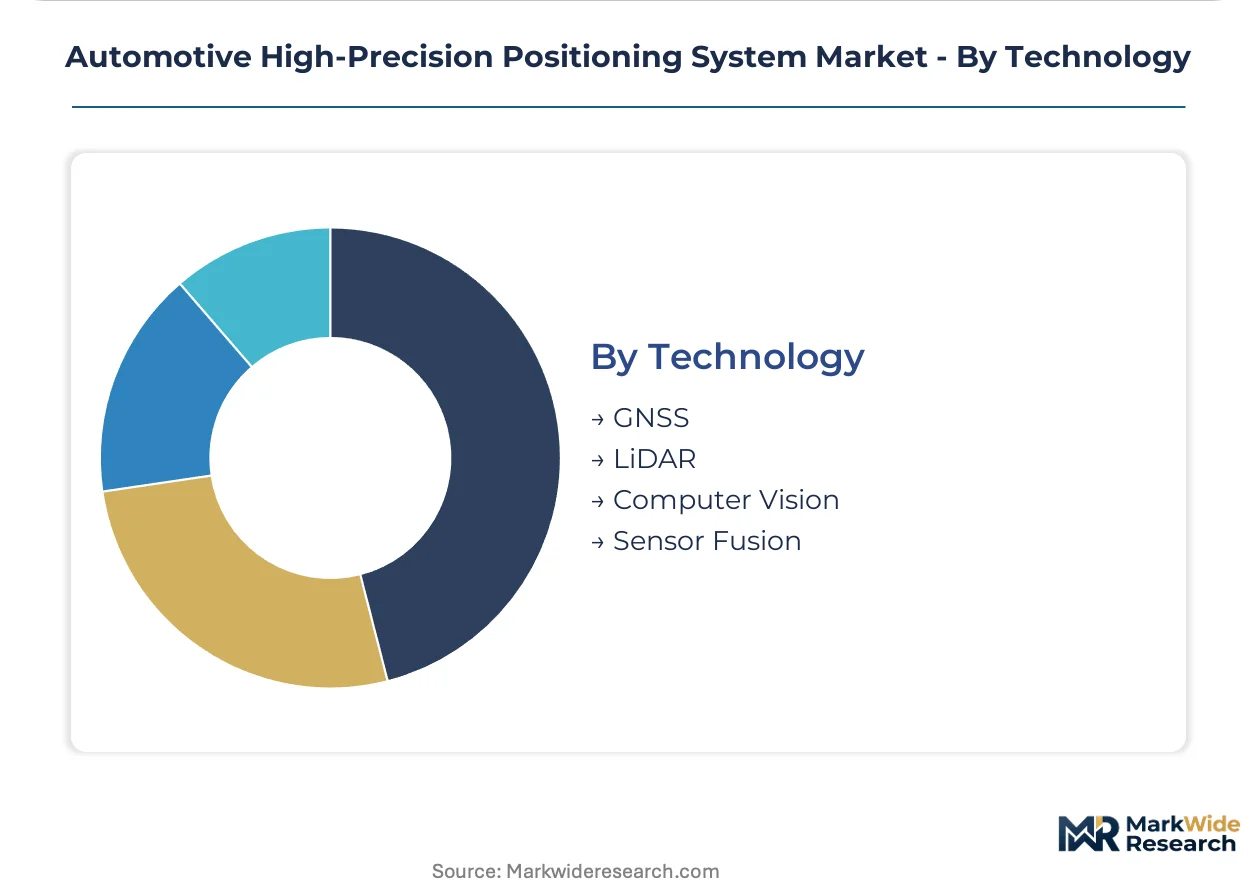
Technology:
Signal processing architectures are converging as software-defined positioning displaces hardware-centric module designs.
- GNSS:Multi-frequency receiver architectures with real-time kinematic correction enable ionospheric error compensation without dual-receiver redundancy. Dense RTK infrastructure in agricultural regions sustains premium service pricing.
- LiDAR:Solid-state and mechanical scanning systems provide point-cloud localization for urban canyon navigation where satellite signals degrade.
- Computer Vision:Visual odometry pipelines extract position estimates from camera feeds, reducing RTK dependency in structured environments.
- Sensor Fusion:Kalman filter and deep-learning architectures unify GNSS, IMU, camera, and LiDAR inputs into single localization outputs.
GNSS leads on scale; Sensor Fusion gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-precision positioning systems trace their automotive lineage to German precision engineering clusters that pioneered ASIL-D certified IMUs for early highway pilot programs. The industry's geographic footprint now spans three continents where regulatory mandates and autonomous driving investments concentrate demand.
Germany
German premium OEMs anchor European demand for ASIL-D certified positioning stacks in Level-2+ and Level-3 programs. KBA enforcement of UN ECE functional safety certifications mandates traceable fault detection for automated lane-keeping systems. Stuttgart and Munich host concentrated supplier engineering centers where Bosch and Continental integrate multi-constellation receivers into domain controllers.
China
Domestic OEMs and fleet operators drive the fastest adoption of BeiDou-centric RTK-GNSS receivers for autonomous validation programs. MIIT GB standards mandate centimeter-level positioning accuracy for Level-3 vehicles, accelerating certification timelines. Shenzhen and Shanghai cluster hardware integration facilities where suppliers localize sensor fusion stacks for domestic platforms.
United States
NHTSA autonomous vehicle testing protocols and emerging V2X infrastructure mandates create certified demand for integrity receivers. FAA drone integration rules extend positioning requirements to aerial mobility applications overlapping automotive sensor suppliers. Michigan and California concentrate OEM validation fleets and Tier-1 engineering operations.
Japan
Japanese vehicle manufacturers specify positioning modules at platform level for highway pilot systems across mass-market and premium segments. METI industrial policy supports domestic MEMS fabrication capacity for automotive IMU production. Nagoya and Tokyo host concentrated ADAS engineering centers where Denso and Continental Japan coordinate multi-sensor fusion development.
South Korea
Hyundai Motor Group and emerging EV specialists absorb multi-frequency GNSS volumes for highway autonomy programs. National standards align with UN ECE frameworks while supporting domestic BeiDou-GPS fusion architectures. Seoul Capital Area clusters semiconductor packaging operations where NXP and Qualcomm supply chain partners localize GNSS SoC integration.
Automotive High-Precision Positioning System Market Competitive Landscape
The competitive structure tilts toward diversified automotive Tier-1 suppliers with captive MEMS fabrication and software-defined positioning stacks. Consolidation pressure runs high as OEMs backward-integrate into silicon selection and reduce qualified supplier lists. Three archetypes dominate: diversified automotive electronics conglomerates with domain controller integration capabilities; precision agriculture specialists pivoting toward automotive autonomy; and semiconductor platform vendors supplying GNSS SoCs and sensor fusion software. M&A activity concentrates on RTK correction network assets and IMU calibration algorithm portfolios.
Among diversified automotive Tier-1 suppliers, Robert Bosch GmbH and Continental AG occupy positions anchored by in-house MEMS fabrication depth and ASIL-D certification track records. Qualcomm Technologies, Inc. represents the semiconductor platform archetype, supplying Snapdragon Ride positioning software to multiple OEM programs. Trimble Inc. exemplifies the precision agriculture pivot, leveraging dense RTK infrastructure in North American farming regions to sustain premium service pricing as automotive applications scale.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Trimble Inc. |
| u-blox Holding AG |
| Hexagon AB |
| Denso Corporation |
| NXP Semiconductors N.V. |
| Qualcomm Technologies, Inc. |
| Valeo SA |
| Others |
Pricing and Supply Chain Analysis
German premium OEM procurement concentration anchors pricing power with ASIL-D certified positioning stacks commanding three-tier spreads across premium, standard, and economy certification levels. China's MIIT GB mandate for centimeter-level accuracy in Level-3 vehicles compresses negotiation timelines as domestic OEMs accelerate supplier qualification.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy certification levels separates ASIL-D IMUs from unqualified alternatives and commoditized GPS modules. Price differentiation hinges on functional safety certification grade and BeiDou constellation support depth. Cost compression in entry-level navigation tiers intensifies because standalone GNSS modules face commoditization without RTK correction bundling. Fleet operators exhibit highest price sensitivity through hardware-service unbundling, while German OEMs absorb premium pricing for traceable fault detection.
Supply Chain Analysis
Dual-sourcing requirements from European OEMs mandate multi-supplier qualification for MEMS die and GNSS SoC components to mitigate geographic concentration risk. Supply draws from Taiwan, South Korea, and China for 300mm wafer fabrication, MEMS foundry services, and BeiDou receiver silicon. Raw material dependencies span semiconductor-grade silicon, rare-earth magnet materials for IMU packaging, and multi-layer ceramic substrates. Single-source vulnerability concentrates in East Asian MEMS foundry clusters. Distribution runs through Tier-1 domain controller integrators with approved component list restrictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory demand through China's MIIT GB standards mandating centimeter-level positioning for Level-3 autonomous vehicles.
For Market Incumbents: Acquire RTK correction network assets to defend service revenue streams against hardware commoditization. Secure captive MEMS fabrication capacity or binding foundry agreements to offset geographic concentration exposure. Deepen certification algorithm portfolios for ASIL-D traceability requirements under UN ECE regulations. For New Entrants and Emerging Players: Aftermarket fleet operators in North American agricultural autonomy represent underserved buyer archetype with network-agnostic correction service appetite. Position around software-defined positioning stacks that reduce RF front-end dependency. Pursue white-label sensor fusion calibration services for Tier-1 domain controller integrators lacking in-house tuning expertise. For Investors and Strategic Acquirers: Semiconductor platform vendors are the most active acquirer in this space, consolidating sensor fusion software capabilities. Long-term viability rests on positioning at the intersection of automotive autonomy mandates and V2X infrastructure deployment. Watch for MIIT GB standard adoption velocity across Chinese OEM validation programs as inflection indicator for RTK-GNSS receiver demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| RTK Correction Network Acquisition | Secures recurring revenue streams as hardware margins compress under OEM backward integration. |
| ASIL-D Certification Investment | Unlocks German premium OEM approved component list placement under KBA enforcement. |
| Sensor Fusion Software Stack Development | Enables domain controller integration beyond standalone GNSS module commoditization. |
| BeiDou Constellation Localization | Captures MIIT GB standard compliance requirement for Level-3 vehicle programs in China. |
| MEMS Foundry Capacity Binding | Offsets East Asian geographic concentration risk through dual-source qualification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and MEMS foundry operations managers with secondary validation against SEC filings, vehicle production databases, IHS Markit registration data, and customs trade records. Bottom-up segment sizing and top-down market reconciliation anchored triangulation.
Segment-weighting approach distributed value across hardware layers, software stacks, and buyer archetypes with autonomous driving use cases and sensor fusion technologies receiving elevated coefficients. CAGRs derived from regression analysis against validation mile expansion and regulatory mandate implementation timelines. Forecast inputs incorporated RTK infrastructure density metrics and OEM backward integration announcements.
Underlying measurement precision varies by segment; autonomous driving and sensor fusion categories carry tighter precision than commoditized GPS navigation. Forecasts reflect assumptions around MIIT GB standard enforcement consistency and UN ECE certification timeline stability. Deviation in Chinese Level-3 vehicle homologation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Automotive AR HUD Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market