
 Asia Pacific in-Car Entertainment System Market | 2026-2036
Asia Pacific in-Car Entertainment System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific in-Car Entertainment System Market Outlook
Semiconductor-grade silicon is recalibrating cost structures across head-unit and display module production. Panasonic Corporation leverages its vertical fabrication partnerships to secure wafer supply for automotive-grade chipsets. Denso Corporation anchors its entertainment hardware within Toyota's keiretsu procurement framework, sustaining captive demand across hybrid and electric platforms. Harman International Industries competes through acoustic engineering specialization, positioning its branded audio systems as tier-one OEM standard equipment.
The Asia Pacific in-car entertainment system encompasses integrated hardware-software platforms delivering audio reproduction, visual content, navigation guidance, and connectivity services within vehicle cabins, typically operating on 12-volt electrical architectures with CAN bus or Ethernet backbone integration. These systems serve the primary commercial purpose of differentiating vehicle trim levels while monetizing software-enabled services over multi-year ownership cycles. Infotainment system deployments command the dominant share of OEM bill-of-material spending, whereas Bluetooth connectivity modules represent the fastest-expanding technology segment as basic wireless pairing becomes standard even in entry-level A-segment vehicles across India and Southeast Asia. Navigation system demand is maturing in Japan and South Korea, where smartphone mirroring has displaced embedded GPS hardware in mass-market segments.
Japan's METI enforces cybersecurity management system requirements for connected vehicle platforms, compelling suppliers to certify over-the-air update protocols. India's TRAI spectrum allocation frameworks for vehicle-to-everything communication are shaping OEM decisions on embedded cellular modems versus tethered smartphone dependency. China's MIIT mandates data localization for in-cabin telemetry, restricting cross-border cloud processing for voice recognition and content streaming. Stakeholders must weigh sovereign data requirements against the cost of region-specific software architectures.
Market Dynamics
Embedded cellular modems are displacing tethered smartphone architectures across Asia Pacific vehicle fleets, forcing OEMs to reconfigure software stacks for sovereign data compliance while absorbing semiconductor cost volatility.
Growth Catalysts
- TRAI spectrum frameworks:India's connected vehicle spectrum allocation is accelerating OEM integration of cellular-enabled entertainment modules. This regulatory clarity reduces uncertainty for tier-one suppliers deploying embedded modems.
- Intelligent cockpit demand:Premium passenger vehicle fleets across Japan and South Korea are expanding embedded infotainment specifications. This specification creep pulls higher-margin hardware into mass-market trims.
- Eastern China manufacturing corridor:BYD and NIO anchor domestic supply chains for cockpit system production. This geographic concentration compresses procurement lead times for regional OEMs.
Market Restraints
- Semiconductor input volatility:Automotive-grade chipsets face wafer allocation competition from consumer electronics. Foundry capacity constraints transmit price instability into head-unit bill-of-materials.
- Keiretsu supply concentration:Denso's captive position within Toyota's procurement framework limits market access for independent module suppliers. This structural lock-in restricts competitive entry.
- Smartphone mirroring substitution:Embedded GPS hardware demand is maturing in Japan and South Korea where Apple CarPlay and Android Auto displace native navigation systems. This substitution erodes software licensing revenue streams.
Strategic Opportunities
- Southeast Asia A-segment penetration:Bluetooth connectivity modules are expanding fastest in entry-level vehicles across India and Thailand. This underpenetrated tier offers volume scale for cost-optimized hardware.
- MIIT data localization mandates:China's in-cabin telemetry rules restrict cross-border cloud processing. This regulatory tailwind creates demand for region-specific voice recognition architectures.
- Over-the-air update certification:Japan's METI cybersecurity management system requirements compel suppliers to certify remote update protocols. This creates service revenue potential for compliant software vendors.
Industry Challenges
- Multi-architecture software development:OEMs must maintain parallel codebases for 12-volt CAN bus legacy fleets and Ethernet-backbone electric platforms. This dual-stack requirement strains engineering capacity.
- Cross-border data governance:Fragmented sovereign requirements across China, Japan, and India force redundant compliance investments. Cloud infrastructure localization multiplies operational complexity.
- Acoustic engineering talent scarcity:Branded audio system differentiation requires specialized transducer design expertise. This skill concentration limits supplier expansion into premium tier-one positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific in-Car Entertainment System Market |
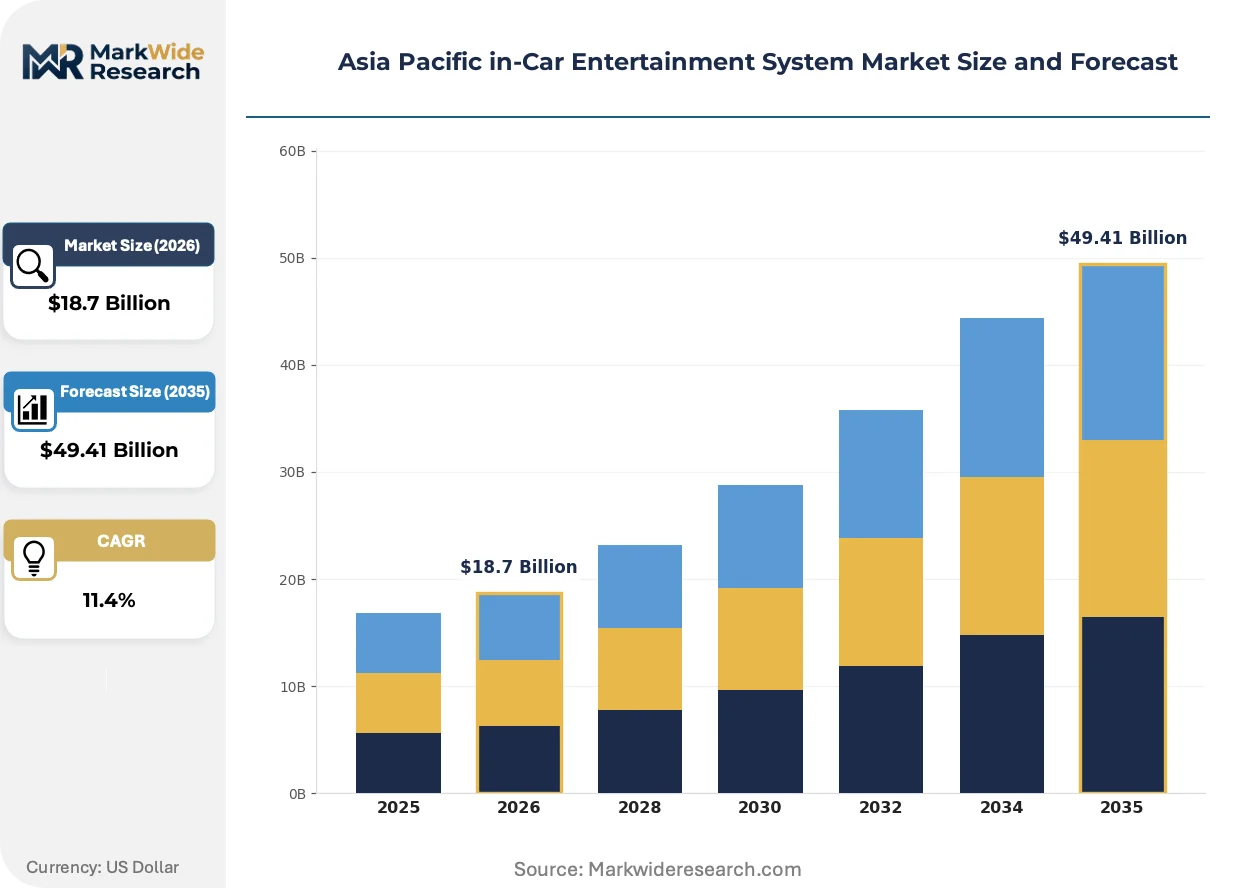
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infotainment System, Audio System, Video System, Navigation System Technology: Bluetooth, Wi-Fi, USB, HDMI End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialized Retail |
| Companies Covered | Panasonic Corporation, Denso Corporation, Harman International Industries, Alpine Electronics Inc., Pioneer Corporation, Robert Bosch GmbH, Visteon Corporation, Continental AG, Hyundai Mobis, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific in-Car Entertainment System Market Strategic Shifts
Ethernet backbone architectures are reconfiguring in-vehicle network topologies, compressing latency for real-time entertainment streaming while enabling centralized compute consolidation.
Automotive-grade system-on-chip designs are consolidating discrete head-unit functions into unified silicon platforms. Tier-one suppliers are adopting these integrated chipsets to reduce board complexity and thermal management overhead. This silicon consolidation is compressing the supplier base for discrete audio and video processors.
METI's cybersecurity management system requirements are mandating formal verification protocols for over-the-air entertainment software updates. Japanese OEMs are restructuring supplier contracts to allocate liability for firmware integrity failures. This regulatory pressure is concentrating certification investment among suppliers with established automotive security practices.
Fleet procurement of intelligent cockpit systems is fragmenting across ownership models. Leasing companies are demanding modular hardware architectures that support mid-contract software upgrades. This purchasing pattern shift is most visible in South Korea's corporate vehicle segment where three-year replacement cycles compress hardware refresh timelines.
Asia Pacific in-Car Entertainment System Market Segmentation
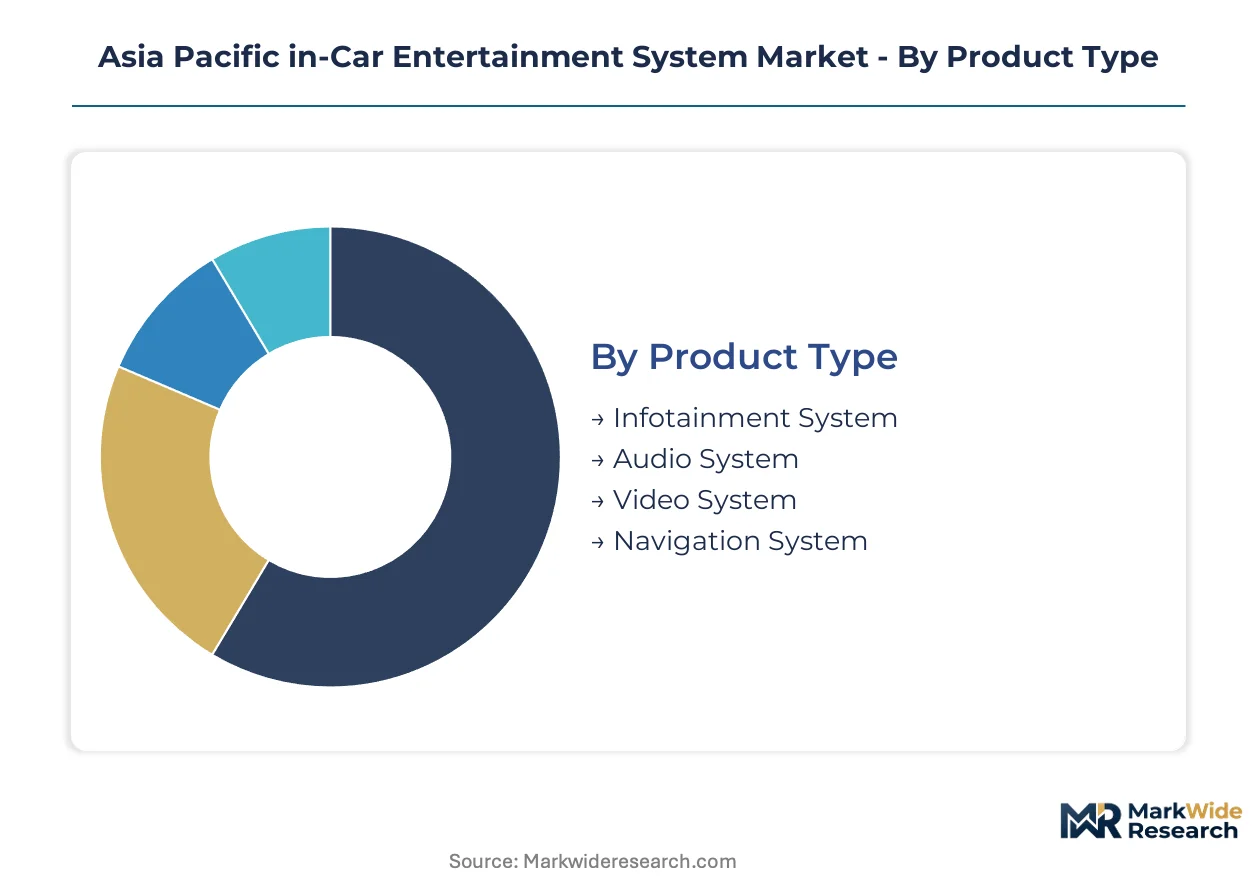
Segmentation reveals how hardware specifications, connectivity protocols, and procurement channels stratify across vehicle price tiers and ownership models. Upgrade cycles differ sharply between embedded OEM configurations and aftermarket replacement demand.
Product Type:
Replacement cycles vary dramatically across product categories, with infotainment hardware refreshing every 3-4 years while audio components persist for 7-10 years in fleet vehicles.
- Infotainment System:Integrated touchscreen platforms combining navigation, media, and vehicle settings on centralized displays. Demand clusters in China's premium electric vehicle segment where NIO and BYD specify 15-inch+ portrait orientations with over-the-air update capability.
- Audio System:Speaker arrays, amplifiers, and acoustic processing modules delivering cabin sound reproduction. Japanese and South Korean OEMs specify branded audio partnerships as trim-level differentiators, with Harman and Bose systems penetrating mid-tier sedans.
- Video System:Rear-seat entertainment displays and head-up projection modules. Rear-seat deployment concentrates in executive vehicle configurations across Japan's corporate leasing market.
- Navigation System:Embedded GPS hardware with localized map databases. Native navigation demand is contracting in Japan and South Korea where smartphone mirroring displaces dedicated hardware in mass-market segments.
Volume placements concentrate in infotainment systems; the faster expansion belongs to audio system upgrades as acoustic branding penetrates mid-market trims.
Technology:
Connectivity specifications cascade from premium vehicle trims downward, with protocol adoption curves differing across manufacturing cost tiers and regional infrastructure maturity.
- Bluetooth:Short-range wireless protocol enabling smartphone audio streaming and hands-free calling. India's TRAI spectrum frameworks accelerate embedded modem integration, yet Bluetooth remains the dominant wireless interface in A-segment vehicles across Thailand and Indonesia.
- Wi-Fi:High-bandwidth wireless enabling in-vehicle hotspot functionality and content streaming. Deployment concentrates in China's intelligent cockpit systems where MIIT data localization mandates require region-specific cloud architectures.
- USB:Wired connectivity for device charging and media playback. USB-C adoption is displacing legacy Type-A ports in South Korean vehicle platforms.
- HDMI:High-definition video input for external device mirroring. HDMI ports are proliferating in Japan's executive vehicle segment for rear-seat productivity applications.
Bluetooth dominates unit placements; Wi-Fi is climbing the fastest as cellular-enabled platforms require high-bandwidth local distribution.
End User:
Procurement authority fragments across vehicle lifecycle stages, with OEMs controlling initial fitment and independent channels capturing wear-related replacement demand.
- OEMs:Original equipment manufacturers specifying factory-installed entertainment configurations. Japan's METI cybersecurity requirements compel OEMs to certify over-the-air update protocols, restructuring supplier liability frameworks.
- Aftermarket Providers:Independent retailers and installation shops serving vehicle owners post-purchase. Aftermarket demand concentrates in India's price-sensitive segments where owners upgrade base audio configurations.
- Vehicle Assemblers:Contract manufacturers building vehicles for multiple brands under shared platforms. Eastern China's manufacturing corridor anchors assembler procurement for BYD and NIO intelligent cockpit systems.
- Tier-1 Suppliers:Direct component vendors integrating entertainment modules into vehicle electrical architectures. Denso's captive position within Toyota's keiretsu procurement framework illustrates tier-1 supply concentration.
OEM channel captures the revenue concentration; aftermarket providers are expanding most quickly as vehicle aging extends replacement windows.
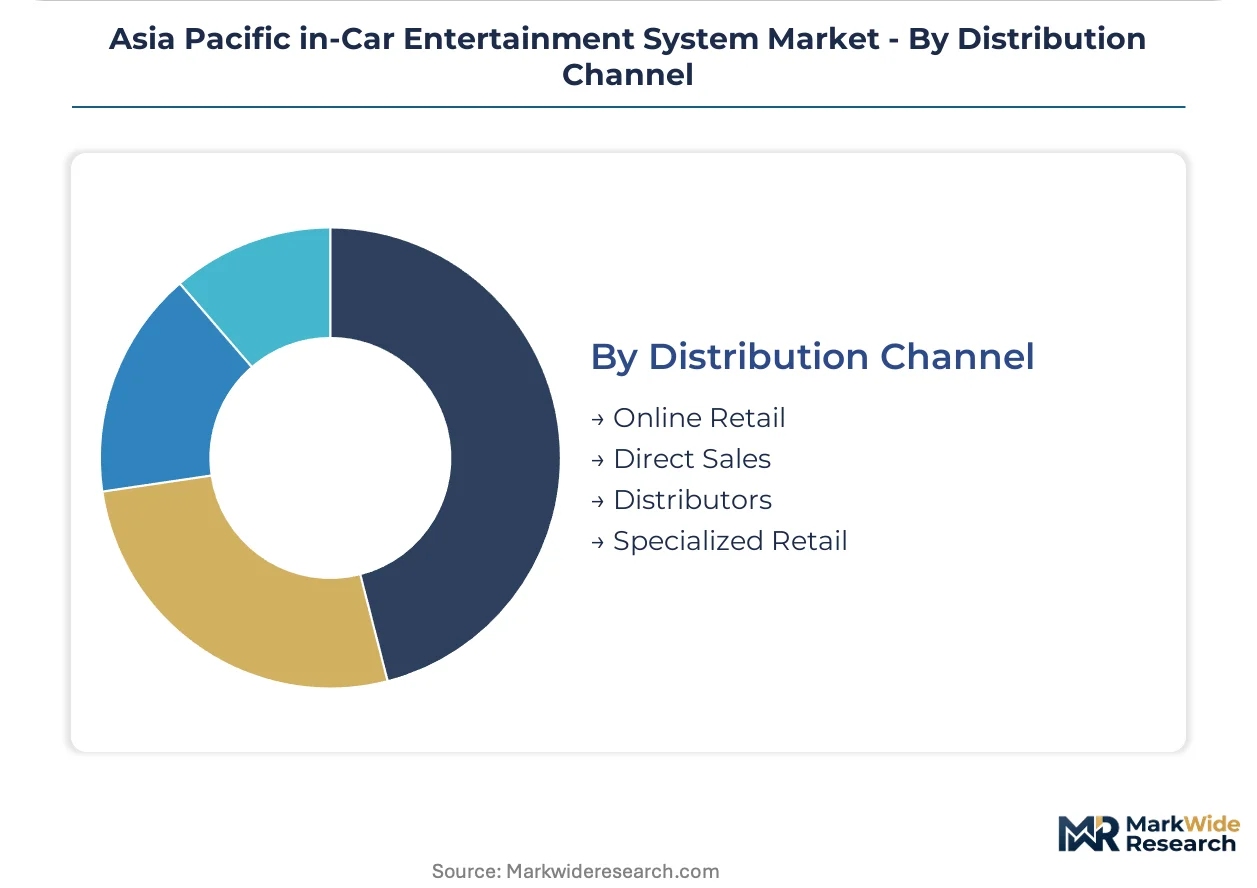
Distribution Channel:
Channel selection correlates with buyer technical sophistication and installation complexity, with direct relationships dominating volume procurement and specialized retail capturing specification-sensitive demand.
- Online Retail:E-commerce platforms enabling consumer-direct component purchases. India's Flipkart and Amazon channels are expanding fastest for Bluetooth module upgrades in entry-level vehicles.
- Direct Sales:Manufacturer-to-OEM contractual relationships for platform-scale supply. Panasonic leverages direct sales to secure wafer allocation for automotive-grade chipset production.
- Distributors:Intermediary networks aggregating demand across regional aftermarket shops. Distributor relationships dominate Southeast Asia's fragmented installation base.
- Specialized Retail:Dedicated automotive electronics retailers with technical installation capability. Japan's specialized retail channel maintains premium positioning for acoustic system upgrades.
Direct sales anchor the value concentration; online retail is gaining share fastest as module standardization reduces installation barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate intelligent cockpit manufacturing, with Shanghai and Suzhou hosting BYD and NIO supply chain operations. This corridor anchors regional production capacity.
China
MIIT data localization mandates for in-cabin telemetry restrict cross-border cloud processing for voice recognition and streaming services. Domestic OEMs BYD and NIO anchor intelligent cockpit production in Shanghai and Shenzhen, compressing procurement lead times for regional assemblers.
Japan
METI cybersecurity management system requirements compel suppliers to certify over-the-air update protocols for connected vehicle platforms. Panasonic Corporation leverages vertical fabrication partnerships to secure wafer supply for automotive-grade chipsets from domestic foundries.
South Korea
Corporate fleet leasing companies demand modular hardware architectures supporting mid-contract software upgrades. Hyundai Mobis supplies entertainment modules within the Hyundai Motor Group procurement framework, sustaining captive demand across electric platforms.
India
TRAI spectrum allocation frameworks for vehicle-to-everything communication accelerate OEM decisions on embedded cellular modems versus tethered smartphone dependency. Aftermarket demand concentrates in Maharashtra and Tamil Nadu where owners upgrade base audio configurations in entry-level vehicles.
Thailand
A-segment vehicle production for domestic and export markets drives Bluetooth module standardization across entry-level trims. Eastern Economic Corridor manufacturing zones host Japanese OEM assembly operations sourcing cockpit systems from regional tier-one suppliers.
Asia Pacific in-Car Entertainment System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with acoustic engineering firms capturing premium-tier positions while diversified electronics conglomerates dominate volume production. The supplier base concentrates around three strategic archetypes: integrated semiconductor-to-systems conglomerates, keiretsu-captive tier-one suppliers, and independent acoustic specialists. Competitive moves center on foundry capacity reservations for automotive-grade chipsets and certification investments for sovereign data compliance architectures.
Among Japan-based diversified manufacturers, Panasonic Corporation and Denso Corporation exemplify contrasting structural positions. Panasonic operates as a vertically integrated systems provider with fabrication partnerships securing upstream semiconductor supply. Denso occupies a keiretsu-captive position within Toyota's procurement framework, illustrating how structural lock-in limits market access for independent module suppliers. Harman International Industries represents the branded specialist archetype, competing through acoustic engineering differentiation rather than manufacturing scale.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Denso Corporation |
| Harman International Industries |
| Alpine Electronics Inc. |
| Pioneer Corporation |
| Robert Bosch GmbH |
| Visteon Corporation |
| Continental AG |
| Hyundai Mobis |
| Others |
Value Chain & Pricing Dynamics
Acoustic engineering talent concentration in Japan's Kansai region compresses labor-cost differentials between premium branded audio systems and commodity speaker modules, widening pricing-tier spreads as OEMs source tier-one acoustic partnerships versus standard-fit configurations from regional assemblers.
Pricing Analysis
Volume placements in Bluetooth-enabled entry-level modules across India and Thailand sacrifice margin for scale, while premium intelligent cockpit systems in China's eastern manufacturing corridor command price premiums through MIIT-mandated data localization compliance. Certification investment for Japan's METI cybersecurity requirements separates tier-one supplier pricing from uncertified competitors. Cost compression in A-segment hardware intensifies because foundry capacity constraints transmit semiconductor price instability into head-unit bill-of-materials. Fleet procurement managers in South Korea's corporate leasing segment demonstrate highest price sensitivity, whereas premium electric vehicle buyers absorb specification-driven premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Toyota's keiretsu procurement framework and Hyundai Motor Group's integrated supply base, while distributor networks aggregate fragmented aftermarket demand across Southeast Asia. Wafer fabrication concentrates in Taiwan, South Korea, and Japan, with automotive-grade chipset production drawing from specialty foundry capacity. Supply chain risk centers on single-source vulnerability for 12-volt CAN bus legacy components as OEMs transition to Ethernet-backbone electric platforms. Distribution runs through tier-one suppliers integrating entertainment modules into vehicle electrical architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity reservation for automotive-grade chipsets props pricing power across the forecast window, constraining supply elasticity for embedded infotainment modules.
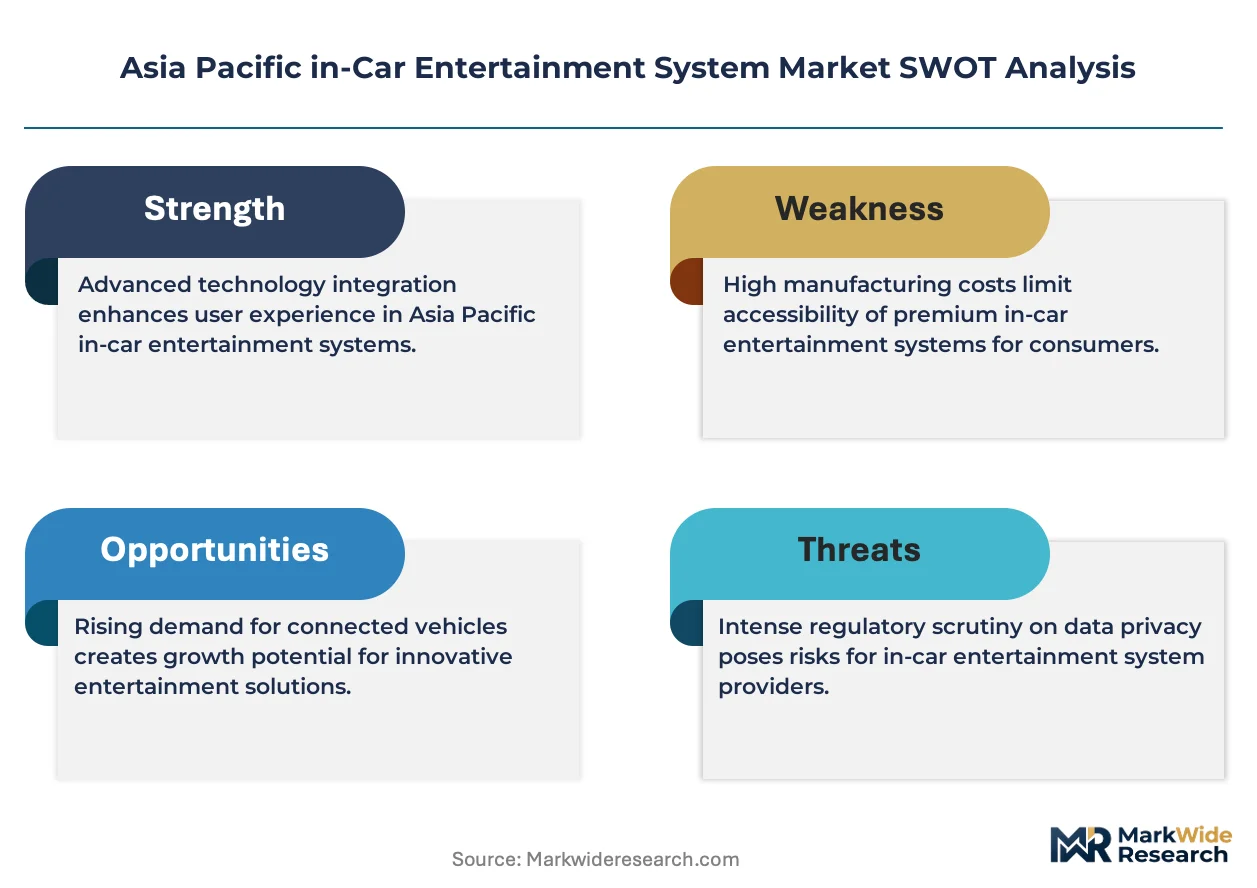
For Market Incumbents: Deploy certification investment as the primary defensive lever. Secure METI cybersecurity management system compliance to lock in Japanese OEM supplier contracts before regulatory deadlines tighten. Accelerate backward integration into wafer allocation partnerships to insulate against semiconductor input volatility from consumer electronics competition. For New Entrants and Emerging Players: Aftermarket distributors in India's Maharashtra and Tamil Nadu states offer the most penetrable channel for cost-optimized Bluetooth module penetration. Target A-segment vehicle owners upgrading base audio configurations through e-commerce platforms. Pursue white-label manufacturing partnerships with eastern China assemblers to compress procurement lead times for regional OEMs. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated semiconductor-to-systems specialists given sovereign data compliance tailwinds across China, Japan, and India. Long-term viability favors suppliers with established automotive security practices and regional cloud infrastructure. Monitor TRAI spectrum allocation implementation timelines as inflection indicator for embedded cellular modem demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Panasonic's vertical fabrication partnerships secure wafer supply for automotive-grade chipsets against consumer electronics competition. |
| Cybersecurity Certification Investment | METI compliance requirements restructure supplier liability frameworks for over-the-air update protocols in Japanese OEM contracts. |
| Regional Cloud Infrastructure Localization | MIIT data localization mandates create demand for China-specific voice recognition architectures separate from cross-border processing. |
| Modular Hardware Architecture Development | South Korean fleet leasing companies demand mid-contract software upgrade capability, compressing hardware refresh timelines. |
| Acoustic Engineering Partnership Expansion | Harman's branded audio positioning as tier-one OEM standard equipment captures trim-level differentiation premiums in mid-market sedans. |
Study Parameters
Independent corroboration across Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations underwrites the qualitative findings. Primary interviews with Denso Corporation supply chain managers and Hyundai Mobis product development leads combined with secondary validation from vehicle production databases, IHS Markit registration data, and MIIT regulatory filings. Bottom-up segment sizing triangulates against top-down market estimates across infotainment, audio, video, and navigation system categories.
Comparable-period anchoring to historical intelligent cockpit deployment rates establishes baseline growth trajectories across the projection horizon. The analytical framework models vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster as core segmentation dimensions. CAGRs derive from weighted average of technology adoption curves and replacement cycle dynamics. Forecast inputs incorporate TRAI spectrum allocation timelines and METI cybersecurity implementation phases.
Caveats apply where semiconductor foundry capacity reallocation or sovereign data requirement fragmentation could materially shift the outlook. Forecasts reflect assumptions regarding embedded cellular modem penetration rates and smartphone mirroring displacement trajectories. Practitioners should monitor foundry utilization rates and regional regulatory implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
Automotive Split-View Camera Module Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
In-Car Wireless Charging Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Automotive Wires Market