
 Mlccs for Automotive Electronics Market | 2026-2036
Mlccs for Automotive Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Mlccs for Automotive Electronics Market Insights
AEC-Q200 automotive passive component qualification is reorganizing the competitive landscape for MLCC suppliers serving vehicle electronics. Murata Manufacturing Co., Ltd. leverages its ceramic formulation heritage to dominate high-reliability grades for powertrain inverters. TDK Corporation anchors its position through ferrite and dielectric material science leadership in low-ESL architectures. Samsung Electro-Mechanics competes on scale, operating massive electrode-printing capacity that underpins cost structures for infotainment-grade components.
Multilayer ceramic capacitors for automotive electronics are non-polarized passive devices built from alternating layers of ceramic dielectric and metal electrode, typically achieving capacitance densities above 100 microfarads per cubic centimeter in X7R and C0G formulations; they stabilize voltage rails and filter noise across ECUs exposed to engine-bay temperatures exceeding 150 degrees Celsius. Specialty MLCC and low ESL MLCC categories command the strongest margin pools, as Advanced Driver Assistance Systems and sensor modules require tighter impedance control than legacy power-supply applications. Standard MLCC remains the volume foundation, though pricing pressure from Tier-1 Suppliers compresses returns at the commodity tier.
FDA oversight of automotive-grade electronics remains indirect, but NHTSA safety recalls for ADAS failures cascade into MLCC reliability requirements, while EPA fuel-economy rules push electrification that multiplies capacitor counts per vehicle. ISO 26262 functional-safety mandates and AEC-Q200 stress-test protocols together determine which suppliers gain design-in access at OEMs and Tier-1 Suppliers. Stakeholders must track how embedded MLCC technology and chip-on-board integration reshape physical form factors before next-platform vehicle architectures lock in component footprints.
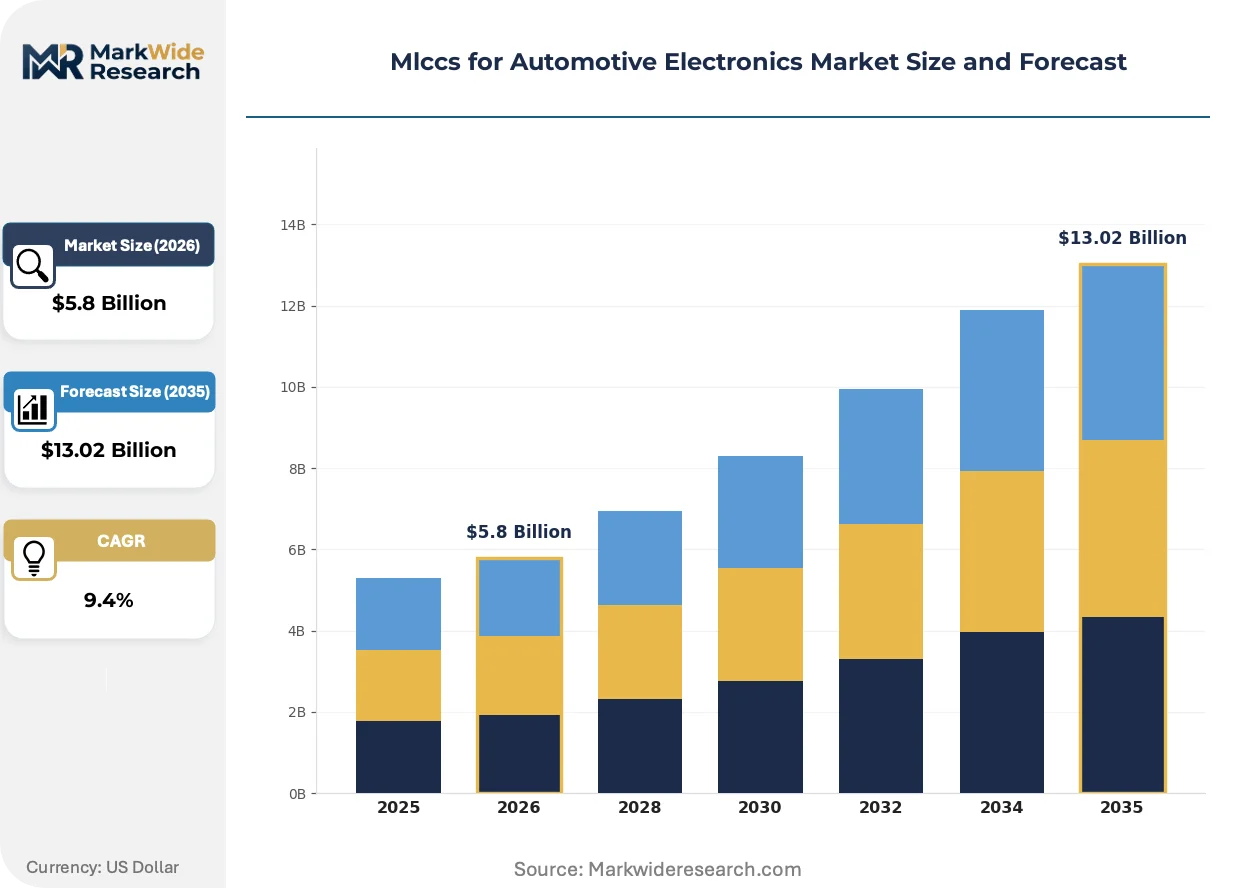
Market Dynamics
Electric vehicle powertrain electrification is compressing MLCC qualification timelines as AEC-Q200 stress-test protocols collide with faster OEM platform cycles, forcing suppliers to parallelize reliability validation with design-in phases.
Growth Catalysts
- EV Powertrain Density:Battery management systems and inverter modules require 3-4x more MLCC units per vehicle than internal combustion architectures, pulling high-voltage-rated dielectrics into mass production.
- China MEE Emissions Rules:Tighter particulate and carbon mandates accelerate domestic EV adoption, expanding addressable vehicle volumes for automotive-grade ceramic capacitors.
- Kyoto-Nagoya Manufacturing Cluster:Concentrated precision ceramic processing infrastructure enables rapid prototyping cycles that shorten OEM qualification paths for next-generation dielectric formulations.
Market Restraints
- Palladium Electrode Cost Volatility:Precious metal price swings in base electrode materials compress margin predictability for Class 2 dielectric MLCC production.
- Japanese Supplier Concentration:Overreliance on ceramic formulation IP held by producers in the Kansai region creates geographic supply vulnerability during seismic or logistics disruptions.
- AEC-Q200 Timeline Compression:Extended thermal cycling and humidity bias test requirements extend certification cycles beyond typical automotive platform development windows.
Strategic Opportunities
- India Automotive Electronics:PLI scheme incentives for domestic EV and component manufacturing open greenfield demand for AEC-Q200 qualified MLCC supply localized to South Asian assembly.
- Chip-on-Board Integration:Embedded capacitor technology converging with substrate miniaturization enables form-factor reduction that displaces discrete component mounting in ADAS sensor modules.
- EU Battery Regulation:Cell passport traceability mandates create specification pull for high-reliability capacitors in battery management systems serving European OEM export markets.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Shortage of engineers capable of integrating thermal, electrical, and mechanical stress modeling slows MLCC failure-mode prediction for 150°C+ underhood applications.
- ISO 26262 Functional Safety Integration:Aligning capacitor reliability data with ASIL-rated component databases requires restructured quality management systems that extend internal audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mlccs for Automotive Electronics Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard MLCC, High Voltage MLCC, Specialty MLCC, Low ESL MLCC Application: Power Supply, Infotainment Systems, Advanced Driver Assistance Systems, Sensor Modules End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Automotive Grade, Surface Mount Technology, Chip-on-Board, Embedded MLCC |
| Companies Covered | Murata Manufacturing Co., Ltd., TDK Corporation, Samsung Electro-Mechanics, Taiyo Yuden Co., Ltd., Yageo Corporation, KYOCERA AVX Components Corp., Walsin Technology Corporation, Nippon Chemi-Con Corp., Vishay Intertechnology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mlccs for Automotive Electronics Market Trends and Innovations
Material science advances in ceramic dielectric formulations and electrode metallurgy are redefining temperature-performance tradeoffs, while regulatory pressure on vehicle electrification compresses component validation cycles.
Base-metal electrode technology utilizing nickel or copper alloys is displacing traditional silver-palladium systems in mid-range automotive MLCC production. Tier-1 Suppliers in powertrain inverter sourcing are accelerating qualification of BME-based X7R formulations to reduce precious metal exposure. This transition is displacing legacy precious-metal-dependent supply chains and reallocating margin pools toward ceramic formulation IP holders.
China's MEE enforcement of dual carbon goals tightens emissions auditing across automotive supply chains, indirectly elevating MLCC reliability requirements for energy-recovery systems. Domestic OEMs must demonstrate component traceability that satisfies both GB standards and export-market AEC-Q200 equivalency. Powertrain electrification programs serving European and North American export markets face the steepest compliance velocity.
Consolidated procurement by battery-electric vehicle platforms favors direct supplier relationships over traditional Tier-1 distribution channels. OEM technical teams now engage MLCC producers for dielectric customization in motor-drive inverters, bypassing standard catalog offerings. This pattern concentrates most visibly in German and South Korean automotive electronics sourcing, where platform-scale commitments justify co-development investments.
Mlccs for Automotive Electronics Market Segmentation
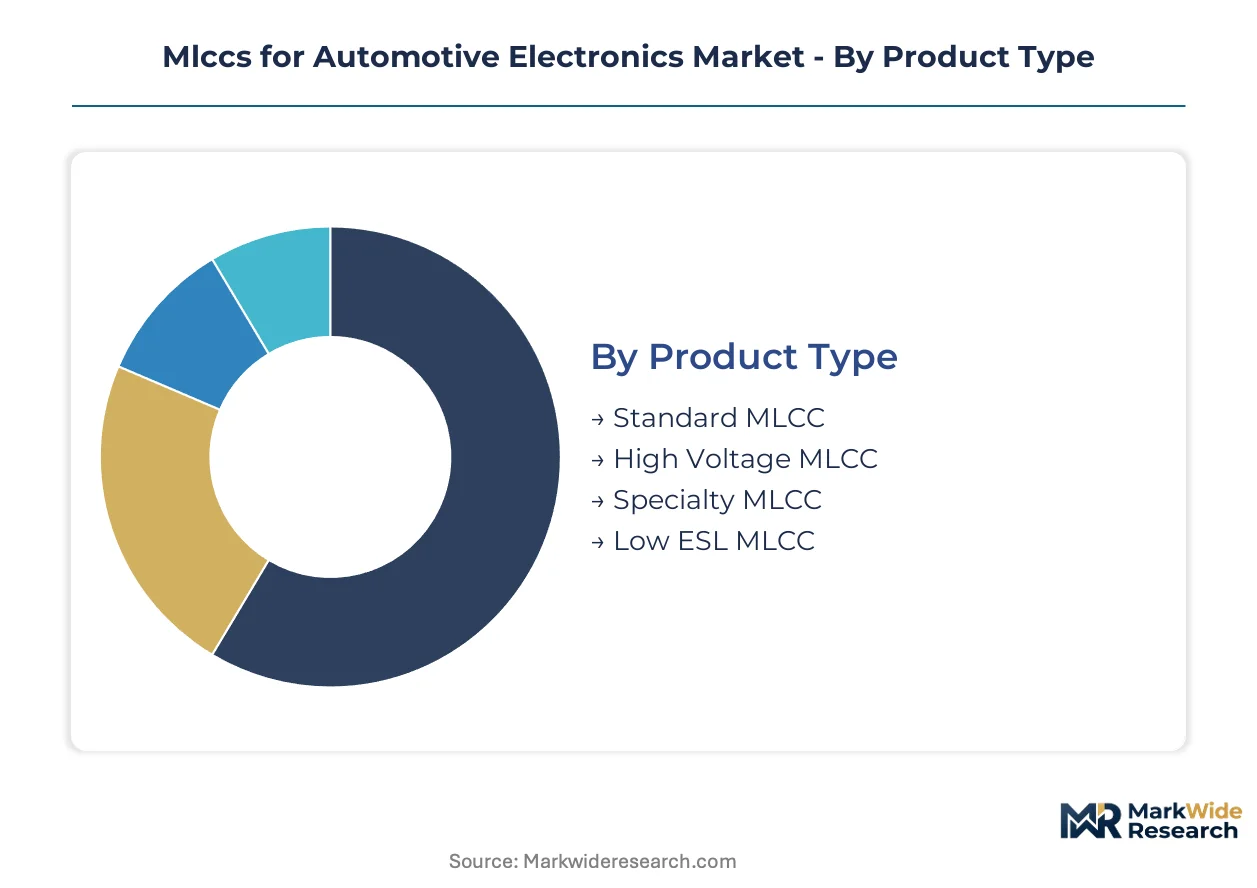
MLCC segmentation for automotive electronics reveals how dielectric performance tiers map to distinct margin pools and qualification barriers. Product type and application dimensions expose where substitute technologies threaten incumbent ceramic formulations.
Product Type:
Substitution pressure from film capacitors and aluminum electrolytic alternatives concentrates most acutely in commodity dielectric tiers, forcing ceramic suppliers to defend position through AEC-Q200 reliability differentiation.
- Specialty MLCC:Custom dielectric formulations achieve ultra-stable capacitance across -55°C to 175°C temperature excursions. Demand concentrates in German powertrain inverter sourcing where ISO 26262 ASIL-D ratings mandate predictable failure modes.
- Low ESL MLCC:Interdigitated electrode architectures suppress equivalent series inductance below 0.1 nH for high-frequency decoupling. Korean ADAS sensor module producers specify these for lidar and radar signal chains where impedance control determines measurement fidelity.
- High Voltage MLCC:Dielectric thickness engineering achieves 630V+ ratings for battery management system isolation.
- Standard MLCC:X7R and C0G formulations serve non-safety-critical body electronics with catalog-specified tolerances.
Standard MLCC anchors the volume base while Specialty MLCC gains share at the steepest rate.
Application:
Application segmentation tracks how electrification redistributes capacitor counts across vehicle domains, with power electronics absorbing disproportionate unit growth.
- Power Supply:DC-DC converter and inverter modules require 3-4x MLCC density per vehicle versus ICE architectures. Chinese EV platform sourcing specifies high-voltage-rated dielectrics for 800V architectures under MEE emissions compliance timelines.
- Advanced Driver Assistance Systems:Sensor fusion processors demand tight voltage ripple suppression for compute-intensive perception algorithms. Japanese OEM technical teams specify low-ESL arrays for camera and radar preprocessing circuits.
- Infotainment Systems:Touchscreen controllers and audio amplifiers use mid-grade X7R for bulk capacitance.
- Sensor Modules:Pressure, temperature, and position sensors deploy C0G for signal path stability.
Power Supply applications absorb the largest absolute unit volumes while Advanced Driver Assistance Systems expand most quickly.
End User:
End user segmentation captures how procurement authority is shifting from traditional Tier-1 distributors toward direct OEM engagement for platform-scale programs.
- OEMs:Volkswagen, Hyundai, and BYD technical teams now source MLCC directly for motor-drive inverters, bypassing catalog distribution. Co-development contracts specify dielectric customization for 10-year vehicle lifecycle reliability.
- Tier-1 Suppliers:Bosch, Denso, and Continental maintain consolidated procurement leverage for infotainment and body electronics modules where standard grades suffice.
- Vehicle Assemblers:Contract manufacturers in Mexico and Eastern Europe execute build-to-print specifications without design authority.
- Aftermarket Providers:Independent repair channels source cross-reference equivalents for legacy vehicle servicing.
Tier-1 Suppliers retain the volume foundation while OEMs capture share fastest through direct supplier relationships.
Technology:
Technology segmentation tracks integration depth, from discrete surface-mount components toward substrate-embedded architectures that eliminate discrete mounting.
- Embedded MLCC:Ceramic layers fuse directly into printed circuit board substrates, eliminating solder joints and reducing form factor by 60%. German automotive electronics producers qualify these for 77GHz radar front-ends where space constraints dominate.
- Chip-on-Board:Uncapsulated die attach enables 3D stacking in camera module processing chains. Korean Tier-1s specify COB for surround-view camera aggregators.
- Automotive Grade:AEC-Q200 qualified components with extended thermal cycling validation.
- Surface Mount Technology:Standard solder-reflow assembly for high-volume ECU production.
Surface Mount Technology maintains the installed base while Embedded MLCC climbs the fastest toward next-platform vehicle architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German powertrain engineering teams and Chinese EV platform architects currently absorb the largest MLCC procurement volumes, with Japanese ceramic suppliers maintaining formulation leadership and South Korean electronics producers driving specification intensity in ADAS modules.
China
Domestic OEMs like BYD and NIO specify high-voltage MLCC arrays for 800V battery architectures under MEE emissions enforcement timelines. The dual carbon goals framework compresses supplier qualification windows for components serving energy-recovery systems. Yangtze River Delta manufacturing corridors host electrode-printing facilities that feed MLCC assembly operations serving both domestic EV platforms and European export contracts.
Germany
Volkswagen and BMW technical teams source MLCC directly for motor-drive inverters, bypassing traditional Tier-1 distribution channels. KBA type-approval requirements for functional safety cascade into AEC-Q200 reliability specifications for powertrain electronics. Bavaria-based automotive electronics producers qualify embedded MLCC substrates for 77GHz radar front-ends where space constraints dominate module design.
Japan
Toyota and Honda electrification programs pull high-reliability dielectrics for hybrid powertrain inverters requiring 10-year lifecycle predictability. METI industrial policy supports ceramic material science research through designated technology clusters. The Kyoto-Nagoya corridor concentrates precision ceramic processing infrastructure that enables rapid prototyping cycles for next-generation dielectric formulations.
South Korea
Hyundai-Kia platform teams specify low-ESL MLCC arrays for lidar and radar signal chains in Highway Driving Assist systems. MFDS automotive electronics guidelines align with ISO 26262 functional safety mandates for ASIL-rated components. Seoul Capital Area packaging houses integrate chip-on-board capacitor technology for surround-view camera aggregators serving domestic and North American vehicle programs.
United States
General Motors and Ford battery-electric platform sourcing concentrates high-voltage MLCC demand for Ultium and F-150 Lightning powertrain modules. NHTSA safety recall patterns for ADAS failures elevate MLCC reliability requirements in sensor fusion processors. Michigan and Tennessee automotive electronics corridors host Tier-1 assembly operations that specify AEC-Q200 qualified components for underhood temperature extremes.
Mlccs for Automotive Electronics Market Competitive Landscape
Player mix skews toward vertically integrated ceramic specialists with in-house dielectric formulation capabilities. Market structure concentrates around Japanese and South Korean producers controlling electrode metallurgy and ceramic material science IP. Two strategic archetypes dominate: precision ceramic formulators serving powertrain safety-critical applications, and scale-driven electrode printers optimizing cost structures for infotainment-grade volumes. Competitive moves center on co-development contracts with OEM platform teams and qualification acceleration for AEC-Q200 stress-test protocols.
Among Japanese ceramic specialists, Murata Manufacturing Co., Ltd. and TDK Corporation occupy positions exemplifying formulation-led competitive advantage, while Samsung Electro-Mechanics represents the scale-driven archetype with massive electrode-printing capacity. These three anchors illustrate how geographic clustering around Kyoto, Nagoya, and Suwon shapes supplier-customer proximity for platform-scale automotive electronics programs. KYOCERA AVX Components Corp. and Vishay Intertechnology Inc. sit within diversified passive component portfolios that span automotive-grade MLCC alongside broader capacitor and resistor offerings.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| TDK Corporation |
| Samsung Electro-Mechanics |
| Taiyo Yuden Co., Ltd. |
| Yageo Corporation |
| KYOCERA AVX Components Corp. |
| Walsin Technology Corporation |
| Nippon Chemi-Con Corp. |
| Vishay Intertechnology Inc. |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week lead times for AEC-Q200 qualified MLCCs concentrate pricing power with Japanese ceramic formulators while compressing margin buffers for electrode-dependent producers. This inventory tightness amplifies cost pass-through from palladium and nickel electrode markets into powertrain inverter sourcing contracts.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange palladium and nickel pricing dominate high-reliability MLCC procurement. Price differentiation hinges on AEC-Q200 certification grade and volume scale, with ASIL-D rated components commanding substantial premiums over infotainment-grade alternatives. Cost compression in standard X7R tiers intensifies as Korean electrode-printing scale erodes catalog margins. Tier-1 suppliers exhibit highest price sensitivity in body electronics modules, while OEM technical teams accept premium positioning for motor-drive inverter co-development programs.
Supply Chain Analysis
Inventory buffers below six weeks signal vulnerability in automotive-grade ceramic supply. Manufacturing concentrates in Japan, South Korea, and China, with the Kyoto-Nagoya corridor anchoring precision dielectric formulation and the Yangtze River Delta hosting electrode-printing scale. Raw material dependencies on palladium, nickel, and barium titanate ceramic feedstock expose margins to commodity volatility. Single-source vulnerability concentrates in proprietary ceramic formulations held by Murata and TDK. Distribution runs through direct OEM contracts for platform-scale programs, with Tier-1 distributors retaining infotainment-grade volume channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment defensive moat. AEC-Q200 qualification timelines and ISO 26262 functional safety mandates create switching costs that cement incumbent positions across powertrain safety-critical applications.
For Market Incumbents: Fortify ceramic formulation IP through METI-supported R&D clusters in the Kyoto-Nagoya corridor. Accelerate embedded MLCC qualification for 77GHz radar substrates to preempt substitution by film capacitor alternatives. Expand captive electrode-printing capacity to reduce palladium price exposure in Class 2 dielectric production.
For New Entrants and Emerging Players: Differentiate on India PLI scheme localization for domestic EV platform supply. Target battery management system tier where AEC-Q200 equivalency requirements remain less stringent than motor-drive inverter grades. Pursue co-development partnerships with Yangtze River Delta electrode houses to bypass Japanese ceramic IP concentration.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because AEC-Q200 qualification barriers and OEM direct-sourcing trends favor scale. Acquisition targets with embedded capacitor substrate capabilities and existing German OEM relationships offer strongest positioning. Monitor China MEE enforcement velocity as inflection signal for domestic EV platform demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Qualification Acceleration | Shortens design-in cycles for BYD and Volkswagen powertrain platforms. |
| Base-Metal Electrode Transition | Reduces palladium exposure in Samsung Electro-Mechanics cost structures. |
| Embedded MLCC Substrate Development | Enables 60% form-factor reduction for German 77GHz radar modules. |
| India Manufacturing Localization | Captures PLI scheme incentives for domestic EV component supply. |
| Direct OEM Co-Development Contracts | Bypasses Tier-1 distribution for Hyundai-Kia platform-scale procurement. |
Research Methodology
Operator-level perspectives from MLCC procurement managers at Tier-1 suppliers, OEM platform engineers, ceramic materials scientists, and electrode-printing facility directors anchored the qualitative base. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, METI industrial policy filings, and China MEE emissions enforcement records. Bottom-up unit economics triangulated against top-down market sizing across dielectric grade, application, and regional production cluster dimensions.
Sensitivity analysis tested forecast robustness across palladium price bands, EV adoption velocity scenarios, and AEC-Q200 timeline compression assumptions. Segmentation modeling incorporated product type, application domain, end-user procurement authority, and integration technology depth. CAGRs derived from vehicle content-per-unit trajectories, platform electrification roadmaps, and regional regulatory compliance timelines. Industry-specific inputs included powertrain inverter MLCC density multiples, ADAS sensor module low-ESL specifications, and embedded capacitor substrate adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained EV platform electrification and stable AEC-Q200 qualification protocols; material deviation in China MEE enforcement or palladium supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
Construction Machinery Wiring Harness Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Over the Air Engine Control Module Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market