
 Automotive Wire Harness Tape Market | 2026-2036
Automotive Wire Harness Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wire Harness Tape Market Insights
Buyer concentration among tier-1 harness suppliers is rebalancing as EV startups diversify procurement beyond incumbent relationships. 3M Company leverages its pressure-sensitive adhesive patent portfolio to sustain pricing power in OEM qualification programs. Nitto Denko Corporation anchors Asian supply chains through captive resin compounding operations in Japan and Thailand. Tesa SE competes on European regulatory pre-certification, reducing customer validation cycles for MDR-aligned automotive cable assemblies.
Automotive wire harness tape denotes a flexible substrate coated with adhesive, engineered to withstand temperatures from minus forty to one hundred fifty degrees Celsius while providing electrical insulation and abrasion resistance for bundled vehicle wiring. Fabric tape variants dominate premium vehicle segments where acoustic dampening and hand-tear ergonomics justify material cost premiums over PVC. Pressure-sensitive adhesive technology leads volume consumption across OEM assembly lines, though thermoplastic formulations are capturing share in battery thermal management applications requiring repositionability during pack assembly.
REACH restrictions on phthalate plasticizers and RoHS substance thresholds constrain PVC tape formulations across European automotive value chains, while EPA and NHTSA durability standards shape North American product qualification protocols. OEMs and tier-1 suppliers must monitor evolving flammability test methods from ISO and SAE committees as high-voltage architectures redefine tape performance specifications. Stakeholders should prioritize adhesive chemistry partnerships that preempt regulatory substance bans rather than react to compliance deadlines.
Market Dynamics
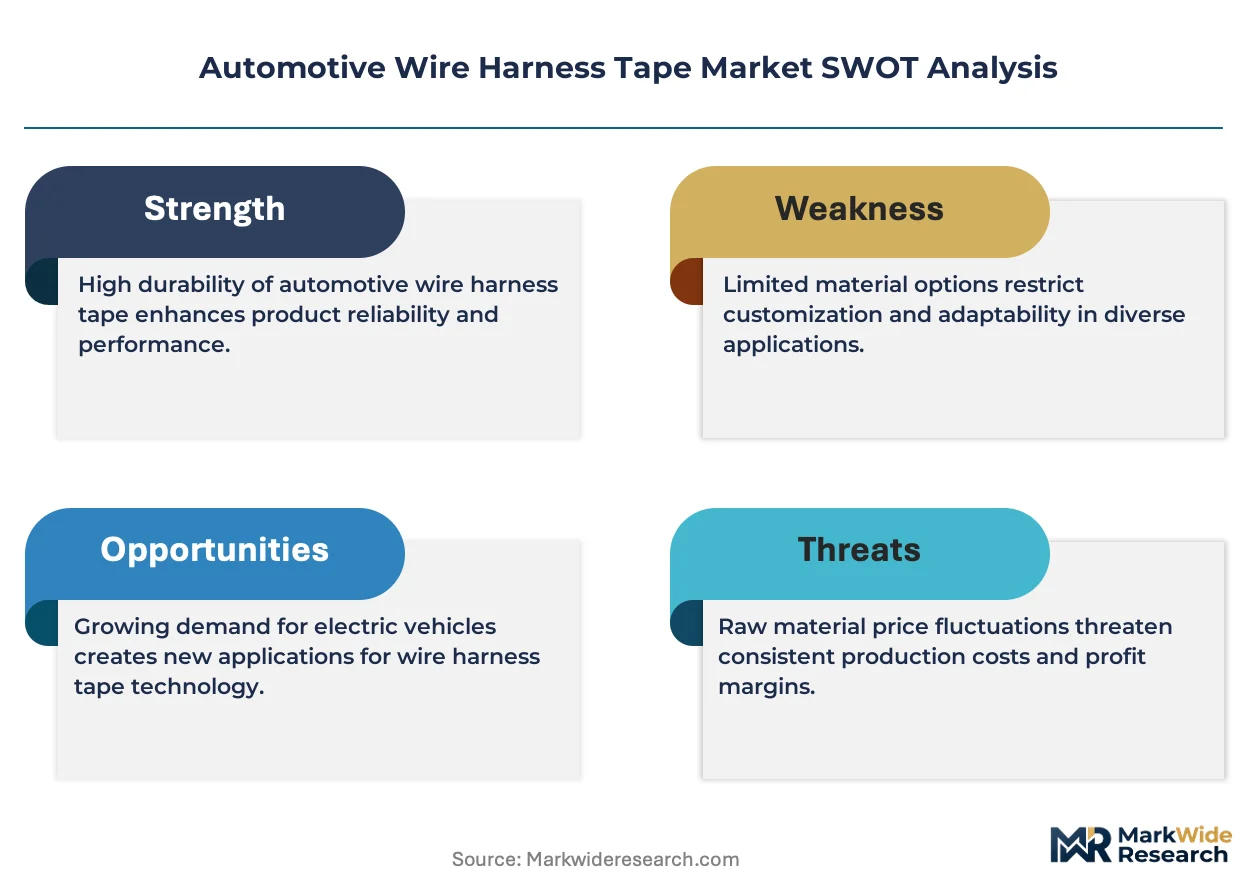
High-voltage battery architectures in electric vehicles are recasting material specifications for wire harness insulation, forcing adhesive chemistries and substrate combinations to satisfy thermal runaway containment standards that did not exist for internal combustion platforms.
Growth Catalysts
- Flame-Retardant Mandates:NHTSA durability protocols and SAE flammability test methods for high-voltage battery packs are compelling OEM specification updates across North American assembly lines.
- China:Domestic EV production clusters in Shanghai and Shenzhen are consuming specialty tapes for 800-volt architectures at volumes that reshape regional resin supply.
- Zero-Halogen Chemistry:REACH substance restrictions on halogenated compounds are accelerating formulation shifts toward low-smoke alternatives in German automotive value chains.
Market Restraints
- Petrochemical Volatility:Acrylic and rubber-based adhesive feedstocks expose margins to naphtha and butadiene price swings that tape manufacturers cannot fully pass through.
- Asian Supply Concentration:Captive resin compounding in Japan and Thailand creates dependency risks for European and North American converters without backward integration.
- Performance Trade-offs:Low-smoke zero-halogen formulations sacrifice tensile strength and hand-tear ergonomics versus legacy PVC, limiting adoption in premium acoustic-dampening segments.
Strategic Opportunities
- Battery Thermal Management:Thermoplastic adhesive repositionability during pack assembly is opening specification windows that pressure-sensitive tapes cannot serve.
- India:PLI scheme subsidies for domestic EV manufacturing are creating first-mover advantages for tape suppliers qualifying with Mahindra and Tata Motors.
- EU Green Deal:Circular economy mandates for automotive recyclability favor mono-material tape constructions that simplify end-of-life wire harness processing.
Industry Challenges
- Qualification Timelines:OEM platform validation cycles spanning 18-24 months delay revenue recognition for new adhesive formulations.
- Skills Shortage:Formulation chemists with expertise in both pressure-sensitive adhesion and high-voltage electrical insulation command premiums that mid-tier suppliers cannot match.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wire Harness Tape Market |
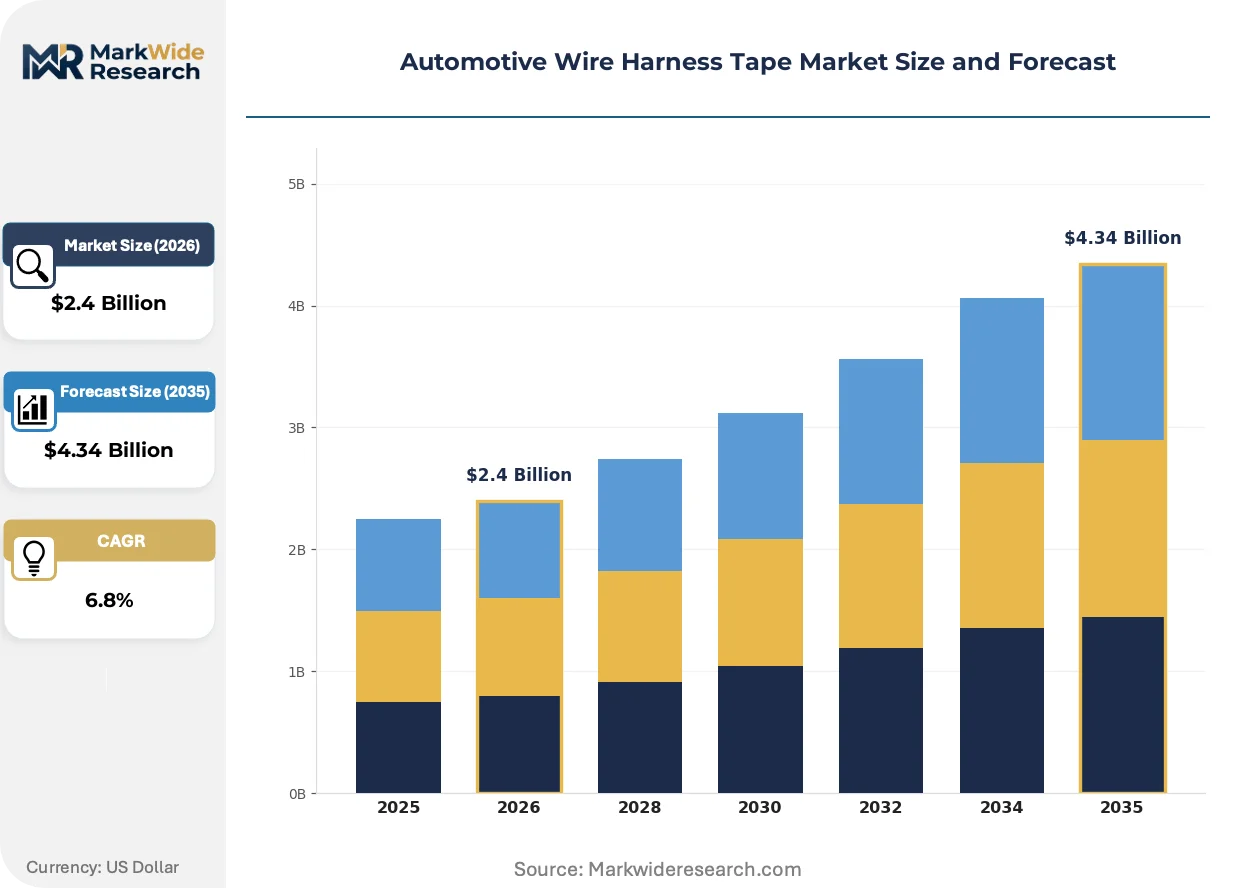
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat-Shrink Tape, PVC Tape, Fabric Tape, Rubber Tape Application: Electrical Insulation, Protective Covering, Bundling, Noise Reduction End User: OEMs, Aftermarket, Tier-1 Suppliers, Automotive Assemblers Technology: Pressure-Sensitive Adhesive, Thermoplastic, Non-Adhesive, Conductive |
| Companies Covered | 3M Company, Nitto Denko Corporation, tesa SE, Avery Dennison Corporation, Saint-Gobain, Intertape Polymer Group, Berry Global, Scapa Group, Henkel AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wire Harness Tape Market Trends and Innovations
Material science advances and regulatory compression are converging to redefine competitive advantage in automotive wire harness protection, with performance specifications now set by battery safety engineers rather than traditional wiring specialists.
Silicone-modified acrylic adhesives are rewriting thermal performance benchmarks for harness tapes exposed to battery pack hotspots exceeding 150 degrees Celsius. EV battery module assemblers in South Korea and Germany are specifying these chemistries for thermal runaway propagation barriers. The technology is compressing qualification advantages held by incumbent suppliers with legacy rubber-based portfolios.
REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC tape reformulation across European automotive supply chains. ECHA substance evaluations have accelerated substitution timelines, compelling compounders to validate alternative plasticizers ahead of sunset dates. German tier-1 harness suppliers are pre-certifying low-phthalate and phthalate-free constructions to maintain platform access.
Fleet operators and battery leasing entities are unbundling wire harness maintenance from vehicle service contracts, creating aftermarket specification authority that bypasses OEM sourcing committees. Independent service networks in the United States and Netherlands are establishing parallel qualification pathways for replacement-grade tapes. This channel fragmentation is most visible in commercial EV segments where total cost of ownership contracts shift material accountability to third-party maintainers.
Automotive Wire Harness Tape Market Segmentation
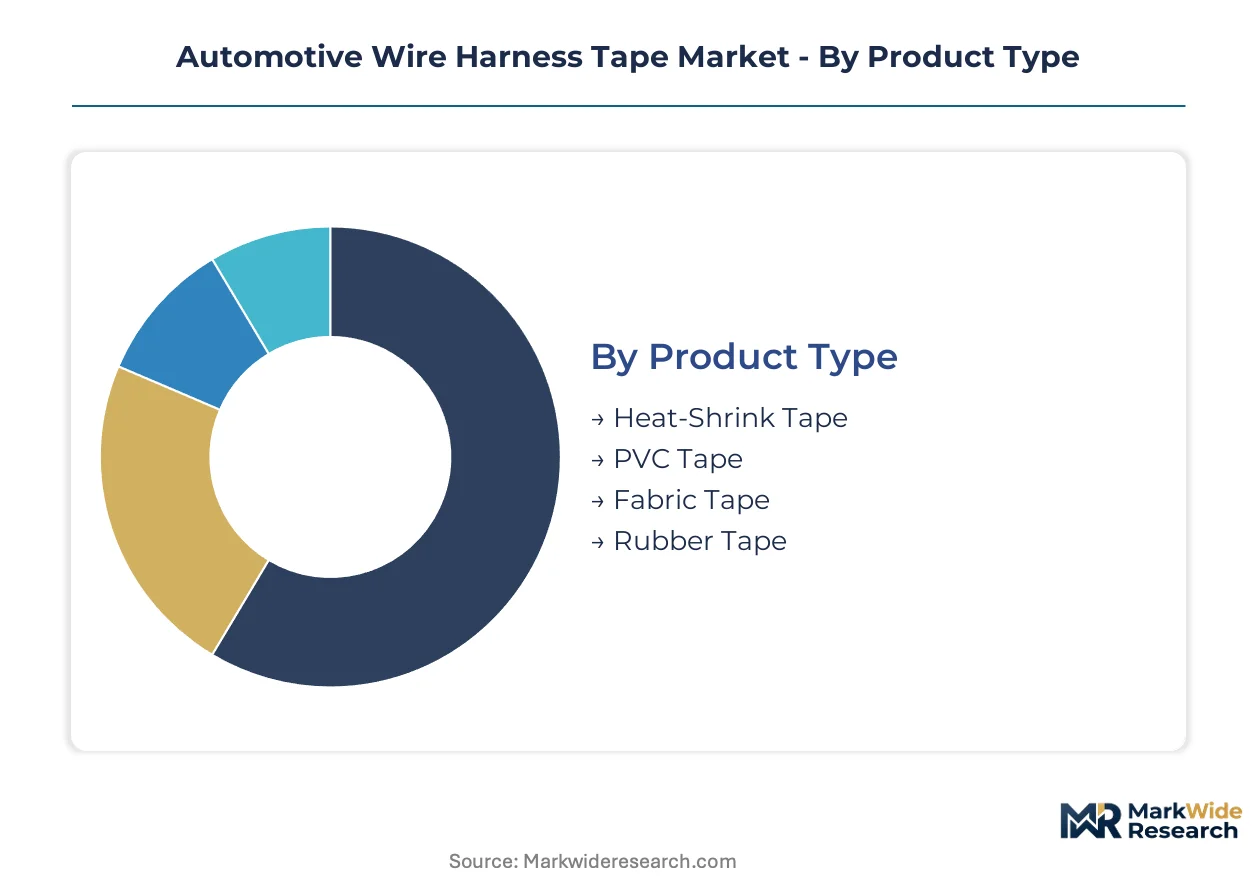
Wire harness tape procurement splits across four distinct decision axes. OEM platform engineers prioritize thermal performance and regulatory pre-certification. Aftermarket channels weight inventory velocity and hand-tear ergonomics differently.
Product Type:
Material selection hinges on temperature exposure profiles and acoustic requirements rather than unit cost alone.
- Fabric Tape:Woven polyester or fleece substrates bonded with rubber-based adhesives deliver acoustic dampening in cabin harness bundles. German premium OEMs in Stuttgart specify fabric constructions for NVH-sensitive platforms despite 40-60% cost premiums over polymer alternatives.
- PVC Tape:Plasticized polyvinyl chloride films dominate high-volume ICE platforms where temperature ceilings stay below 105 degrees Celsius. REACH phthalate restrictions are forcing compounders toward citrate and trimellitate plasticizer systems ahead of sunset dates.
- Heat-Shrink Tape:Cross-linked polyolefin constructions activate at 90-120 degrees Celsius for environmental sealing in underhood harness passages.
- Rubber Tape:Self-fusing ethylene propylene formulations serve high-voltage battery pack junctions requiring moisture exclusion without adhesive residues.
Volume sits with PVC Tape; growth tilts toward Fabric Tape.
Application:
Functional requirements vary sharply between powertrain architectures and cabin zones.
- Electrical Insulation:Dielectric strength specifications now start at 5 kV for 800-volt battery architectures versus 1 kV legacy thresholds. Korean cell manufacturers in Gyeonggi Province are driving qualification of silicone-modified acrylic systems for module-to-module busbar coverage.
- Noise Reduction:Fleece-backed tapes with 2-4mm loft densities absorb harness vibration in premium vehicle segments. Stuttgart-based tier-1s bundle fabric tapes with conduit clips for NVH-optimized routing through bulkhead penetrations.
- Protective Covering:Abrasion-resistant PVC and polyethylene films shield harnesses from firewall edges and suspension hardware.
- Bundling:Hand-tearable constructions with controlled unwind tension accelerate assembly line productivity in high-mix manufacturing environments.
Protective Covering commands the largest addressable base; Electrical Insulation is climbing the fastest.
End User:
Procurement authority is fragmenting as battery leasing and fleet maintenance models redistribute specification control.
- Tier-1 Suppliers:Delphi, Aptiv, and LEONI aggregate platform-level purchasing power across multiple OEM customers. Their qualification laboratories in Germany and Mexico set adhesive performance benchmarks that constrain converter formulation choices.
- OEMs:Direct procurement of specialty tapes for battery thermal management is bypassing traditional harness supplier relationships. Tesla's Gigafactory Nevada and BYD's Shenzhen operations maintain direct adhesive chemistry partnerships for thermal runaway barriers.
- Automotive Assemblers:Contract manufacturers in Eastern Europe and Mexico execute tape application per tier-1 supplied kits without independent material selection authority.
- Aftermarket:Independent service networks in the Netherlands and United States are establishing parallel qualification pathways for replacement-grade tapes as battery leasing contracts shift maintenance accountability.
Revenue concentrates with Tier-1 Suppliers; specification authority is drifting toward OEMs.
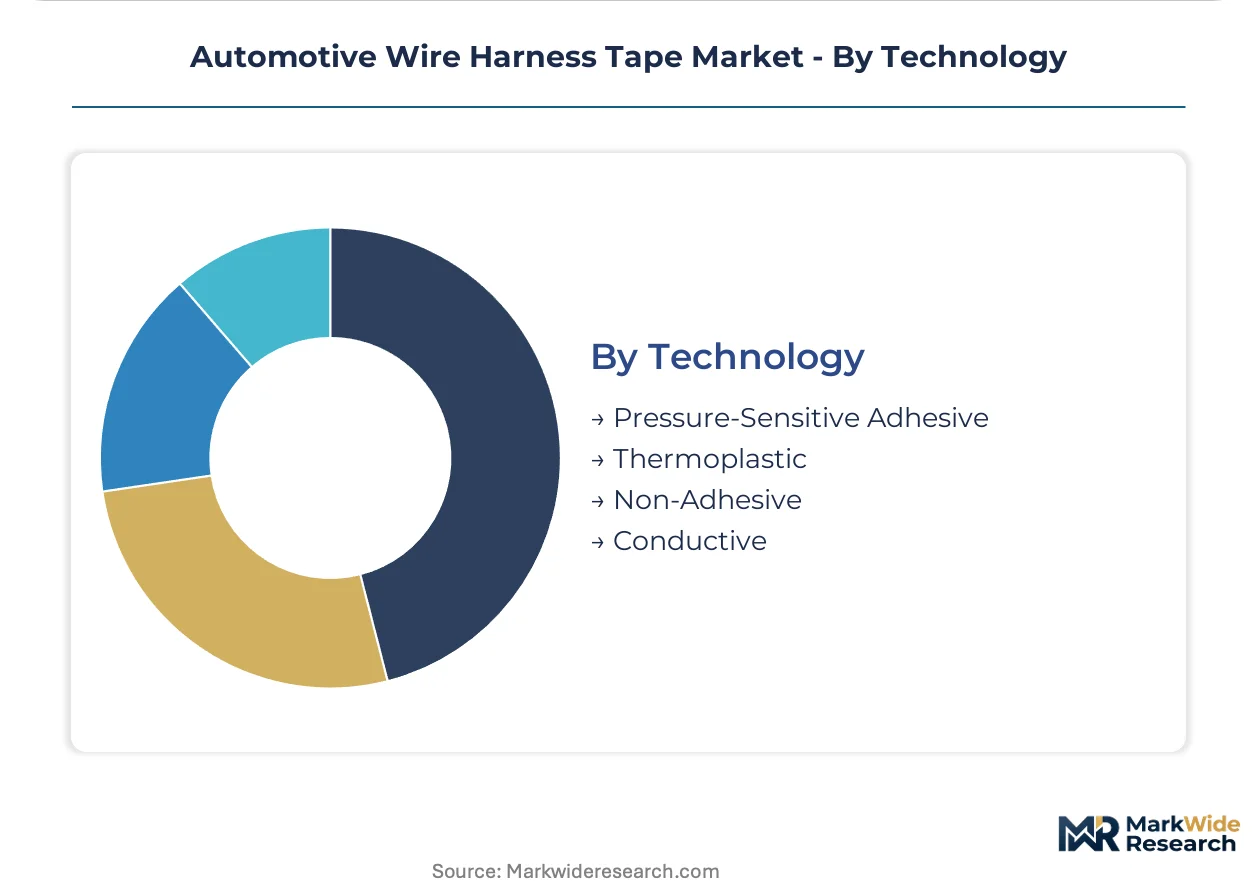
Technology:
Adhesive chemistry selection determines repositionability, temperature ceiling, and regulatory compliance simultaneously.
- Pressure-Sensitive Adhesive:Acrylic and rubber-based systems cure through solvent evaporation or UV initiation without thermal activation. 3M's solventless acrylic platforms dominate North American OEM assembly lines where immediate tack and shear resistance are non-negotiable.
- Thermoplastic:Hot-melt polyamide and polyester formulations activate at 120-180 degrees Celsius for repositionable bonding during battery pack assembly. South Korean module manufacturers specify thermoplastic tapes for cell-to-cell thermal interface management where post-assembly adjustment is required.
- Non-Adhesive:Self-fusing rubber tapes bond through molecular interpenetration without separate adhesive layers.
- Conductive:Silver-filled or carbon-loaded substrates provide electromagnetic shielding for high-voltage harnesses in proximity to CAN bus wiring.
Pressure-Sensitive Adhesive anchors current volume; Thermoplastic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast and resin compounding concentration in Japan's Chukyo industrial corridor anchor regional supply architectures for automotive wire harness tape manufacturing.
United States
NHTSA durability protocols for high-voltage battery packs are compelling OEM specification updates across Michigan and Tennessee assembly corridors. EPA oversight of adhesive solvent emissions shapes converter plant siting decisions in Ohio and Kentucky. Detroit-based tier-1 harness suppliers aggregate platform-level purchasing power that constrains formulation choices for regional tape converters.
Germany
REACH Annex XVII restrictions on phthalate plasticizers are accelerating PVC tape reformulation timelines across Baden-Württemberg automotive value chains. ECHA substance evaluations compel compounders to validate alternative plasticizers ahead of regulatory sunset dates. Stuttgart production clusters drive global specification-setting for premium vehicle NVH-optimized harness bundles.
China
Domestic EV production clusters in Shanghai and Shenzhen are consuming specialty tapes for 800-volt architectures at volumes that reshape regional acrylic resin supply. MIIT new energy vehicle safety standards mandate flame-retardant performance thresholds for battery pack wiring. BYD's Shenzhen operations maintain direct adhesive chemistry partnerships that bypass traditional harness supplier relationships.
Japan
Captive resin compounding operations in Aichi and Shizuoka prefectures anchor Asian supply chains for pressure-sensitive adhesive platforms. METI carbon neutrality roadmaps are pressuring petrochemical-dependent tape formulations toward bio-based feedstock transitions. Nagoya-based automotive electronics manufacturers specify silicone-modified acrylic systems for thermal runaway propagation barriers.
South Korea
Cell manufacturers in Gyeonggi Province are driving qualification of high-dielectric tapes for module-to-module busbar coverage in 800-volt battery packs. MFDS chemical substance notification requirements influence adhesive import documentation for foreign tape suppliers. Busan-Ulsan industrial complexes concentrate module assembly operations that specify thermoplastic repositionable bonding for pack construction.
Automotive Wire Harness Tape Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue battery thermal management specializations where qualification windows remain permeable. The market exhibits consolidated pricing power among adhesive patent holders while fragmenting across regional converters serving aftermarket channels. Three archetypes dominate: multinational diversified materials conglomerates, Asia-Pacific captive resin compounders, and European regulatory pre-certification specialists. Capacity expansion and strategic partnerships represent the dominant competitive vectors as OEMs compress supplier bases for high-voltage platform qualification.
Within the diversified materials tier, 3M Company and Nitto Denko Corporation exemplify patent-protected adhesive chemistry positions that sustain pricing power in OEM qualification programs. Tesa SE occupies a position anchored on European regulatory pre-certification capabilities that reduce customer validation cycles. These three entities represent distinct geographic anchoring strategies—US-based solventless acrylic platforms, Japanese captive resin compounding, and German REACH-aligned formulation expertise—that collectively shape global specification-setting dynamics.
| Leading Market Players |
|---|
| 3M Company |
| Nitto Denko Corporation |
| tesa SE |
| Avery Dennison Corporation |
| Saint-Gobain |
| Intertape Polymer Group |
| Berry Global |
| Scapa Group |
| Henkel AG |
| Others |
Pricing and Supply Chain Analysis
Silicone-modified acrylic adhesive platforms are displacing legacy rubber-based formulations across high-voltage battery applications, simultaneously compressing converter margins through resin feedstock premiums while concentrating specification-setting power among patent-holding chemical conglomerates in Japan and the United States.
Pricing Analysis
Warranty and service-bundling unbundling is fragmenting procurement authority as battery leasing contracts shift material accountability to third-party maintainers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified low-halogen formulations from legacy PVC and unbranded aftermarket alternatives. Price differentiation stems from OEM qualification status and dielectric performance certification for 800-volt architectures. Cost compression in standard-grade PVC tapes is intensifying because REACH phthalate reformulation expenses cannot be fully recovered from price-sensitive aftermarket distributors in Eastern Europe and Mexico.
Supply Chain Analysis
Reverse-logistics flows for end-of-life wire harness recovery remain underdeveloped, though EU Green Deal circular economy mandates are pressuring German OEMs to design mono-material tape constructions that simplify shredding and resin reclamation. Captive resin compounding in Japan, Thailand, and Germany draws from acrylic monomer and synthetic rubber feedstocks anchored in US Gulf Coast petrochemical complexes. Single-source vulnerability concentrates in Japanese adhesive polymer production, where Aichi and Shizuoka prefecture facilities supply Asian module assemblers. Distribution runs through tier-1 harness supplier kitting operations rather than direct OEM delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive wire harness tape sector sits in a technology-transition phase as thermoplastic repositionable adhesives replace pressure-sensitive platforms in battery thermal management applications.
For Market Incumbents: Deepen backward integration into acrylic monomer supply through partnerships with US Gulf Coast petrochemical operators, defending margin position against feedstock volatility that erodes converter profitability. Prioritize silicone-modified acrylic R&D investment to preempt Korean cell manufacturers' qualification windows for thermal runaway barriers.
For New Entrants and Emerging Players: Enter via aftermarket certification for replacement-grade tapes serving Netherlands and United States independent service networks, where battery leasing contracts have fragmented specification authority away from OEM sourcing committees. Target thermoplastic adhesive white space in South Korean module assembly operations requiring post-assembly repositionability during pack construction.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified materials conglomerates seeking REACH-compliant formulation capabilities; strategic buyers prioritize German regulatory pre-certification assets. Long-term viability favors suppliers with captive resin compounding and direct OEM relationships for 800-volt platform qualification. Monitor ECHA substance evaluation timelines for phthalate plasticizer sunset dates as inflection indicators for formulation-switching demand surges.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive feedstock access insulates margins from naphtha price volatility affecting Japanese and Thai compounders. |
| REACH Pre-Certification Investment | Early validation of low-phthalate PVC alternatives secures platform access with Stuttgart-based tier-1 harness suppliers. |
| Thermoplastic Adhesive Capacity Expansion | Repositionable bonding capability opens specification windows with Gyeonggi Province cell manufacturers. |
| Aftermarket Channel Qualification | Parallel certification pathways with Dutch and US independent service networks capture battery leasing maintenance flows. |
| Silicone-Modified Acrylic R&D Partnership | Direct chemistry collaboration with BYD Shenzhen and Tesla Nevada bypasses traditional harness supplier relationships. |
Research Methodology
Multi-period observation of adhesive formulation patent filings, OEM platform qualification timelines, and ECHA substance evaluation dockets anchored the trend analysis, supplemented by interviews with tier-1 harness supplier procurement directors, OEM platform engineers, aftermarket distributors, and adhesive compounder technical directors. Secondary validation drew from MIIT new energy vehicle safety standards, EPA solvent emission disclosures, customs trade data for acrylic resin flows, and SEC filings from diversified materials conglomerates. Bottom-up segment sizing triangulated against top-down OEM production forecasts across the analysis window.
Segment-weighting approaches distributed volume and value projections across product type, application, end user, and technology dimensions, with additional stratification by regional production cluster and voltage architecture tier. CAGRs derived from regression analysis of historical procurement patterns and forward-looking platform content assumptions. Key inputs included 800-volt adoption curves from Korean and Chinese cell manufacturers, REACH reformulation cost estimates from German compounders, and thermal runaway containment specification evolution from SAE committee drafts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EU substance bans or sustained petrochemical price volatility. Practitioners should monitor ECHA sunset date confirmations, MIIT battery safety standard revisions, and tier-1 supplier qualification laboratory backlog reports for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Automotive Wires Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
On Board Connectivity Market