
 Mexico E-Bike Market | 2026-2036
Mexico E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico E-Bike Market Foresight
Lithium-ion cell chemistry is consolidating as the dominant power source across Mexico's e-bike landscape, displacing heavier lead-acid alternatives in both entry-level and premium segments. Giant Manufacturing Co Ltd leverages its established Taiwan-to-Mexico supply corridors to sustain competitive landed costs on lithium-powered city models. Trek Bicycle Corporation anchors its position through specialized dealer networks concentrated in Mexico City, Monterrey, and Guadalajara. Italika competes aggressively on price while controlling one of the largest domestic assembly footprints for electric two-wheelers.
An e-bike combines a traditional bicycle frame with an integrated electric motor, battery pack, and controller system that provides pedal-assist or throttle-based propulsion up to regulated speed thresholds, typically drawing 250-750 watts from rechargeable lithium-ion cells. City and commuting configurations lead unit sales as urban professionals seek alternatives to gridlocked automotive transport, while mountain and fat tire variants capture premium margin pools among recreational buyers in Mexico's northern tourism corridors. Battery type segmentation shows lithium-ion chemistry extending its share lead as nickel-metal hydride fades from new product introductions and lead acid retreats to price-sensitive fleet replacement cycles.
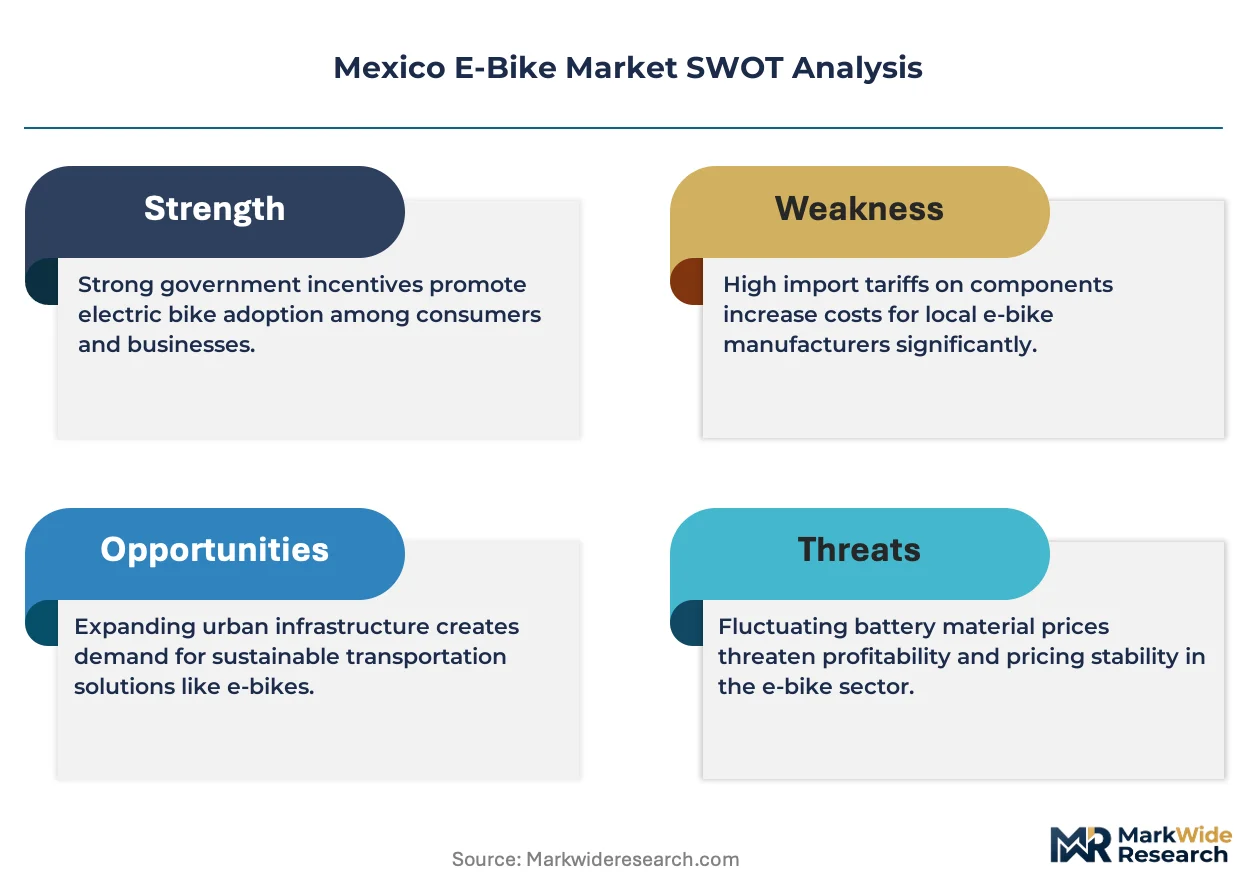
SEMARNAT emissions benchmarks and NOM energy-efficiency standards shape product certification requirements for imported and domestically assembled e-bikes, while Mexico City's Hoy No Circula restrictions on combustion vehicles indirectly stimulate electric two-wheeler demand. State-level mobility programs in Jalisco and Nuevo León are piloting dedicated e-bike lane infrastructure and purchase incentive frameworks. Stakeholders must monitor how federal industrial policy under the PROSEC tariff regime evolves for battery and motor component imports, as this will determine whether domestic assembly economics hold against fully built imports from Asia.
Market Dynamics
SEMARNAT emissions benchmarks and Mexico City's Hoy No Circula restrictions on combustion vehicles are accelerating fleet electrification among last-mile logistics operators, compressing procurement cycles from annual replacement to quarterly expansion.
Growth Catalysts
- Lithium-ion chemistry advances:Energy density improvements extend urban delivery range while reducing battery pack weight, enabling heavier cargo configurations without frame redesign.
- Hoy No Circula enforcement:Mexico City's alternate-day driving restrictions on gasoline vehicles push commercial operators toward electric two-wheeler alternatives exempt from circulation bans.
- Last-mile logistics densification:E-commerce fulfillment networks in Guadalajara and Monterrey are expanding micro-warehouse footprints that favor compact electric cargo bikes over van-based delivery.
Market Restraints
- Import dependency for lithium cells:Domestic assemblers source over 90% of battery cells from East Asian suppliers, exposing landed costs to currency volatility and shipping rate fluctuations.
- PROSEC tariff regime uncertainty:Federal industrial policy revisions for motor and controller component imports threaten the cost advantage of domestic assembly versus fully built Asian imports.
- Lead-acid battery residual demand:Price-sensitive fleet operators in secondary cities continue specifying heavier lead-acid packs, fragmenting supplier R&D focus across incompatible voltage architectures.
Strategic Opportunities
- Jalisco state mobility incentives:State-level purchase subsidies and dedicated lane infrastructure pilots in Guadalajara create a regulatory template for replication across central Mexico.
- Battery swapping networks:Station-based exchange systems address range anxiety among delivery fleets without requiring overnight charging facilities at every depot.
- Tourism corridor rental fleets:Mountain and fat-tire variants are penetrating recreational markets in Baja California Sur and Quintana Roo where conventional bike rentals previously dominated.
Industry Challenges
- NOM certification timelines:Energy-efficiency testing protocols at accredited laboratories create 8-12 week delays between product finalization and commercial availability.
- Technician training gaps:Dealer networks lack standardized curricula for lithium battery diagnostics and motor controller troubleshooting, extending repair turnaround times.
- Spare parts inventory fragmentation:Proprietary connector standards across motor suppliers force distributors to carry redundant component stocks, compressing working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico E-Bike Market |
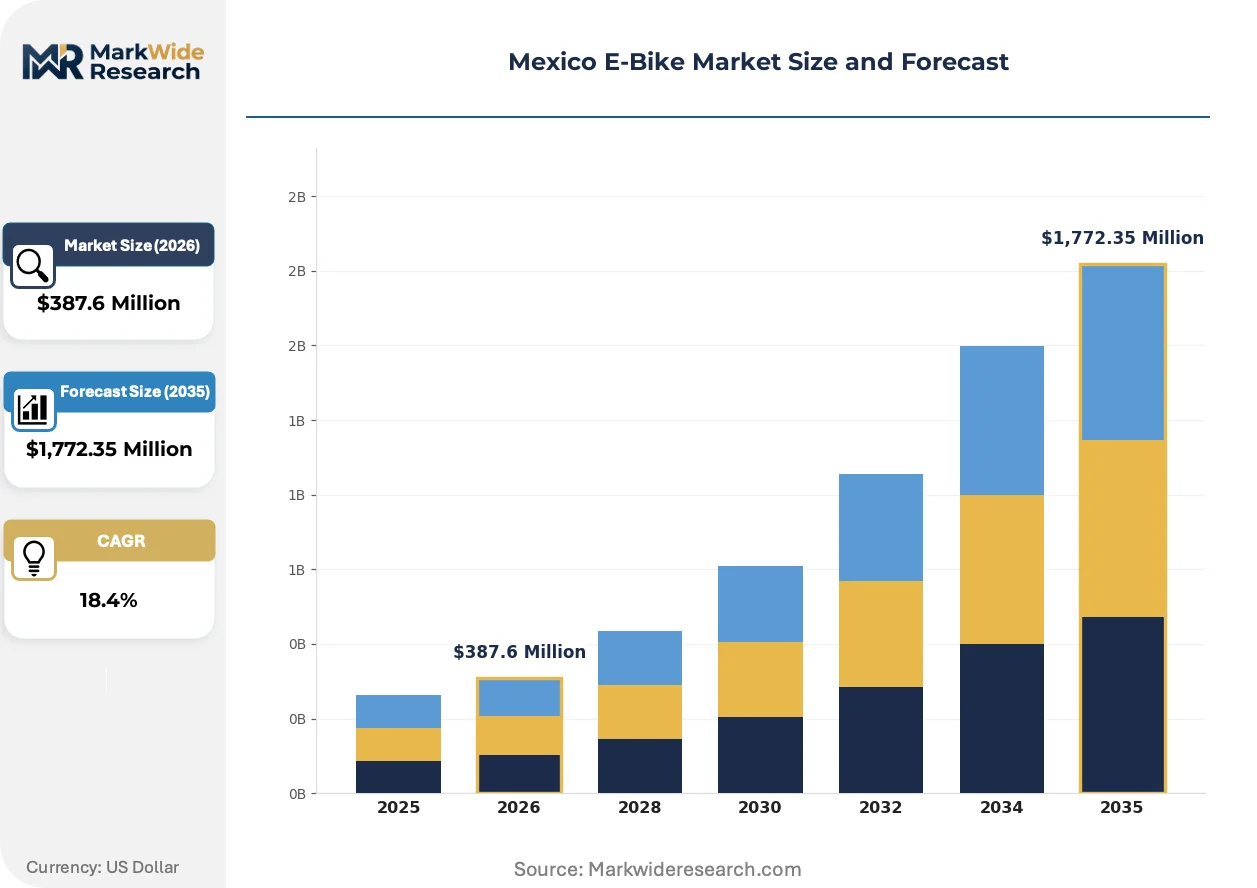
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fat Tire, Folding, Mountain, City Battery Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Lithium Polymer Usage Scenario: Commuting, Recreational, Delivery, Fitness End User: Individuals, Businesses, Tour Operators, Government |
| Companies Covered | Bicicletas Mercurio SA De CV, Distribuidora de Bicicletas Benotto, S.A. de C.V., Specialized Bicycle Components, Trek Bicycle Corporation, Italika, Yamaha Bicycles, Rad Power Bikes, Giant Manufacturing Co Ltd, Citio, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico E-Bike Market Shifts & Advancements
Intelligent power management systems and connected fleet telematics are redefining how commercial operators optimize e-bike utilization rates and battery lifecycle performance.
Mid-drive torque sensor technology is converging with cloud-based route optimization platforms. Food delivery aggregators in Mexico City are deploying these integrated systems to match motor output with real-time traffic gradients. This convergence is compressing the performance gap between premium European drivetrains and cost-optimized Asian alternatives in the commercial segment.
SEMARNAT's updated NOM-163-ENER efficiency standards will mandate minimum energy conversion rates for all imported and domestically assembled units starting next certification cycle. Manufacturers must redesign controller algorithms and motor winding specifications to comply. City and commuting configurations face the steepest redesign burden due to their higher unit volumes and thinner margin structures.
Fleet procurement is consolidating under direct manufacturer relationships, bypassing traditional distributor markups. Large logistics operators in Nuevo León are negotiating volume-based service agreements that bundle hardware, preventive maintenance, and battery replacement schedules. This shift is most visible among grocery and pharmaceutical delivery verticals where vehicle uptime directly correlates with contract renewal rates.
Mexico E-Bike Market Segmentation
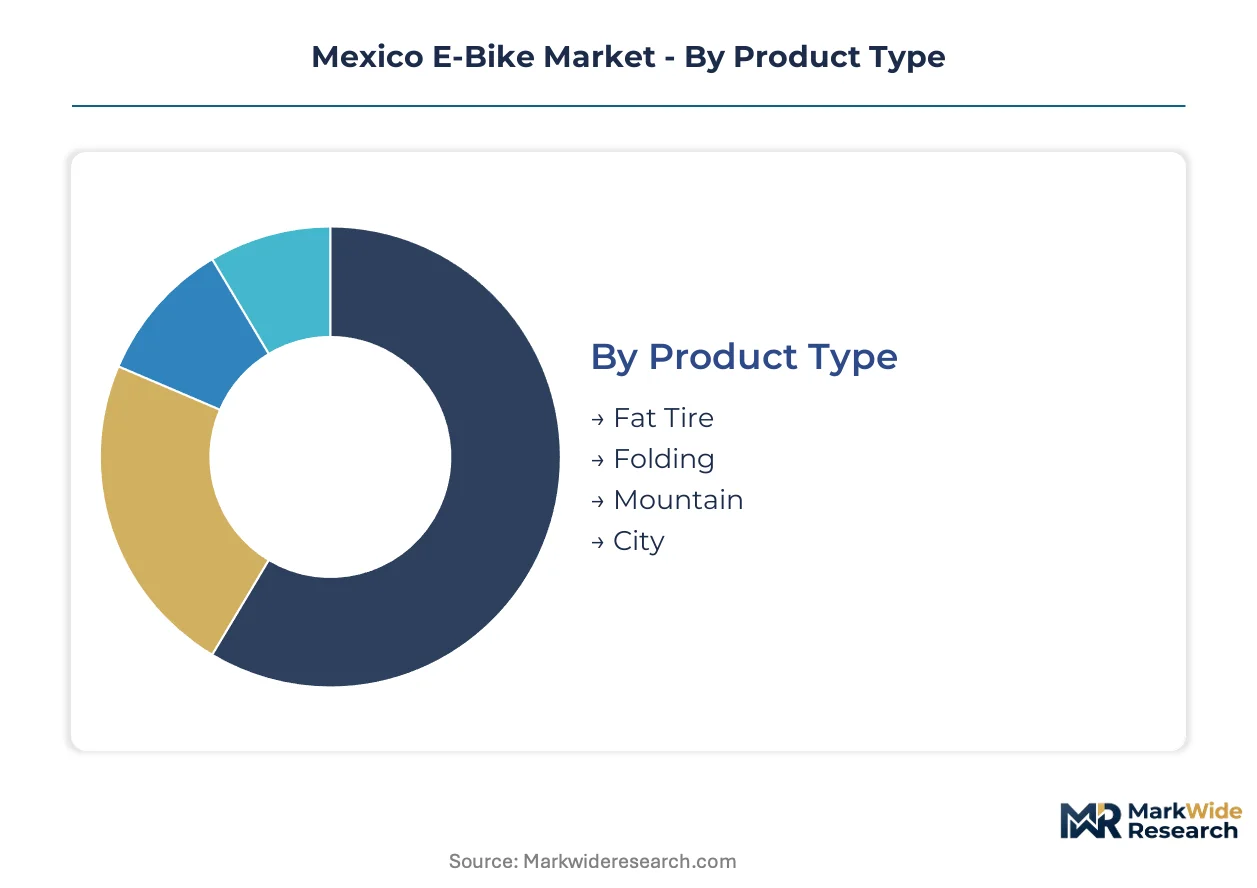
Mexico's e-bike market fragments across four distinct dimensions that shape procurement priorities and margin structures. Product type and battery chemistry determine technical specifications and price positioning, while usage scenario and end user identity drive channel strategy and service requirements.
Product Type:
Frame geometry and tire specification separate urban utility buyers from recreational and commercial purchasers.
- City:Step-through frames and integrated lighting dominate Mexico City and Guadalajara commuter corridors. Fleet operators favor these configurations for their maneuverability in congested centro histórico districts where parking constraints eliminate automotive alternatives.
- Mountain:Full-suspension and hardtail variants with 27.5-inch or 29-inch wheels capture premium pricing in northern tourism corridors. Demand concentrates around Monterrey's Chipinque trails and Guanajuato's mountain tourism circuits where rental operators replace conventional bicycle fleets.
- Fat Tire:Oversized 4-inch width tires enable sand and snow traversal. Beach rental concessions in Quintana Roo and Baja California Sur specify these for coastal terrain where standard tires sink.
- Folding:Hinge-frame designs with 20-inch wheels address multi-modal commuters combining Metrobús or Metro lines with last-mile segments. Mexico City's Hoy No Circula restrictions amplify interest among professionals requiring trunk-stowable backup transport.
City configurations lead volumes today; Mountain variants are gaining share fastest.
Battery Type:
Cell chemistry determines weight, cycle life, and thermal performance across Mexico's varied altitude and temperature zones.
- Lithium-Ion:Cylindrical 18650 and 21700 cell configurations deliver 500-800 watt-hour capacities at 3-4 kilogram pack weights. SEMARNAT NOM-163-ENER certification requirements favor these chemistries for their superior energy conversion efficiency in commercial fleet applications.
- Lithium Polymer:Pouch-cell architectures enable custom form factors that integrate into step-through frame downtubes. Jalisco state mobility pilots specify these for their compact packaging in dedicated lane infrastructure projects.
- Lead Acid:Flooded and AGM variants persist in price-sensitive secondary markets. Puebla and León fleet operators continue specifying these for replacement cycles despite 15-20 kilogram weight penalties.
- Nickel-Metal Hydride:Cylindrical cell formats with moderate energy density occupy shrinking niche positions. Remaining demand concentrates in legacy fleet maintenance where voltage architecture compatibility prevents lithium migration.
Lithium-Ion dominates commercial procurement today; Lithium Polymer is climbing the fastest among new product introductions.
Usage Scenario:
Application context dictates motor power requirements, frame durability specifications, and accessory integration priorities.
- Delivery:Front and rear cargo rack configurations with 750-watt motors and dual battery mounts support 150-kilogram combined loads. Mexico City food aggregators and pharmaceutical distributors specify these for all-weather fleet deployment.
- Commuting:250-350 watt pedal-assist systems with integrated fenders and chain guards serve daily transport needs. Guadalajara's expanding ciclovía network and Monterrey's Ecovía corridor expansion stimulate this segment.
- Recreational:Weekend-use specifications prioritize comfort saddles and upright handlebar positions. Lake Chapala and Valle de Bravo weekend residence communities drive seasonal demand spikes.
- Fitness:Road-bike geometry with minimal assist integration appeals to training-oriented cyclists. Mexico City Bosque de Chapultepec and Paseo de la Reforma morning circuits host concentrated user populations.
Delivery applications lead fleet volumes today; Commuting is expanding most quickly among individual purchasers.
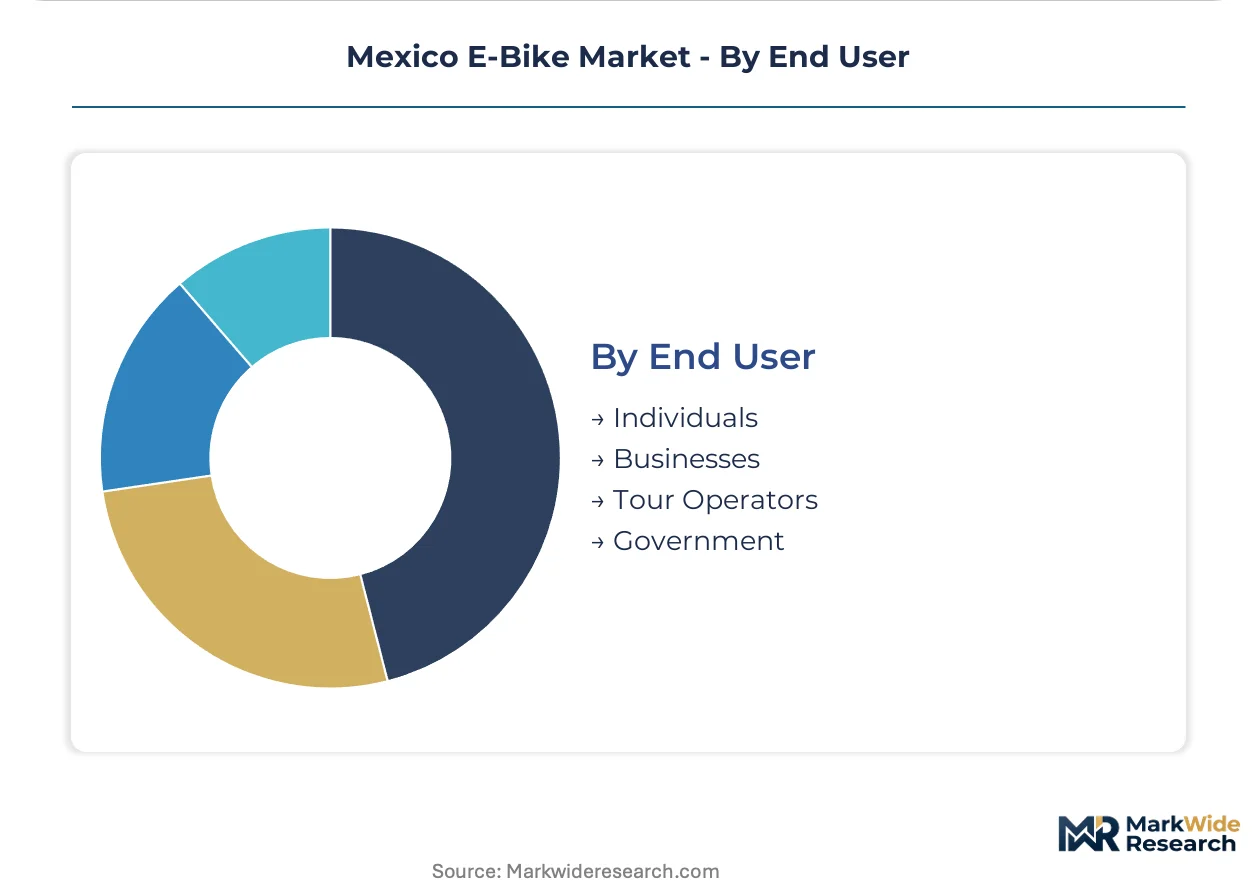
End User:
Procurement scale and decision authority separate fragmented consumer demand from concentrated institutional purchasing.
- Businesses:Logistics operators, food delivery platforms, and courier services negotiate direct manufacturer relationships with volume-based service agreements. Nuevo León grocery chains and pharmaceutical distributors consolidate procurement under centralized fleet management.
- Individuals:Single-unit purchasers through dealer networks or direct-to-consumer channels. Mexico City professionals in Roma, Condesa, and Polanco neighborhoods represent the highest concentration of discretionary spending.
- Tour Operators:Rental fleet procurement with seasonal replacement cycles. Baja California Sur eco-tourism concessions and Quintana Roo hotel chains specify durable frame designs for high-turnover daily rental.
- Government:Municipal procurement for shared mobility programs and enforcement fleet electrification. Jalisco and Nuevo León state mobility departments pilot dedicated lane infrastructure with accompanying vehicle subsidies.
Business procurement leads revenue concentration today; Government purchasing is accelerating most rapidly through state-level mobility programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico City Metro anchors national e-bike demand through congestion pricing enforcement and last-mile logistics densification. State-level mobility programs in Jalisco and Nuevo León are replicating federal incentives with dedicated lane infrastructure.
Mexico City Metro
Delivery fleet electrification accelerates under Hoy No Circula restrictions that exempt electric two-wheelers from alternate-day driving bans. SEMARNAT emissions benchmarks tighten certification requirements for commercial vehicles entering the metropolitan zone. Food aggregators and pharmaceutical distributors concentrate procurement in Cuauhtémoc and Miguel Hidalgo boroughs where parking scarcity eliminates automotive alternatives.
Nuevo León
Monterrey's Ecovía corridor expansion and micro-warehouse proliferation drive cargo bike adoption among grocery chains. State mobility department pilots subsidized purchase programs for last-mile operators. San Pedro Garza García hosts the densest concentration of corporate fleet electrification contracts in northern Mexico.
Jalisco
Guadalajara's ciclovía network expansion and dedicated e-bike lane pilots reduce collision risk for commercial riders. State-level purchase incentives complement federal PROSEC tariff advantages for domestic assemblers. Zapopan and Tlajomulco de Zúñiga warehouse clusters favor compact electric cargo configurations over van-based delivery.
Bajío Region
León and Querétaro automotive supplier networks generate technician labor pools for battery diagnostics and motor controller maintenance. Price-sensitive fleet operators in secondary cities continue specifying lead-acid battery replacements. Puebla's manufacturing base supplies frame components to domestic assemblers serving central Mexico.
Northern Border States
Tijuana and Ciudad Juárez maquiladora corridors absorb cross-border e-bike flows for employee commuter programs. Baja California Sur tourism concessions specify fat-tire variants for beach rental fleets. Mexicali and Hermosillo face limited charging infrastructure penetration, constraining individual purchaser adoption outside commercial fleets.
Mexico E-Bike Market Competitive Landscape
Global majors compete with regional champions across distribution channel strategy and fleet service bundling. The vendor base separates into three tiers: full-line bicycle multinationals with established dealer networks, domestic assemblers exploiting tariff-advantaged component imports, and direct-to-consumer specialists bypassing traditional retail markups. Two archetypes dominate procurement outcomes: scale-driven manufacturers optimizing landed costs through Asia-to-Mexico supply corridors, and service-integrated providers bundling hardware with preventive maintenance contracts. Consolidation pressure is intensifying through volume-based fleet agreements and exclusive distribution territory allocations.
Among Taiwan-based manufacturers, Giant Manufacturing Co Ltd exemplifies the scale-driven archetype with established supply corridor economics. Trek Bicycle Corporation anchors the premium-tier dealer network model through specialized retail presence. Italika occupies the domestic assembly position with tariff-advantaged component sourcing and state-level procurement relationships. These three patterns represent the competitive structure confronting new entrants: cost leadership through supply chain configuration, brand equity through retail investment, or regulatory arbitrage through local assembly.
| Leading Market Players |
|---|
| Bicicletas Mercurio SA De CV |
| Distribuidora de Bicicletas Benotto, S.A. de C.V. |
| Specialized Bicycle Components |
| Trek Bicycle Corporation |
| Italika |
| Yamaha Bicycles |
| Rad Power Bikes |
| Giant Manufacturing Co Ltd |
| Citio |
| Others |
Supply & Pricing Matrix
SEMARNAT NOM-163-ENER certification gates qualified supply and premium-tier pricing access, as uncertified assemblers face exclusion from Mexico City fleet procurement while certified manufacturers command 15-20 point margin premiums. Battery chemistry grade and motor controller efficiency ratings separate compliant from non-compliant supply tiers, concentrating pricing power among importers with established laboratory relationships.
Pricing Analysis
Input-cost pass-through from lithium cell imports dominates pricing dynamics, with East Asian cell pricing volatility transmitting directly to landed pack costs. Three-tier pricing structure across premium, standard, and economy levels reflects NOM certification status, brand equity, and after-sales service bundling. Pricing pressure stems from PROSEC tariff regime uncertainty compressing domestic assembly margins. Fleet operators exhibit highest price sensitivity, while recreational purchasers in Baja California Sur tourism corridors show lowest elasticity.
Supply Chain Analysis
Workforce availability in León and Querétaro automotive supplier networks feeds technician labor pools for battery diagnostics and motor controller maintenance. Cell supply concentrates in China, South Korea, and Japan, with cylindrical 18650 and 21700 formats dominating commercial procurement. Raw material dependencies span lithium carbonate, nickel sulfate, and rare-earth permanent magnets. Single-source vulnerability in controller chipset supply creates bottleneck risk. Distribution runs through specialized dealer networks in Mexico City, Monterrey, and Guadalajara, with direct manufacturer relationships bypassing traditional markups among large fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in lithium-ion chemistry migration and certified fleet service bundling, as battery cost curves and NOM compliance requirements simultaneously squeeze uncertified competitors and elevate premium-tier pricing power.
For Market Incumbents: Extend service-integrated fleet contracts to capture recurring revenue streams and lock out direct-to-consumer specialists. Deepen backward integration into battery pack assembly within PROSEC-advantaged tariff zones to defend cost position against fully built Asian imports. Certify additional SKUs under NOM-163-ENER ahead of regulatory tightening to preempt competitor access. For New Entrants and Emerging Players: Battery swapping station networks offer technology-first wedge into Mexico City delivery fleet infrastructure gaps, bypassing overnight charging facility requirements that constrain incumbent depot-based models. Target Jalisco state mobility incentive programs as the most penetrable geography, where dedicated lane infrastructure pilots reduce collision risk and insurance costs. Pursue direct municipal procurement relationships rather than dealer network buildouts. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic assemblers with underutilized PROSEC tariff capacity and established SEMARNAT laboratory relationships. Long-term viability hinges on lithium chemistry transition completion and fleet service contract renewal rates. Watch NOM-163-ENER certification backlog clearance timelines as inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Network Deployment | Addresses range anxiety among Mexico City delivery fleets without depot charging infrastructure. |
| NOM-163-ENER Certification Investment | Unlocks Mexico City Hoy No Circula-exempt fleet procurement and premium-tier pricing access. |
| PROSEC Tariff Zone Assembly Expansion | Preserves cost advantage against fully built Asian imports under evolving federal industrial policy. |
| Direct Fleet Service Agreement | Bundles hardware, preventive maintenance, and battery replacement to capture recurring revenue. |
| Jalisco State Mobility Partnership | Secures dedicated lane access and purchase incentive eligibility ahead of replication across central Mexico. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with e-bike fleet operators, dealer network principals, battery pack assemblers, and SEMARNAT certification laboratory directors with secondary validation. Trade data from Mexican customs authorities, PROSEC tariff regime filings, NOM-163-ENER certification registries, and state mobility program disclosures anchored supply-side modeling. Bottom-up unit shipment estimates triangulated against top-down battery cell import volumes.
Segment-weighting approach distributed volume and value across product type, battery chemistry, usage scenario, and end user dimensions. CAGRs derived from fitted growth curves calibrated to fleet procurement cycle compression and individual adoption elasticity. Forecast inputs incorporated Hoy No Circula enforcement intensity, ciclovía network expansion timelines, and lithium cell cost trajectory assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PROSEC tariff revisions and federal industrial policy shifts. Projections reflect documented assumptions on battery chemistry migration rates and fleet electrification mandates. Material deviation in NOM certification timelines or state-level incentive program scaling warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market