
 Automotive Wireless Charger Market | 2026-2036
Automotive Wireless Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wireless Charger Market Insights
Qi2 magnetic alignment certification is reorganizing supplier eligibility across the automotive wireless charger value chain. Infineon Technologies leverages its semiconductor portfolio to dominate in-car power management subsystems. Powermat Technologies anchors aftermarket distribution through partnerships with tier-one automotive retailers. Continental sustains R&D intensity in integrated charging surfaces embedded directly into vehicle interiors.
Automotive wireless chargers transfer electrical energy via electromagnetic induction or magnetic resonance to compatible devices without physical connectors, typically operating at frequencies between 87 and 205 kHz with power outputs up to 15 watts for smartphone applications. OEM chargers command premium positioning as vehicle manufacturers bundle wireless charging within luxury and mid-tier trim configurations. Inductive charging occupies the dominant technology position due to proven interoperability with existing smartphone ecosystems. Resonant charging represents the fastest-expanding segment as automakers seek greater spatial freedom in cabin layout design.
The Federal Communications Commission in the United States governs radio frequency emissions from in-vehicle wireless power transmitters, while the European Union's Radio Equipment Directive mandates electromagnetic compatibility and spectrum efficiency standards for automotive aftermarket installations. China's Ministry of Industry and Information Technology coordinates GB standard development for wireless power transfer in electric vehicle applications. Stakeholders must monitor evolving Qi2 certification requirements alongside regional electromagnetic field exposure limits to preserve market access across multiple jurisdictions.
Market Dynamics
Qi2 magnetic alignment certification is restructuring supplier eligibility across the automotive wireless charger value chain, forcing component manufacturers to retool for interoperability compliance while OEMs consolidate procurement around certified vendors.
Growth Catalysts
- EU Radio Equipment Directive:Mandates electromagnetic compatibility standards for automotive aftermarket installations, accelerating supplier consolidation toward compliant manufacturers.
- China EV specification surge:Domestic electric vehicle brands now specify wireless charging in over half of new passenger vehicle trims, creating concentrated demand pull.
- Magnetic resonance advancement:Automakers seek greater spatial freedom in cabin layout design, expanding resonant charging deployment beyond traditional inductive pads.
Market Restraints
- Semiconductor supply concentration:Power management ICs for in-car transmitters depend on concentrated Asian foundry capacity, exposing automakers to allocation risk.
- Copper coil cost volatility:Litz wire and ferrite substrate prices fluctuate with raw material markets, compressing margin at tier-two component suppliers.
- Qi2 certification backlog:Wireless Power Consortium testing queue delays product launches by 4-8 months for non-priority members.
Strategic Opportunities
- India PLI scheme extension:Production-linked incentives for automotive electronics manufacturing attract wireless charger assembly investment away from traditional China sourcing.
- Integrated surface charging:Direct embedding of transmitter coils into dashboard and door panel materials eliminates visible hardware, enabling premium interior differentiation.
- Vehicle-to-device power export:Bidirectional wireless energy transfer turns EV cabins into mobile power hubs for consumer electronics and camping equipment.
Industry Challenges
- RF engineer scarcity:Electromagnetic field simulation expertise for 87-205 kHz transmitter optimization concentrates at semiconductor firms, starving tier-one automotive suppliers.
- Legacy 12V electrical architecture integration:Older vehicle platforms lack the power budget and thermal management for 15-watt charging without substantial wiring harness redesign.
- Cross-standard IP licensing:Magnetic resonance patents held by university consortia and competing standards bodies create royalty stacking for multi-mode chargers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wireless Charger Market |
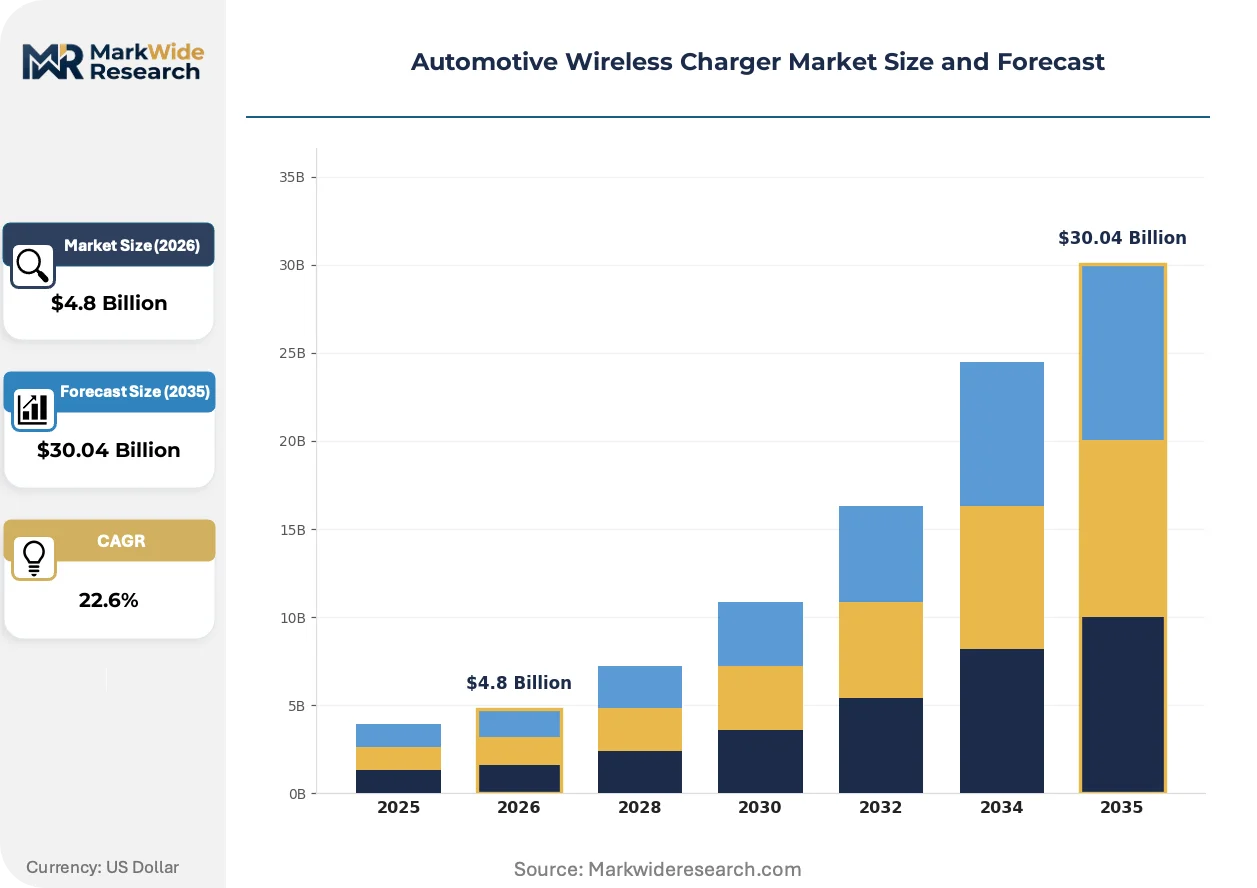
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.04 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aftermarket Chargers, OEM Chargers, Portable Chargers, Integrated Chargers Technology: Inductive Charging, Resonant Charging, Magnetic Charging, Ultrasonic Charging End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Two-Wheelers Installation: In-dash Installation, Center Console Installation, Floor Installation, Wireless Retrofit Kits |
| Companies Covered | Powermat Technologies, Aircharge, Infineon Technologies, Mojo Mobility, Wieson Automotive, Monolithic Power Systems, Zens, Molex, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wireless Charger Market Trends and Innovations
Wireless power transmission architectures are diverging as automakers balance interoperability mandates against proprietary ecosystem lock-in, creating parallel development tracks for open-standard and closed-system implementations.
Multi-coil transmitter arrays is fragmenting the dominant single-pad design paradigm by enabling device positioning flexibility across broader cabin surfaces. Luxury German automakers are adopting this topology for second-row entertainment zones and center console coverage. The technology is fragmenting competitive positioning between integrated interior suppliers and discrete charger module vendors.
FCC Part 18 rules governing radio frequency emissions from in-vehicle wireless power transmitters are tightening enforcement on thermal runaway documentation and electromagnetic field exposure testing. US-based automakers must submit expanded SAR measurement data for each seating position configuration. Aftermarket kit manufacturers face particular compliance burden as retrofit installations multiply potential interference scenarios with existing vehicle electronics.
Fleet procurement managers are bundling wireless charging specification into total cost of ownership calculations for executive vehicle leases, elevating the feature from convenience option to retention tool. Rental car operators in corporate travel corridors now specify Qi2-certified pads as standard equipment across mid-tier and above vehicle classes. This specification elevation is most visible in airport-adjacent fleet hubs where device compatibility complaints directly impact customer satisfaction scores.
Automotive Wireless Charger Market Segmentation
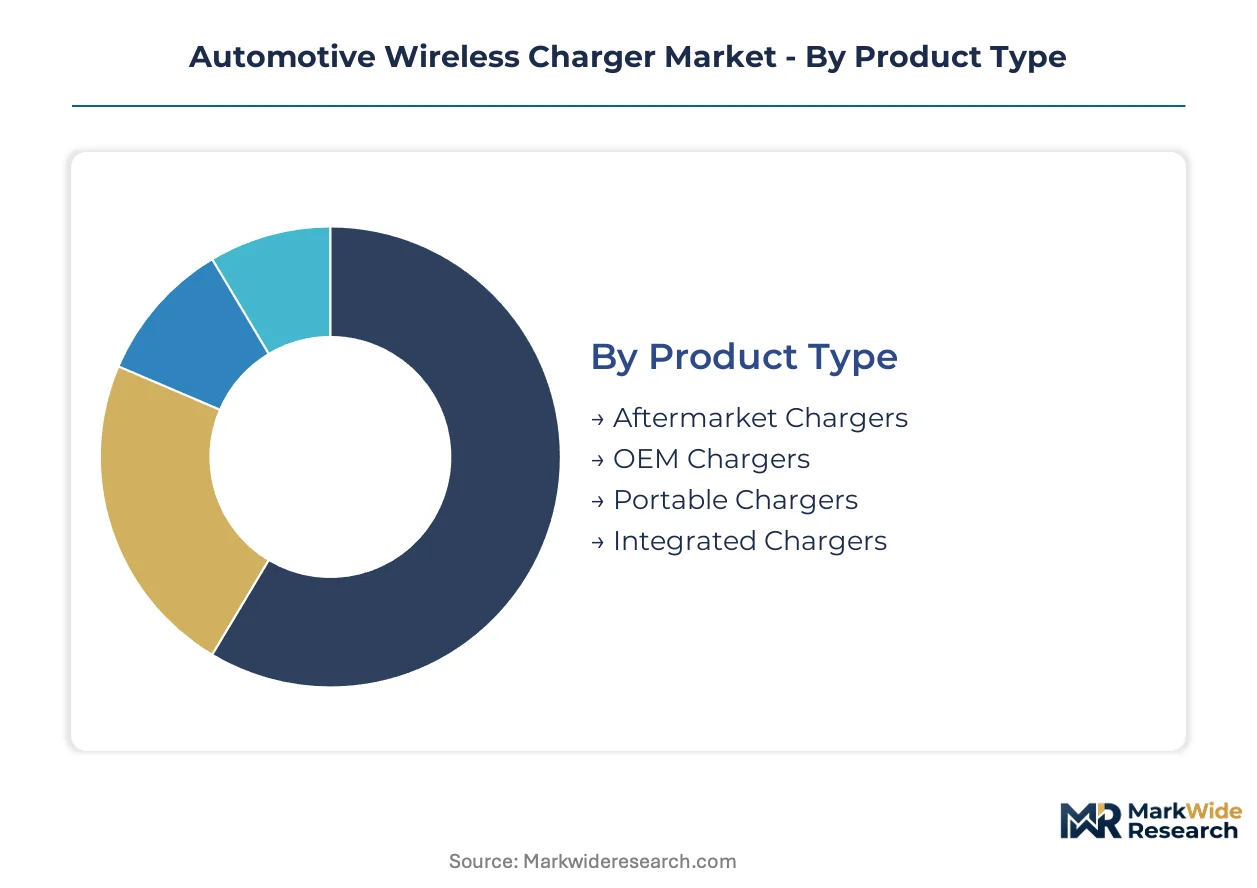
Automotive wireless charger segmentation reveals divergent channel economics between factory-installed systems and aftermarket retrofit solutions. Technology maturity and vehicle electrical architecture constraints create distinct procurement patterns across passenger and commercial applications.
Product Type:
Factory-fit systems flow through tier-one interior suppliers to OEM assembly plants, while aftermarket units distribute through automotive retailers and e-commerce channels with lower certification barriers.
- OEM Chargers:Factory-integrated transmitter modules ship pre-calibrated for specific vehicle platforms with embedded thermal management and CAN bus communication protocols. German luxury manufacturers bundle these as standard equipment across mid-tier and above configurations, with procurement consolidated around Qi2-certified vendors capable of electromagnetic compatibility documentation.
- Aftermarket Chargers:Retrofit transmitter pads install via 12V accessory ports or hardwired connections, targeting vehicle owners seeking to upgrade legacy cabins without factory wireless charging capability. Distribution concentrates through Amazon Automotive, AutoZone, and O'Reilly Auto Parts with price positioning 60-70% below OEM equivalents.
- Integrated Chargers:Coil arrays embedded directly into dashboard substrates and door panel materials eliminate visible hardware entirely. Tier-one interior suppliers like Continental and Faurecia control this segment through exclusive OEM supply agreements.
- Portable Chargers:Battery-powered transmitter units enable wireless charging flexibility across multiple vehicles or rental fleets. Enterprise procurement managers specify these for executive vehicle pools where permanent installation is impractical.
OEM chargers dominate installed base. Aftermarket chargers are where expansion concentrates.
Technology:
Cost tier stratification separates proven inductive architectures from emerging resonance and magnetic alignment standards with higher R&D amortization burdens.
- Inductive Charging:Operating at 87-205 kHz with tightly coupled transmitter-receiver coils, this mature technology delivers 5-15W to smartphones with 70-75% efficiency. The Wireless Power Consortium's Qi specification governs interoperability, with semiconductor firms like Infineon and NXP dominating power management IC supply.
- Resonant Charging:Magnetic resonance architectures operating at 6.78 MHz enable spatial freedom with charging zones extending 15-50 centimeters from transmitter surfaces. BMW and Mercedes-Benz deploy this technology for second-row entertainment tablets where precise device positioning is impractical.
- Magnetic Charging:Qi2's magnetic alignment ring specification combines inductive power transfer with precise device positioning through permanent magnet arrays. Apple's MagSafe ecosystem compatibility drives automaker adoption for iPhone-dominant markets.
- Ultrasonic Charging:Piezoelectric transmitter arrays convert electrical energy to acoustic waves for true spatial freedom without electromagnetic field exposure concerns. University research consortia hold foundational patents, limiting commercial deployment to prototype fleet evaluations.
Inductive charging commands volume leadership. Resonant charging is climbing the fastest as cabin layout flexibility gains priority.
End User:
Application requirements vary sharply between consumer convenience expectations and commercial fleet total-cost-of-ownership calculations.
- Passenger Vehicles:Private automobile owners prioritize smartphone compatibility and charging speed over spatial flexibility, with demand concentrated in premium and luxury segments where feature bundling is standard.
- Electric Vehicles:Chinese domestic brands including BYD and NIO specify wireless charging in over half of new passenger vehicle trims, creating concentrated demand pull for integrated transmitter modules with bidirectional power export capability.
- Commercial Vehicles:Fleet procurement managers at rental operators like Enterprise and Hertz specify Qi2-certified pads as standard equipment across mid-tier vehicle classes, elevating the feature from convenience option to customer retention tool.
- Two-Wheelers:Electric scooter and motorcycle manufacturers deploy compact transmitter modules in under-seat storage compartments, with India's Ola Electric and Ather Energy leading integration for smartphone-dependent navigation applications.
Passenger vehicles anchor volume. Electric vehicles are gaining share fastest as OEM specification rates accelerate.
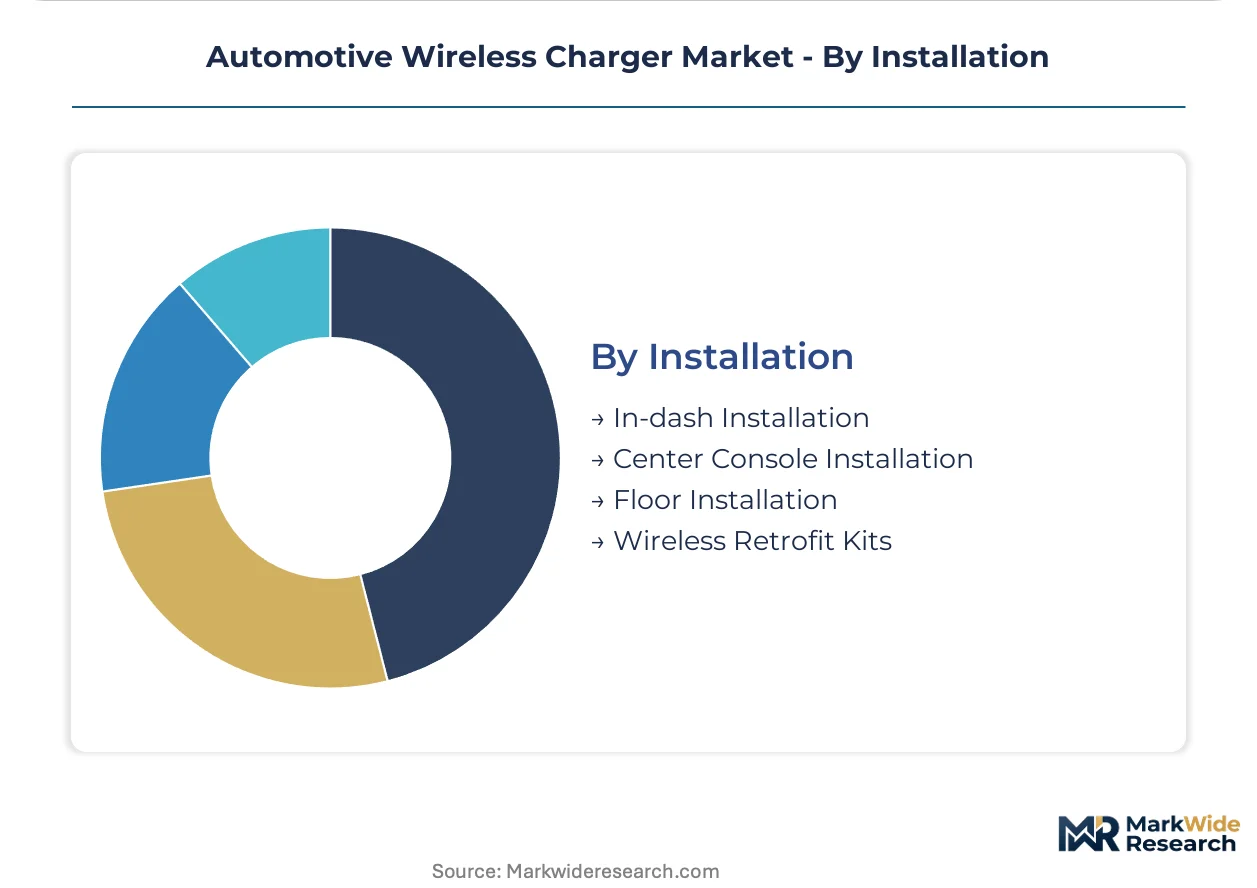
Installation:
Margin structure inverts between factory-integrated architectures with long development cycles and retrofit solutions with immediate revenue recognition.
- Center Console Installation:The dominant factory-fit topology positions transmitter coils beneath padded surfaces with magnetic alignment guides, capturing 70% of OEM-specified systems.
- In-dash Installation:Dashboard-embedded coils behind climate control interfaces target vehicles with limited console real estate, requiring extensive electromagnetic interference testing with infotainment systems.
- Floor Installation:Second-row footwell transmitters serve tablet and laptop charging for executive vehicle configurations, with Mercedes-Benz S-Class and BMW 7-Series deploying this architecture.
- Wireless Retrofit Kits:Self-install transmitter pads with adhesive mounting and 12V power delivery target vehicle owners with expired factory warranties, distributed through automotive retailers with minimal technical support requirements.
Center console installation dominates installed base. Floor installation is where expansion concentrates as rear-seat productivity features proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Radio Equipment Directive accelerates compliance investments across automotive electronics suppliers, while China's MIIT coordinates GB standard development for wireless power transfer in electric vehicle applications. India's PLI scheme extension attracts assembly investment away from traditional sourcing patterns.
United States
Fleet procurement managers at Enterprise and Hertz specify Qi2-certified pads as standard equipment across mid-tier vehicle classes. The FCC governs radio frequency emissions from in-vehicle wireless power transmitters under Part 18 rules. Silicon Valley semiconductor firms concentrate power management IC design for automotive transmitter modules.
Germany
Luxury automakers embed Qi2-certified charging pads into center consoles as standard equipment across mid-tier and above configurations. The KBA enforces electromagnetic compatibility standards for vehicle type approval. Bavaria-based tier-one interior suppliers control integrated charging surface development for dashboard embedding.
China
Domestic EV brands including BYD and NIO specify wireless charging in over half of new passenger vehicle trims. MIIT coordinates GB standard development for wireless power transfer in electric vehicle applications. The Yangtze River Delta concentrates transmitter module manufacturing for integrated automotive supply chains.
Japan
Automakers prioritize magnetic resonance architectures for second-row entertainment zones in executive vehicle configurations. METI oversees electromagnetic field exposure limits for consumer electronics integration. The Kansai region anchors ferrite substrate production for high-efficiency transmitter coils.
India
Electric scooter manufacturers deploy compact transmitter modules in under-seat storage compartments for smartphone-dependent navigation. The PLI scheme for automotive electronics manufacturing attracts wireless charger assembly investment. Tamil Nadu's automotive electronics corridor hosts emerging tier-two component suppliers.
Automotive Wireless Charger Market Competitive Landscape
Player mix skews toward semiconductor specialists and tier-one interior suppliers with established OEM supply relationships. The vendor base concentrates around electromagnetic component fabricators and power management IC designers with automotive qualification credentials. Two strategic archetypes dominate: integrated interior subsystem suppliers and discrete module specialists. Competitive moves center on Qi2 certification acceleration and exclusive OEM supply agreement consolidation.
Within the semiconductor archetype, Infineon Technologies and Monolithic Power Systems represent power management IC supply concentration for in-car transmitters. Continental anchors the integrated interior tier through exclusive OEM agreements for embedded charging surfaces. Powermat Technologies occupies a position in aftermarket distribution partnerships with automotive retailers.
| Leading Market Players |
|---|
| Powermat Technologies |
| Aircharge |
| Infineon Technologies |
| Mojo Mobility |
| Wieson Automotive |
| Monolithic Power Systems |
| Zens |
| Molex |
| Continental |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-week lead times for Qi2-certified power management ICs concentrate pricing power with semiconductor firms holding automotive qualification credentials, while tier-two coil suppliers absorb copper volatility through contract pass-through mechanisms.
Pricing Analysis
Certification level creates the primary spread across the automotive wireless charger market, with Qi2-compliant modules commanding substantial premiums over legacy Qi 1.2.3 equivalents. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates OEM-specified systems from aftermarket retrofit kits. Cost compression in aftermarket channels is intensifying because Amazon Automotive and AutoZone consolidate procurement around lowest-landed-cost Asian suppliers. Fleet procurement managers at Enterprise and Hertz demonstrate lowest price sensitivity, prioritizing Qi2 compatibility and warranty terms over unit economics.
Supply Chain Analysis
Strategic stockpiling of ferrite substrates and Litz wire dominates inventory strategy among tier-one interior suppliers, insulating against copper price volatility and foundry allocation shocks. Manufacturing concentrates in China, Germany, and Taiwan, with the Yangtze River Delta anchoring transmitter module assembly and Bavaria housing integrated surface development. Supply chains draw from concentrated Asian foundry capacity for power management ICs, Japanese ferrite production, and German automotive-grade substrate fabrication. Single-source vulnerability in 12-inch wafer supply at TSMC and Samsung Foundry exposes automakers to allocation risk during semiconductor cycles. Distribution runs through tier-one interior suppliers to OEM assembly plants for factory-fit systems, while aftermarket channels bypass traditional automotive tiers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive wireless charging incumbents face substitution pressure from USB-C Power Delivery 240W and vehicle-native device docking systems that bypass transmitter coils entirely.
For Market Incumbents: Compound defensive positioning through backward integration into ferrite substrate production and exclusive Qi2 certification fast-track arrangements with the Wireless Power Consortium. Lock in multi-year supply agreements with Infineon and NXP before foundry allocation tightens. Prioritize R&D spend on bidirectional power export architectures that USB-C cannot replicate. For New Entrants and Emerging Players: Qi2 certification fast-track through WPC priority membership unlocks white-space penetration in India's electric two-wheeler segment and North American commercial fleet retrofit markets. Target underpenetrated floor-installation configurations for second-row productivity in executive vehicle classes. Pursue direct OEM supply relationships bypassing tier-one interior supplier consolidation through specialized magnetic resonance expertise. For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor-heavy component play because power management IC content per vehicle scales with multi-coil transmitter arrays and bidirectional architectures. Acquisition targets should display automotive AEC-Q100 qualification credentials and existing OEM supply relationships rather than consumer electronics heritage. Monitor Wireless Power Consortium priority membership queue depth as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Qi2 Certification Acceleration | WPC priority membership compresses testing queue from 8 months to 90 days for automotive suppliers. |
| Backward Integration into Ferrite | Captive ferrite substrate production insulates margin from rare earth price volatility and Chinese export quotas. |
| Bidirectional Power Export Development | Vehicle-to-device architectures differentiate against USB-C substitution in camping and emergency power applications. |
| Multi-Coil Transmitter Arrays | Second-row entertainment zone coverage captures fleet specification upgrades at Enterprise and Hertz. |
| India PLI Manufacturing Footprint | Tamil Nadu assembly operations reduce tariff exposure and access Ola Electric and Ather Energy supply chains. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution category managers, and dealership operations heads. Secondary validation incorporated vehicle production databases, IHS Markit registration data, Wireless Power Consortium certification records, and FCC Part 18 filing documentation. Bottom-up transmitter module shipment tallies triangulated against top-down automotive electronics content forecasts.
Across the analysis window, projections model vehicle class stratification, propulsion architecture differentiation, content per vehicle trajectories, OEM tier positioning, and regional production cluster dynamics. CAGRs derive from segment-level shipment forecasts weighted by average selling price evolution. Industry-specific inputs include Qi2 certification adoption curves, copper coil commodity price bands, and foundry capacity utilization assumptions.
Underlying assumptions cover sustained semiconductor allocation stability and EU Radio Equipment Directive compliance continuity, with deviation risk concentrated in raw material price spikes and regulatory timeline slippage. Revision becomes warranted when WPC certification queue depth exceeds six months or when USB-C Power Delivery penetration in vehicle cabins crosses threshold adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
UK Automotive Camera Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Construction Machinery Wiring Harness Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market