
 In-Vehicle Ethernet System Market | 2026-2036
In-Vehicle Ethernet System Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vehicle Ethernet System Market Foresight
Semiconductor foundry capacity in Taiwan is realigning toward automotive-grade Ethernet PHYs and switches as vehicle data throughput requirements multiply. Broadcom Inc. leverages its SerDes portfolio to dominate high-speed automotive connectivity designs. NXP Semiconductors anchors its position through integrated switch families purpose-built for zonal E/E architectures. Infineon Technologies AG differentiates via AEC-Q100-qualified transceivers that sustain qualification cycles across multiple OEM platforms.
An in-vehicle Ethernet system comprises a network of physical layer transceivers, switches, and shielded twisted-pair cabling operating at data rates from 100 Mbps to 10 Gbps, designed to transport audio, video, sensor, and control data across automotive domains with deterministic latency. Wired Ethernet components occupy the dominant value share as backbone infrastructure for ADAS and infotainment domains, while Gigabit Ethernet implementations represent the fastest-expanding technology tier as camera and lidar data loads intensify. OEMs constitute the primary demand channel, though Tier-1 Suppliers capture expanding margin pools by integrating switch hardware with embedded software stacks.
The IEEE 802.3 standards body, NHTSA, and the EU's UNECE WP.29 framework collectively shape product specifications through bandwidth mandates, cybersecurity management requirements, and type-approval protocols for connected vehicle systems. NHTSA's anticipated software and data integrity rules will compel Ethernet suppliers to embed hardware security modules alongside physical layer devices. Stakeholders must monitor how zonal architecture transitions redistribute switch placement decisions between OEMs and their Tier-1 partners.
Market Dynamics
Zonal E/E architecture migration is compressing legacy domain controller hierarchies into regional compute clusters, forcing Ethernet switch placement decisions upstream into Tier-1 supplier negotiations and away from traditional module-level sourcing.
Growth Catalysts
- IEEE 802.3ch Standardization:Multi-gigabit automotive Ethernet specifications unlock 2.5G/5G/10G PHY development for camera and lidar backbone networks. PHY vendors accelerate tape-outs to capture zonal platform sockets.
- Germany Premium OEM Integration:Bavarian and Stuttgart-based automakers embed Ethernet as primary ADAS data plane across next-generation vehicle platforms. Their specification power cascades through global supplier networks.
- UNECE WP.29 Cybersecurity Mandates:Type-approval requirements for connected vehicle systems compel hardware security module integration alongside physical layer devices. Suppliers redesign transceiver architectures to embed cryptographic acceleration.
Market Restraints
- Automotive-Grade Silicon Foundry Concentration:Taiwan-based 28nm and 16nm capacity allocation favors consumer and datacenter demand cycles. Automotive Ethernet PHY tape-outs face queue delays during foundry allocation shocks.
- Shielded Twisted-Pair Copper Cost Structure:High-purity copper and fluoropolymer jacketing materials experience commodity volatility. Cable harness suppliers struggle to pass through raw material escalations under fixed OEM supply agreements.
- Legacy MOST and CAN-FD Substitution Resistance:Established infotainment and body domain networks resist Ethernet migration where bandwidth requirements remain below 100 Mbps. OEMs defer switching costs for mid-cycle platform refreshes.
Strategic Opportunities
- Software-Defined Vehicle Service Layer:Over-the-air update architectures create recurring revenue pools for Ethernet switch vendors bundling embedded software stacks. Subscription-enabled feature activation requires persistent high-bandwidth connectivity.
- India Passenger Vehicle Electrification:Domestic OEMs and joint ventures adopt zonal architectures for cost-optimized EV platforms skipping legacy domain controller generations. Local Tier-1 suppliers build Ethernet competency ahead of volume ramp.
- EU Battery Electric Vehicle Type-Approval:UNECE regulations for EV data logging and remote diagnostics mandate standardized high-speed diagnostic interfaces. Ethernet replaces CAN-based diagnostic links in BEV architectures.
Industry Challenges
- AEC-Q100 Qualification Timeline Compression:Grade 0 and Grade 1 temperature qualification cycles span 12-18 months for multi-gigabit PHYs. OEM platform deadlines force parallel validation risking field failure exposure.
- SerDes IP Licensing Complexity:Proprietary encoding schemes from dominant suppliers fragment interoperability testing. Second-source PHY development requires costly reverse engineering or royalty stacking.
- Zonal Architecture Integration Friction:Legacy powertrain and chassis domain controllers resist native Ethernet connectivity. Gateway hardware proliferation adds cost and latency until full domain consolidation matures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vehicle Ethernet System Market |
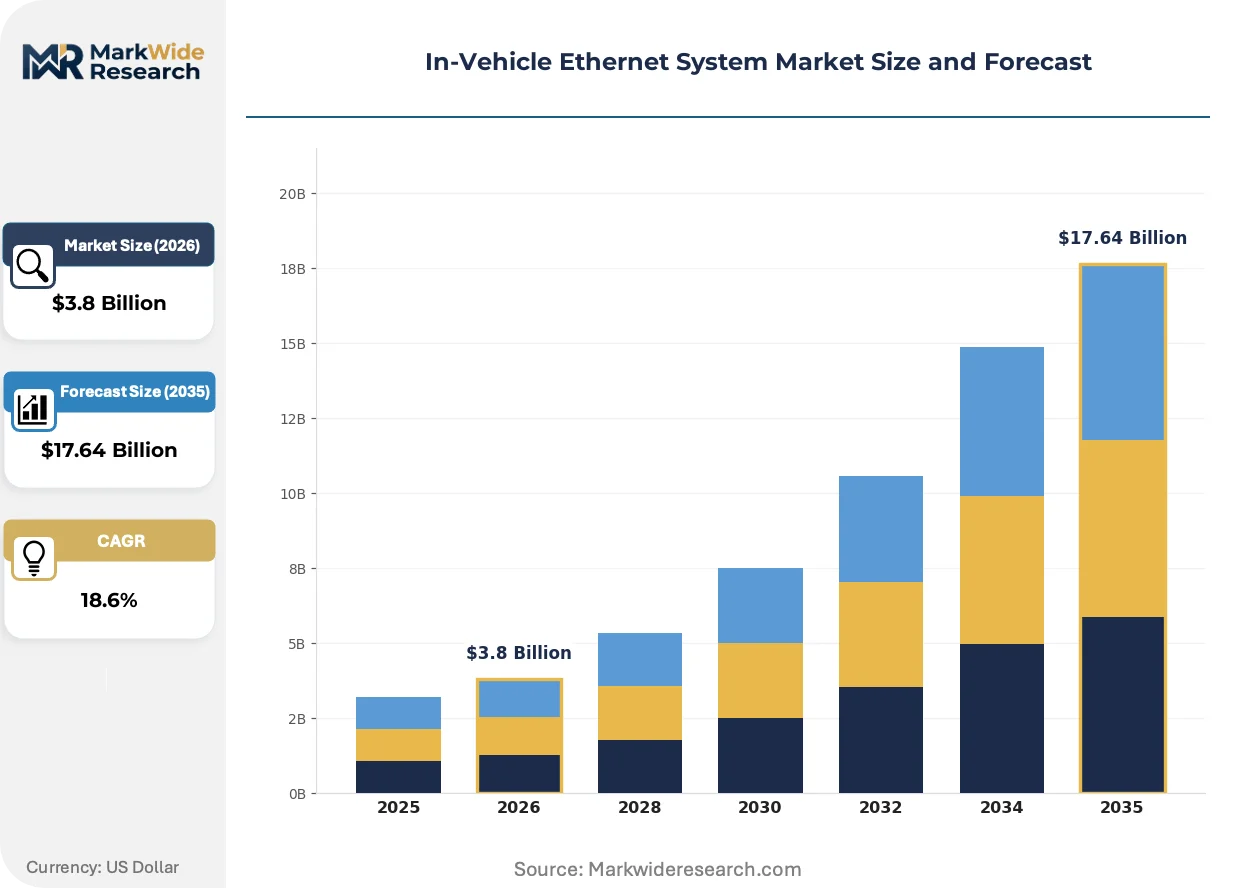
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Ethernet, Wireless Ethernet, Switches, Cables End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Fast Ethernet, Gigabit Ethernet, PoE, AVB Application: Infotainment, Advanced Driver Assistance Systems, Vehicle Diagnostics, Connectivity Solutions |
| Companies Covered | Broadcom Inc., NXP Semiconductors, Microchip Technology Inc., Marvell Technology, Texas Instruments Incorporated, Cadence Design Systems Inc., Infineon Technologies AG, TE Connectivity, Elektrobit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vehicle Ethernet System Market Shifts & Advancements
Deterministic time-sensitive networking is displacing best-effort Ethernet transport for safety-critical vehicle functions, while semiconductor packaging innovations compress switch form factors for engine compartment mounting.
Time-sensitive networking with IEEE 802.1Qbv time-aware shaping is decentralizing real-time control traffic scheduling away from centralized gateway arbitration. ADAS domain controllers adopt TSN-enabled switches to guarantee sensor fusion latency bounds. This architecture is decentralizing deterministic networking hardware placement into zonal compute nodes.
NHTSA's anticipated software and data integrity rules will mandate hardware-backed secure boot and runtime attestation for connected vehicle systems. Ethernet PHY suppliers must integrate hardware security modules alongside SerDes cores. The regulation most affects Tier-1 module suppliers redesigning infotainment and telematics gateways for 2026 platform introductions.
Automotive OEMs are consolidating switch procurement decisions at the platform architecture level rather than delegating to individual domain module specifications. Tier-1 suppliers compete on embedded software integration depth rather than hardware bill-of-materials differentiation. This concentration is most visible in German premium OEM sourcing strategies for 2025-2028 vehicle platforms.
In-Vehicle Ethernet System Market Segmentation
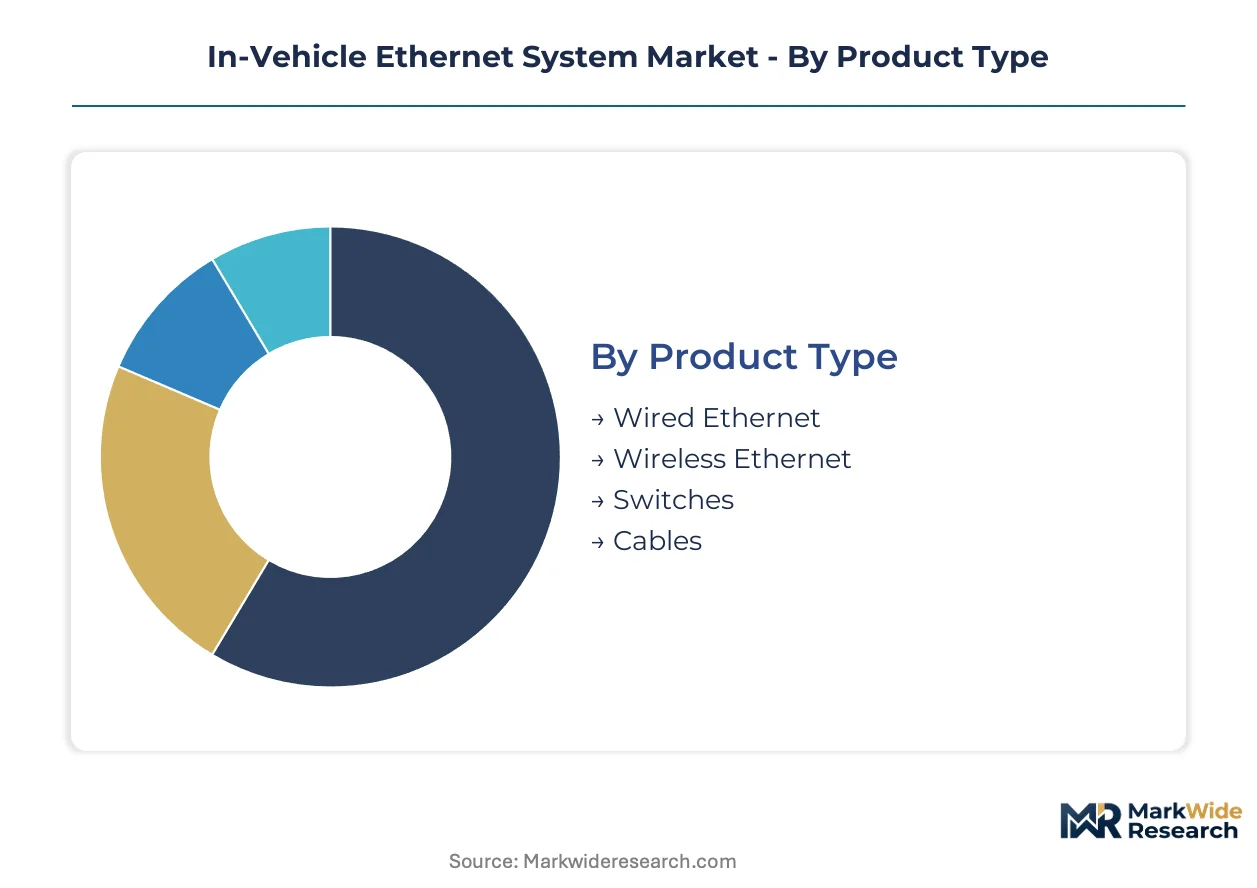
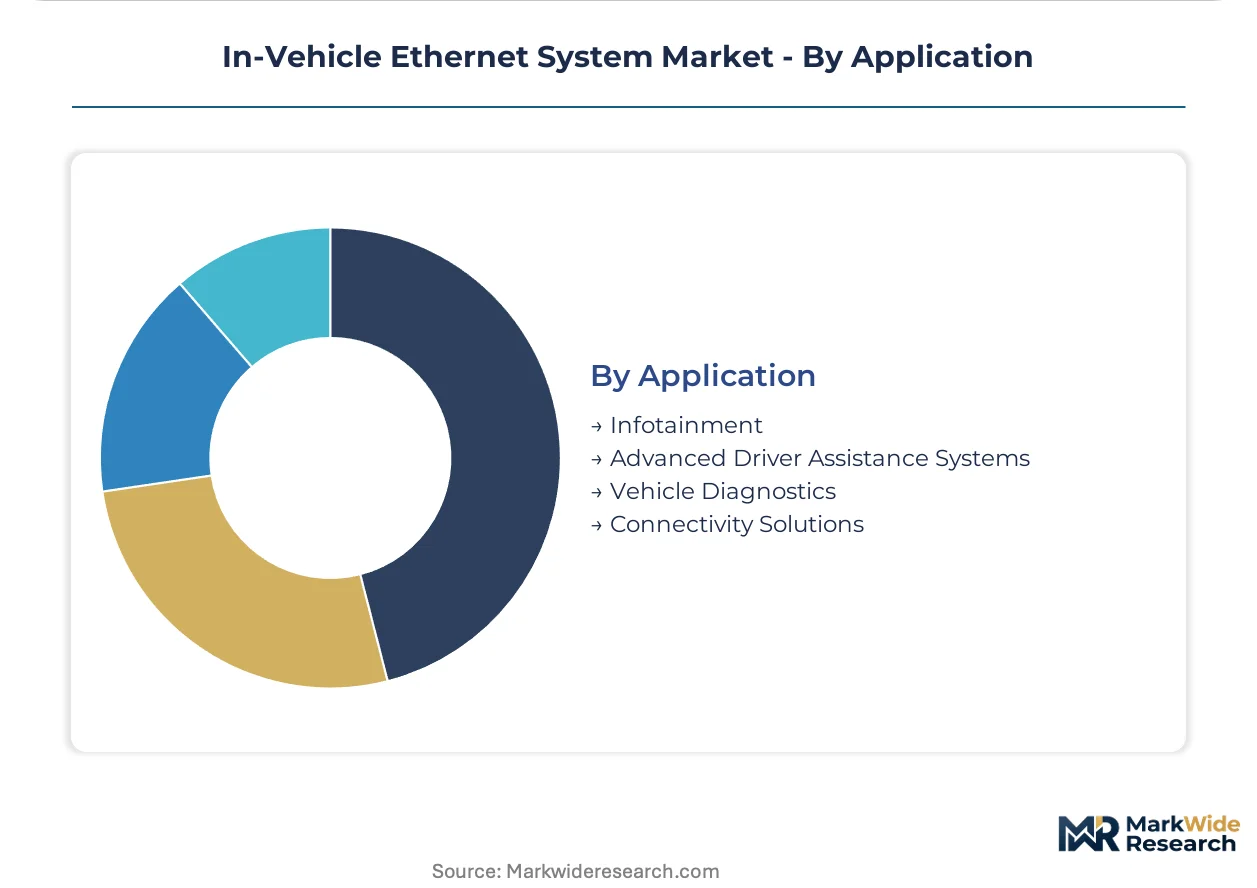
In-vehicle Ethernet system segmentation reveals how certification burdens, bandwidth requirements, and integration complexity redistribute value across hardware tiers. OEM sourcing strategies now favor segments that consolidate multiple AEC-Q100 qualifications into single platform sockets.
Product Type:
Wired Ethernet components carry AEC-Q100 Grade 0 thermal cycling burdens for engine-bay mounting, while wireless modules face FCC and ETSI RF emission certifications alongside automotive safety integrity levels.
- Wired Ethernet:Physical layer transceivers and PHYs operating at 100 Mbps to 10 Gbps over shielded twisted-pair copper. Bavarian premium OEMs specify these for backbone ADAS networks where deterministic latency is non-negotiable.
- Switches:Multi-port switching fabrics purpose-built for zonal E/E architectures with integrated TSN capabilities. Tier-1 suppliers in Stuttgart source these at platform level rather than module level to reduce qualification duplication.
- Wireless Ethernet:Wi-Fi 6 and 6E modules for cabin hotspot and device tethering functions. The modules must satisfy both automotive temperature grades and consumer electronics RF protocols.
- Cables:Shielded twisted-pair harnesses with fluoropolymer jacketing for 10 Gbps signal integrity. Copper commodity volatility constrains margin expansion for harness suppliers under fixed OEM agreements.
Wired Ethernet sits at the top of the volume ranking, with switches climbing the fastest as zonal architectures proliferate.
End User:
Procurement authority is shifting from module-level specifications toward platform architecture decisions, altering which end-user segments capture margin pools.
- OEMs:Vehicle manufacturers defining Ethernet topology at platform conception. German premium OEMs embed Ethernet specifications into global supplier mandates that cascade through Tier-1 networks.
- Tier-1 Suppliers:Integrated module houses combining switch hardware with embedded software stacks. These suppliers now compete on software integration depth rather than hardware bill-of-materials differentiation.
- Vehicle Assemblers:Contract manufacturing partners executing harness routing and gateway installation per OEM blueprints. Their procurement influence remains limited to execution efficiency.
- Aftermarket Providers:Retrofit specialists offering diagnostic interface upgrades and infotainment retrofit kits. Regulatory fragmentation across UNECE, NHTSA, and KBA type-approval regimes constrains scale.
OEMs retain the largest procurement volume, though Tier-1 Suppliers are expanding their share fastest through software bundling.
Technology:
Data rate tiers stratify by camera and lidar payload requirements, with higher-speed technologies demanding proportionally more rigorous EMI shielding validation.
- Gigabit Ethernet:1000BASE-T1 and multi-gigabit variants per IEEE 802.3ch for camera backbone networks. PHY vendors accelerate tape-outs to capture zonal platform sockets in next-generation vehicle programs.
- Fast Ethernet:100BASE-T1 for control domain and diagnostic links where bandwidth requirements remain modest. Legacy platform refreshes defer migration to higher speeds where substitution economics resist.
- PoE:Power-over-Ethernet delivering 15-90W over data pairs for distributed sensors and actuators. Thermal management requirements complicate Grade 0 qualification for engine-company mounting.
- AVB:Audio Video Bridging protocols for synchronized infotainment transport. MOST network replacement drives adoption in premium cabin entertainment architectures.
Fast Ethernet maintains volume leadership from legacy platform persistence, while Gigabit Ethernet shows the steepest expansion trajectory from ADAS data load intensification.
Application:
Safety-critical domains impose ISO 26262 functional safety burdens that infotainment applications escape, creating divergent qualification economics across segments.
- Advanced Driver Assistance Systems:Sensor fusion networks demanding deterministic latency below 10 milliseconds. TSN-enabled switches guarantee latency bounds for lidar and camera data aggregation.
- Infotainment:High-resolution display and audio transport with best-effort quality of service. Stuttgart-based OEMs specify Ethernet as primary data plane for next-generation cabin experiences.
- Vehicle Diagnostics:Standardized high-speed interfaces replacing CAN-based links for EV data logging. UNECE WP.29 regulations for BEV type-approval mandate standardized diagnostic access.
- Connectivity Solutions:Telematics and V2X gateway functions for over-the-air update architectures. Hardware security module integration accompanies NHTSA software integrity rule anticipation.
Infotainment commands current volume leadership, with Advanced Driver Assistance Systems gaining share fastest from zonal architecture migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specification authority through Bavarian and Stuttgart-based OEMs, while the United States drives volume through Detroit's electrification programs and Silicon Valley's chip design ecosystem.
United States
Detroit's Big Three and Tesla anchor zonal architecture adoption for electric pickup and SUV platforms. NHTSA's anticipated software integrity rules compel hardware security module integration alongside Ethernet PHYs. Michigan's automotive corridor concentrates Tier-1 module houses redesigning gateway architectures for 2026 platform introductions.
Germany
Bavarian premium OEMs embed multi-gigabit Ethernet as primary ADAS data plane across next-generation vehicle platforms. UNECE WP.29 cybersecurity mandates cascade through global supplier networks originating from Stuttgart specification centers. Baden-Württemberg's Tier-1 cluster sources switches at platform level rather than module level to reduce qualification duplication.
China
Domestic OEMs and joint ventures adopt zonal architectures for cost-optimized EV platforms skipping legacy domain controller generations. MIIT's GB standards for connected vehicle data security shape local Ethernet component specifications. Shanghai's Yangtze River Delta semiconductor foundries realign capacity toward automotive-grade PHY tape-outs.
Japan
Toyota and Honda integrate TSN-enabled switches for deterministic sensor fusion latency bounds. METI's carbon neutrality roadmap accelerates Ethernet adoption in battery electric vehicle architectures. Nagoya's Chubu industrial corridor concentrates harness suppliers developing fluoropolymer-jacketed cable for 10 Gbps signal integrity.
South Korea
Hyundai-Kia embed Ethernet backbone networks for Level 3 autonomous driving platforms. MFDS automotive cybersecurity guidelines align with UNECE WP.29 frameworks for type-approval compliance. Seoul Capital Area fabless semiconductor houses accelerate multi-gigabit PHY development for zonal compute sockets.
In-Vehicle Ethernet System Market Competitive Landscape
United States producers anchor one tier; German and Dutch specialists hold specification influence through OEM proximity. The vendor base stratifies across three tiers: diversified semiconductor conglomerates with SerDes IP portfolios, automotive-focused integrated device manufacturers with AEC-Q100 qualification depth, and connectivity specialists with harness integration capabilities. Consolidation pressure intensifies as OEMs reduce qualified supplier lists for platform-level switch procurement. Competitive moves center on strategic partnerships for embedded software stacks and backward integration into automotive-grade foundry capacity.
Within the diversified semiconductor tier, Broadcom Inc. and Marvell Technology exemplify players leveraging high-speed connectivity IP for automotive Ethernet PHY development. NXP Semiconductors represents the automotive-integrated specialist archetype with switch families purpose-built for zonal E/E architectures. Infineon Technologies AG anchors the European supplier position through AEC-Q100-qualified transceiver portfolios sustaining qualification cycles across multiple OEM platforms.
| Leading Market Players |
|---|
| Broadcom Inc. |
| NXP Semiconductors |
| Microchip Technology Inc. |
| Marvell Technology |
| Texas Instruments Incorporated |
| Cadence Design Systems Inc. |
| Infineon Technologies AG |
| TE Connectivity |
| Elektrobit |
| Others |
Supply & Pricing Matrix
AEC-Q100 Grade 0 and Grade 1 certification divergence separates premium automotive Ethernet PHYs from commodity-grade alternatives, embedding qualification timeline costs into supplier pricing power while concentrating foundry allocation negotiations with Taiwan-based semiconductor fabricators. This bifurcation manifests in procurement contracts where Bavarian OEMs absorb 12-18 month qualification premiums for engine-bay mounting resilience, while mid-tier suppliers compete on volume scale for cabin-grade switch sockets.
Pricing Analysis
Direct-to-OEM channel margins compress Tier-1 supplier profitability as German premium automakers consolidate switch procurement at platform architecture level. Pricing stratifies across AEC-Q100 thermal grade tiers, with Grade 0 PHYs commanding substantial premiums for under-hood deployment against Grade 2 cabin alternatives. Cost compression in copper-intensive shielded twisted-pair harnesses intensifies as fluoropolymer jacketing materials face commodity volatility. Aftermarket diagnostic interface providers exhibit highest price sensitivity due to regulatory fragmentation constraining scale economies.
Supply Chain Analysis
AEC-Q100 qualification gating restricts qualified foundry capacity to Taiwan, South Korea, and select United States facilities with automotive-grade process nodes. Multi-gigabit PHY tape-outs draw from 28nm and 16nm capacity pools shared with consumer and datacenter demand cycles. Single-source vulnerability concentrates in SerDes IP licensing where proprietary encoding schemes fragment interoperability. Distribution runs through Tier-1 module houses bundling switch hardware with embedded software stacks for zonal architecture integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The In-Vehicle Ethernet System Market functions as a stable compounder where zonal E/E architecture migration across electric vehicle platforms sustains embedded demand for multi-gigabit connectivity infrastructure.
For Market Incumbents: To counter foundry allocation queue delays threatening OEM platform deadlines, incumbents should secure captive 28nm automotive-grade capacity through foundry partnership structures. Backward integration into AEC-Q100 test and qualification facilities reduces parallel validation risks for multi-gigabit PHY tape-outs.
For New Entrants and Emerging Players: Begin with India passenger vehicle electrification programs where domestic OEMs adopt zonal architectures without legacy domain controller baggage. Local Tier-1 supplier partnerships offer the most penetrable channel for Ethernet switch qualification, leveraging software-defined vehicle service layer bundling as primary go-to-market positioning.
For Investors and Strategic Acquirers: Consolidation pressure builds where OEMs reduce qualified supplier lists for platform-level switch procurement. Five-to-ten year viability favors automotive-focused integrated device manufacturers with AEC-Q100 depth across multiple OEM platforms. Target acquisition archetypes include fabless PHY specialists with IEEE 802.3ch-compliant multi-gigabit portfolios. Watch for inflection where UNECE WP.29 cybersecurity mandates trigger hardware security module integration requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform-Level Switch Procurement Consolidation | German premium OEMs cascade specifications through global Tier-1 networks. |
| Multi-Gigabit PHY Tape-Out Acceleration | IEEE 802.3ch compliance unlocks 2.5G/5G/10G socket capture in zonal programs. |
| Hardware Security Module Integration | NHTSA software integrity rules compel cryptographic acceleration embedding. |
| TSN-Enabled Switch Development | Deterministic latency guarantees capture ADAS domain controller placements. |
| India EV Platform Partnership | Domestic OEMs skip legacy architectures for cost-optimized zonal adoption. |
Research Methodology
Bottom-up zonal architecture adoption modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, automotive semiconductor R&D directors, and Ethernet standards committee participants combined with secondary validation from IEEE 802.3 standards documentation, vehicle production databases, IHS Markit registration data, and SEC semiconductor filings. Triangulation across supply-side capacity announcements and demand-side platform roadmaps calibrated volume projections.
Input-output matrices map PHY and switch unit economics against vehicle class, propulsion architecture, and regional production cluster penetration rates. Segmentation dimensions span product type, end user procurement authority, data rate technology tier, and application domain safety criticality. CAGRs derive from fitted adoption curves across the projection horizon, incorporating content-per-vehicle trajectories for camera and lidar backbone networks alongside software-defined vehicle connectivity intensity assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan foundry operations, copper commodity supercycle dynamics, and legacy MOST network substitution resistance beyond mid-cycle platform refreshes. Deviation in IEEE 802.3ch standardization timing or UNECE WP.29 enforcement rigor would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Electric and Autonomous Vehicles Wiring Harness Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Automotive Steer-By-Wire System (Sbw) Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
South Africa Automotive Camera Market
Automotive Electronics & Wiring
USA Automotive Smart Keys Market