
 Navigation System Market | 2026-2036
Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Navigation System Market Outlook
ISO 26262 functional safety certification is bifurcating the competitive landscape between qualified automotive-grade suppliers and generalist positioning vendors. Garmin Ltd. leverages its consumer heritage while extending into aviation-certified displays. Thales Group dominates military-grade encrypted navigation through sovereign European supply chains. Trimble Inc. anchors precision agriculture and construction workflows with centimeter-level correction services.
A navigation system comprises positioning hardware, mapping software, and connectivity modules that compute real-time location using satellite constellations and sensor fusion, typically achieving lane-level accuracy through multi-frequency GNSS receivers combined with inertial measurement units. Its primary purpose spans route optimization, asset tracking, and autonomous vehicle guidance across commercial and defense applications. Integrated product types now capture the bulk of OEM automotive contracts as dashboards consolidate functions. Cloud-based architectures represent the fastest-expanding technology layer, enabling over-the-air map updates and crowd-sourced traffic fusion. Fleet management applications generate recurring revenue streams through subscription telemetry services, while military demand sustains premium pricing for anti-jam waveform resilience.
FAA Technical Standard Orders govern U.S. aviation navigation hardware, while Europe's ETSI EN 303 413 and CE marking frameworks regulate radio frequency emissions for automotive and personal devices. These certification regimes create multi-year qualification barriers that freeze out unqualified vendors and lock in incumbent relationships. China's MIIT issues network access licenses for terrestrial augmentation systems, adding a parallel compliance track for suppliers serving domestic automotive brands. Stakeholders must monitor divergence between sovereign GNSS constellations and encryption protocols, as regional autonomy initiatives fragment formerly unified technical standards.
Market Dynamics
Automotive OEM consolidation of dashboard electronics is compressing supplier tiers, forcing navigation hardware vendors to absorb mapping software capabilities or exit embedded contracts entirely. Tier 1 integrators now specify combined positioning-software stacks that eliminate standalone module procurement.
Growth Catalysts
- ETSI EN 303 413 compliance mandates:Europe's radio equipment standards are accelerating replacement cycles for non-compliant legacy hardware across German and French automotive production lines.
- Sensor fusion architectures:Multi-frequency GNSS receivers combined with inertial measurement units are enabling lane-level accuracy requirements for autonomous vehicle platforms.
- Cloud-based map distribution:Over-the-air update infrastructure is decomposing traditional physical media supply chains and creating recurring revenue attachment points.
Market Restraints
- Semiconductor foundry concentration:Advanced multi-frequency receiver fabrication depends on Taiwan-based capacity subject to geopolitical supply interruption risk.
- ISO 26262 qualification timelines:Functional safety certification for automotive-grade silicon extends development cycles and freezes out generalist positioning vendors.
- Terrestrial augmentation substitution:Cellular-based positioning services in dense urban corridors threaten standalone GNSS module attach rates.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Domestic production incentives are opening captive supply opportunities for navigation hardware serving Maruti Suzuki and Tata Motors platforms.
- Construction equipment autonomy:Centimeter-level correction services for excavator and grader fleets represent an underpenetrated vertical beyond precision agriculture.
- China MIIT network access licensing:Terrestrial augmentation system approvals create a parallel compliance track favoring local joint ventures over direct import.
Industry Challenges
- Multi-constellation firmware complexity:Simultaneous Galileo, BeiDou, and GPS signal processing requires specialized RF engineering talent scarce outside aerospace hubs.
- Anti-jam waveform IP licensing:Military-grade encrypted navigation depends on sovereign patent thickets that fragment supplier qualification across defense procurement jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Navigation System Market |
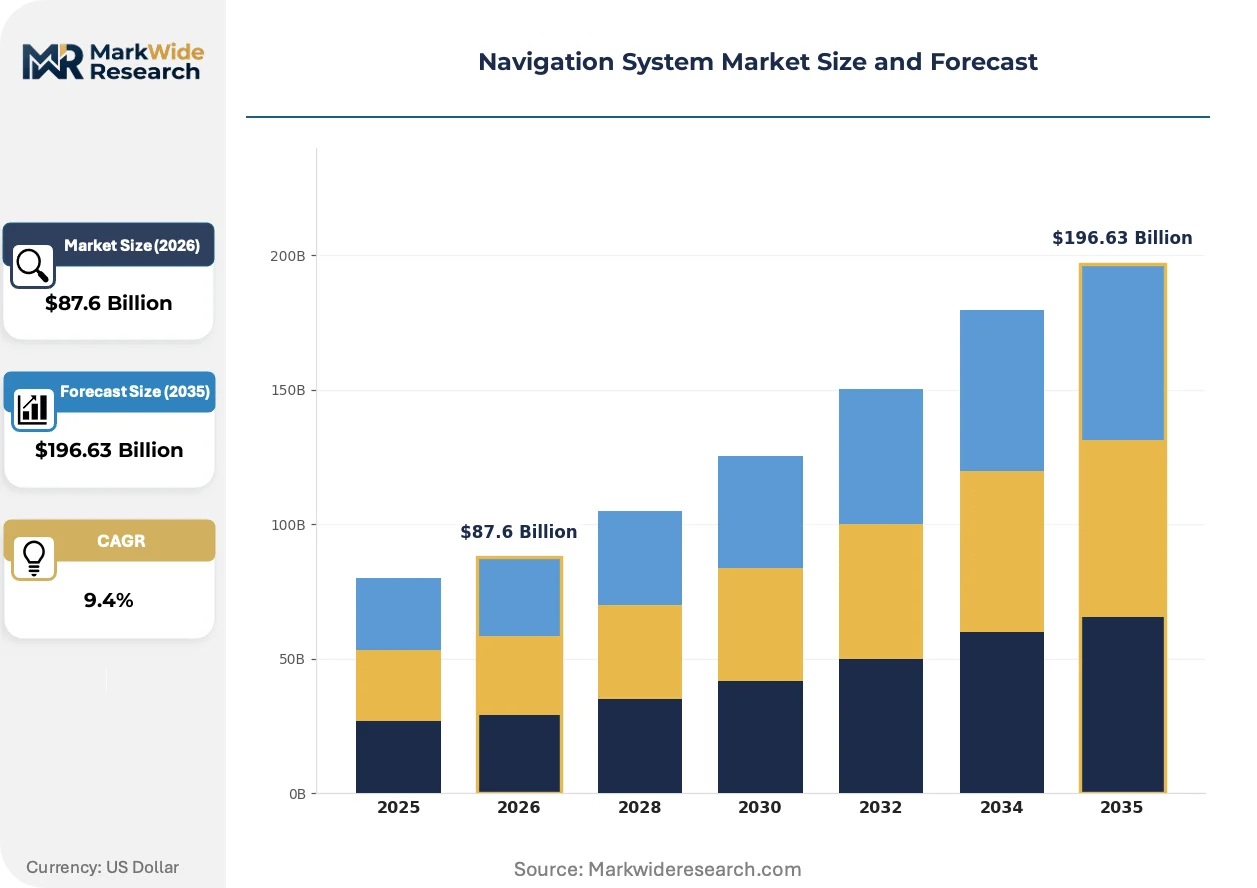
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Mobile, Cloud-Based Technology: GPS, GNSS, RFID, Ultra-Wideband End User: Aerospace, Automotive, Marine, Logistics Application: Personal Navigation, Fleet Management, Emergency Services, Military |
| Companies Covered | Safran Electronics & Defense, Thales Group, Garmin Ltd., Trimble Inc., HERE Technologies, Honeywell International Inc., TomTom N.V., L3Harris Technologies Inc., Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Navigation System Market Strategic Shifts
Navigation system architecture is fragmenting into disaggregated hardware-software layers that decouple positioning compute from display rendering. This decomposition is redistributing value capture toward cloud-based map providers and away from integrated module vendors.
Multi-frequency GNSS chipsets is decomposing the traditional standalone receiver market by embedding positioning compute directly into automotive system-on-chip designs. Qualcomm and NXP semiconductor platforms now integrate multi-constellation basebands that eliminate separate navigation processor procurement. This compression forces legacy receiver vendors into software-only map licensing or aviation-military niche survival.
Europe's CSRD sustainability disclosure requirements are mandating supply chain carbon footprint documentation for automotive electronics suppliers. Tier 1 integrators now require navigation module vendors to certify smelter sources and energy consumption per unit. German OEM procurement teams are prioritizing qualified suppliers with documented Scope 3 reductions.
Fleet operators are unbundling navigation hardware from telematics service contracts, treating positioning as a commodity input while paying premiums for predictive maintenance analytics. This preference shift compresses standalone GPS device margins and elevating platform vendors with integrated vehicle health monitoring. North American trucking carriers are consolidating supplier relationships around combined navigation-telemetry offerings.
Navigation System Market Segmentation
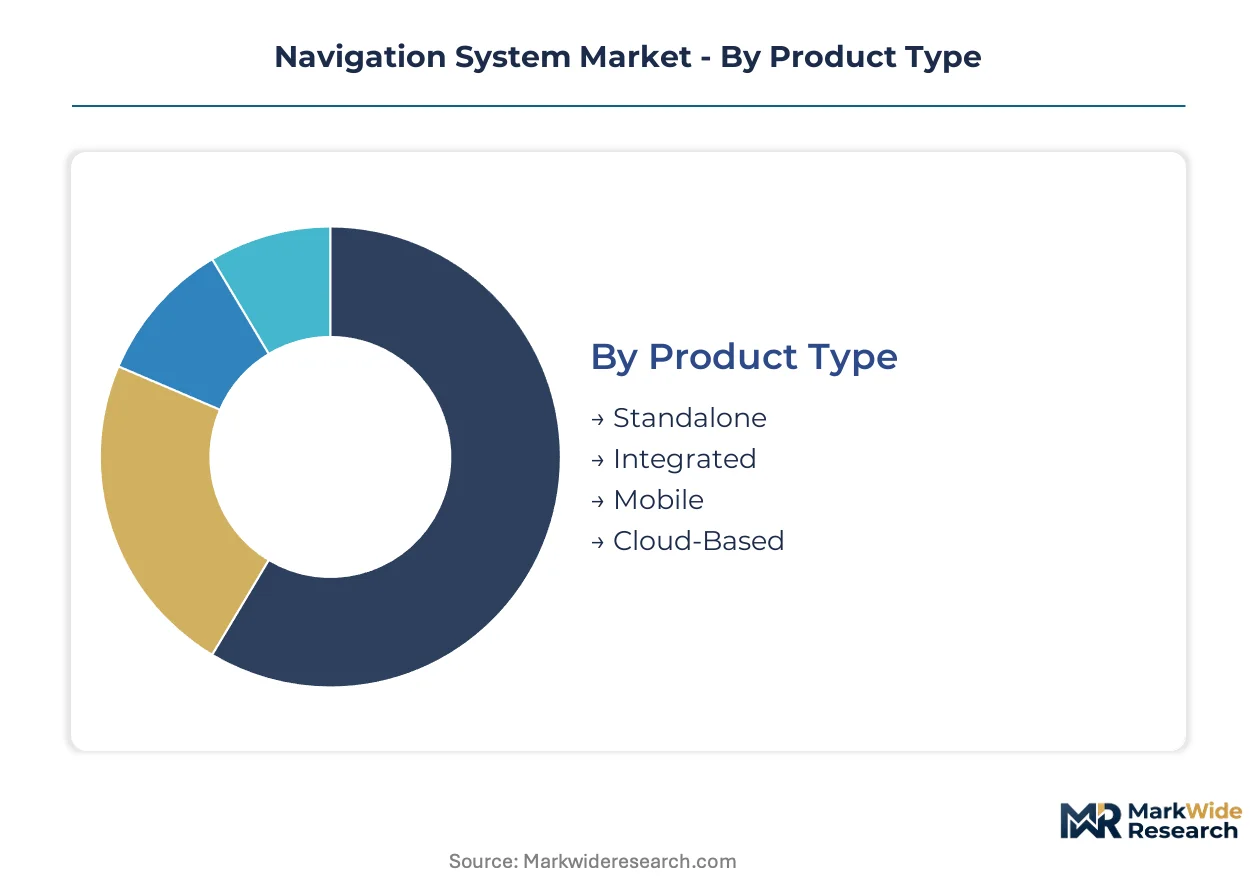
Navigation system procurement varies sharply across certification tiers, with automotive-grade silicon commanding premium qualification timelines while consumer-grade modules compete on cost. Understanding how product architecture, signal technology, end-use requirements, and deployment models fragment demand enables suppliers to target qualification investments and avoid margin erosion in commoditized segments.
Product Type:
ETSI EN 303 413 and CE marking thresholds in Europe bifurcate hardware into certified automotive-grade equipment versus consumer electronics, with compliance timelines extending development cycles by 18-24 months for embedded contracts.
- Integrated:Combined positioning-software stacks embedded directly into automotive system-on-chip designs eliminate separate navigation processor procurement. German Tier 1 suppliers specify these consolidated modules for dashboard consolidation programs across Volkswagen and BMW platforms, absorbing standalone receiver vendors into software-only roles.
- Cloud-Based:Over-the-air map distribution architectures decompose traditional physical media supply chains and create recurring revenue attachment points through subscription telemetry. Fleet operators in North American trucking corridors unbundle hardware from service contracts here, treating positioning as commodity input while paying premiums for predictive maintenance analytics.
- Standalone:Discrete receiver modules persist in aviation and marine applications where FAA Technical Standard Orders and sovereign maritime regulations mandate hardware traceability.
- Mobile:Smartphone-integrated positioning relies on multi-constellation basebands from Qualcomm and NXP platforms, compressing margins for dedicated receiver vendors.
Integrated modules handle the majority of automotive throughput; cloud-based architectures are expanding most quickly on share as over-the-air infrastructure matures.
Technology:
Cost tier differentiation separates precision correction services from standard positioning, with centimeter-level accuracy commanding subscription premiums in agriculture and construction while meter-level GNSS saturates consumer automotive.
- GNSS:Multi-frequency receivers processing Galileo, BeiDou, and GPS signals simultaneously enable lane-level accuracy through sensor fusion with inertial measurement units. Automotive OEMs in Germany's manufacturing corridor specify these chipsets for autonomous vehicle platforms, though firmware complexity requires RF engineering talent scarce outside aerospace hubs.
- GPS:Legacy single-constellation receivers dominate price-sensitive fleet telematics and personal navigation devices where regulatory mandates do not require multi-signal redundancy.
- Ultra-Wideband:Short-range precision positioning for indoor asset tracking and automated warehouse robotics operates on unlicensed spectrum with minimal regulatory qualification overhead.
- RFID:Passive and active radio-frequency identification supports yard management and container tracking in logistics hubs where satellite visibility is obstructed.
GNSS carries the heaviest automotive qualification burden; ultra-wideband is climbing the fastest as indoor positioning demand accelerates.
End User:
Customer type determines certification intensity, with military and aerospace procurement requiring anti-jam waveform resilience and encrypted navigation while commercial automotive prioritizes ISO 26262 functional safety.
- Automotive:Embedded navigation adoption as standard equipment drives volume, with OEM consolidation of dashboard electronics compressing supplier tiers and forcing hardware vendors to absorb mapping software capabilities or exit contracts entirely.
- Aerospace:FAA Technical Standard Orders govern U.S. aviation hardware while European equivalents mandate sovereign supply chain documentation for encrypted navigation systems.
- Logistics:Fleet management applications generate recurring revenue through subscription telemetry services, with unbundling trends compressing standalone GPS device margins.
- Marine:Commercial shipping and recreational boating demand weather-resistant hardware with chart plotter integration, subject to International Maritime Organization equipment standards.
Automotive end-use generates the dominant revenue base; logistics is gaining share fastest as fleet telemetry unification accelerates.
Application:
Deployment maturity varies from saturated personal navigation smartphones to underpenetrated construction equipment autonomy requiring centimeter-level correction services.
- Fleet Management:Combined navigation-telemetry offerings consolidate supplier relationships among North American trucking carriers, with platform vendors integrating vehicle health monitoring commanding premium positioning.
- Military:Anti-jam waveform resilience and sovereign encryption protocols sustain premium pricing, though patent thickets fragment supplier qualification across defense procurement jurisdictions.
- Personal Navigation:Smartphone saturation has collapsed standalone device demand, relegating dedicated hardware to aviation and marine niches.
- Emergency Services:First responder location requirements drive public safety-grade reliability specifications with enhanced indoor positioning mandates.
Fleet management anchors commercial revenue; military applications maintain the steepest pricing tier despite lower volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for automotive electronics is reshaping supplier geography, while Europe's ETSI mandates accelerate hardware replacement cycles. Germany's automotive corridor and China's MIIT licensing regime concentrate embedded navigation procurement.
United States
FAA Technical Standard Orders govern aviation hardware certification, creating multi-year qualification barriers for cockpit navigation systems. The FAA mandates hardware traceability for encrypted navigation in commercial and defense aircraft. Greater Seattle and Dallas-Fort Worth anchor aerospace clusters where Collins Aerospace and Honeywell maintain sovereign supply chains for military-grade waveform resilience.
Germany
ETSI EN 303 413 compliance mandates are accelerating replacement cycles for non-compliant legacy hardware across Volkswagen and BMW production lines. KBA vehicle-type approval requires documented functional safety certification for embedded navigation modules. Stuttgart and Munich host Tier 1 integrators specifying combined positioning-software stacks that absorb standalone receiver vendors.
China
MIIT network access licenses for terrestrial augmentation systems favor local joint ventures over direct import for domestic automotive brands. SAMR market surveillance enforces GB standards for radio equipment in connected vehicles. The Yangtze River Delta concentrates multi-constellation chipset fabrication where Qualcomm and NXP platforms integrate positioning basebands.
India
PLI scheme production incentives are opening captive supply opportunities for navigation hardware serving Maruti Suzuki and Tata Motors platforms. BIS certification mandates radio equipment standards for automotive electronics imports. Gujarat and Tamil Nadu automotive corridors host emerging Tier 2 suppliers qualifying for embedded navigation contracts.
Japan
METI industrial policy prioritizes autonomous vehicle positioning infrastructure through public-private consortia. JIS standards govern electromagnetic compatibility for automotive-grade receivers. Nagoya's Chubu region anchors precision manufacturing clusters where sensor fusion engineering talent concentrates for lane-level accuracy development.
Navigation System Market Competitive Environment
Player mix skews toward diversified aerospace-defense conglomerates with sovereign encryption capabilities, compressing mid-tier positioning specialists into software-only roles. Tier 1 automotive integrators now specify combined hardware-software stacks that eliminate standalone module procurement. Two strategic archetypes dominate: military-grade encrypted navigation vendors with anti-jam IP portfolios, and precision agriculture-construction specialists with centimeter-level correction service networks. Competitive moves center on backward integration into multi-frequency chipset design and geographic expansion through MIIT-licensed joint ventures in China.
Among diversified aerospace-defense conglomerates, Thales Group and L3Harris Technologies exemplify the military-grade encrypted navigation archetype, occupying positions sustained by sovereign European and North American supply chain requirements. Garmin Ltd. anchors the consumer-heritage vector extending into aviation-certified displays. HERE Technologies sits within the cloud-based map distribution tier, representing the value migration toward over-the-air update infrastructure and recurring telemetry revenue streams.
| Leading Market Players |
|---|
| Safran Electronics & Defense |
| Thales Group |
| Garmin Ltd. |
| Trimble Inc. |
| HERE Technologies |
| Honeywell International Inc. |
| TomTom N.V. |
| L3Harris Technologies Inc. |
| Collins Aerospace |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwan-based foundries lock in multi-frequency GNSS receiver supply while fixing unit costs for German automotive OEMs navigating ETSI compliance mandates. These arrangements tether pricing visibility to semiconductor allocation priority, compressing margin flexibility for unqualified vendors frozen out by ISO 26262 timelines.
Pricing Analysis
Certification level creates the primary spread, with ISO 26262 automotive-grade silicon commanding three-tier pricing structure across premium, standard, and economy levels based on functional safety documentation depth. Subscription-based telemetry services for fleet management generate recurring revenue streams that offset hardware commoditization, while project-based military contracts sustain premium pricing for anti-jam waveform resilience. Cost compression in consumer-grade modules intensifies as smartphone-integrated positioning eliminates standalone receiver attach rates. Tier 1 automotive integrators exhibit lowest price sensitivity due to dashboard consolidation requirements, whereas personal navigation device manufacturers face acute margin pressure from platform vendor competition.
Supply Chain Analysis
Strategic stockpiling of multi-frequency GNSS basebands dominates automotive qualification cycles, contrasting with just-in-time inventory for consumer electronics where specification volatility is lower. Taiwan, South Korea, and China concentrate advanced receiver fabrication, with Yangtze River Delta facilities anchoring Qualcomm and NXP platform integration. Raw material dependencies span gallium arsenide substrates, precision RF filters, and inertial measurement unit MEMS sensors. Single-source vulnerability concentrates in Taiwan-based foundry capacity subject to geopolitical interruption risk. Distribution runs through Tier 1 integrator direct procurement for embedded automotive contracts, bypassing traditional module vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular-based positioning services in dense urban corridors threaten standalone GNSS module substitution, forcing incumbents to defend integrated software-hardware value capture against telecommunications platform encroachment.
For Market Incumbents: Secure ISO 26262 qualification pipelines ahead of German KBA vehicle-type approval deadlines to freeze out generalist positioning vendors from Volkswagen and BMW platform contracts. Backward integration into multi-frequency chipset design with Taiwan-based foundry capacity reservations defends margin position against Qualcomm and NXP platform consolidation. Anti-jam waveform IP licensing with sovereign European supply chains reinforces military-grade positioning moats against Thales Group and L3Harris Technologies dominance. For New Entrants and Emerging Players: Lead with construction equipment autonomy as the most penetrable vertical beyond precision agriculture, where Trimble Inc. correction service networks remain underextended for excavator and grader fleets. Target India's PLI scheme production incentives for captive supply opportunities serving Maruti Suzuki and Tata Motors platforms, exploiting BIS certification gaps before incumbent qualification. Cloud-based map distribution architectures offer lowest barrier-to-entry for software-only positioning plays, decoupling from hardware qualification timelines entirely. For Investors and Strategic Acquirers: Capital is best deployed toward precision agriculture-construction specialists with centimeter-level correction service networks and established subscriber bases, as these verticals exhibit durable pricing power against commodity GNSS erosion. Acquisition target archetype combines multi-constellation firmware engineering talent with MIIT-licensed joint venture access in China, capturing terrestrial augmentation system growth. Signal to watch is divergence between sovereign GNSS constellation encryption protocols, which fragments supplier qualification and creates regional monopoly opportunities for compliant vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Frequency Chipset Integration | Embedding Galileo, BeiDou, and GPS basebands into automotive system-on-chip designs eliminates standalone navigation processor procurement. |
| Terrestrial Augmentation Licensing | China MIIT network access approvals favor local joint ventures over direct import for domestic automotive brand supply. |
| Cloud-Based Map Distribution | Over-the-air update infrastructure decomposes physical media supply chains and creates recurring telemetry revenue attachment points. |
| Anti-Jam Waveform IP Development | Military-grade encrypted navigation depends on sovereign patent thickets that fragment supplier qualification across defense procurement jurisdictions. |
| Construction Equipment Autonomy | Centimeter-level correction services for excavator and grader fleets represent underpenetrated vertical beyond precision agriculture saturation. |
Study Parameters
A spread of perspectives from Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, and RF engineering specialists converged on the working assumptions for navigation system demand trajectories. Primary fieldwork with German automotive corridor integrators and Taiwan-based foundry planning teams combined with secondary validation through ETSI regulatory filings, FAA Technical Standard Order databases, vehicle production registries, and semiconductor customs records. Bottom-up unit economics for multi-frequency receiver bill-of-materials were triangulated against top-down OEM platform adoption forecasts.
Segmentation dimensions modeled span product architecture, signal technology, end-use certification intensity, and deployment model across the projection horizon. Automotive-grade versus consumer-grade silicon bifurcation, multi-constellation versus single-constellation receiver design, and integrated versus standalone module procurement patterns structured the analytical framework. CAGRs were derived from shipment volume trajectories weighted by average selling price evolution for each certification tier. Industry-specific forecast inputs included ETSI EN 303 413 compliance mandate timing and MIIT terrestrial augmentation licensing velocity.
Underlying assumptions cover sustained Taiwan-based foundry capacity allocation, stable ETSI regulatory trajectory, and continued OEM dashboard consolidation preference, with deviation risk concentrated in geopolitical supply interruption and sovereign GNSS constellation fragmentation. Forecasts reflect these conditions with explicit sensitivity to qualification timeline extensions and terrestrial positioning substitution acceleration. Revision becomes warranted when cellular-based positioning accuracy crosses autonomous vehicle lane-level thresholds in dense urban deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Construction Machinery Wiring Harness Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Latin America Automotive Camera Market