
 Automotive OLED Market | 2026-2036
Automotive OLED Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive OLED Market Analysis
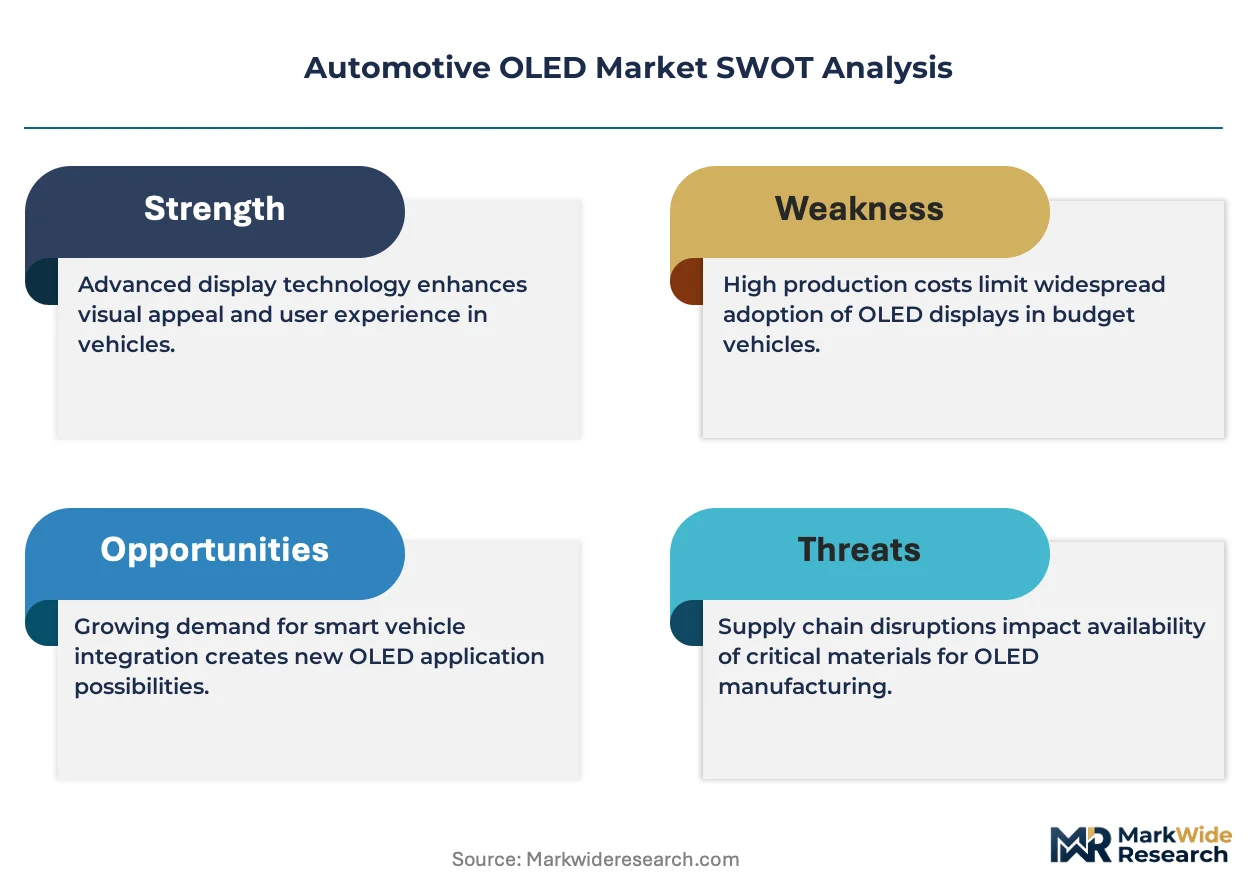
Capital-intensity divergence between display panel fabricators and automotive lighting specialists is redrawing competitive boundaries in automotive OLED supply. Samsung Display leverages vertical integration across semiconductor backplanes and organic deposition to sustain technology leadership in flexible cockpit displays. BOE Technology Group competes through manufacturing scale in rigid OLED instrument clusters, while OSRAM anchors its position in exterior lighting modules through phosphorescent OLED architectures and thermal management IP.
Automotive OLED denotes electroluminescent diode arrays employing organic compounds that emit light across visible wavelengths when current passes between anode and cathode layers, typically fabricated on glass or polyimide substrates with thin-film encapsulation below 10 micrometers to prevent moisture ingress. These devices serve dual commercial purposes: information displays exploit self-emissive pixels for infinite contrast and form-factor freedom, while lighting applications exploit surface-area emission and dimmability for signature styling and adaptive beam shaping. Flexible OLED technology captures the dominant margin pool as curved infotainment surfaces and wraparound dashboard elements penetrate luxury vehicle lines, whereas transparent OLED represents the fastest-growing structural category for augmented-reality head-up display integration. Rigid OLED maintains volume concentration in cost-sensitive instrument panel applications where planar geometry suffices.
FCC electromagnetic compatibility standards and NHTSA driver-distraction guidelines shape display luminance limits and interface response protocols for US-market vehicles, while REACH substance restrictions and RoHS hazardous-material limits govern organic compound selection and manufacturing chemistry for European supply chains. Japan's METI energy-efficiency benchmarks and JIS reliability standards further constrain module thermal performance and operational lifetime certification. Stakeholders must monitor regulatory convergence between automotive functional-safety mandates and consumer-electronics display standards as cabin digitization accelerates.
Market Dynamics
Curved dashboard displays are reconfiguring cockpit electronics procurement as premium electric vehicle manufacturers demand seamless visual surfaces that conventional LCD technology cannot fabricate.
Growth Catalysts
- EU Vehicle Safety Mandates:European Union regulations on driver distraction and energy efficiency are compelling OEMs to replace incandescent lighting with OLED exterior modules.
- Flexible Substrate Engineering:Polyimide-based manufacturing breakthroughs enable wraparound instrument panels that conform to curved interior surfaces without optical distortion.
- South Korean Cluster Concentration:Display panel engineering co-location with luxury automotive headquarters accelerates prototype-to-production cycles for next-generation cockpit systems.
Market Restraints
- Organic Compound Supply Concentration:Phosphorescent emitter material synthesis depends on a limited supplier base concentrated in East Asian chemical foundries.
- Thermal Degradation Limits:Operational lifetime certification requires sub-85°C junction temperatures that constrain peak luminance in direct-sunlight applications.
- Thin-Film Encapsulation Costs:Multi-layer barrier deposition below 10 micrometers thickness demands vacuum processing that inflates module cost structures relative to LED alternatives.
Strategic Opportunities
- Transparent OLED HUD Integration:Windshield-embedded augmented-reality displays represent unserved demand in the German luxury automotive segment.
- US IRA Clean Vehicle Credits:Domestic content requirements for federal tax incentives are incentivizing North American OLED module assembly investments.
- Digital Mirror Replacement:Camera-monitor systems using flexible OLED rear-view displays are penetrating Japanese regulatory frameworks as conventional mirror alternatives.
Industry Challenges
- Automotive Functional Safety Certification:ISO 26262 ASIL-B compliance for display systems requires fault-tolerant pixel architectures that extend validation timelines.
- Cross-Industry Talent Competition:Organic electronics PhD specialists face recruitment pressure from consumer display and pharmaceutical sectors with deeper compensation pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive OLED Market |
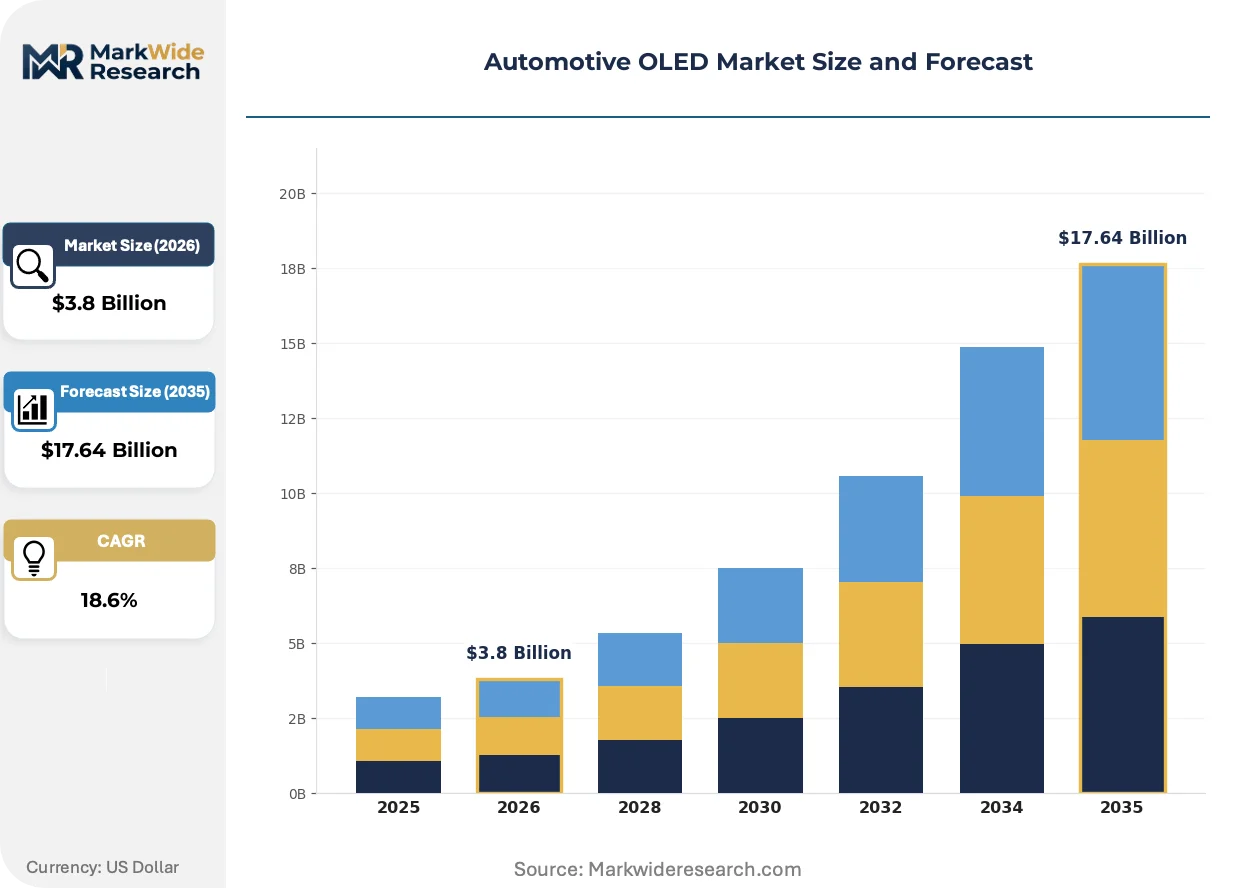
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Lighting, Instrument Panels, Head-Up Displays Technology: Flexible OLED, Rigid OLED, Transparent OLED, MicroOLED End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Interior Design, Exterior Lighting, Dashboard, Infotainment Systems |
| Companies Covered | LG Display, Samsung Display, BOE Technology Group, OSRAM, Continental AG, Denso Corporation, Visteon Corporation, Japan Display Inc., Universal Display Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive OLED Market Emerging Trajectories
Automotive OLED technology is bifurcating into two innovation tracks: display applications pursuing form-factor freedom through flexible substrates, and lighting applications exploiting surface-area emission for signature styling.
Phosphorescent OLED architectures are displacing fluorescent alternatives in exterior lighting modules by delivering higher external quantum efficiency at equivalent drive voltages. Tier-1 lighting suppliers are adopting this emitter technology for adaptive beam-shaping applications in premium vehicle lines. The transition is compressing power consumption benchmarks and enabling slimmer headlamp form factors that violate no previous thermal packaging constraints.
Japan's METI energy-efficiency benchmarks are tightening operational lifetime requirements for cabin display modules, forcing manufacturers to redesign thermal management subsystems. These standards now mandate 15,000-hour luminance maintenance above 70% for certified automotive panels. Korean and Chinese display fabricators are responding with graphite-sheet heat spreaders and localized dimming algorithms that reduce peak thermal load.
Fleet procurement of standardized cockpit electronics is fragmenting previously consolidated OEM supply agreements. Rental and mobility-service operators are specifying modular display architectures that permit rapid replacement without vehicle downtime. This behavioral shift is most visible in North American and European electric vehicle subscription programs, where uptime guarantees override brand-differentiated interior specifications.
Automotive OLED Market Segmentation
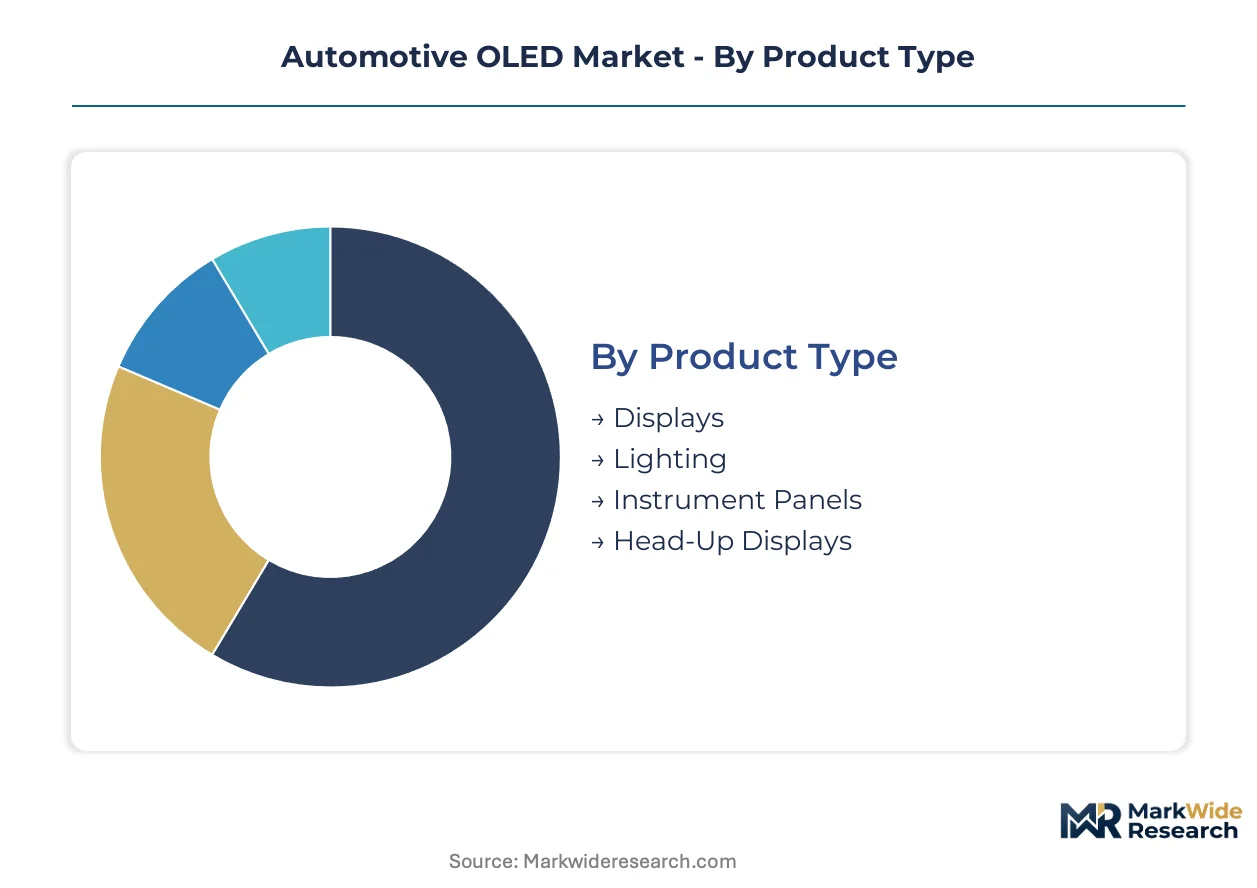
Automotive OLED procurement channels diverge sharply between display panel fabricators supplying direct to OEMs and lighting specialists routing through Tier-1 integrators. Understanding these pathway distinctions illuminates where margin pools concentrate and which technical specifications dominate purchasing criteria.
Product Type:
Displays and lighting modules flow through fundamentally different commercial channels, with display panels shipping direct from Korean and Chinese fabricators to vehicle brand headquarters while exterior lighting assemblies route through specialized Tier-1 automotive suppliers.
- Displays:Self-emissive pixel arrays fabricated on glass or polyimide substrates deliver infinite contrast ratios for cockpit information surfaces. Demand concentrates in German luxury electric vehicle programs where curved dashboard integration commands premium positioning against conventional LCD alternatives.
- Lighting:Surface-area emission modules employing phosphorescent organic architectures enable signature styling and adaptive beam shaping. South Korean chemical foundries supply the iridium-based emitter complexes that determine external quantum efficiency in headlamp applications.
- Instrument Panels:Planar or gently curved information clusters combining gauge readouts with warning indicators.
- Head-Up Displays:Windshield-projection systems requiring high peak luminance for daylight visibility.
By volume, Displays leads. By growth pace, Head-Up Displays is climbing the fastest.
Technology:
Manufacturing cost tiers separate these technologies, with rigid substrates occupying economy positioning and flexible polyimide constructions commanding premium pricing for form-factor freedom.
- Flexible OLED:Polyimide substrate engineering enables wraparound dashboard surfaces that conform to curved interior geometries without optical distortion. German OEMs specify these modules for flagship electric vehicle lines where cabin differentiation justifies unit costs three to four times above rigid alternatives.
- Rigid OLED:Glass-substrate construction delivers planar emission surfaces at manufacturing scales that constrain per-unit costs. Volume concentration sits in cost-sensitive instrument panel applications across mid-market vehicle segments where planar geometry suffices.
- Transparent OLED:Partially transmissive pixel architectures permitting see-through operation for augmented-reality integration.
- MicroOLED:Silicon backplane fabrication achieving pixel densities exceeding conventional display limits for compact projection systems.
By installed base, Rigid OLED dominates. By expansion trajectory, Transparent OLED is gaining share fastest.
End User:
Procurement authority patterns determine specification stringency, with OEM direct purchasing enforcing the tightest thermal performance and lifetime certification requirements.
- OEMs:Vehicle brand headquarters in Germany, South Korea, and the United States issue technical specifications that cascade through supply chains. These organizations mandate ISO 26262 ASIL-B compliance and 15,000-hour luminance maintenance thresholds that filter supplier qualification.
- Tier-1 Suppliers:Lighting and electronics integrators combining OLED modules with thermal management, driver circuitry, and mechanical housing.
- Aftermarket Providers:Replacement and upgrade specialists serving vehicle modification and repair channels.
- Vehicle Assemblers:Contract manufacturing facilities executing final integration per OEM-provided build specifications.
By contract value, OEMs command the largest share. By channel expansion, Aftermarket Providers are expanding most quickly.
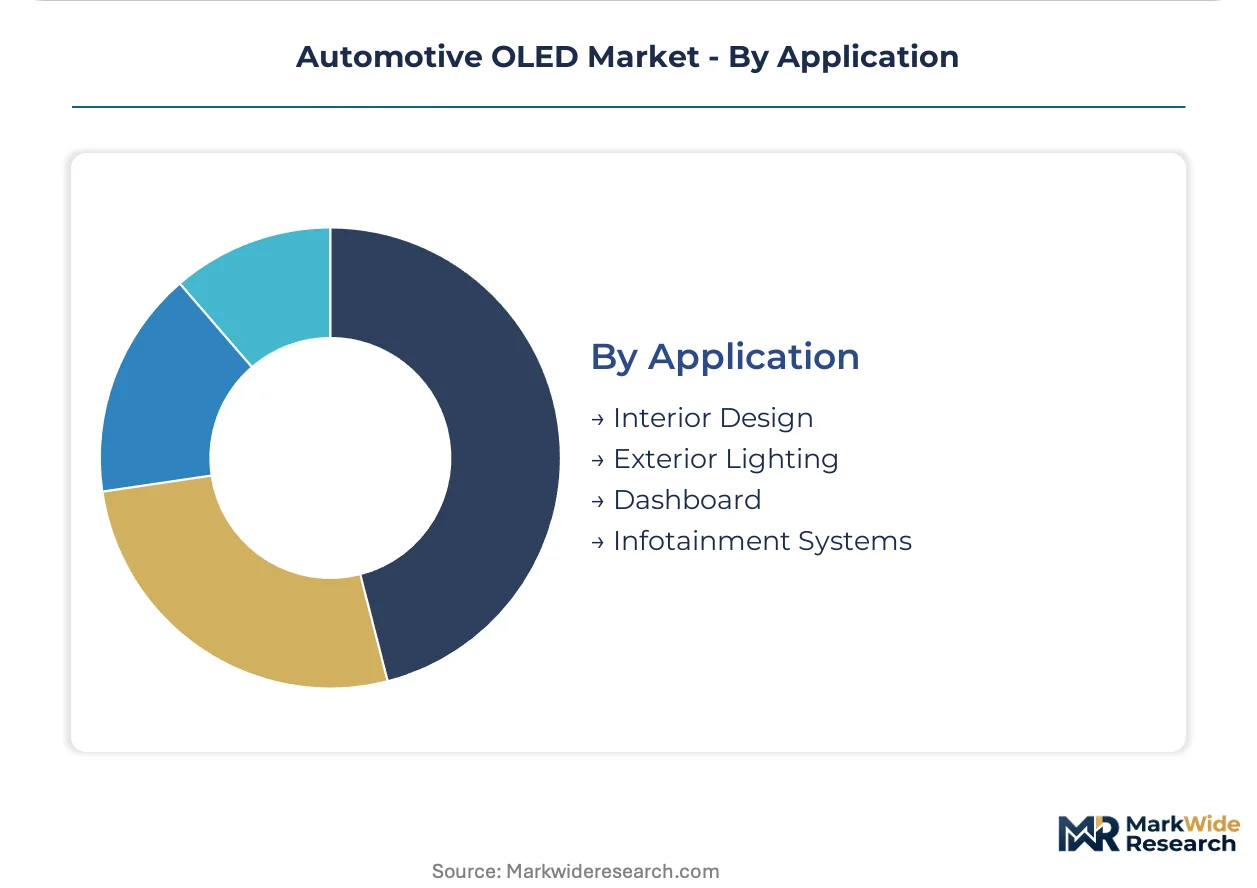
Application:
Interior and exterior deployment environments impose divergent reliability demands, with cabin modules facing thermal cycling and lighting modules confronting moisture, vibration, and stone impact exposure.
- Interior Design:Ambient lighting and decorative surface illumination exploiting OLED surface-area emission for uniform glow without point-source artifacts. Japanese OEMs specify these modules for flagship sedan programs where cabin atmosphere differentiation supports premium pricing.
- Exterior Lighting:Headlamp, taillamp, and signature lighting modules requiring hermetic sealing against environmental ingress.
- Dashboard:Centralized information display surfaces combining instrumentation with navigation and entertainment integration.
- Infotainment Systems:Touch-interactive media and connectivity interfaces demanding rapid pixel response and wide color gamut reproduction.
By deployment volume, Dashboard leads. By specification intensity, Exterior Lighting imposes the steepest certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net exporters of OLED display panels dominate automotive supply chains, while vehicle-assembly nations import modules for final integration. Trade flows concentrate between East Asian fabrication centers and German, US, and South Korean vehicle headquarters.
Germany
Luxury OEM headquarters in Munich and Stuttgart specify curved dashboard OLED modules for flagship electric vehicle programs. REACH substance restrictions and RoHS hazardous-material limits govern organic compound selection across European supply chains. The Baden-Württemberg cluster hosts engineering co-location between display panel makers and Tier-1 lighting integrators.
South Korea
Seoul-based display fabricators supply flexible OLED substrates directly to domestic and German luxury vehicle manufacturers. METI energy-efficiency benchmarks from Japan indirectly shape Korean export certification standards through competitive alignment. The Gyeonggi-do corridor concentrates phosphorescent emitter material synthesis and thin-film encapsulation capacity.
United States
NHTSA driver-distraction guidelines constrain display luminance limits and interface response protocols for domestic-market vehicles. IRA Clean Vehicle Credits incentivize North American OLED module assembly investments through domestic content requirements. Michigan and California engineering centers prototype head-up display integration for augmented-reality windshield systems.
Japan
METI mandates 15,000-hour luminance maintenance above 70% for certified automotive panels, forcing thermal management subsystem redesigns. JIS reliability standards further constrain module operational lifetime certification. The Kansai region anchors phosphorescent OLED architecture development for exterior lighting modules.
China
BOE Technology Group and domestic fabricators scale rigid OLED production for cost-sensitive instrument panel applications. MIIT industrial policy supports display panel manufacturing scale expansion. The Yangtze River Delta cluster concentrates backplane semiconductor fabrication and organic deposition capacity.
Automotive OLED Market Vendor Landscape
Concentration sits with display panel fabricators possessing captive semiconductor backplane capacity and organic deposition expertise. Korean and Chinese manufacturers command cockpit display supply through direct OEM relationships, while European and Japanese specialists anchor exterior lighting module integration. Two strategic archetypes dominate: vertically integrated display fabricators and phosphorescent emitter material specialists. Competitive moves center on capacity expansion for flexible substrate manufacturing and strategic partnerships for thin-film encapsulation technology licensing.
Among Korean fabricators, LG Display Co., Ltd. and Samsung Display Co., Ltd. exemplify the vertically integrated archetype with control over backplane semiconductor and organic deposition processes. BOE Technology Group Co., Ltd. represents Chinese manufacturing scale in rigid substrate construction. These three anchors illustrate how geographic clustering of display engineering with luxury vehicle headquarters accelerates prototype-to-production cycles.
| Leading Market Players |
|---|
| LG Display |
| Samsung Display |
| BOE Technology Group |
| OSRAM |
| Continental AG |
| Denso Corporation |
| Visteon Corporation |
| Japan Display Inc. |
| Universal Display Corporation |
| Others |
Supply Flow & Price Mechanics
ISO 26262 ASIL-B functional safety certification gates both supplier qualification and price differentiation simultaneously, forcing display fabricators to absorb validation costs that rigid OLED producers cannot recover in mid-market instrument panel contracts. Buyers with flagship electric vehicle programs leverage this barrier to extract premium positioning for curved flexible modules while relegating planar alternatives to commodity procurement tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Flexible polyimide substrate modules command premium positioning against rigid glass alternatives due to form-factor freedom and thermal management complexity. Cost compression in rigid instrument panel tiers is intensifying because BOE Technology Group and Chinese fabricators are scaling manufacturing capacity without corresponding demand expansion. Fleet procurement teams at rental and mobility-service operators exhibit the highest price sensitivity, while German luxury OEM platform engineers prioritize performance specifications over unit economics.
Supply Chain Analysis
Phosphorescent emitter material synthesis in South Korean chemical foundries anchors supply concentration for exterior lighting modules. The Gyeonggi-do corridor draws from iridium-based precursor chemicals and thin-film encapsulation equipment to sustain organic deposition capacity. Single-source vulnerability concentrates in East Asian phosphorescent emitter supply, where limited qualified suppliers constrain adaptive beam-shaping module availability. Distribution runs through direct OEM relationships for display panels and Tier-1 lighting integrators for exterior modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU vehicle safety mandates on energy efficiency and driver distraction are accelerating OLED substitution faster than supply chain capacity expansion can match, creating a high-growth disruption window for qualified suppliers.
For Market Incumbents: Shield market position by deepening captive supply of phosphorescent emitter materials through backward integration into South Korean chemical synthesis capacity. Accelerate ISO 26262 ASIL-D certification investment for next-generation fault-tolerant pixel architectures before emerging Chinese fabricators close the compliance gap. The priority lever sits in thermal management IP that sustains 15,000-hour luminance maintenance thresholds under METI benchmarks. For New Entrants and Emerging Players: Aftermarket modular display architectures for fleet operators represent a service-layer gap where incumbents under-serve rapid replacement requirements. Target North American electric vehicle subscription programs where uptime guarantees override brand-differentiated specifications. Penetration runs fastest through standardized cockpit electronics with plug-and-play thermal management subsystems that minimize vehicle downtime. For Investors and Strategic Acquirers: IRA Clean Vehicle Credits reshapes the acquisition landscape by incentivizing North American OLED module assembly investments through domestic content requirements. Long-term viability centers on suppliers with qualified flexible substrate capacity and established OEM direct relationships. The signal to watch is Tier-1 lighting integrator consolidation as phosphorescent OLED architecture specialization concentrates among fewer European and Japanese specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Flexible Substrate Capacity Expansion | Korean fabricators leverage polyimide engineering breakthroughs to capture curved dashboard demand from German luxury OEMs. |
| Phosphorescent Emitter Backward Integration | Lighting specialists secure iridium-based material supply chains against East Asian chemical foundry concentration risk. |
| North American Assembly Footprint | Domestic module production qualifies Tier-1 suppliers for IRA Clean Vehicle Credit content requirements. |
| Thermal Management IP Development | Graphite-sheet heat spreader and localized dimming algorithm patents differentiate suppliers under METI lifetime benchmarks. |
| Transparent OLED HUD Partnership | Windshield-embedded augmented-reality display collaboration with German OEM engineering centers captures unserved premium demand. |
Methodological Framework
The analysis maps flexible display fabrication, rigid instrument panel supply, exterior lighting module integration, and transparent HUD development, each validated through primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, phosphorescent emitter material chemists, and aftermarket fleet operators. Secondary validation draws from vehicle production databases, IHS Markit registration data, SEC filings of listed display fabricators, and customs records of organic compound trade flows. Bottom-up segment sizing triangulates against top-down OEM procurement budget analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from fitted growth curves applied to technology penetration rates and OEM platform launch schedules. Forecast inputs include phosphorescent OLED external quantum efficiency improvement trajectories and thin-film encapsulation cost reduction curves.
Material uncertainties — regulatory convergence between automotive functional-safety mandates and consumer-electronics display standards, phosphorescent emitter supply disruption, and thermal degradation limit breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and OEM platform electrification commitments. Practitioners should keep alternative scenarios live as EU energy-efficiency mandate enforcement intensity and IRA domestic content rule interpretations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Steer-By-Wire and Brake-By-Wire HMI Controller Systems Market
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market