
 North America Connected Car Market | 2026-2036
North America Connected Car Market Size, Share, and Industry Trends Forecast 2026-2036
North America Connected Car Market Outlook
FCC Part 90 rules governing the 5.9 GHz safety band is hardening the compliance burden for new entrants while favoring incumbents with established certification pipelines. General Motors leverages its proprietary Ultifi software platform to sustain deep integration between vehicle hardware and cloud services. Ford Motor Company anchors its connected strategy through BlueCruise and Ford Pro telematics, competing directly in fleet-centric segments. Tesla Inc. dominates over-the-air update architecture, differentiating through continuous feature deployment without dealer intervention.
A connected car integrates embedded cellular modems, onboard computing platforms, and external communication interfaces to enable real-time data exchange between vehicles, infrastructure, and cloud services. These systems typically operate on 4G LTE or 5G networks with edge computing nodes processing sensor inputs at sub-100 millisecond latency for safety-critical functions. Infotainment Systems and Advanced Driver Assistance Systems represent the most mature revenue pools, while V2X Communication emerges as the fastest-growing technology dimension as municipalities deploy roadside units. Cloud Computing underpins the shift toward subscription-based Connected Vehicle Services, where OEMs retain ongoing revenue relationships beyond initial vehicle sale.
NHTSA crashworthiness standards and EPA emissions monitoring mandates both require robust telematics data logging, creating dual regulatory pull for onboard connectivity hardware. The FCC's C-V2X spectrum framework and NHTSA's anticipated vehicle-to-everything rulemaking will determine which communication protocols achieve scale deployment across US and Canadian road networks. Stakeholders must monitor whether federal infrastructure spending prioritizes DSRC legacy systems or accelerates C-V2X-exclusive buildouts, as this choice will lock in technology winners for a decade-long equipment cycle.
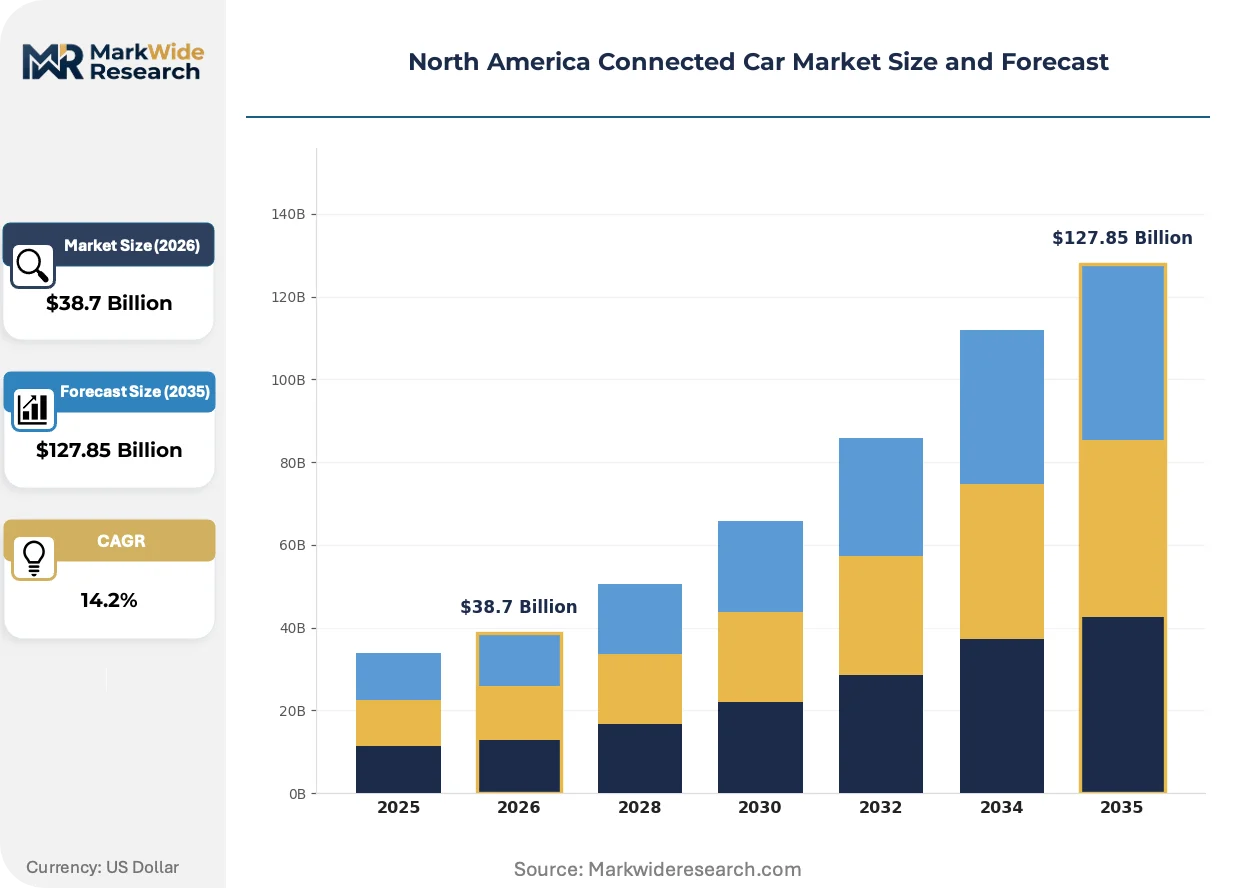
Market Dynamics
The FCC's 5.9 GHz spectrum reallocation for C-V2X communication is compressing deployment timelines and forcing OEMs to abandon DSRC legacy investments mid-cycle. This regulatory pivot is redistributing competitive advantage toward suppliers with established cellular certification pipelines and cloud-native architectures.
Growth Catalysts
- FCC C-V2X Framework:The commission's 2020 rulemaking reserving the upper 30 MHz of the 5.9 GHz band for cellular vehicle-to-everything protocols creates immediate regulatory pull for modem hardware upgrades across US and Canadian fleets.
- Predictive Maintenance Platforms:Fleet operators in the Great Lakes automotive corridor spanning Michigan and Ontario are mandating real-time engine diagnostics and brake-wear monitoring to minimize downtime across Class 8 truck deployments.
- Edge Computing Nodes:Sub-100 millisecond latency requirements for automatic emergency braking are driving integration of roadside unit networks with onboard sensor fusion processors.
Market Restraints
- Semiconductor Supply Concentration:Advanced driver assistance system chipsets depend on Taiwan-based foundry capacity, exposing Tier 1 suppliers to 18-24 month allocation queues for automotive-grade silicon.
- DSRC Stranded Assets:Municipalities that deployed dedicated short-range communication roadside units before 2020 face write-down pressures as C-V2X becomes the sole federally backed protocol.
- Cellular Modem Cost Structure:5G NR automotive modules carry 40% premium over 4G LTE equivalents, compressing margin for entry-segment vehicle lines where connectivity is standard equipment.
Strategic Opportunities
- Subscription Service Unbundling:OEMs are experimenting with à-la-carte connected vehicle feature activation, allowing owners to purchase enhanced navigation or remote climate control post-purchase through over-the-air commerce portals.
- Insurance Telematics Integration:Usage-based coverage models in Ontario and California are creating data monetization partnerships between automakers and property-casualty carriers.
- Commercial Fleet Electrification:Battery electric vehicle deployments require fundamentally different predictive maintenance algorithms, opening white space for software vendors specializing in state-of-charge optimization and thermal runaway detection.
Industry Challenges
- Embedded Systems Security Certification:ISO/SAE 21434 cybersecurity management standards impose 14-18 month validation timelines for new connected platforms, compressing model-year refresh cycles.
- Cross-Border Data Governance:Divergent privacy frameworks between US state laws and Canada's PIPEDA create compliance fragmentation for vehicles operating across the Detroit-Windsor corridor and other binational logistics routes.
- Legacy Architecture Integration:Controller area network buses in existing vehicle platforms lack bandwidth for 5G modem throughput, forcing expensive gateway redesigns for model-year carryover programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Connected Car Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infotainment Systems, Telematics, Advanced Driver Assistance Systems, Connected Vehicle Services Technology: V2X Communication, Cloud Computing, 5G Connectivity, Edge Computing End User: OEMs, Fleet Operators, Insurance Companies, Aftermarket Providers Application: Navigation, Remote Diagnostics, Safety Features, Entertainment Services |
| Companies Covered | General Motors, Ford Motor Company, Tesla Inc., AT&T, Aptiv, Apple Inc., Alphabet Inc., NXP Semiconductors, Audi AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Connected Car Market Strategic Shifts
Software-defined vehicle architectures are decoupling hardware release cycles from feature deployment, enabling continuous monetization through over-the-air updates. This shift is compressing traditional Tier 1 supplier roles while elevating cloud service providers into direct OEM partnerships.
Multi-access edge computing infrastructure is absorbing safety-critical workloads that previously required onboard supercomputing. Municipalities in Michigan and Texas are deploying roadside units with GPU clusters to process lidar fusion for intersection collision avoidance. Fleet operators are adopting this architecture to reduce per-vehicle silicon costs while maintaining sub-50 millisecond response times for vulnerable road user detection.
NHTSA's anticipated vehicle-to-everything rulemaking is forcing protocol standardization across state departments of transportation. The agency's pending mandate will require all new light vehicles to transmit basic safety messages using C-V2X by 2029, accelerating roadside unit procurement by the Federal Highway Administration. Canadian transport authorities are harmonizing with this framework through bilateral regulatory cooperation agreements.
After-sales service unbundling is displacing traditional dealer maintenance revenue with direct-to-consumer software subscriptions. Owners in California and Ontario are purchasing remote diagnostics and predictive maintenance alerts through OEM mobile applications rather than scheduled dealership visits. This pattern is most visible in battery electric vehicle segments where powertrain service intervals have collapsed and software monetization must replace lost parts-and-labor income.
North America Connected Car Market Segmentation
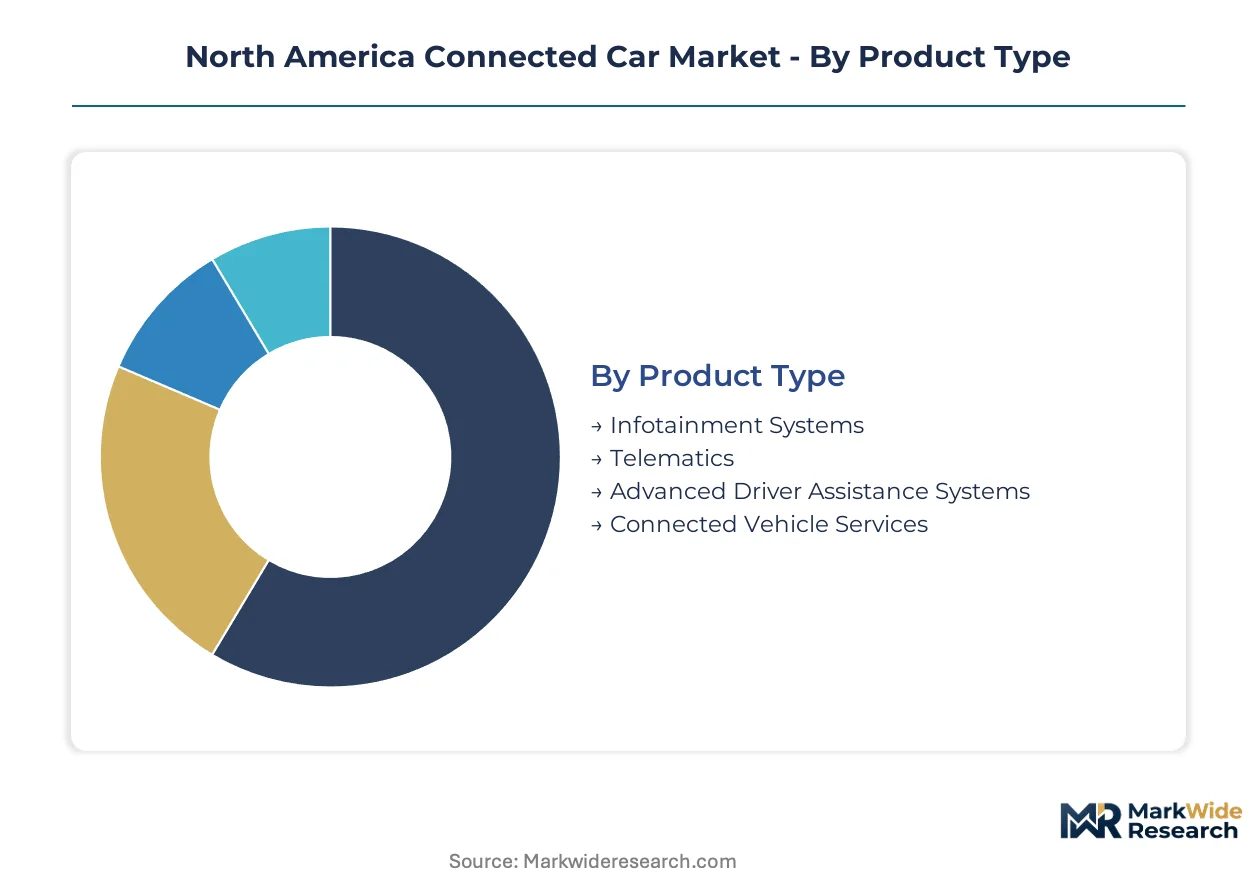
Segmentation in the North America Connected Car Market reveals how hardware, software, and service layers integrate at varying depths. Understanding these boundaries clarifies where OEMs retain control versus where third-party vendors penetrate the value chain.
Product Type:
Standalone infotainment head units contrast with deeply embedded telematics control units that interface directly with powertrain controllers.
- Infotainment Systems:Touchscreen interfaces integrate navigation, media streaming, and voice assistants through Android Automotive or proprietary operating systems. Demand concentrates in premium light-truck segments across Texas and California where large display real estate commands price premiums.
- Telematics:Embedded cellular modems transmit vehicle health data, location, and crash notifications to cloud platforms. Fleet operators in Michigan and Ontario mandate these units for real-time asset tracking and predictive maintenance scheduling.
- Advanced Driver Assistance Systems:Sensor fusion processors enable adaptive cruise control and lane-keeping assistance.
- Connected Vehicle Services:Subscription-based feature activation delivered through over-the-air software updates.
Infotainment Systems lead volumes today; Connected Vehicle Services is gaining share fastest.
Technology:
Cost tiers separate legacy 4G implementations from premium 5G deployments that enable high-definition map streaming and low-latency safety messaging.
- V2X Communication:Cellular vehicle-to-everything protocols operating in the upper 30 MHz of the 5.9 GHz band enable direct vehicle-to-vehicle and vehicle-to-infrastructure messaging. NHTSA's anticipated mandate is accelerating roadside unit deployment across Michigan and Texas DOT networks.
- Cloud Computing:Distributed data centers process telematics streams and enable over-the-air feature deployment. OEMs in the Great Lakes corridor leverage these platforms to sustain recurring revenue relationships beyond initial vehicle sale.
- 5G Connectivity:New radio automotive modules support ultra-reliable low-latency communication for autonomous driving functions.
- Edge Computing:Roadside GPU clusters process sensor fusion locally to reduce onboard silicon costs.
V2X Communication leads volumes today; Edge Computing is expanding most quickly.
End User:
Customer type determines procurement scale and data ownership structures, from single-vehicle consumers to thousand-unit fleet managers.
- OEMs:Vehicle manufacturers integrate connectivity hardware during assembly and control software update distribution. Ford and General Motors in Detroit anchor demand through proprietary platforms that bundle telematics with infotainment.
- Fleet Operators:Commercial vehicle managers across the US-Canada border corridor mandate real-time diagnostics and route optimization. These buyers prioritize total cost of ownership metrics over upfront hardware expense.
- Insurance Companies:Property-casualty carriers in Ontario and California purchase driving behavior data for usage-based pricing models.
- Aftermarket Providers:Third-party installers retrofit connectivity hardware to legacy vehicle fleets.
OEMs lead volumes today; Fleet Operators are climbing the fastest.
Application:
Maturity curves separate established navigation services from emerging safety features that depend on municipal infrastructure deployment.
- Navigation:Real-time traffic routing and high-definition mapping services delivered through cloud-connected head units. Consumer demand remains concentrated in urban California and Northeast corridor markets where congestion drives subscription renewal.
- Remote Diagnostics:Predictive algorithms analyze powertrain and brake system telemetry to flag maintenance needs before failure. Fleet operators in Ontario and Michigan prioritize these capabilities to minimize Class 8 truck downtime.
- Safety Features:Automatic emergency braking and intersection collision warnings enabled by V2X communication.
- Entertainment Services:Streaming media and gaming applications delivered to passenger displays.
Navigation leads volumes today; Safety Features are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American connected car industry traces its commercial origins to Detroit's post-restructuring technology investments during the 2010s, when automakers began embedding cellular modems as standard equipment rather than dealer-installed accessories.
United States
Fleet operators in Michigan and Texas are mandating real-time diagnostics for Class 8 trucks to minimize downtime across interstate logistics routes. The FCC's C-V2X spectrum framework in the upper 30 MHz of 5.9 GHz is accelerating modem hardware upgrades nationwide. The Great Lakes automotive manufacturing corridor spanning Detroit and surrounding counties anchors embedded telematics production for domestic OEM platforms.
Canada
Commercial vehicle managers in Ontario are prioritizing predictive maintenance platforms to optimize cross-border freight movements through the Detroit-Windsor corridor. Transport Canada harmonizes with NHTSA's anticipated V2X mandate through bilateral regulatory cooperation agreements. The Toronto-Waterloo technology cluster hosts software vendors specializing in usage-based insurance telematics for property-casualty carriers.
Mexico
Export-oriented assembly plants in Nuevo León and the Bajío Region are integrating connectivity hardware to meet US homologation requirements for vehicles shipped north. The country's automotive regulator aligns certification timelines with EPA emissions monitoring mandates that require robust telematics data logging. Querétaro's electronics manufacturing hub supplies Tier 2 connectivity modules to major assembly operations across the central plateau.
North America Connected Car Market Competitive Environment
The competitive structure tilts toward vertically integrated OEMs with proprietary software platforms and cloud-native architectures. The vendor base separates into three distinct tiers: established Detroit manufacturers controlling end-to-end vehicle integration, cellular carriers managing data transmission infrastructure, and semiconductor specialists supplying modem chipsets. Strategic moves concentrate on spectrum certification pipelines and over-the-air update capabilities that sustain recurring revenue relationships beyond initial vehicle sale.
Within the integrated OEM tier, General Motors and Ford Motor Company exemplify the vertically integrated archetype with captive telematics platforms, while Tesla Inc. occupies a distinct position through its software-first architecture and direct-to-consumer distribution model. AT&T represents the carrier archetype, anchoring connectivity service provision across multiple OEM brands rather than single-manufacturer ecosystems.
| Leading Market Players |
|---|
| General Motors |
| Ford Motor Company |
| Tesla Inc. |
| AT&T |
| Aptiv |
| Apple Inc. |
| Alphabet Inc. |
| NXP Semiconductors |
| Audi AG |
| Others |
Value Chain & Pricing Dynamics
Cellular modem certification tiers split the North America connected car market into sharply divergent cost structures, with FCC Part 90 compliance pipelines concentrating pricing power among incumbents while forcing new entrants into extended validation timelines that reshape supplier selection and component sourcing geography. This bifurcation manifests in procurement patterns where premium 5G modules command sustained margin premiums against commoditized 4G alternatives, and where supply chain configuration favors vertically integrated OEMs with captive certification resources.
Pricing Analysis
Bundled hardware-software packages dominate fleet procurement, while unbundled subscription services gain traction in consumer segments. Three-tier pricing structure across premium 5G, standard 4G, and economy legacy tiers reflects certification grade and volume scale differentials. Cost compression in entry-segment vehicle lines intensifies because 5G NR automotive modules carry substantial premiums over LTE equivalents. Fleet operators in Michigan and Ontario exhibit lowest price sensitivity due to total cost of ownership focus, while aftermarket retrofit buyers face acute margin pressure.
Supply Chain Analysis
Domestic-content mandates under USMCA rules of origin reshape sourcing patterns for telematics control units and modem chipsets. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, while final assembly of automotive-grade modules clusters in Mexico and the American Midwest. Advanced driver assistance system processors draw from Taiwan-based foundry capacity, creating single-source vulnerability for Tier 1 suppliers facing 18-24 month allocation queues. Distribution runs through captive OEM supply chains and independent aftermarket channels serving legacy fleet retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America connected car market functions as a regulatory compounder where NHTSA's anticipated C-V2X mandate accelerates hardware replacement cycles and locks in technology winners across a decade-long equipment horizon.
For Market Incumbents: To counter semiconductor supply concentration threatening production schedules, General Motors and Ford should deepen backward integration into modem chipset design while expanding captive cloud-native architecture development. Certification investment in FCC Part 90 pipelines represents the critical defensive lever, with channel control over dealership service networks sustaining aftermarket revenue displacement.
For New Entrants and Emerging Players: Direct-to-consumer software subscription portals offer the most penetrable entry vector, particularly in battery electric vehicle segments where powertrain service intervals have collapsed and owners purchase predictive maintenance alerts through OEM mobile applications. White space concentrates in commercial fleet electrification software, where state-of-charge optimization algorithms for Class 8 trucks remain underdeveloped.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO/SAE 21434 cybersecurity validation timelines compress model-year refresh cycles and strand smaller suppliers without compliance resources. Long-term viability favors targets with established cellular certification pipelines and cloud-native vehicle architectures. The signal to monitor is FCC infrastructure spending allocation between DSRC legacy systems and C-V2X-exclusive buildouts.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Decouples hardware release cycles from feature deployment, enabling continuous monetization through over-the-air updates. |
| C-V2X Spectrum Certification Pipeline | Secures regulatory approval for 5.9 GHz safety band operation ahead of NHTSA mandate implementation. |
| Edge Computing Infrastructure Partnership | Reduces per-vehicle silicon costs while maintaining sub-50 millisecond response times for safety-critical functions. |
| Telematics Data Monetization Agreement | Creates recurring revenue streams through usage-based insurance partnerships with property-casualty carriers in Ontario and California. |
| Cross-Border Data Governance Compliance | Resolves fragmentation between US state privacy laws and Canada's PIPEDA framework for binational logistics routes. |
Study Parameters
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers, and cellular carrier network planners grounded this analysis in operational reality. Secondary validation drew from NHTSA rulemaking dockets, FCC spectrum allocation records, vehicle production databases, and SEC filings from publicly traded automotive technology suppliers. Bottom-up and top-down triangulation reconciled component-level cost structures with aggregate market value estimates.
Bottom-up modeling of content per vehicle across propulsion architectures and OEM tiers anchored volume projections, while top-down expenditure analysis from fleet operator budgets and infrastructure spending programs cross-checked value estimates. Segmentation dimensions included vehicle class, connectivity technology generation, end-user type, and application maturity. CAGRs were derived from installed base growth rates and replacement cycle compression under regulatory mandate timelines, with sensitivity analysis around semiconductor supply recovery trajectories.
The model assumes a particular technology adoption path; alternative pathways for DSRC-to-C-V2X transition timing would alter the outlook for roadside unit deployment and modem hardware demand. Forecasts reflect assumptions regarding regulatory harmonization between US and Canadian transport authorities, with cross-border data governance friction and semiconductor allocation bottlenecks representing primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Electric and Autonomous Vehicles Wiring Harness Market
Automotive Electronics & Wiring
North America Automotive Steering Sensor Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Mlccs for Automotive Electronics Market
Automotive Electronics & Wiring
Wire Protection and Routing Component Systems for Vehicles Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market