
 Instrument Cluster Market | 2026-2036
Instrument Cluster Market Size, Share, and Industry Trends Forecast 2026-2036
Instrument Cluster Market Intelligence
Software-defined instrumentation is reconfiguring how vehicle data reaches drivers, replacing mechanical gauges with reconfigurable digital surfaces. Continental AG leverages deep electronics integration to sustain leadership in premium cockpit systems. Robert Bosch GmbH anchors its position through manufacturing scale across European and Asian assembly corridors. Nippon Seiki Co. Ltd. specializes in high-precision analog-to-digital transitions for motorcycle and compact vehicle applications.
An instrument cluster constitutes the driver's primary information interface, integrating speedometers, tachometers, fuel gauges, and warning indicators through electromechanical or fully electronic display architectures with resolution thresholds reaching 1920x720 pixels in current TFT LCD implementations. Its commercial purpose centers on delivering real-time vehicle telemetry while satisfying safety-critical visibility standards under variable ambient lighting. TFT LCD technology dominates current OEM fitments due to cost-scalability and proven thermal resilience, while OLED displays represent the fastest-growing display type as automakers pursue deeper contrast ratios and curved surface integration. The passenger vehicle application segment commands the largest volume commitment, though heavy machinery applications retain distinct margin pools given certification complexity and aftermarket replacement cycles.
The EPA enforces emissions-related onboard diagnostic display requirements that shape cluster information architecture in the United States, while ECE R121 standardizes tell-tale symbols across European type approvals and China's GB standards govern electromagnetic compatibility for electronic display modules. OEM procurement teams must weigh semiconductor supply continuity against display technology roadmaps as stakeholder planning priorities.
Market Dynamics
Software-defined instrumentation is collapsing the traditional hardware-software boundary in vehicle cockpits, forcing suppliers to restructure engineering organizations around continuous deployment models rather than static platform cycles.
Growth Catalysts
- China's GB electromagnetic compatibility standards:Domestic EV manufacturers accelerate local sourcing of compliant display modules, building captive supply chains that bypass import dependencies.
- Heavy machinery certification complexity:Specialized safety requirements for construction and agricultural equipment create durable margin pools for suppliers mastering ISO 15006 ergonomic standards.
- Curved surface integration:Automotive OEMs demand flexible display architectures enabling seamless dashboard curvature, pulling investment toward OLED and mini-LED backlighting technologies.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate driver IC fabrication, exposing cluster manufacturers to single-source vulnerability for high-resolution timing controllers.
- Thermal management costs:Extended operating temperature requirements for engine-bay proximity installations inflate bill-of-materials for heavy-duty applications.
- Mechanical gauge substitution ceiling:Budget motorcycle and commercial vehicle segments in Southeast Asia retain analog instrumentation due to repair infrastructure and operator familiarity.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Component manufacturers establishing local assembly gain tariff advantages serving Maruti Suzuki and Tata Motors' expanding domestic EV portfolios.
- Aftermarket retrofit channels:Aging commercial fleets in Brazil and Mexico create demand for digital cluster upgrades compatible with legacy CAN bus architectures.
- Head-up display convergence:Windshield projection systems merging with instrument cluster data streams enable new subscription-based feature monetization models.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-B compliance for safety-critical warning displays extends development cycles by 14-18 months.
- Legacy vehicle integration friction:Retrofitting digital clusters into platforms with analog sensor outputs requires signal conditioning hardware that erodes margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instrument Cluster Market |
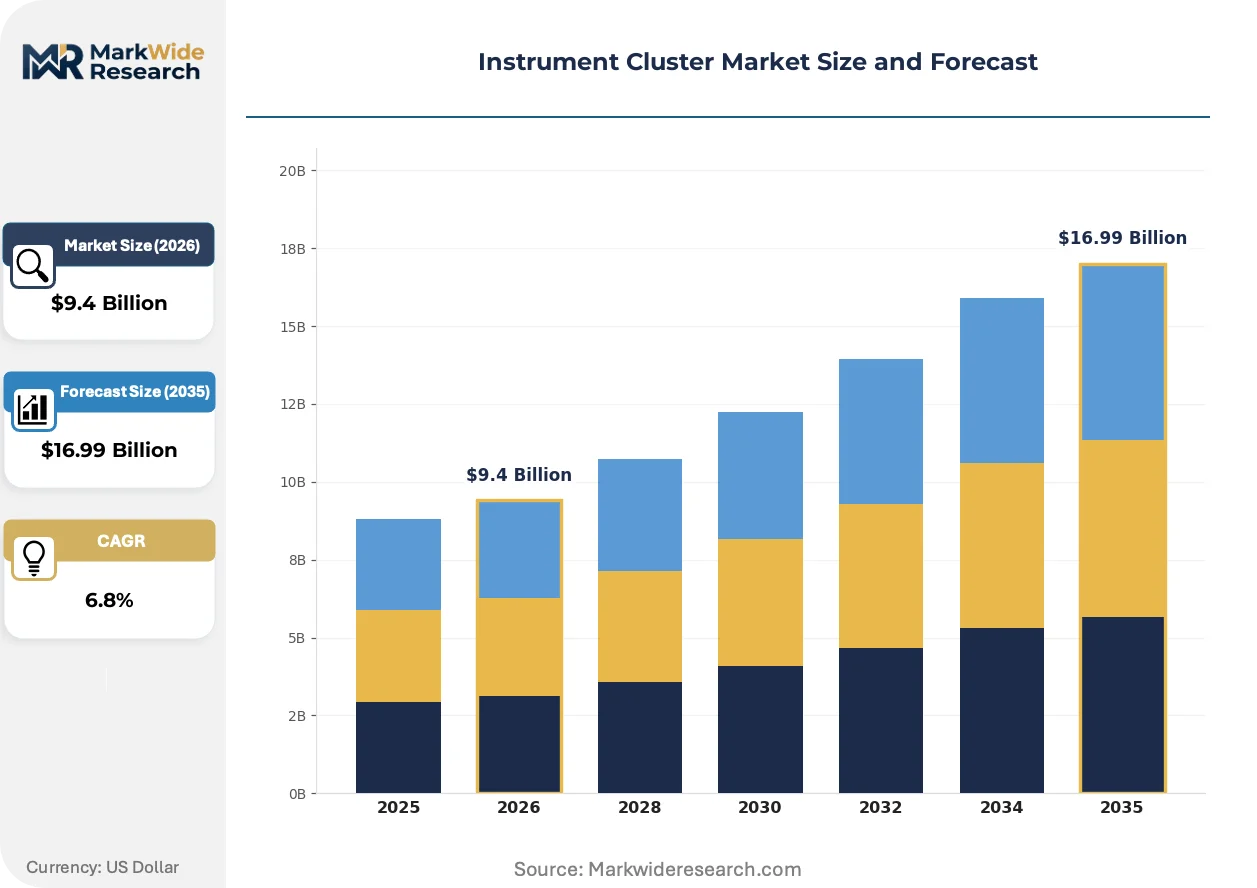
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Analog, Digital, Hybrid, TFT LCD, OLED Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Dealerships Display Type: Monochrome, Color, Touchscreen, Heads-Up Display, 3D Display |
| Companies Covered | Nippon Seiki Co. Ltd., Yazaki Corporation, Continental AG, Hyundai Mobis Co., Ltd., Panasonic Automotive Systems Co., Ltd., Visteon Corporation, Robert Bosch GmbH, Aptiv plc, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instrument Cluster Market Strategic Shifts & Innovations
Active matrix display technologies are restructuring supplier value capture, compressing hardware margins while expanding software and calibration service revenues across tiered automotive programs.
Mini-LED backlighting arrays are collapsing the cost-performance tradeoff that previously favored edge-lit TFT LCD in mid-market vehicles. Premium German OEMs have adopted full-array local dimming for 2024 model year flagship platforms. The technology is collapsing differentiation between luxury and mass-market cluster specifications, forcing suppliers to compete on software integration depth rather than display hardware alone.
Europe's ECE R121 revision mandating standardized tell-tale symbols for advanced driver assistance states is harmonizing warning iconography across 27 national type approval regimes. Component suppliers must revalidate existing graphics libraries against the updated symbol set. Aftermarket cluster manufacturers serving Eastern European independent repair networks face the steepest compliance recertification burden.
Fleet operators are unbundling cluster specification from vehicle platform procurement, negotiating direct supply agreements with tier-one cockpit integrators for standardized telematics-ready configurations. This disintermediation is visible most acutely in North American long-haul trucking, where Werner Enterprises and Schneider National have established preferred supplier frameworks bypassing traditional OEM captive sourcing. The practice compresses specification variation while concentrating purchasing leverage with logistics operators rather than vehicle assemblers.
Instrument Cluster Market Segmentation
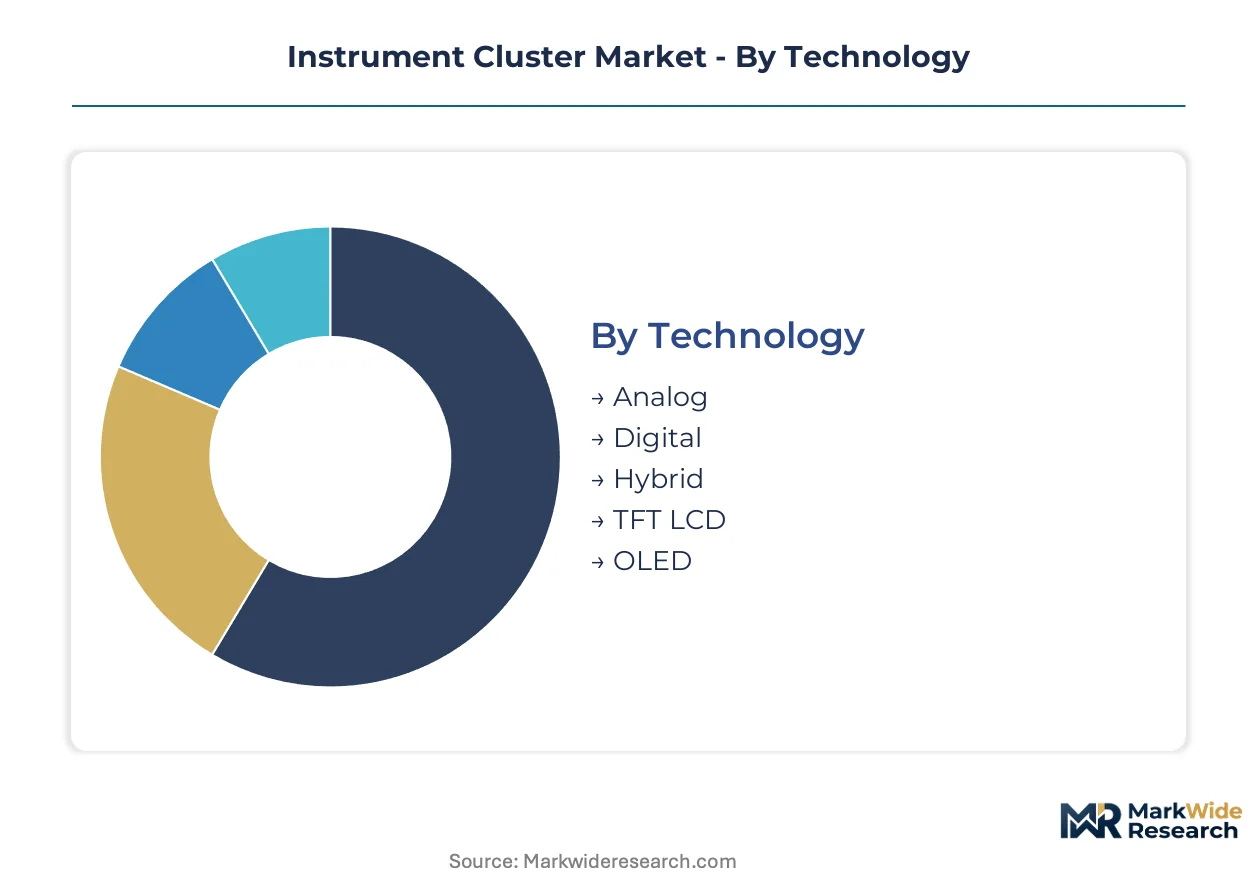
Technology and application boundaries in instrument clusters are dissolving as software-defined architectures enable single hardware platforms to serve multiple vehicle categories. Display specifications now drive procurement decisions more than mechanical gauge heritage, reshaping how suppliers organize their product portfolios and pricing structures.
Technology:
Mature electromechanical formats coexist with emerging solid-state display technologies across a fragmented supplier landscape.
- TFT LCD:Thin-film transistor active matrix backplanes deliver 1920x720 resolution at operating temperatures spanning -40°C to 85°C. Chinese EV manufacturers dominate procurement volumes as domestic panel fabs achieve cost parity with Korean suppliers.
- OLED:Organic light-emitting diode stacks eliminate backlight assemblies, enabling curved surface integration and infinite contrast ratios. German premium OEMs specify full-array implementations for flagship sedan platforms, absorbing yield-related cost premiums.
- Hybrid:Combines analog gauge aesthetics with digital information zones for transitional vehicle architectures. Japanese motorcycle OEMs favor this format for heritage model lines where rider familiarity overrides full digitization.
- Analog:Mechanical stepper motor-driven needles persist in budget commercial vehicles and emerging market two-wheelers. Repair infrastructure and operator training gaps sustain demand despite declining fitment rates.
- Digital:Fully reconfigurable pixel-based displays without physical gauge elements. Heavy machinery OEMs specify these for programmable warning hierarchies under ISO 15006 ergonomic mandates.
TFT LCD handles the majority of throughput; OLED is climbing the fastest on share as curved dashboard architectures proliferate.
Application:
Volume concentration and margin structure diverge sharply across vehicle categories with distinct certification burdens and replacement cycles.
- Passenger Vehicles:Cockpit integration complexity drives tier-one supplier consolidation. European type approvals under ECE R121 mandate standardized tell-tale symbol libraries that increase software validation costs.
- Heavy Machinery:Construction and agricultural equipment demand vibration-resistant enclosures and extended temperature specifications. ISO 15006 compliance creates durable margin pools through specialized engineering capabilities.
- Commercial Vehicles:Fleet operators negotiate direct supply agreements bypassing OEM captive sourcing. North American long-haul trucking concentrates purchasing leverage with logistics operators rather than vehicle assemblers.
- Two-Wheelers:Compact form factors and cost constraints favor simplified display architectures. Southeast Asian markets retain analog instrumentation where repair infrastructure supports mechanical gauge servicing.
- Specialty Vehicles:Military, emergency services, and recreational applications require customized information hierarchies. Low volumes preclude platform economics, sustaining premium pricing for specialized integrators.
Passenger vehicles absorb the dominant share of production capacity; heavy machinery offers the steepest margin premiums per unit.
End User:
Procurement authority is shifting downstream as fleet operators and aftermarket channels gain specification influence.
- OEMs:Vehicle manufacturers define cluster architecture for new platform development. Software-defined instrumentation enables over-the-air feature activation, creating recurring revenue streams from hardware already installed.
- Tier-1 Suppliers:Cockpit integrators consolidate display, HUD, and infotainment system procurement. Continental AG and Robert Bosch GmbH leverage electronics integration depth to capture value migrating from hardware to software services.
- Aftermarket Providers:Digital cluster retrofits for aging commercial fleets drive demand in Brazil and Mexico. Legacy CAN bus compatibility requirements constrain design flexibility and erode margin through signal conditioning hardware.
- Vehicle Assemblers:Contract manufacturers serving emerging market OEMs source pre-validated cluster modules. India's PLI scheme for automotive electronics incentivizes local assembly for Maruti Suzuki and Tata Motors.
- Dealerships:Service channels generate replacement demand for damaged or obsolete clusters. Warranty cost pressures push OEMs toward modular designs with field-replaceable display subassemblies.
OEMs retain architecture control for new platforms; aftermarket providers are expanding most quickly as fleet retrofit cycles accelerate.
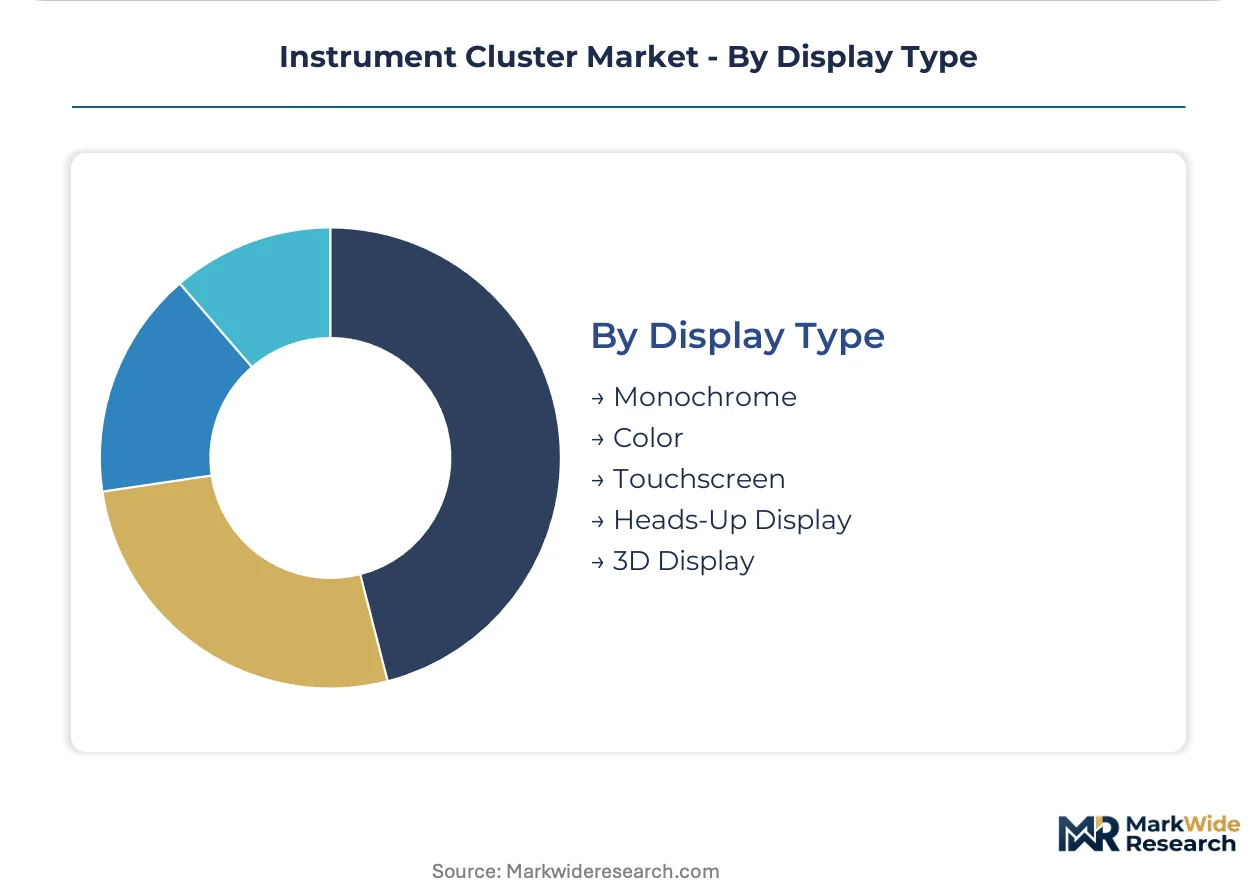
Display Type:
Color depth and interaction modality define tiered pricing structures across automotive programs.
- Color:Full RGB subpixel arrays enable warning state differentiation and brand-aligned aesthetic customization. Standard fitment for passenger vehicles above economy trim levels.
- Touchscreen:Capacitive sensing layers integrate control surfaces with information displays. Premium German OEMs specify these for center console convergence with instrument cluster data streams.
- Heads-Up Display:Windshield projection systems merge telemetry with driver forward vision. Subscription-based feature monetization models are emerging as software-defined architectures enable post-sale capability activation.
- Monochrome:Single-color passive matrix LCDs persist in cost-constrained commercial vehicle applications. Sufficient for regulatory minimum information display without aesthetic differentiation.
- 3D Display:Autostereoscopic surfaces create depth perception without wearable optics. Limited production volumes due to viewing angle constraints and driver fatigue concerns under extended use.
Color displays command the dominant installation base; heads-up display integration is gaining share fastest as windshield projection technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tier-one suppliers export cockpit integration systems to Chinese EV manufacturers, establishing the dominant trade corridor in instrument cluster procurement. This cross-border flow concentrates advanced display technology transfer while localizing final assembly under China's GB electromagnetic compatibility standards.
China
Domestic EV manufacturers BYD and NIO drive procurement volumes for 1920x720 resolution TFT LCD modules. MIIT enforces GB standards for electromagnetic compatibility in electronic display modules. Panel fabs in Hefei and Wuhan achieve cost parity with Korean suppliers, building captive supply chains that bypass import dependencies for driver ICs.
Germany
Premium OEMs BMW and Mercedes-Benz specify full-array mini-LED backlighting for flagship sedan platforms. KBA administers ECE R121 type approvals mandating standardized tell-tale symbols for advanced driver assistance states. Stuttgart and Ingolstadt industrial clusters concentrate cockpit integration engineering for curved OLED surface architectures.
United States
Fleet operators Werner Enterprises and Schneider National negotiate direct supply agreements bypassing OEM captive sourcing. EPA enforces emissions-related onboard diagnostic display requirements shaping cluster information architecture. Michigan and Ohio assembly corridors anchor North American production for heavy-duty commercial vehicle applications.
Japan
Motorcycle OEMs Yamaha and Honda favor hybrid analog-digital formats for heritage model lines. METI oversees JIS standards for automotive electronics reliability. Hamamatsu and Tokyo-Yokohama manufacturing belts specialize in high-precision analog-to-digital transitions for compact vehicle instrument clusters.
India
Maruti Suzuki and Tata Motors expand domestic EV portfolios requiring locally assembled display modules. PLI scheme for automotive electronics incentivizes component manufacturers establishing local assembly. Tamil Nadu and Gujarat industrial corridors attract tier-one cockpit integrators seeking tariff advantages.
Instrument Cluster Market Key Industry Players
On the supply side, the industry is consolidating around tier-one cockpit integrators with deep electronics integration capabilities. Continental AG and Robert Bosch GmbH anchor European supply positions while Asian specialists concentrate on cost-optimized module fabrication. Three strategic archetypes dominate: full-system integrators owning software-defined architectures, display panel specialists controlling backlighting technology transitions, and regional assemblers serving emerging market OEMs through localized content requirements. Competitive moves center on strategic partnerships for semiconductor supply continuity and portfolio diversification into head-up display convergence.
Among German-based full-system integrators, Continental AG and Robert Bosch GmbH exemplify the electronics integration archetype, occupying positions where software services capture value migrating from hardware. Japanese specialists Nippon Seiki Co. Ltd. and Yazaki Corporation represent the precision-transition segment, anchoring supply for motorcycle and compact vehicle applications where analog-to-digital migration requires ergonomic continuity. These named entities sit within a competitive structure where geographic origin correlates with technology specialization—European entities dominate premium cockpit systems, Japanese entities concentrate on two-wheeler and heritage automotive formats, and Korean entities supply display panel backplanes at scale.
| Leading Market Players |
|---|
| Nippon Seiki Co. Ltd. |
| Yazaki Corporation |
| Continental AG |
| Hyundai Mobis Co., Ltd. |
| Panasonic Automotive Systems Co., Ltd. |
| Visteon Corporation |
| Robert Bosch GmbH |
| Aptiv plc |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese TFT LCD panel fabs is compressing module pricing while simultaneously accelerating supplier consolidation around electronics-integrated tier-one integrators. This utilization dynamic rewards manufacturers with captive semiconductor sourcing and software calibration capabilities, while squeezing pure-play display assemblers unable to offset hardware margin erosion with service revenues.
Pricing Analysis
The technology-generation pricing gap between edge-lit TFT LCD, full-array mini-LED, and curved OLED implementations stratifies procurement tiers across passenger vehicle programs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ISO 26262 ASIL-B functional safety mandates and volume scale commitments from fleet operators. Cost compression in mid-market TFT LCD modules is intensifying because Chinese domestic panel production has achieved cost parity with Korean suppliers. Fleet operators negotiating direct supply agreements exhibit the highest price sensitivity, while German premium OEMs specifying full-array OLED implementations demonstrate the lowest sensitivity due to brand positioning requirements.
Supply Chain Analysis
Export-control regimes limiting advanced semiconductor lithography equipment flows to Chinese fabs are constraining domestic driver IC production scaling despite mature TFT LCD backplane capabilities. Geographic supply concentration centers on Taiwan and South Korea for high-resolution timing controllers, China for TFT LCD panel backplanes, and Germany for cockpit integration systems. Raw material dependencies include indium tin oxide for transparent electrodes, gallium nitride for mini-LED drivers, and specialized optical films for brightness enhancement. Single-source vulnerability for driver IC fabrication exposes cluster manufacturers to supply disruption. Distribution runs through tier-one cockpit integrators consolidating display, HUD, and infotainment procurement for OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering organizations capable of ISO 26262 functional safety certification represent the critical scarcity asset in this market, with ASIL-B validation timelines extending development cycles and consolidating procurement authority among tier-one integrators with established compliance infrastructure.
For Market Incumbents: Entrench electronics integration depth by acquiring specialized calibration service providers and expanding software-defined architecture capabilities to capture recurring revenue from over-the-air feature activation. Semiconductor supply continuity threats from Taiwan concentration require backward integration into driver IC sourcing or strategic partnerships with Korean alternative suppliers. Certification investment in ECE R121 symbol library revalidation creates switching costs that lock in European OEM relationships. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-incentivized automotive electronics assembly corridor, serving Maruti Suzuki and Tata Motors' expanding domestic EV portfolios with locally compliant display modules. Aftermarket retrofit channels for aging commercial fleets in Brazil and Mexico offer the most penetrable white-space target, with legacy CAN bus compatibility requirements favoring entrants with signal conditioning hardware expertise. Direct sales to fleet operators bypassing OEM captive sourcing represents the optimal go-to-market angle for volume scale. For Investors and Strategic Acquirers: Long-term, this sits as a software-services transition play because hardware margins are compressing toward commodity levels while calibration, validation, and over-the-air update capabilities concentrate value capture with integrators owning the full stack. Acquisition targets should display deep vertical integration into semiconductor sourcing paired with established functional safety certification infrastructure. The signal to watch is fleet operator procurement authority expansion, with direct supply agreements disintermediating traditional OEM channels indicating sustained margin migration toward logistics operators.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Supply Partnership | Taiwan and South Korea driver IC sourcing agreements secure timing controller continuity for high-resolution displays. |
| Software-Defined Architecture Investment | Reconfigurable digital surfaces enable subscription-based feature monetization from installed hardware base. |
| Functional Safety Certification Buildout | ISO 26262 ASIL-B compliance infrastructure extends development cycle lock-in with European premium OEMs. |
| Geographic Manufacturing Footprint Expansion | India PLI scheme assembly localization captures tariff advantages serving domestic EV manufacturer procurement. |
| Head-Up Display Convergence Development | Windshield projection integration merges telemetry streams enabling new cockpit data monetization models. |
Research Approach
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel managers, and fleet operator specification leads provided ongoing calibration throughout the research process. Primary interviews combined with secondary validation against vehicle production databases, IHS Markit registration data, customs and trade flow records, and semiconductor supply chain disclosures established demand-side and supply-side baselines. Bottom-up unit volume estimates triangulated against top-down market value assessments derived from tiered pricing structures across technology generations.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning display technology type, vehicle application category, propulsion architecture, and regional production cluster. CAGRs were derived from fitted growth curves incorporating technology substitution rates, regulatory compliance timeline impacts, and fleet replacement cycle dynamics. Industry-specific forecast inputs included EV production ramp schedules, ECE R121 revision implementation deadlines, and semiconductor fab capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor supply availability, or trade policy configurations would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory compliance timelines. Material shifts in functional safety certification requirements or fleet operator procurement authority consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Global Automotive Ethernet Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Automotive Data Cables Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
North America Automotive Smart Key Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market