
 Off-Highway Vehicle HVAC Market | 2026-2036
Off-Highway Vehicle HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Vehicle HVAC Market Analytics
Aftermarket service revenue is fragmenting across regional dealer networks and independent refurbishment shops as thermal system complexity outpaces field technician training pipelines. Denso Corporation leverages its compressor manufacturing scale to anchor captive supply relationships with Japanese construction equipment OEMs. MAHLE GmbH competes through R&D intensity in refrigerant migration solutions for compact engine bays. Bergstrom Inc. dominates North American aftermarket distribution through direct fleet operator channel control.
Off-highway vehicle HVAC systems regulate cabin temperature, air quality, and defrost performance in equipment operating across unimproved terrain, extreme ambient conditions, and continuous duty cycles exceeding sixteen hours; these systems typically integrate vapor-compression refrigeration cycles with hydronic or combustion heating elements, requiring sealed hose assemblies rated for vibration exposure beyond standard automotive specifications. Air conditioning product lines carry the deepest installed base and highest replacement part attach rates, while hybrid systems represent the fastest-growing technology segment as electrified auxiliary power units displace belt-driven compressor architectures. Agricultural machinery applications sustain above-average margin pools due to seasonal demand spikes and deferred maintenance patterns that concentrate aftermarket purchasing.
EPA Tier 4 Final and EU Stage V emissions standards have tightened engine compartment packaging constraints, forcing HVAC suppliers to certify compact heat exchanger designs under thermal load conditions that exceed prior regulatory baselines. ISO 16750-3 vibration testing and SAE J1455 environmental durability protocols govern product qualification for mining and forestry deployments, creating compliance barriers for unvalidated component sources. Stakeholders must monitor refrigerant transition timelines under the Kigali Amendment and assess manufacturing footprint exposure to regional carbon border adjustment mechanisms.
Market Dynamics
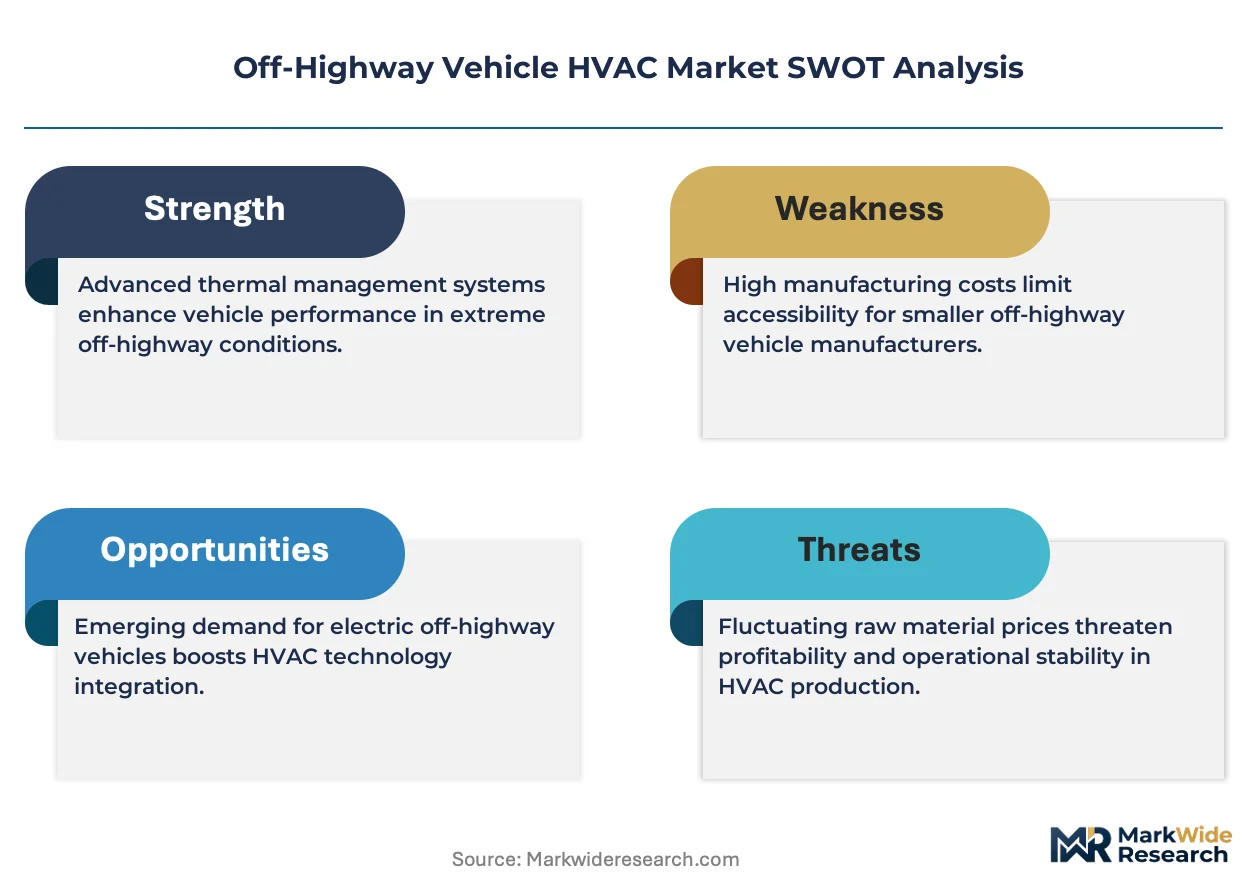
EPA Tier 4 Final and EU Stage V emissions standards have compressed engine compartment packaging space, forcing HVAC suppliers to miniaturize thermal components while maintaining performance under elevated thermal loads.
Growth Catalysts
- Underground Mining Depth Extension:Australian and Chilean mining operators are retrofitting climate-controlled cabs as extraction depths exceed 1,500 meters, where ambient rock temperatures surpass 40°C.
- Electrified Auxiliary Power Units:Belt-driven compressor architectures are giving way to electrified APUs that enable engine-off HVAC operation, reducing fuel burn during idle periods.
- Shandong-Jiangsu OEM Clustering:China's construction equipment manufacturing concentration in these provinces generates localized demand for integrated HVAC assemblies with shortened logistics loops.
Market Restraints
- Refrigerant Cost Volatility:R-1234yf and emerging low-GWP alternatives carry price premiums exceeding 300% versus legacy R-134a, squeezing margin pools on replacement cycles.
- Copper-Aluminum Alloy Supply Concentration:Heat exchanger manufacturers depend on specialized alloy suppliers concentrated in East Asian smelting corridors, exposing procurement to tariff and logistics disruptions.
- ISO 16750-3 Vibration Certification Barriers:Unvalidated component sources face exclusion from mining and forestry deployments where SAE J1455 durability protocols govern qualification.
Strategic Opportunities
- Indian Agricultural Mechanization:Tractor OEMs in Punjab and Haryana are specifying factory-fit HVAC as operator comfort becomes a competitive differentiator in land consolidation trends.
- Kigali Amendment Refrigerant Transition:HVAC suppliers can capture retrofit revenue streams by certifying HFO and natural refrigerant systems ahead of national phase-down mandates.
- Predictive Maintenance Integration:Sensor-embedded hose assemblies and compressor monitoring modules enable fleet operators to shift from scheduled to condition-based replacement.
Industry Challenges
- Thermal System Technician Scarcity:Field service networks lack sufficient trained personnel to diagnose integrated refrigerant-hydronic systems, lengthening downtime for mining fleets.
- Dual Certification Timeline Compression:Suppliers must simultaneously validate designs under EPA Tier 4 Final and EU Stage V thermal load conditions, extending product development cycles.
- Legacy Fleet Integration Complexity:Compact integrated HVAC units require structural cab modifications that conflict with warranty terms on equipment nearing end-of-design-life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Vehicle HVAC Market |
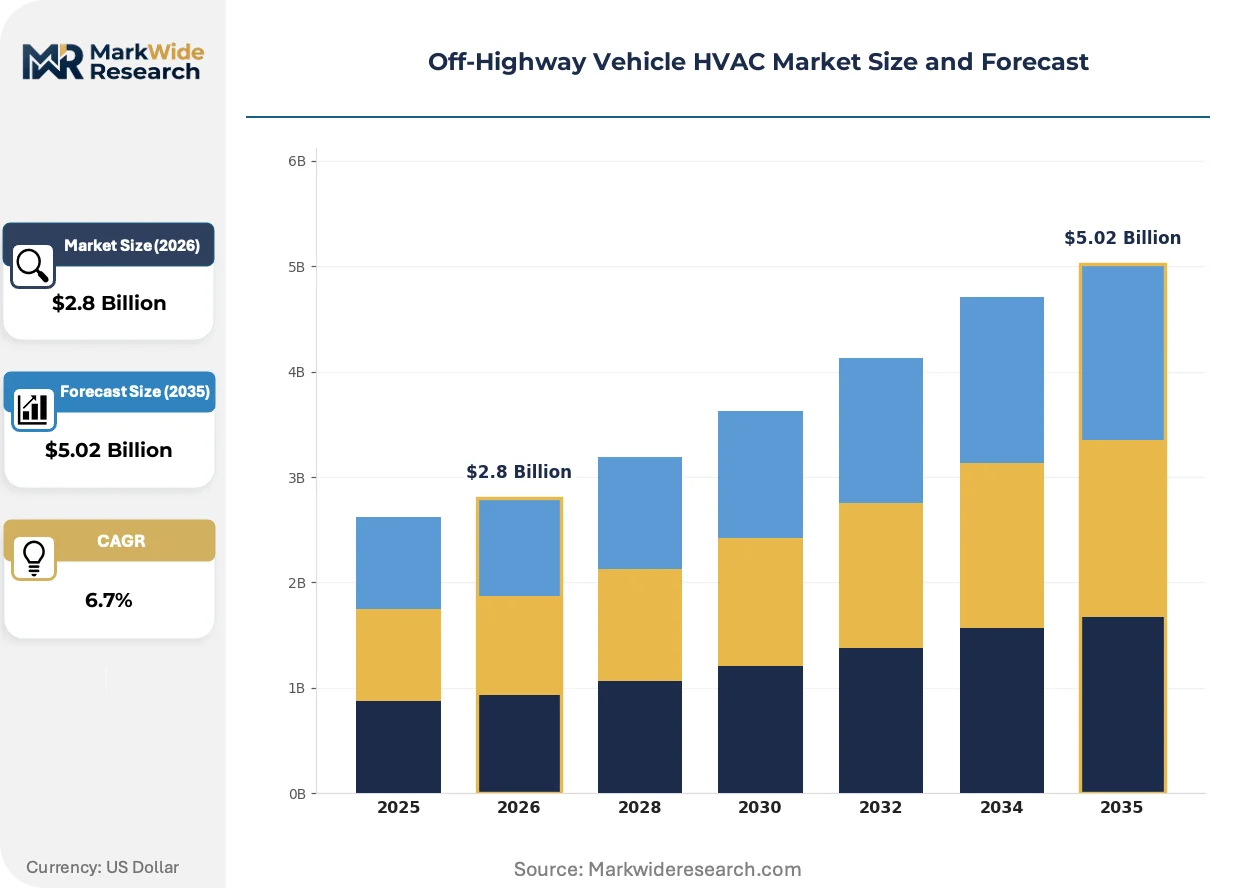
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioning, Heating System, Ventilation System, Cabin Filter Application: Agricultural Machinery, Construction Equipment, Mining Vehicles, Forestry Equipment End User: OEMs, Aftermarket, Fleet Operators, Distributors Technology: Refrigerant-Based, Evaporative Cooling, Thermoelectric, Hybrid Systems |
| Companies Covered | Mitsubishi Heavy Industries Ltd, S.E.A SRL, Denso Corporation, Hanon Systems, Marelli Corporation, MAHLE GmbH, Sanden Holdings Corporation, Bergstrom Inc., Webasto SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Vehicle HVAC Market Evolving Landscape
Digital integration is reshaping how thermal systems communicate with vehicle telematics, enabling real-time performance optimization and predictive fault detection across remote operations.
Smart compressor controllers are digitizing refrigerant flow management through variable-speed drive algorithms that match cooling output to cabin thermal load. Underground mining fleets in Australia are adopting these systems fastest, with operators reporting 15-20% fuel savings during continuous duty cycles. The technology is digitizing maintenance scheduling by transmitting vibration and temperature telemetry to centralized fleet management platforms.
The EU F-Gas Regulation is tightening refrigerant containment requirements and accelerating HFO adoption timelines for mobile equipment categories. HVAC suppliers must now certify systems under leak-tightness protocols that exceed prior automotive baselines, adding validation cost layers. Construction equipment deployed in Germany and France faces the most immediate compliance pressure, with OEMs pre-qualifying low-GWP refrigerant architectures for 2025 model year releases.
Fleet operators are unbundling aftermarket service contracts from OEM captive networks, creating openings for independent refurbishment shops with specialized thermal diagnostics capability. This disintermediation concentrates most visibly in North American construction and agricultural verticals, where direct procurement from component suppliers reduces parts markup by 30-40%. Channel restructuring forces HVAC manufacturers to develop dual-track distribution strategies serving both OEM assembly lines and independent installer networks.
Off-Highway Vehicle HVAC Market Segmentation
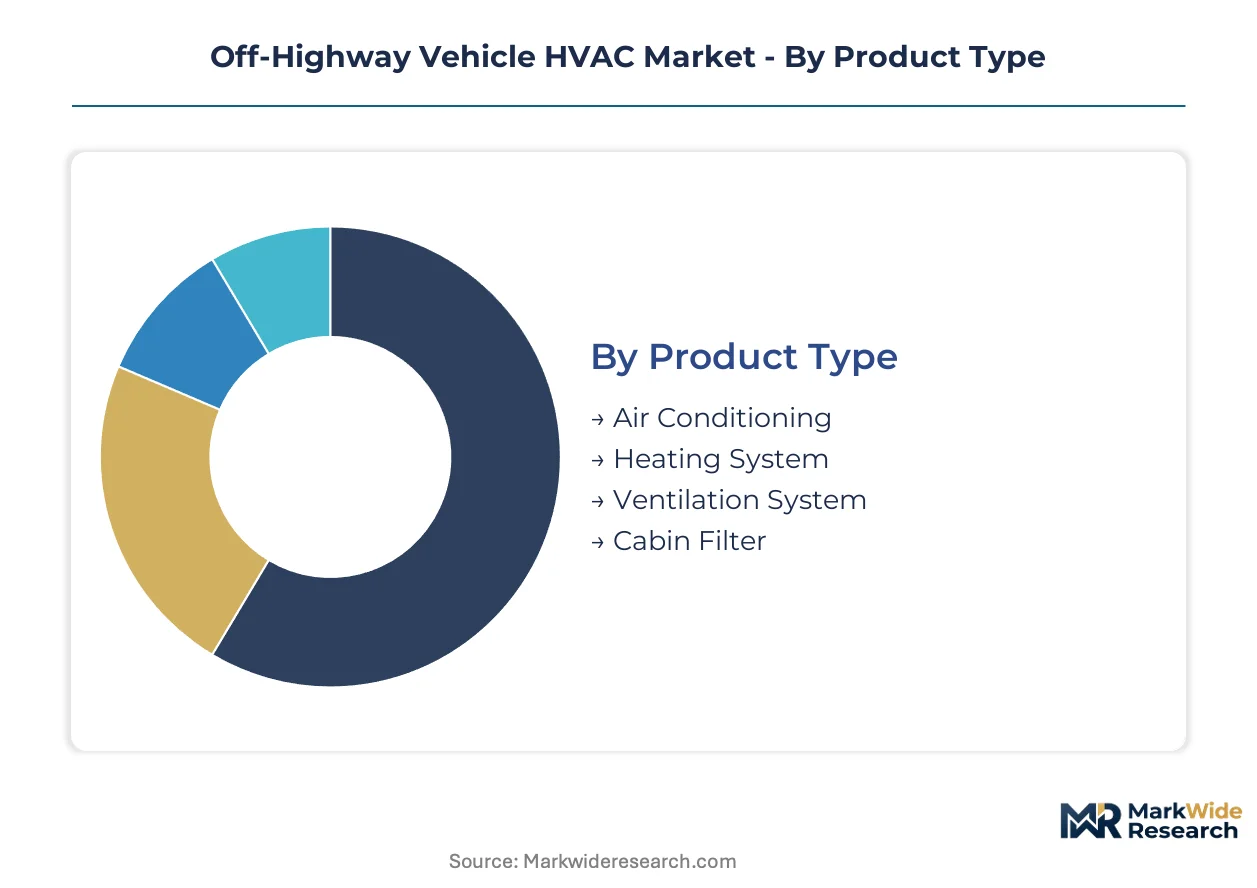
Off-highway vehicle HVAC segmentation reveals how thermal system requirements diverge across duty cycles, operator environments, and procurement channels. Equipment deployed in Australian underground mines demands fundamentally different architectures than tractors operating in Punjab's agricultural belts.
Product Type:
Climate control hardware spans cooling, heating, air distribution, and filtration functions that equipment operators combine based on regional weather patterns and cab enclosure standards.
- Air Conditioning:Vapor-compression refrigeration cycles using R-1234yf or R-134a refrigerants dominate thermal load management in high-ambient environments. Australian mining fleets at depths exceeding 1,500 meters specify heavy-duty compressor architectures rated for continuous 16-hour duty cycles where rock temperatures surpass 40°C.
- Heating System:Hydronic heat exchangers and combustion-based units address sub-zero startup conditions in Nordic forestry operations and high-altitude Chilean copper mines. Demand concentrates in retrofit packages for older equipment lacking factory-fit thermal management.
- Ventilation System:Forced-air distribution networks with sealed hose assemblies rated to SAE J1455 vibration specifications maintain cab pressurization in dusty agricultural and construction environments.
- Cabin Filter:High-efficiency filtration media capture respirable silica and diesel particulate in underground mining cabs where operator exposure limits are tightening.
The dominant share belongs to Air Conditioning, while Hybrid Systems (spanning product integration) is closing the gap fastest.
Application:
Equipment category determines thermal load profiles, regulatory exposure, and replacement part attach rates across the installed base.
- Agricultural Machinery:Tractor and combine harvester installations face seasonal demand spikes and deferred maintenance patterns that concentrate aftermarket purchasing in pre-planting and pre-harvest windows.
- Construction Equipment:Excavators and wheel loaders operating in China's Shandong-Jiangsu manufacturing corridor source localized HVAC assemblies with shortened logistics loops.
- Mining Vehicles:Underground haul trucks and loaders in Chilean copper districts drive climate-controlled cab retrofits as extraction depths extend beyond 1,500 meters.
- Forestry Equipment:Harvesters and forwarders in Nordic markets require defrost-dominant thermal systems for extended winter operations in sub-zero conditions.
Construction Equipment holds the largest installed base, though Mining Vehicles is expanding most quickly on retrofit demand.
End User:
Procurement authority sits differently across factory assembly, post-warranty replacement, fleet direct purchasing, and intermediated distribution channels.
- OEMs:Factory-fit specifications from construction and agricultural equipment manufacturers in China and India drive volume demand for integrated HVAC assemblies.
- Aftermarket:Independent refurbishment shops and regional dealer networks capture service revenue as thermal system complexity outpaces technician training pipelines.
- Fleet Operators:Mining and construction fleets in Australia and North America are unbundling service contracts from OEM captive networks to procure directly from component suppliers.
- Distributors:Channel intermediaries in North American agricultural verticals maintain inventory positions for seasonal demand spikes.
OEMs command the dominant procurement volume, yet Fleet Operators are gaining purchasing influence fastest through direct sourcing.
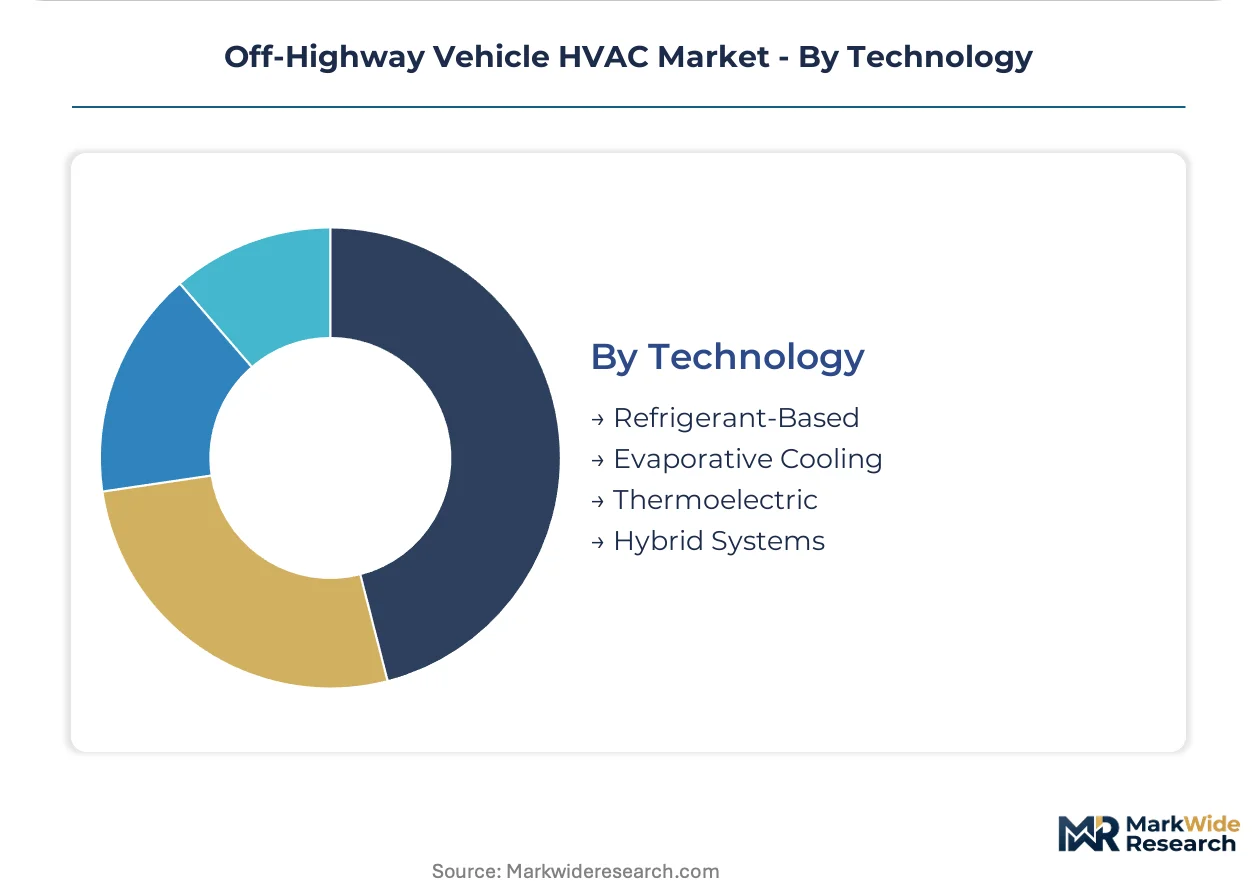
Technology:
Thermal management architectures range from conventional refrigerant cycles to emerging electrified and solid-state approaches.
- Refrigerant-Based:Conventional vapor-compression systems using R-134a and transitioning R-1234yf face cost volatility under Kigali Amendment phase-down timelines.
- Evaporative Cooling:Water-based cooling suits dry-climate agricultural applications in India where ambient humidity permits effective latent heat transfer.
- Thermoelectric:Solid-state Peltier devices enable compact localized cooling in space-constrained engine compartments under EPA Tier 4 Final packaging constraints.
- Hybrid Systems:Electrified auxiliary power units displace belt-driven compressors to enable engine-off HVAC operation, reducing fuel burn during idle periods in mining fleets.
Refrigerant-Based technology retains the largest share, while Hybrid Systems represents the steepest expansion trajectory as electrified APUs displace mechanical drives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication clusters in East Asia and specialized retrofit demand in high-ambient mining corridors are redrawing procurement geography for thermal systems. Regulatory divergence between EPA Tier 4 Final and EU Stage V compliance timelines is fragmenting supplier certification requirements across export markets. Equipment OEMs now source integrated HVAC assemblies through regionally anchored supply relationships rather than centralized global contracts.
China
Construction equipment manufacturing in Shandong and Jiangsu provinces generates concentrated demand for localized HVAC assemblies with shortened logistics loops. MIIT certification requirements for mobile machinery thermal systems are tightening refrigerant containment standards ahead of national Kigali Amendment schedules. Sany Heavy Industry and XCMG procurement teams in Xuzhou and Changsha are qualifying compact integrated units for next-generation excavator platforms.
United States
Underground mining fleets in Arizona and Nevada are retrofitting climate-controlled cabs as extraction depths extend below 1,500 meters. EPA Tier 4 Final emissions compliance has compressed engine compartment packaging space, forcing thermal system redesigns for domestic OEM assembly lines. Caterpillar and John Deere specification engineers in Illinois and Iowa are validating compact heat exchanger architectures under elevated thermal load conditions.
Germany
Forestry equipment manufacturers in Baden-Württemberg and Lower Saxony require defrost-dominant thermal systems for extended winter operations in sub-zero Nordic export markets. The EU F-Gas Regulation is accelerating HFO refrigerant adoption timelines for mobile equipment categories ahead of 2025 model year releases. KBA type-approval processes for construction machinery HVAC now incorporate leak-tightness protocols exceeding prior automotive baselines.
Australia
Underground haul truck operators in Western Australia's Pilbara region and Queensland's Bowen Basin are expanding climate-controlled cab retrofits as rock temperatures at depth exceed 40°C. ISO 16750-3 vibration certification requirements govern qualification for mining deployments, creating compliance barriers for unvalidated component sources. Perth-based fleet maintenance contractors are unbundling service contracts from OEM captive networks to procure directly from component suppliers.
India
Tractor OEMs in Punjab and Haryana are specifying factory-fit HVAC as operator comfort becomes a competitive differentiator in agricultural land consolidation trends. BIS certification for mobile air conditioning systems is aligning with international refrigerant phase-down timelines under the Kigali Amendment. Mahindra & Mahindra and TAFE manufacturing facilities in Maharashtra and Tamil Nadu are integrating evaporative cooling alternatives for dry-climate applications.
Off-Highway Vehicle HVAC Market Competitive Landscape
Scale-driven diversified industrials and specialized thermal component fabricators split the market across distinct value capture tiers. Japanese and Korean conglomerates anchor captive supply relationships with domestic construction equipment OEMs through compressor manufacturing scale and integrated module assembly. European specialists compete through refrigerant system engineering intensity and aftermarket distribution network control. North American independents dominate fleet operator direct procurement channels. Competitive dynamics center on dual certification timeline compression and predictive maintenance technology integration.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries Ltd, Denso Corporation, and MAHLE GmbH exemplify distinct strategic positioning archetypes. Mitsubishi Heavy Industries Ltd occupies a position within integrated HVAC module supply for heavy equipment platforms. Denso Corporation represents compressor manufacturing scale as a foundation for captive OEM relationships. MAHLE GmbH anchors thermal system engineering specialization addressing compact engine bay packaging constraints. These three entities collectively illustrate how geographic origin and corporate structure shape competitive approach without converging on identical capability profiles.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd |
| S.E.A SRL |
| Denso Corporation |
| Hanon Systems |
| Marelli Corporation |
| MAHLE GmbH |
| Sanden Holdings Corporation |
| Bergstrom Inc. |
| Webasto SE |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's Shandong-Jiangsu HVAC fabrication corridor compresses supplier margins while concentrating pricing power among alloy input processors. Utilization rates below 75% in regional compressor assembly plants force tier-one suppliers into extended warranty bundling to defend value capture.
Pricing Analysis
Aftermarket service revenue drives lifetime value across mining and agricultural equipment fleets. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 16750-3 certification grade and SAE J1455 vibration rating. Cost compression in replacement compressor modules intensifies because R-1234yf refrigerant premiums exceed legacy R-134a baselines. Fleet operators in Australia's Pilbara region exhibit highest price sensitivity on retrofits; OEM captive channels in Japan show lowest sensitivity due to bundled maintenance contracts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates procurement risk for heat exchanger manufacturers. Component fabrication concentrates in China, South Korea, and Japan; copper-aluminum alloy supply rests on East Asian smelting corridors. Single-source vulnerability in specialized refrigerant hose assemblies creates chokepoints for mining fleet retrofits. Distribution runs through OEM captive networks and independent refurbishment shops with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrified auxiliary power unit integration is shifting this market toward platform-economics dynamics as compressor controllers digitize and telematics interoperability becomes mandatory for fleet procurement.
For Market Incumbents: Entrench position by deepening backward integration into refrigerant containment systems and securing dual EPA Tier 4 Final and EU Stage V certification ahead of competitor timelines. Denso Corporation's captive supply model with Japanese construction OEMs demonstrates how channel control defends against independent refurbishment shop disintermediation. Prioritize sensor-embedded hose assembly R&D to capture predictive maintenance revenue streams.
For New Entrants and Emerging Players: India's Punjab-Haryana tractor belt offers underpenetrated factory-fit HVAC specification as agricultural mechanization accelerates. Target evaporative cooling alternatives for dry-climate deployments where Mahindra & Mahindra procurement teams seek cost-optimized thermal solutions. Pursue direct fleet operator relationships in Western Australia's mining corridor to bypass established OEM captive networks.
For Investors and Strategic Acquirers: Long-term, this sits as a refrigerant transition play because Kigali Amendment phase-down timelines will obsolete legacy R-134a installed bases and force system-level retrofit demand. Acquisition targets should combine HFO certification capability with mining-sector ISO 16750-3 validation. Watch for MIIT refrigerant containment standard acceleration as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous EPA Tier 4 Final and EU Stage V validation opens access to both North American and European OEM assembly lines. |
| Predictive Maintenance Module Development | Sensor-embedded compressor controllers enable condition-based replacement contracts with Australian mining fleet operators. |
| HFO Refrigerant System Certification | Early qualification under EU F-Gas Regulation leak-tightness protocols positions suppliers for German and French 2025 model year releases. |
| Direct Fleet Procurement Channel | Bypassing OEM captive networks captures 30-40% parts markup reduction demanded by North American construction and agricultural verticals. |
| Evaporative Cooling Product Line | Water-based thermal systems address BIS-certified demand from Indian tractor OEMs in Maharashtra and Tamil Nadu dry-climate applications. |
Research Methodology
Cross-validation between primary interviews with thermal system engineers and aftermarket service heads anchors the qualitative findings against customs data on HVAC assembly imports and MIIT certification registries. OEM procurement directors, mining fleet maintenance contractors, and independent refurbishment shop operators provided field-level insight on refrigerant transition timelines and technician training gaps. Secondary sources include EPA Tier 4 Final compliance filings, EU F-Gas Regulation implementation guidance, and SAE J1455 durability protocol documentation. Bottom-up equipment installation estimates and top-down regional construction and mining expenditure data complete the triangulation.
Calibration against historical refrigerant phase-down patterns in adjacent mobile equipment categories informs the projection framework. Segmentation dimensions span product type, application, end user, and technology architecture across the analysis window. CAGRs derive from fitted growth curves adjusted for regulatory mandate acceleration and fleet replacement cycle compression. Electrified APU penetration rates and underground mining depth extension trajectories serve as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese component suppliers or accelerated Kigali Amendment national schedules would shift outcomes. Material shifts in copper-aluminum alloy tariff structures or refrigerant containment standard enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
Middle East and Africa Utility Terrain Vehicles Market
Off Road Vehicles
All-Terrain Vehicle (ATV) Engines Market
Off Road Vehicles
Off-Highway Vehicle Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
US Off-Road Vehicles Market
Off Road Vehicles
Snow Scooter Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Off-Highway Diesel Common Rail Injection System Market
Off Road Vehicles
Global Electric Off-Highway Equipment Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Off-Highway Engine Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Global Off-Road Trailers Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market