
 Automotive Suspension Control Arms Market | 2026-2036
Automotive Suspension Control Arms Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Suspension Control Arms Market Outlook
Premium forged aluminum control arms is decoupling from commodity stamped steel equivalents on cost, performance, and supply chain terms. ThyssenKrupp AG leverages its integrated forging and machining capacity to serve German luxury OEM programs with tight tolerance specifications. ZF Friedrichshafen AG anchors its position through modular suspension architectures that bundle control arms with damper modules. Magna International Inc. competes by operating stamping and assembly plants adjacent to major North American vehicle assembly corridors.
Automotive suspension control arms are load-bearing linkage components that connect the vehicle chassis to the wheel hub, typically manufactured through forging, stamping, or casting processes with specified yield strengths exceeding 400 MPa for safety-critical applications. Their primary function is to maintain wheel alignment geometry while isolating road-induced forces from the passenger compartment. Aluminum control arms command expanding share as OEMs target unsprung mass reduction, though steel variants sustain dominance in heavy duty and cost-sensitive segments where durability outweighs weight targets. Aftermarket Providers represent a mature margin pool driven by aging vehicle parc and independent repair channel density, while OEMs concentrate procurement among vertically capable tier-one suppliers.
EPA fuel economy standards, Euro 7 emissions frameworks, and China's MIIT dual carbon goals collectively mandate lighter vehicle architectures that cascade into suspension material specifications and testing protocols. NHTSA crashworthiness requirements further dictate control arm failure modes and energy absorption characteristics that influence alloy selection and geometric design. Stakeholders must monitor evolving alloy recycling mandates and regional content thresholds that threaten to fragment procurement strategies across major production geographies.
Market Dynamics
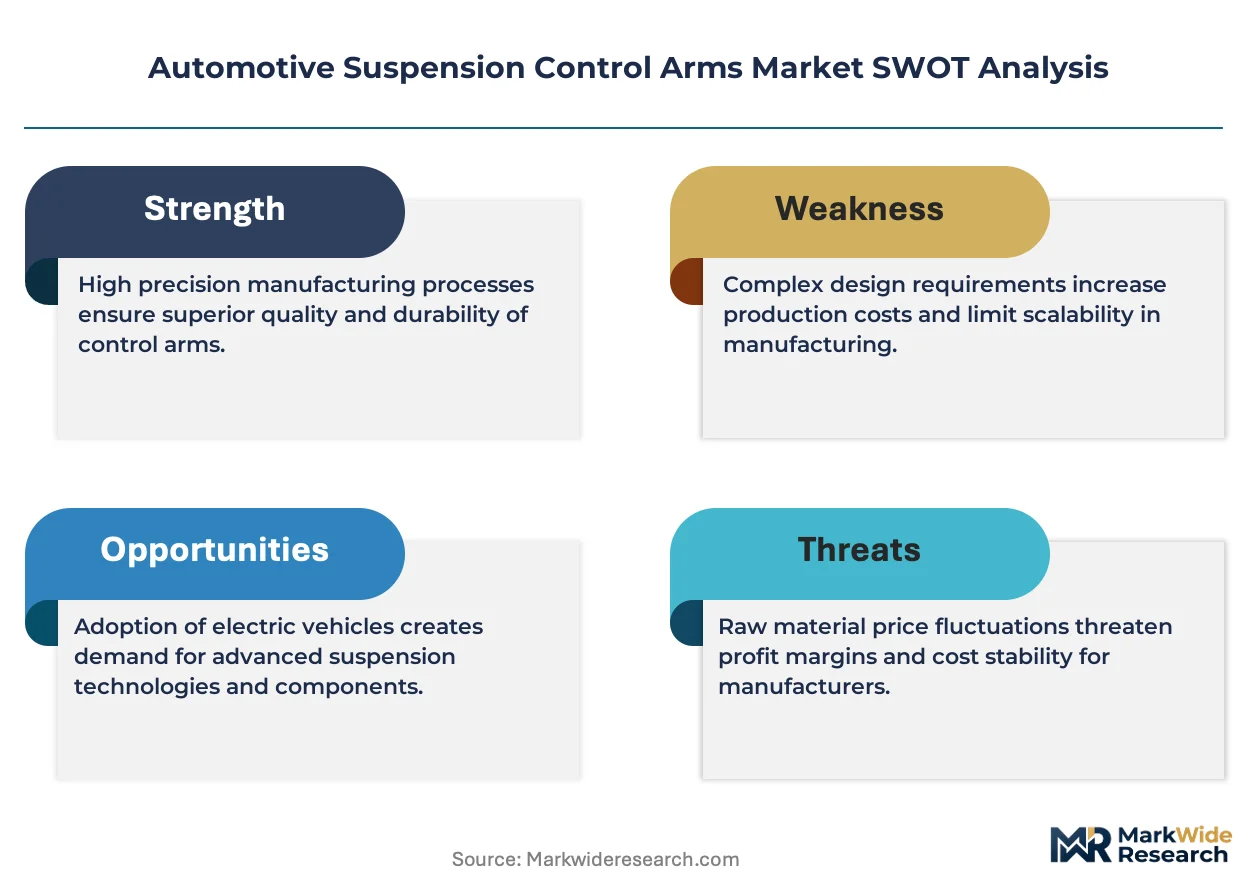
Electric vehicle platform architectures are forcing a material substitution cascade across suspension systems, as unsprung mass reduction directly correlates with battery range extension and OEMs redesign chassis geometries around battery pack integration.
Growth Catalysts
- Euro 7 emissions frameworks:The regulation mandates particulate and NOx reductions that cascade into lighter vehicle architectures, compelling suspension redesigns that favor aluminum control arms over steel equivalents in passenger vehicle segments.
- Battery-electric vehicle startups:These OEMs specify forged aluminum control arms from program inception to maximize range ratings, bypassing the steel-to-aluminum transition friction that legacy automakers face.
- Aluminum forging capacity expansion:Dedicated investments in closed-die forging lines across Germany, China, and the United States are compressing lead times for complex geometry control arms with thin-wall sections.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange pricing swings for aluminum ingot compress margin predictability for forged component suppliers locked into annual OEM supply agreements.
- High-volume steel stamping concentration:Control arm stamping capacity clusters in China's Yangtze River Delta and Mexico's Bajío region, creating geographic single-source risk for cost-sensitive vehicle programs.
- Cast iron knuckle compatibility:Legacy hub carrier geometries optimized for steel control arm attachment points resist aluminum control arm retrofit without full suspension module redesign.
Strategic Opportunities
- India's PLI scheme for automotive components:The production-linked incentive framework subsidizes capital expenditure for forging and machining capacity, enabling first-mover positioning ahead of domestic EV platform localization.
- Topology-optimized generative design:Convergence of AI-driven geometry optimization with additive manufacturing tooling is enabling bionic aluminum control arm structures that manual design cycles cannot replicate.
- Independent repair channel digitization:E-commerce platforms with VIN-specific fitment databases are disintermediating traditional aftermarket distributors, opening direct-to-installer channels for premium control arm brands.
Industry Challenges
- Multi-axis CNC programming expertise:Complex aluminum control arm geometries require simultaneous five-axis machining capabilities that outstrip the available talent pool in traditional stamping-dominant supplier bases.
- Homologation timeline compression:Euro NCAP and IIHS test protocol updates demand accelerated durability and crash validation cycles that strain supplier testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Suspension Control Arms Market |
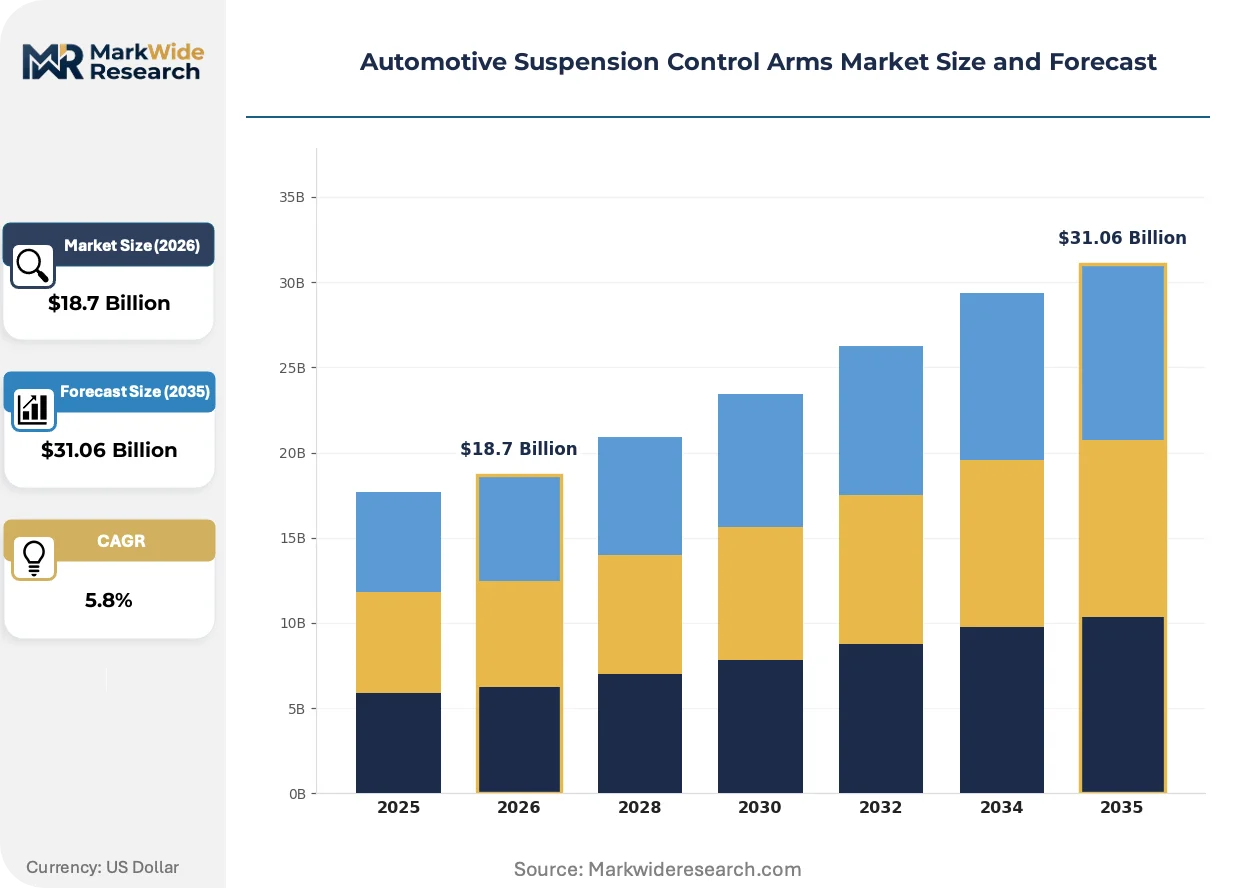
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
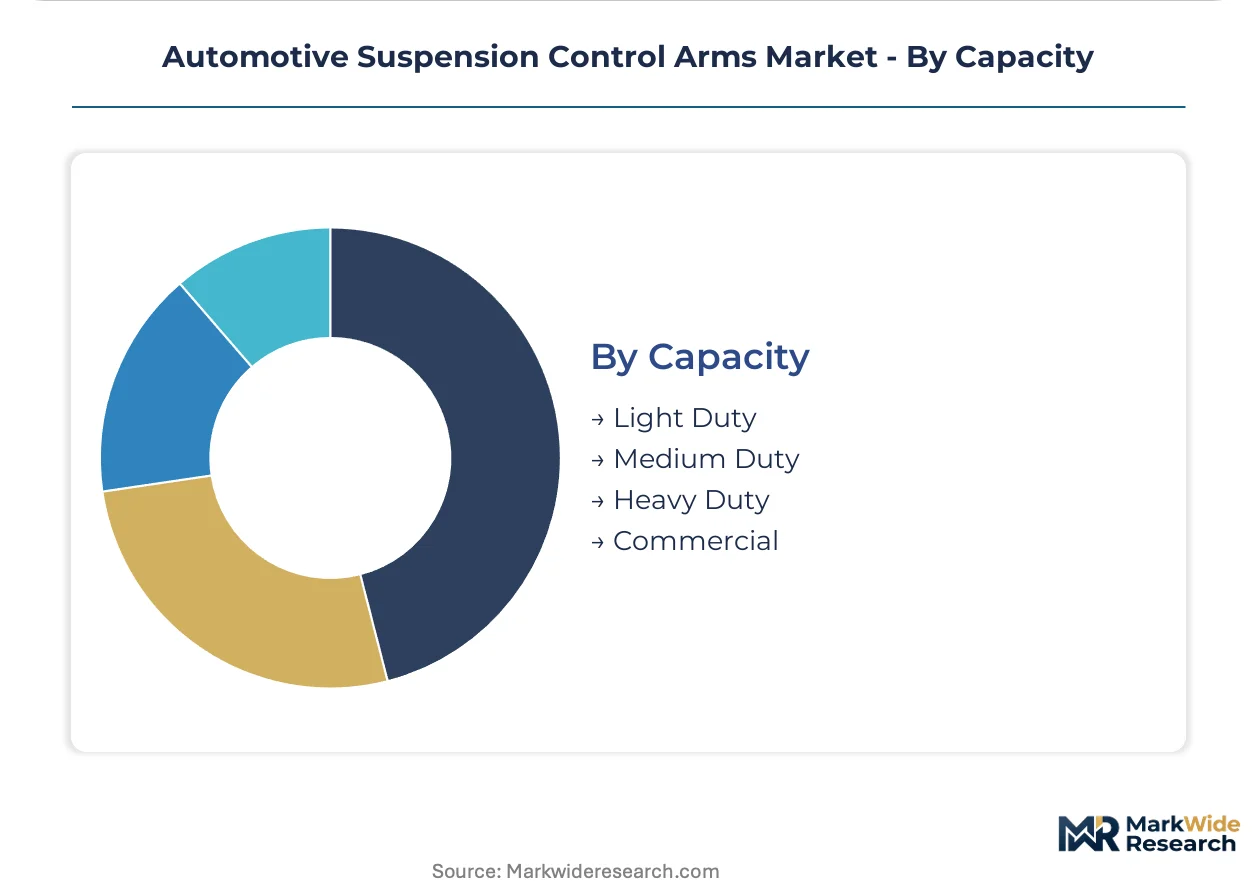
| Segmentation | Product Type: Front Control Arms, Rear Control Arms, Upper Control Arms, Lower Control Arms Material: Steel, Aluminum, Composite, Cast Iron End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Capacity: Light Duty, Medium Duty, Heavy Duty, Commercial |
| Companies Covered | ThyssenKrupp AG, KYB Corporation, ZF Friedrichshafen AG, Meyle AG, DRiV Incorporated (MOOG), Magna International Inc., Tenneco Inc., OCAP Group, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Suspension Control Arms Market Strategic Shifts
Material science advances and digital manufacturing integration are collapsing the traditional trade-off between weight reduction and structural integrity in suspension linkage design.
Hollow aluminum forging is rewriting the cost-performance frontier for unsprung mass reduction. The process extrudes internal cavities during closed-die forging to create box-section control arms with stiffness-to-weight ratios previously achievable only through solid titanium. German luxury OEMs have adopted this technology across their electric SUV platforms. The structural consequence is compressing the viable application window for stamped steel control arms to heavy-duty and entry-price vehicle segments exclusively.
EPA fuel economy standards and the EU Green Deal's embodied carbon requirements are tightening lifecycle emissions accounting for automotive components. Suppliers must now document cradle-to-gate carbon intensity for aluminum control arms, including primary smelting energy sources. European OEMs are responding by specifying recycled-content aluminum with renewable energy certificates, shifting procurement qualification criteria beyond unit cost to carbon-adjusted total cost of ownership.
Direct OEM-to-forge relationships are displacing traditional tiered supply hierarchies in aluminum control arm procurement. Battery-electric vehicle platforms require suspension geometries that differ fundamentally from internal combustion architectures, eliminating the part-number carryover that justified incumbent tier-one supplier relationships. North American EV startups are negotiating directly with forging specialists, compressing the value chain and forcing established suspension module integrators to reposition around assembly and testing rather than component manufacturing.
Automotive Suspension Control Arms Market Segmentation
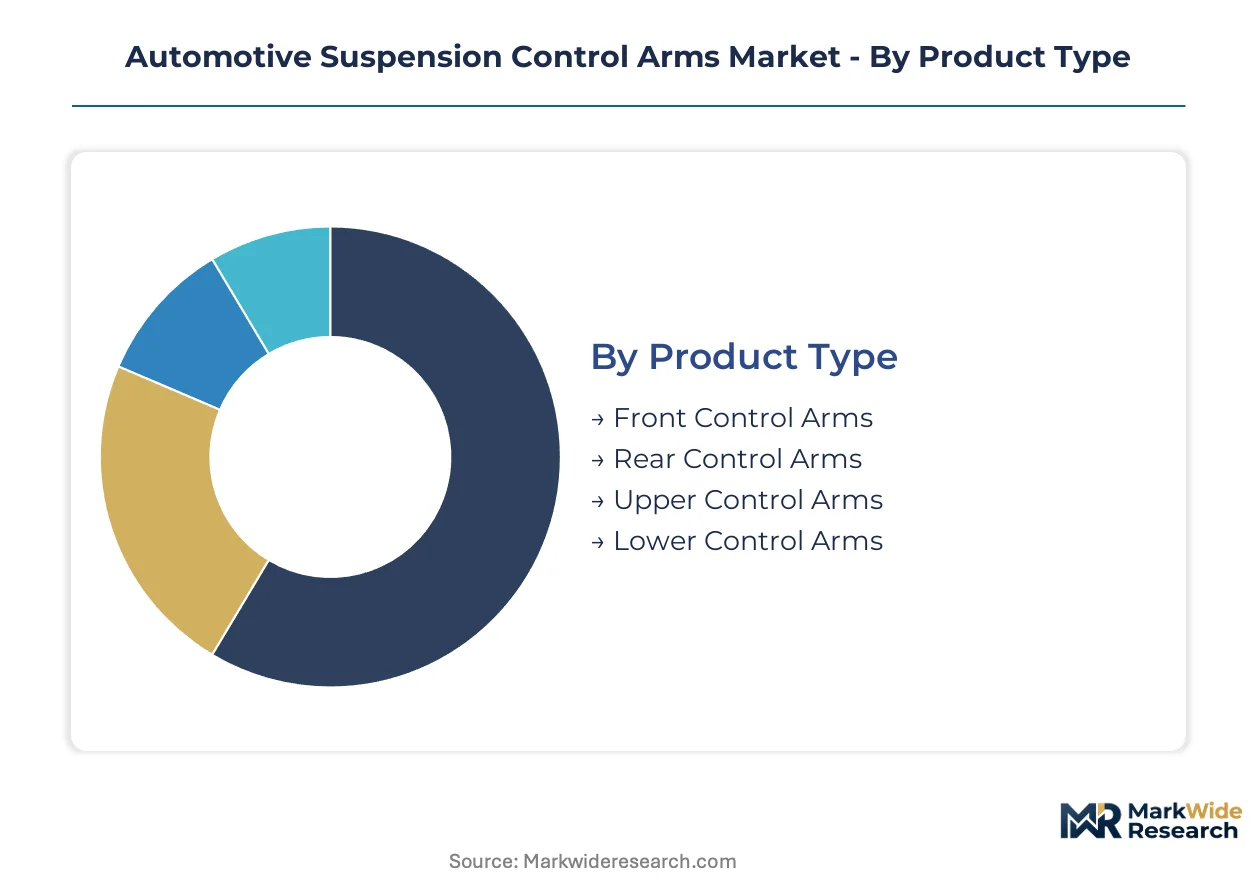
Segmentation in automotive suspension control arms reveals distinct capital requirements, margin profiles, and customer loyalty patterns across manufacturing technologies and procurement channels. Each dimension exposes different competitive moats and vulnerability points for suppliers positioning across vehicle electrification cycles.
Product Type:
Capital intensity concentrates in front and lower control arms where forging investments for aluminum variants demand dedicated press lines and multi-axis machining centers.
- Front Control Arms:These components manage steering geometry and vertical wheel travel through complex ball-joint integrations. German and Chinese OEMs specify hollow-forged aluminum variants for electric SUV platforms to reduce unsprung mass and extend battery range ratings.
- Lower Control Arms:Primary load-bearing linkages that transfer lateral and longitudinal forces to the chassis. North American battery-electric vehicle startups source these directly from forging specialists, bypassing traditional tier-one module integrators to compress development timelines.
- Rear Control Arms:Typically stamped steel in cost-sensitive mass-market segments.
- Upper Control Arms:Often integrated with adjustable camber plates in performance applications.
Lower control arms absorb the bulk of installed forging capacity; front control arms are expanding most quickly as electric platforms proliferate.
Material:
Cost tier stratification separates premium aluminum programs from commodity steel supply, with composite materials occupying narrow performance niches.
- Aluminum:Closed-die forging with hollow-section extrusion creates stiffness-to-weight ratios that stamped steel cannot match. European OEMs now mandate recycled-content aluminum with renewable energy certificates under EU Green Deal embodied carbon accounting.
- Steel:High-volume stamping dominates heavy-duty and entry-price vehicle segments where durability targets exceed weight reduction priorities. Capacity clusters in China's Yangtze River Delta and Mexico's Bajío region create geographic concentration risk.
- Composite:Carbon fiber-reinforced polymers serve motorsport and ultra-premium electric hypercar programs.
- Cast Iron:Legacy hub carrier compatibility limits retrofit potential without full suspension module redesign.
Steel commands the greatest production volume; aluminum is climbing the fastest as Euro 7 emissions frameworks cascade into lighter vehicle architectures.
End User:
Customer type determines contract structure, with OEMs demanding multi-year supply agreements and aftermarket channels operating on spot purchasing.
- OEMs:Direct procurement relationships with forging specialists are displacing traditional tiered supply hierarchies for aluminum control arms on dedicated electric vehicle platforms. Annual supply agreements lock in volume commitments with price volatility clauses tied to London Metal Exchange aluminum ingot pricing.
- Aftermarket Providers:E-commerce platforms with VIN-specific fitment databases are disintermediating traditional distributors, opening direct-to-installer channels for premium control arm brands serving aging vehicle parc in the United States and Germany.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands source pre-assembled suspension modules.
- Fleet Operators:High-mileage commercial vehicle fleets prioritize steel control arms for total cost of ownership calculations.
OEMs concentrate the highest value procurement; aftermarket providers are gaining share fastest through digital channel disintermediation.
Capacity:
Application severity dictates material specification and testing protocol intensity across duty cycle classifications.
- Light Duty:Passenger cars and crossover utilities where aluminum control arms deliver measurable range extension for battery-electric platforms. EPA fuel economy standards and NHTSA crashworthiness requirements shape alloy selection and geometric design.
- Heavy Duty:Commercial trucks and off-highway equipment where forged steel control arms withstand extreme cyclic loading. India's PLI scheme for automotive components is subsidizing capital expenditure for forging capacity targeting this segment.
- Medium Duty:Delivery vans and light commercial vehicles with mixed fleet electrification timelines.
- Commercial:Transit buses and vocational trucks with standardized suspension architectures.
Heavy duty applications anchor steel forging capacity; light duty programs are expanding most quickly as EV platform architectures force material substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European forging capacity for aluminum control arms serving German luxury OEM electrification programs. The city's integrated automotive engineering ecosystem compresses development cycles for hollow-section suspension components. Regional specialization concentrates procurement decisions among vertically capable tier-one suppliers.
Germany
Battery-electric SUV platforms from Munich and Stuttgart-based automakers specify hollow-forged aluminum lower control arms to extend range ratings. The EU Green Deal's embodied carbon requirements mandate recycled-content aluminum with renewable energy certificates. Baden-Württemberg's forging clusters around Stuttgart and Pforzheim host closed-die press lines dedicated to thin-wall suspension geometries.
China
MIIT dual carbon goals accelerate material substitution in Yangtze River Delta vehicle assembly corridors. Domestic EV startups specify forged aluminum control arms from program inception to maximize range benchmarks against Tesla and BYD. Shanghai and Ningbo forging specialists are expanding capacity to serve NIO, Xpeng, and Li Auto platform architectures.
United States
EPA fuel economy standards cascade into lighter vehicle architectures for Detroit Three electrification programs. NHTSA crashworthiness protocols dictate control arm failure modes that influence alloy selection and geometric validation. Michigan's automotive corridor hosts stamping and forging plants adjacent to Dearborn and Warren assembly complexes.
India
The PLI scheme for automotive components subsidizes capital expenditure for forging capacity targeting domestic EV platform localization. Tata Motors and Mahindra electric SUV programs drive specification of aluminum control arms previously imported from European suppliers. Tamil Nadu and Maharashtra industrial zones attract first-mover forging investments ahead of 2025-2026 localization deadlines.
Japan
METI carbon neutrality roadmaps pressure Toyota and Honda to reduce unsprung mass in hybrid and battery-electric architectures. JIS standards for suspension component durability shape testing protocols for aluminum alloy selection. Aichi Prefecture's Toyota City supplier ecosystem maintains steel forging dominance while piloting aluminum transition programs for next-generation platforms.
Automotive Suspension Control Arms Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent cost structures and customer access models. The market exhibits tiered consolidation among integrated forging specialists and diversified suspension module integrators. Strategic archetypes separate aluminum forging purists, steel stamping volume leaders, and modular system bundlers. Dominant competitive moves include direct OEM-forge relationship formation and topology-optimized generative design adoption.
Among German industrial conglomerates, ThyssenKrupp AG and ZF Friedrichshafen AG exemplify divergent positioning archetypes. ThyssenKrupp AG represents the integrated forging specialist model with captive metallurgy and machining capacity. ZF Friedrichshafen AG occupies the modular system integrator position bundling control arms with damper modules. Magna International Inc. anchors the geographic proximity strategy with North American stamping and assembly plants adjacent to major vehicle assembly corridors.
| Leading Market Players |
|---|
| ThyssenKrupp AG |
| KYB Corporation |
| ZF Friedrichshafen AG |
| Meyle AG |
| DRiV Incorporated (MOOG) |
| Magna International Inc. |
| Tenneco Inc. |
| OCAP Group |
| Continental AG |
| Others |
Value Chain & Pricing Dynamics
Captive aluminum forging capacity in Germany and China anchors supplier pricing power, as OEMs negotiate directly with metallurgy-integrated producers for hollow-section control arms on dedicated electric vehicle platforms. This backward integration into primary smelting and closed-die pressing compresses margin leakage while London Metal Exchange volatility clauses in annual supply agreements transfer commodity risk downstream.
Pricing Analysis
Value-based pricing anchored to battery range extension outcomes separates premium aluminum control arms from commodity steel equivalents. Three-tier pricing structure across premium forged aluminum, standard stamped steel, and economy gray iron variants reflects certification grade and unsprung mass reduction performance. Pricing pressure stems from primary aluminum ingot volatility squeezing forge-operator margins under fixed-price OEM contracts. Fleet operators and entry-vehicle programs exhibit highest price sensitivity; German luxury OEMs and North American EV startups demonstrate lowest.
Supply Chain Analysis
Primary aluminum supply rests on smelters in China, Russia, and the Arabian Gulf, with secondary recycled feedstock concentrating in European scrap processing networks. Bauxite refining and alumina production hinge on Australian and Guinean extraction, while closed-die forging equipment sources from German and Japanese press manufacturers. Single-source vulnerability clusters in China's Yangtze River Delta stamping capacity for high-volume steel control arms. Distribution runs through tier-one module integrators for legacy OEM programs, with direct OEM-forge relationships displacing intermediaries in battery-electric platform procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive suspension control arms constitute a vertical-integration race where captive metallurgy and machining capacity determines who captures value from aluminum substitution. Players are pursuing upstream control over primary and recycled aluminum feedstock to secure margin and carbon-accounting credentials.
For Market Incumbents: Anchor market position through hollow-forging capacity expansion in Baden-Württemberg and Michigan corridors, securing multi-year supply agreements with battery-electric vehicle startups before topology-optimized generative design commoditizes geometric complexity. Defend against direct OEM-forge relationship formation by bundling control arms with damper modules and wheel-end assemblies. Prioritize renewable-energy-certificated recycled aluminum qualification to meet EU Green Deal embodied carbon thresholds. For New Entrants and Emerging Players: Topology-optimized generative design capabilities offer entry wedge into premium electric SUV programs where manual design cycles cannot match bionic aluminum structures. Target India's PLI-subsidized forging capacity buildout ahead of Tata Motors and Mahindra EV platform localization. Pursue white-space in aftermarket e-commerce channels with VIN-specific fitment databases that disintermediate traditional distributors serving aging German and United States vehicle parc. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified suspension module integrators seeking captive forging capacity. Long-term viability favors vertically capable tier-one suppliers with demonstrated Euro NCAP and IIHS validation track records. Watch for aluminum forging capacity utilization inflection as battery-electric vehicle platform volumes cross threshold where dedicated press-line economics outperform outsourced procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Hollow Aluminum Forging Capacity Expansion | Captures range-optimization premiums from German and Chinese luxury OEM electrification programs. |
| Recycled-Content Aluminum Qualification | Secures EU Green Deal compliance and renewable energy certificate procurement for European supply. |
| Direct OEM Relationship Formation | Bypasses tier-one module integrators for North American EV startup platform architectures. |
| Topology-Optimized Generative Design Adoption | Enables bionic structures that manual design cycles cannot replicate for unsprung mass reduction. |
| Aftermarket E-Commerce Channel Development | Disintermediates traditional distributors through VIN-specific fitment databases in United States and Germany. |
Study Parameters
Multi-period observation of aluminum forging capacity utilization, London Metal Exchange pricing volatility, and OEM platform electrification timelines anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and closed-die forging plant managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of diversified automotive suppliers, and EPA fuel economy compliance reports. Bottom-up segment sizing triangulated against top-down macroeconomic vehicle demand projections.
Segment-weighting across product type, material specification, end-user channel, and vehicle duty class informed volume and value outputs across the projection horizon. Propulsion architecture and content-per-vehicle assumptions modeled aluminum penetration rates by platform. CAGRs derived from regression analysis of historical forging capacity expansion against electrification program announcements, with scenario weighting for Euro 7 regulatory compliance timelines and India's PLI scheme disbursement schedules.
Several conditions sit outside the modeled scope, including tariff regime shifts affecting primary aluminum trade flows, unannounced battery-electric vehicle platform cancellations, and breakthrough composite material substitutions. Forecasts reflect documented assumptions about OEM electrification commitments and alloy recycling mandate trajectories. A small set of named triggers warrants ongoing watch: London Metal Exchange price spike duration, Euro NCAP test protocol update timing, and Chinese MIIT dual carbon goal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Fluid Couplings Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Automotive Brake Wheel Cylinder Market
Automotive Parts
Crank Trigger System Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Cylinder Head Cover Market