
 Automotive Interior Ambient Lighting Market | 2026-2036
Automotive Interior Ambient Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Interior Ambient Lighting Market Analysis
Aftermarket service revenue is reconfiguring margin distribution across the automotive lighting value chain. OSRAM GmbH leverages its semiconductor heritage to dominate LED component supply for OEM programs. Koito Manufacturing Co., Ltd. anchors production scale through integrated headlamp and interior lighting platforms. HELLA GmbH & Co. KGaA differentiates via control electronics that bridge body-domain controllers with RGB ambient modules.
Automotive interior ambient lighting comprises distributed light sources, optical conductors, and driver electronics engineered to deliver tunable illumination across footwells, door panels, dashboards, and headliners, typically operating at low voltages with pulse-width modulation for dimming precision. Its primary purpose is enhancing perceived cabin quality while supporting driver alertness and passenger comfort through chromatic and intensity variation. LED product types command the dominant share due to thermal efficiency and miniaturization, though fiber optic architectures retain traction in luxury vehicle type segments where uniform linear glow is prioritized. RGB technology is expanding fastest as smart lighting systems enable over-the-air palette updates and synchronization with vehicle state data.
FCC electromagnetic compatibility standards govern wireless control interfaces in US-bound vehicles, while EU REACH and RoHS restrict heavy metals in phosphor formulations and solder joints. ECE R48 and its national transpositions regulate light intensity and color boundaries to prevent driver distraction in European type approvals. Stakeholders must monitor how software-defined vehicle architectures will redistribute control logic between tier-one lighting suppliers and OEM central compute platforms.
Market Dynamics
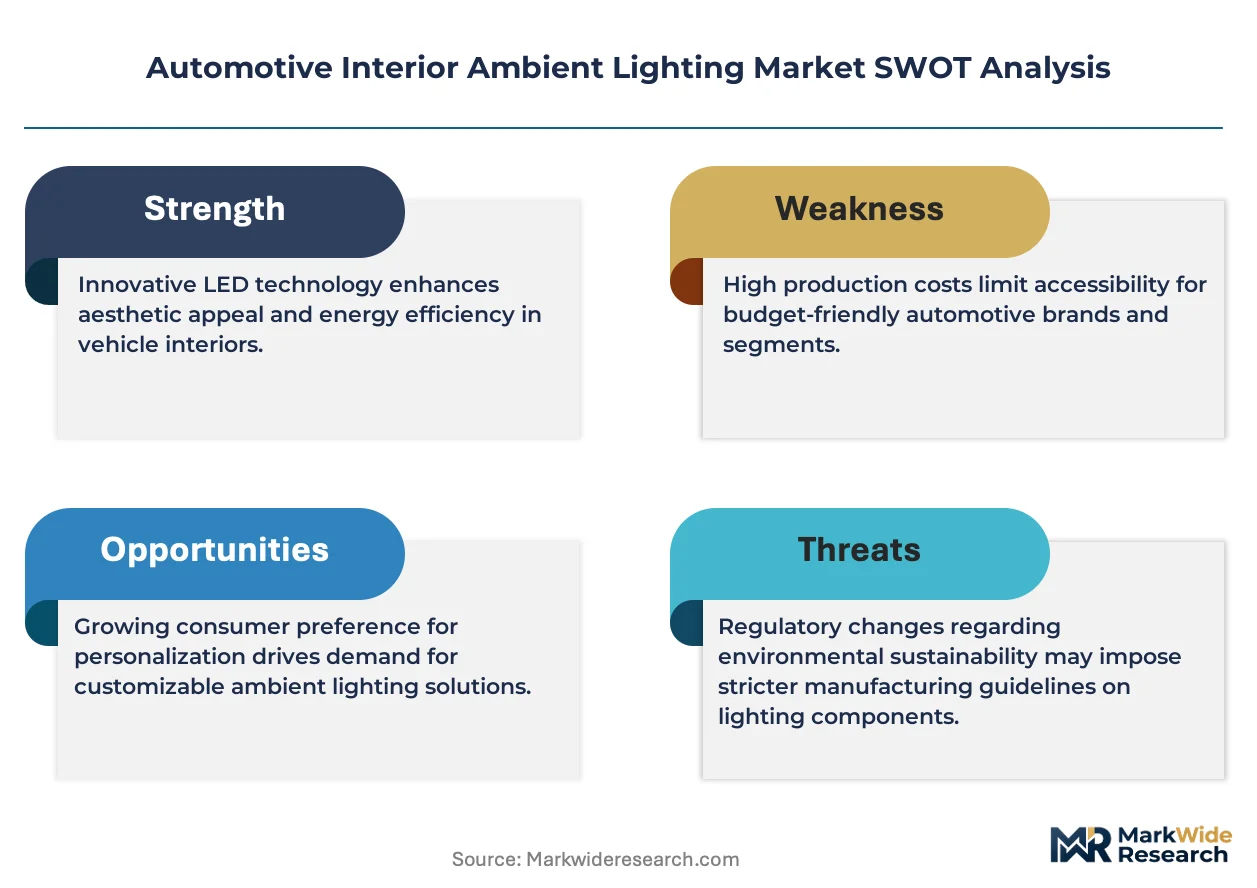
Software-defined vehicle architectures are redistributing control logic from tier-one lighting suppliers toward OEM central compute platforms, compressing traditional component margins while expanding firmware and integration service revenue pools.
Growth Catalysts
- EU REACH compliance:Hazardous substance restrictions on halogen phosphors and solder joints are accelerating LED substitution across European vehicle programs.
- China EV integration:Domestic electric vehicle brands are deploying multi-zone ambient systems as standard equipment across mass-market vehicle classes.
- RGB synchronization:Smart lighting systems now enable over-the-air palette updates tied to vehicle state data, creating recurring service attachment opportunities.
Market Restraints
- Phosphor cost volatility:Rare earth element price swings in cerium and yttrium formulations create margin pressure for LED component suppliers.
- Concentrated semiconductor supply:Driver IC fabrication depends on a narrow base of foundry capacity concentrated in Taiwan and South Korea.
- Fiber optic technical ceiling:Uniform linear glow architectures face heat dissipation limits above 85°C ambient, restricting engine-bay proximity placement.
Strategic Opportunities
- India passenger vehicle penetration:Ambient lighting attachment rates remain below 15% in domestic mass-market models, creating white space for tier-one localization.
- Wellness application expansion:Circadian rhythm synchronization and driver alertness systems are opening new therapeutic positioning for cabin illumination.
- OTA service monetization:Theme marketplace models for RGB palette libraries represent unexploited recurring revenue streams adjacent to hardware sales.
Industry Challenges
- Embedded software talent scarcity:Firmware development for body-domain controller integration requires scarce automotive Ethernet and AUTOSAR expertise.
- ECE R48 certification timelines:European type approval for color boundary compliance adds 8-14 months to new vehicle program launches.
- Legacy harness integration friction:Retrofitting smart ambient modules into existing 12V architectures without full platform redesign constrains aftermarket penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Interior Ambient Lighting Market |
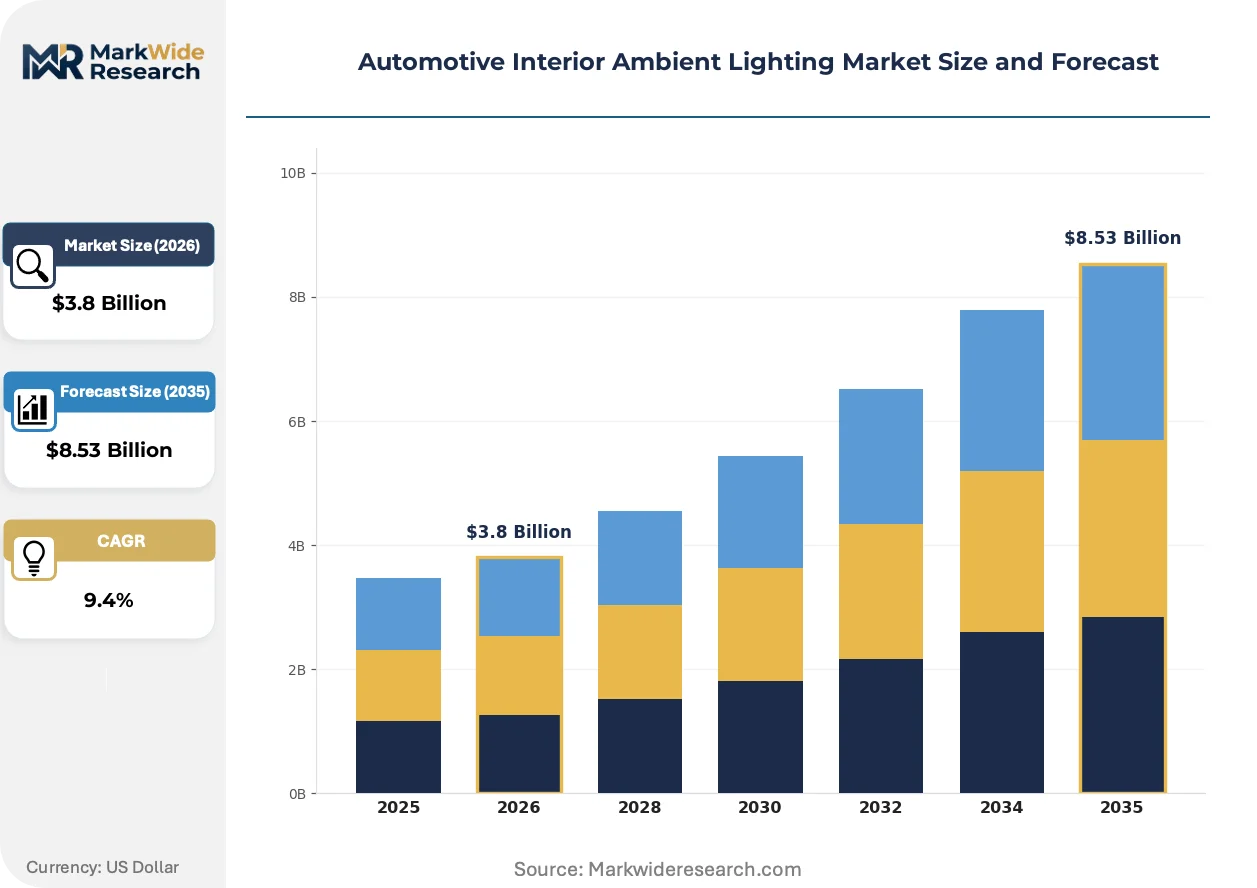
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fiber Optic, Neon, Halogen Technology: Smart Lighting, RGB Lighting, Wireless Control, Dimming Features Vehicle Type: SUVs, Sedans, Hatchbacks, Luxury Cars End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Customization Services |
| Companies Covered | Dräxlmaier Group, Everlight Electronics Co., Ltd., OSRAM GmbH, Koito Manufacturing Co., Ltd., Toshiba Corporation, HELLA GmbH & Co. KGaA, Antolin, Innotec, Valeo Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Interior Ambient Lighting Market Emerging Trajectories
Automotive interior lighting is transitioning from static hardware to software-configurable experience layers, with control electronics and digital service architectures capturing value previously embedded in physical components.
Matrix LED arrays with individual pixel control are digitizing cabin illumination by enabling dynamic animation sequences and zone-specific intensity modulation. Luxury and near-luxury OEMs are adopting these systems at program refresh cycles of 24-36 months. The technology is digitizing traditional tier-one supplier roles by shifting value toward semiconductor and software integration capabilities.
ECE R48 and its national transpositions in Germany, France, and Italy are tightening color boundary enforcement for interior illumination to prevent driver distraction. This regulatory pressure is forcing RGB module suppliers to narrow wavelength tolerance specifications and add closed-loop calibration hardware. Premium vehicle segments in European type approval markets are absorbing the compliance cost through higher trim-level pricing.
Fleet procurement managers are unbundling lighting system specification from full vehicle program awards, creating direct sourcing relationships with tier-one suppliers for aftermarket retrofit and refresh cycles. This disintermediation is compressing traditional OEM captive supply arrangements. China and Germany are exhibiting the most pronounced procurement model evolution, driven by large fleet operators in premium mobility services.
Automotive Interior Ambient Lighting Market Segmentation
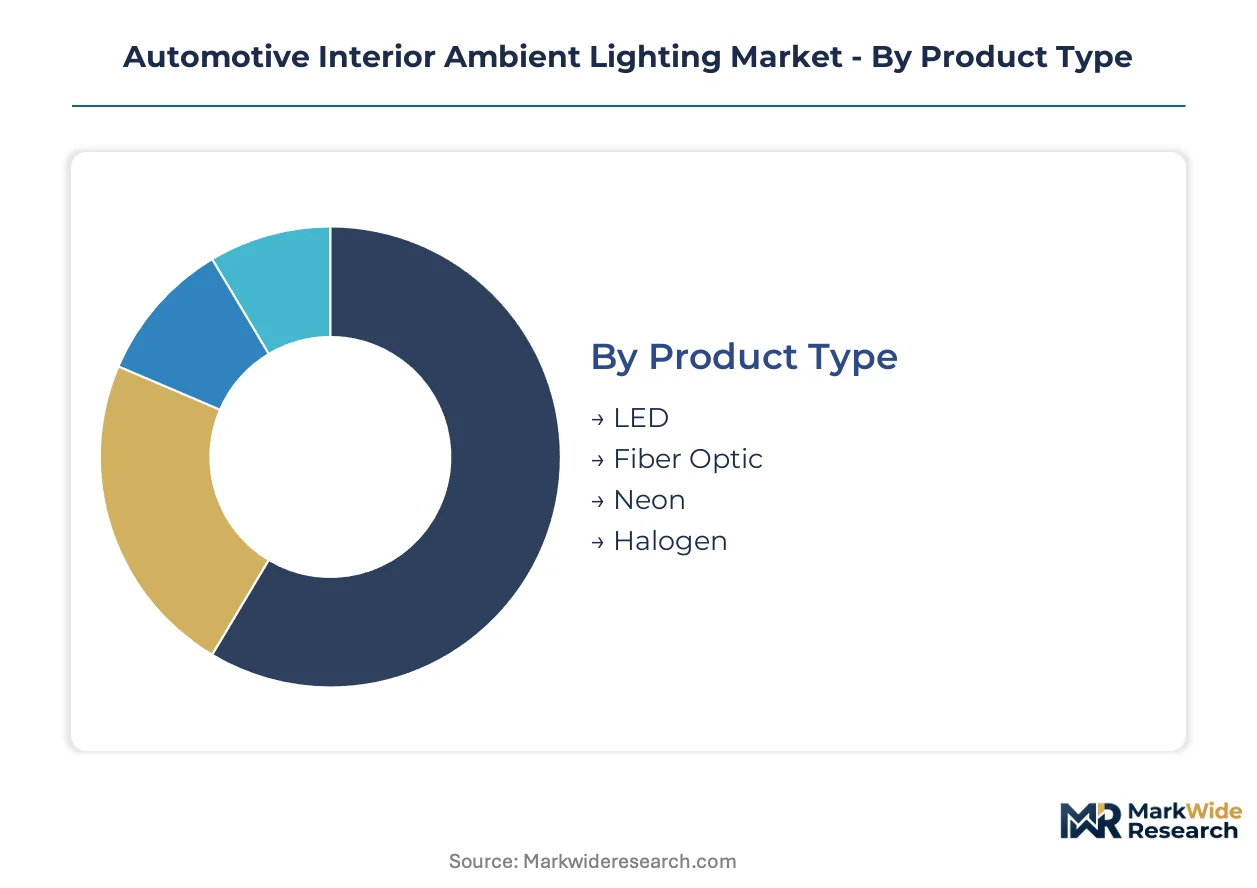
Automotive interior ambient lighting segments diverge sharply by thermal performance, control architecture, and integration complexity. Suppliers must align portfolio depth with the specific certification burdens and software dependencies each category imposes.
Product Type:
Mature LED platforms dominate factory installations while emerging fiber optic architectures retain niche positioning in premium cabin designs.
- LED:Solid-state semiconductor emitters operating at 12V with pulse-width modulation deliver thermal efficiency below 60°C junction temperatures. Chinese EV manufacturers specify multi-zone LED arrays as standard equipment across mass-market crossovers and sedans, compressing cost curves through domestic phosphor supply chains.
- Fiber Optic:Polymer or glass light guides distribute illumination from remote sources, enabling uniform linear glow across door panels and headliners. German luxury OEMs specify fiber architectures for flagship sedans where thermal isolation from engine compartments permits extended linear runs without LED density penalties.
- Neon:Cold cathode fluorescent tubes produce high-luminance accent lighting through mercury vapor excitation. Aftermarket customization services in Japan deploy neon footwell kits for kei-car and compact tuner segments where regulatory enforcement of ECE R48 color boundaries remains less stringent.
- Halogen:Tungsten-filament bulbs with halogen regenerative cycles face phase-out pressure from EU REACH substance restrictions on heavy metal phosphors. Remaining demand concentrates in legacy vehicle refurbishment programs and developing-market vehicle classes where LED retrofit economics fail.
LED handles the majority of throughput; fiber optic is the fastest mover on share.
Technology:
Cost tier stratification separates premium software-configurable systems from hardware-locked economy offerings.
- Smart Lighting:Networked control architectures enable over-the-air palette updates and vehicle-state synchronization through body-domain controllers. RGB synchronization protocols are expanding fastest in China as domestic EV brands monetize lighting themes through subscription marketplaces.
- RGB Lighting:Red-green-blue trichromatic mixing produces tunable white points and saturated accent colors across 16 million addressable states. European premium OEMs absorb ECE R48 compliance costs through closed-loop calibration hardware that narrows wavelength tolerances for type approval.
- Wireless Control:Bluetooth Low Energy and proprietary RF protocols eliminate harness routing to door panels and seatbacks. FCC electromagnetic compatibility certification governs US-bound implementations, adding 4-6 months to program development cycles.
- Dimming Features:Analog and digital dimming circuits adjust intensity through voltage reduction or PWM frequency modulation. Mass-market hatchbacks and compact sedans in India specify basic dimming as a cost-controlled quality differentiator where full RGB remains uneconomical.
Smart lighting commands premium pricing; RGB is expanding most quickly in factory fitment rates.
Vehicle Type:
Application intensity varies by cabin architecture complexity and trim-level pricing power.
- SUVs:Elevated rooflines and expanded interior volumes accommodate extended headliner light guides and multi-zone footwell arrays. Chinese domestic brands deploy ambient lighting as standard across compact and mid-size SUV segments to differentiate against legacy joint-venture competitors.
- Sedans:Longitudinal cabin proportions favor linear door panel illumination and dashboard accent strips. German luxury sedans specify matrix LED arrays with individual pixel control for dynamic animation sequences at 24-36 month refresh cycles.
- Hatchbacks:Compact cabin dimensions constrain light guide routing and reduce zone count economics. Indian mass-market hatchbacks exhibit ambient lighting attachment rates below 15%, creating white space for tier-one localization as feature penetration expands.
- Luxury Cars:Unlimited trim pricing permits fiber optic headliner constellations, 64-color RGB zone control, and wellness-mode circadian synchronization. Fleet procurement managers in German premium mobility services are disintermediating OEM captive supply arrangements through direct tier-one sourcing.
SUVs absorb the highest absolute unit volumes; luxury cars maintain steepest expansion trajectory in per-vehicle content value.
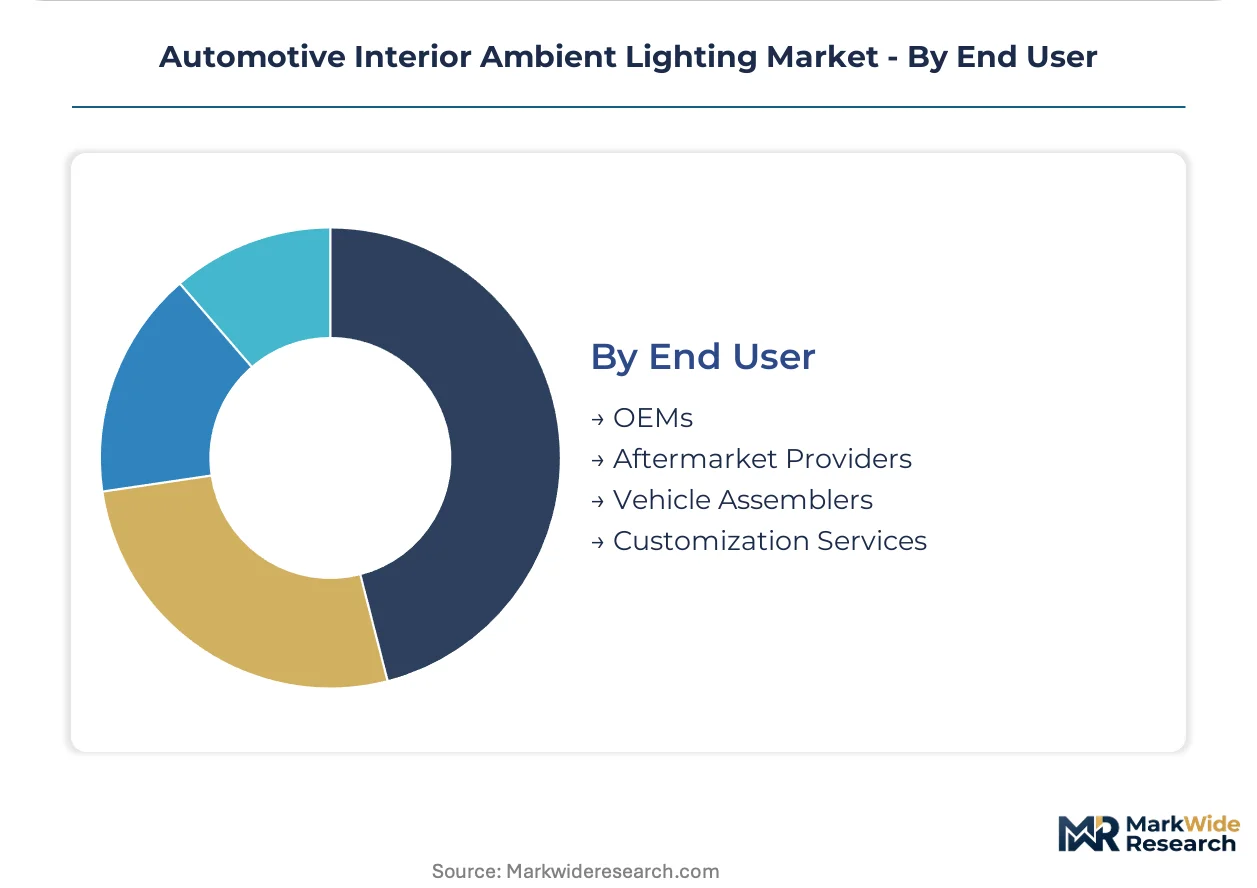
End User:
Customer type determines integration depth, certification responsibility, and margin capture mechanics.
- OEMs:Original equipment manufacturers specify lighting systems at vehicle program inception, bearing ECE R48 and FCC certification liability. Software-defined vehicle architectures are redistributing control logic from tier-one suppliers toward OEM central compute platforms.
- Aftermarket Providers:Independent distributors and installers serve vehicle refresh cycles and owner customization preferences. Legacy 12V harness integration friction constrains smart ambient module penetration without full platform redesign.
- Vehicle Assemblers:Contract manufacturers and knock-down assembly operations in emerging markets source lighting modules through CKD/SKD supply chains. Indian passenger vehicle assemblers are localizing LED component supply to capture PLI scheme incentives.
- Customization Services:Bespoke interior studios and fleet upfitters deliver personalized illumination configurations outside factory specifications. Japanese aftermarket tuners specialize in neon and fiber optic accent packages for domestic compact and kei-vehicle segments.
OEMs retain majority revenue share; customization services are climbing fastest as experience-layer monetization expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Driver IC foundry capacity concentrates in Taiwan and South Korea, creating geographic dependencies for LED module assembly. Chinese EV manufacturers absorb the highest absolute volumes of multi-zone ambient systems.
China
Domestic EV brands deploy ambient lighting as standard equipment across mass-market crossovers and sedans, compressing cost curves through local phosphor supply chains. MIIT GB standards govern electromagnetic compatibility for wireless control interfaces. The Yangtze River Delta clusters LED component fabrication and module assembly operations around Shanghai and Suzhou.
Germany
Luxury automakers expand cabin personalization programs with matrix LED arrays and fiber optic headliner constellations. ECE R48 and KBA enforcement tighten color boundary compliance for RGB wavelength tolerances. Bavaria anchors development engineering while Baden-Württemberg concentrates tier-one supplier headquarters near Stuttgart.
United States
Fleet procurement managers disintermediate OEM captive supply through direct tier-one sourcing for premium mobility services. FCC electromagnetic compatibility certification adds 4-6 months to program development cycles for Bluetooth-enabled modules. Michigan and Ohio retain legacy harness integration expertise while California studios pioneer wellness-mode circadian synchronization.
Japan
Kei-car and compact tuner segments sustain aftermarket neon and fiber optic accent demand where ECE R48 enforcement remains less stringent. METI JIS standards establish baseline photometric performance for domestic type approval. Kansai region around Osaka concentrates LED component heritage manufacturing.
India
Passenger vehicle ambient lighting attachment rates remain below 15% in mass-market models, creating localization opportunities for tier-one suppliers. PLI scheme incentives accelerate domestic LED component sourcing for vehicle assemblers. Maharashtra and Tamil Nadu cluster emerging module assembly operations near Chennai and Pune.
Automotive Interior Ambient Lighting Market Vendor Landscape
Semiconductor heritage specialists and integrated lighting platforms split the market between component supply and full-system delivery. The vendor base concentrates around three strategic archetypes: LED emitters with phosphor formulation control, tier-one integrators bridging body-domain electronics, and aftermarket customization services. Dominant competitive moves include backward integration into driver IC design and geographic expansion through CKD supply chains for emerging market vehicle assemblers.
Within the semiconductor heritage tier, OSRAM GmbH and Everlight Electronics Co., Ltd. represent contrasting geographic anchors for LED emitter supply. Koito Manufacturing Co., Ltd. exemplifies the integrated platform archetype that spans headlamp and interior lighting domains. HELLA GmbH & Co. KGaA occupies a position bridging control electronics with RGB ambient modules, reflecting the software-defined vehicle transition redistributing value toward firmware integration.
| Leading Market Players |
|---|
| Dräxlmaier Group |
| Everlight Electronics Co., Ltd. |
| OSRAM GmbH |
| Koito Manufacturing Co., Ltd. |
| Toshiba Corporation |
| HELLA GmbH & Co. KGaA |
| Antolin |
| Innotec |
| Valeo Service |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Taiwanese driver IC foundries is compressing component margins while simultaneously enabling aggressive pricing postures among LED module assemblers in China and South Korea. This utilization dynamic feeds back into tier-one supplier negotiations, where volume commitments extract preferential pricing on phosphor formulations and thermal substrates.
Pricing Analysis
Aftermarket service revenue from OTA palette updates and extended warranty contracts drives lifetime value capture beyond initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates closed-loop calibrated RGB systems from basic dimming modules and unregulated neon accent kits. Cost compression in mass-market LED arrays is intensifying because Chinese EV manufacturers specify multi-zone systems as standard equipment. Fleet procurement managers exhibit lowest price sensitivity, while Indian mass-market vehicle assemblers face acute pressure from sub-15% ambient lighting attachment rates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for tier-one suppliers with cross-border assembly footprints. Driver IC fabrication concentrates in Taiwan and South Korea, while phosphor formulation and LED packaging cluster in China and Japan. Rare earth element dependencies in cerium and yttrium formulations create commodity price volatility that propagates through module costs. Distribution runs through OEM captive supply arrangements in Germany and direct tier-one sourcing relationships emerging in China and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical trough conditions driven by automotive production volume normalization and EV platform refresh cycles. OEMs are re-engaging tier-one suppliers for multi-zone ambient system integration at accelerated program timelines.
For Market Incumbents: Insulate firmware revenue streams from hardware margin erosion by deepening AUTOSAR expertise and body-domain controller integration capabilities. Secure phosphor supply through backward integration into rare earth processing or long-term offtake agreements with Chinese suppliers. Counter emerging semiconductor heritage competitors by embedding closed-loop calibration hardware that satisfies ECE R48 wavelength tolerance enforcement. For New Entrants and Emerging Players: Build out India-focused module assembly operations to capture PLI scheme incentives and serve domestic vehicle assemblers below 15% ambient lighting penetration. Target wellness-mode circadian synchronization applications where therapeutic positioning commands premium pricing. Pursue direct fleet procurement relationships in German premium mobility services as an entry vector outside OEM captive supply. For Investors and Strategic Acquirers: Long-term, this sits as a software-layer monetization play because vehicle-state synchronization and OTA theme marketplaces transform lighting from hardware commodity to recurring service platform. Acquisition candidates with driver IC design capability and automotive Ethernet firmware stacks warrant priority evaluation. Monitor RGB subscription attachment rates in Chinese EV brands as the inflection signal for service revenue scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Control logic redistribution toward OEM central compute compresses tier-one hardware margins while expanding firmware service pools. |
| Phosphor Supply Agreement | Long-term cerium and yttrium offtake contracts insulate LED component suppliers from rare earth price volatility. |
| Geographic Manufacturing Footprint | India module assembly localization captures PLI incentives and reduces logistics friction for sub-15% penetration markets. |
| OTA Platform Integration | Theme marketplace deployment enables recurring revenue attachment adjacent to hardware sales in Chinese EV segments. |
| Regulatory Certification Investment | ECE R48 closed-loop calibration hardware narrows wavelength tolerances for European type approval compliance. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and semiconductor foundry planning officers and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs trade records. Bottom-up volume modeling triangulated with top-down market sizing across LED, fiber optic, and emerging technology categories.
Demand-supply balance dynamics across the projection horizon informed analytical framework construction. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from unit-volume trajectories and average selling price evolution. Industry-specific forecast inputs incorporated MIIT GB standard compliance timelines and ECE R48 certification cycle durations.
Stress conditions across rare earth element price bands, Taiwanese foundry utilization rates, and EU REACH enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or software-defined vehicle architecture adoption shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive HVAC Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market