
 Automotive Infotainment Market | 2026-2036
Automotive Infotainment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Infotainment Market Intelligence
Germany is tilting toward expanded software-defined vehicle capacity as automakers localize infotainment stack development. Robert Bosch GmbH leverages its Stuttgart engineering base to sustain integrated cockpit controller production. Harman International anchors premium audio and connected platform R&D across Bavarian tech corridors. Panasonic Corporation competes through display module specialization for Tier-1 dashboard programs.
Automotive infotainment denotes the integrated hardware-software systems delivering navigation, entertainment, telematics, and human-machine interface functions within vehicles, typically operating on multicore processors with real-time operating systems and automotive-grade Linux distributions. These systems serve the primary commercial purpose of differentiating vehicle interiors while reducing driver distraction through centralized control architectures. Touchscreen displays occupy the largest installed base across OEM programs, though augmented reality interfaces represent the fastest-growing technology segment as windshield projection resolutions advance toward 4K fidelity. Voice recognition systems capture expanding margin pools as natural language processing shifts from cloud-dependent to edge-computing architectures.
The EU AI Act imposes risk-classification requirements on driver-monitoring algorithms embedded within infotainment stacks, while ECE R10 governs electromagnetic emissions from 4G LTE and Wi-Fi connectivity modules. Japan's METI promotes software-defined vehicle standards that accelerate over-the-air update capabilities across infotainment platforms. Stakeholders must decide whether to pursue proprietary operating system development or consolidate around open-source automotive Linux distributions as regulatory fragmentation deepens.
Market Dynamics
The automotive infotainment sector confronts a fundamental architecture transition as cockpit electronics migrate from distributed ECU networks toward centralized domain controllers running hypervisor-enabled software stacks. This consolidation compresses hardware variety while expanding firmware complexity, forcing suppliers to restructure engineering competencies around cloud-native development pipelines.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for driver-monitoring algorithms are accelerating edge-computing investments across infotainment stacks, creating certified hardware demand.
- Edge AI voice processing:Natural language inference migrating from cloud dependency to local neural processing units reduces latency and connectivity costs for mass-market vehicle lines.
- Stuttgart engineering concentration:Germany's supplier ecosystem around digital instrument clusters generates specialized talent pools and component testing infrastructure.
Market Restraints
- Automotive-grade display panel supply:OLED and mini-LED substrate fabrication concentrates among Korean and Taiwanese foundries, exposing OEMs to single-source allocation risk.
- ECE R10 certification timelines:Electromagnetic compatibility testing for 5G-V2X modules extends program schedules by 8-14 months versus 4G predecessors.
- Silicon carbide power component costs:High-voltage infotainment charging circuits require SiC MOSFETs priced at 3-4x silicon equivalents.
Strategic Opportunities
- India's PLI scheme for automotive electronics:Domestic manufacturing incentives attract cockpit controller assembly away from traditional East Asian export bases.
- AR-HUD windshield projection:4K-resolution augmented reality interfaces converge with ADAS visualization, opening premium subscription revenue streams.
- Over-the-air update infrastructure:Japan's METI software-defined vehicle standards create regulatory tailwind for firmware monetization platforms.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates among German and Japanese tier-1 suppliers, constraining program scaling.
- Legacy CAN bus integration:New Ethernet-based cockpit architectures must maintain backward compatibility with 20-year-old vehicle communication protocols.
- Hypervisor software validation:Multi-OS isolation testing for safety-critical and infotainment domains extends verification cycles by 30-40%.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Infotainment Market |
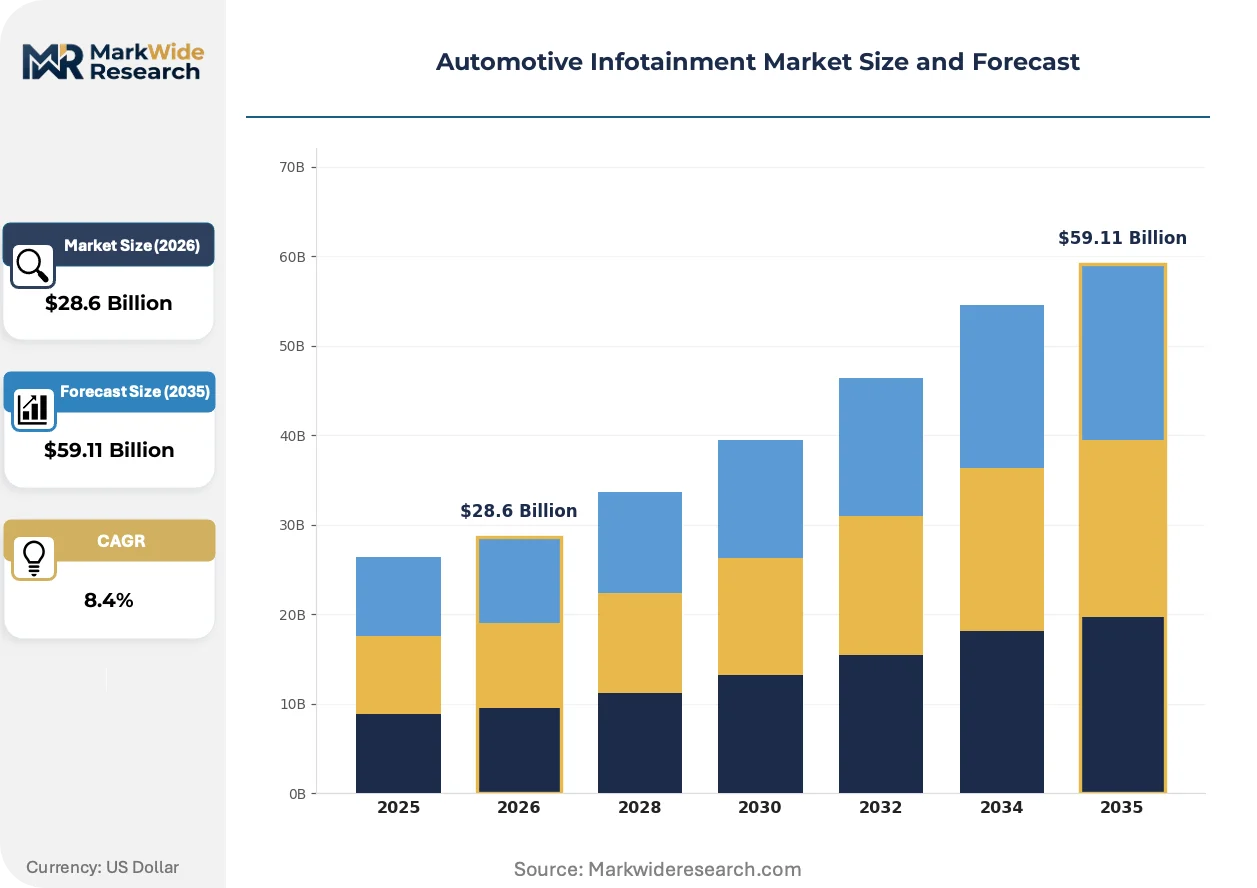
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen Displays, Head-Up Displays, Voice Recognition Systems, Digital Instrument Clusters, Steering Wheel Controls Technology: Bluetooth Connectivity, Wi-Fi, 4G LTE, Near Field Communication, Augmented Reality Interfaces Application: Navigation Systems, Multimedia Playback, Hands-Free Communication, Driver Assistance, Real-Time Traffic Updates End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Dealerships, Aftermarket Providers |
| Companies Covered | Robert Bosch GmbH, Continental AG, Harman International, Panasonic Corporation, Denso Corporation, Alpine Electronics, Pioneer Corporation, Visteon Corporation, Aptiv PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Infotainment Market Strategic Shifts & Innovations
Software-defined vehicle architectures are collapsing the boundary between infotainment and vehicle control systems, enabling feature subscriptions that extend revenue capture across the ownership lifecycle. This transformation demands new supplier capabilities in cloud orchestration and cybersecurity hardening.
Consolidated cockpit domain controllers are digitizing instrument cluster, head-up display, and center-stack functions onto single multicore processors with automotive-grade Linux distributions. Premium OEMs in Germany and Japan deploy these architectures first, compressing hardware bill-of-materials while expanding software service margins. The shift is digitizing traditional tier-2 display driver and gauge component markets into software licensing opportunities.
Europe's ECE R10 electromagnetic compatibility standards now govern 5G-V2X and Wi-Fi 6E emissions from integrated connectivity modules, forcing antenna redesigns and shielding investments. The regulation's industrial consequence is extended pre-homologation testing cycles that favor suppliers with captive EMC chambers. Mass-market programs targeting 2027 model years face the steepest compliance cost absorption.
Fleet operators and mobility service providers now specify open API access to infotainment stacks as a procurement precondition, displacing closed proprietary systems. This buyer concentration in commercial vehicle segments forces tier-1 suppliers to expose middleware layers previously held as intellectual property. The pattern is most visible in North American last-mile delivery vehicle programs where route optimization app integration determines platform selection.
Automotive Infotainment Market Segmentation
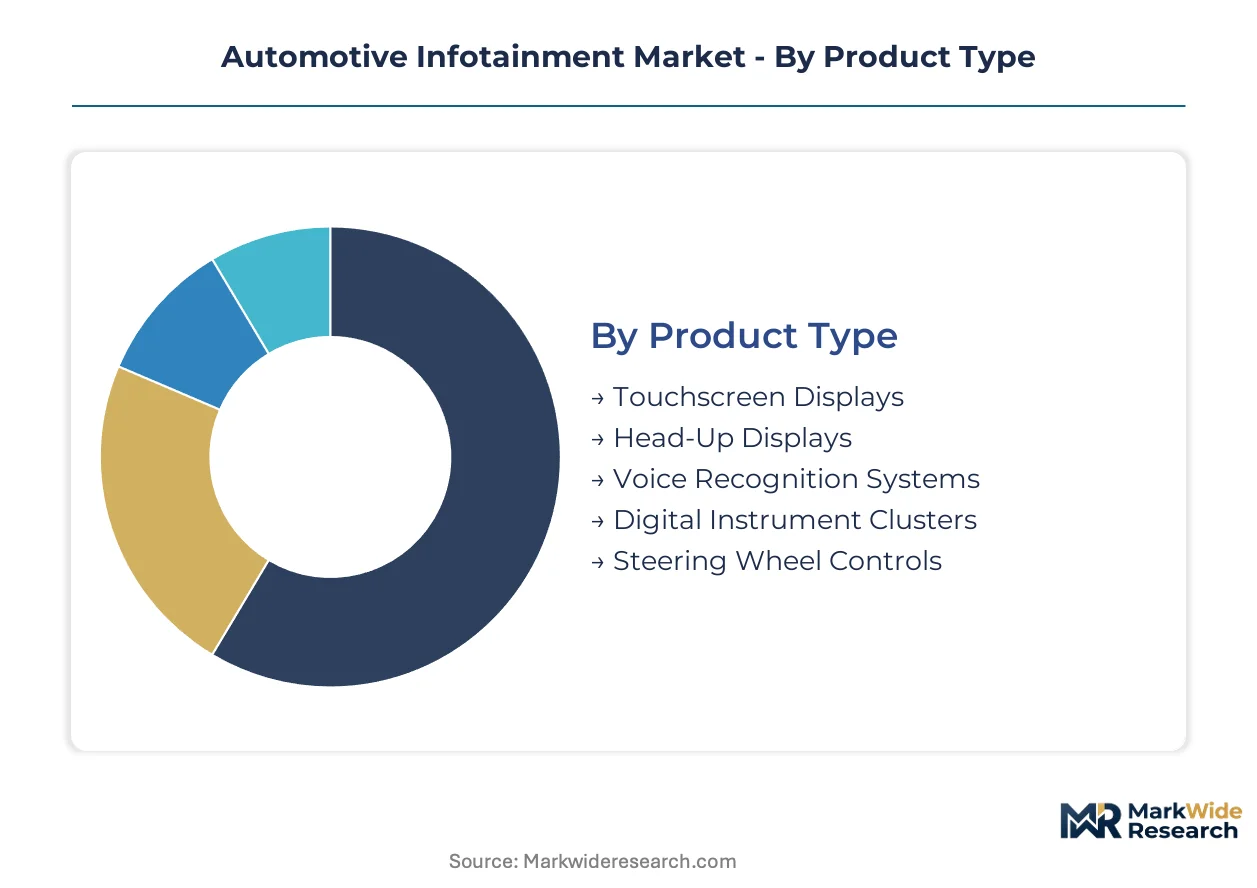
Segmentation in automotive infotainment reveals how hardware commoditization and software monetization create divergent margin pools. Product refresh cycles vary dramatically, from display modules replaced every 5-7 years to voice systems updated via over-the-air patches.
Product Type:
Touchscreen displays turn over slowest due to dashboard integration complexity, while voice recognition modules refresh fastest as edge-AI silicon improves.
- Touchscreen Displays:Multicore processor-driven LCD, OLED, and mini-LED panels ranging from 8 to 17 inches diagonal. Demand clusters in German premium OEM programs where Stuttgart-based engineering teams specify 4K-resolution center-stack modules. ECE R10 electromagnetic certification extends development timelines for capacitive multi-touch variants.
- Voice Recognition Systems:Natural language processing hardware migrating from cloud-dependent architectures to local neural processing units. Japanese automakers under METI software-defined vehicle guidelines prioritize edge-computing voice stacks for latency reduction.
- Head-Up Displays:Windshield projection systems combining combiner optics with DLP or laser pico-projectors.
- Digital Instrument Clusters:Reconfigurable TFT-LCD or OLED panels replacing analog gauge assemblies.
- Steering Wheel Controls:Haptic feedback switches and capacitive touchpads integrating with domain controller architectures.
Touchscreen displays dominate installed base. Voice recognition systems are where expansion concentrates.
Technology:
Connectivity technologies stratify by cost tier, with Bluetooth and Wi-Fi saturating mass-market vehicles while augmented reality interfaces command premium pricing.
- Bluetooth Connectivity:Low-energy audio and data protocols enabling smartphone pairing and hands-free calling. Aftermarket providers in India leverage PLI scheme incentives to localize module assembly for cost-sensitive vehicle lines.
- Augmented Reality Interfaces:4K-resolution windshield projection systems converging ADAS visualization with navigation cues. German OEMs in Ingolstadt and Stuttgart anchor AR-HUD demand as subscription revenue models mature.
- Wi-Fi:802.11ac and Wi-Fi 6E standards for in-vehicle hotspot and device mirroring functions.
- 4G LTE:Cellular connectivity modules enabling telematics and cloud-based services.
- Near Field Communication:Short-range contactless protocols for digital key and payment authentication.
Bluetooth and Wi-Fi modules saturate volume production. Augmented reality interfaces are climbing the fastest.
Application:
Application segments align with customer type, where fleet operators prioritize real-time traffic while retail buyers emphasize multimedia playback.
- Navigation Systems:GPS and dead-reckoning positioning fused with cloud-based routing algorithms. Tier-1 suppliers concentrate development in Bavarian tech corridors to serve Harman International's connected platform programs.
- Real-Time Traffic Updates:V2X and cellular-based congestion data services. North American last-mile delivery fleets specify open API access to traffic layers as procurement precondition.
- Multimedia Playback:Audio and video streaming through integrated apps and smartphone mirroring.
- Hands-Free Communication:Microphone arrays and noise cancellation for voice calling.
- Driver Assistance:Camera-based monitoring and alerts integrated with infotainment displays.
Navigation systems anchor software licensing revenue. Real-time traffic updates are gaining share fastest.
End User:
End user categories reflect supply chain position, with OEMs capturing software margin and aftermarket providers serving replacement demand.
- OEMs:Vehicle manufacturers specifying integrated cockpit architectures and monetizing feature subscriptions. German automakers localize infotainment stack development to reduce dependency on tier-1 suppliers.
- Tier-1 Suppliers:Bosch, Harman, and Panasonic delivering domain controllers and display modules. ISO 26262 ASIL-D certification expertise concentrates among German and Japanese tier-1s, constraining program scaling.
- Vehicle Assemblers:Contract manufacturers integrating pre-validated infotainment modules.
- Dealerships:Retail channels for factory-option upgrades and accessory sales.
- Aftermarket Providers:Independent installers of replacement head units and connectivity modules.
OEMs and tier-1 suppliers control architecture decisions. Aftermarket providers are expanding most quickly in India's PLI-incentivized manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Display module fabrication clusters in Korea and Taiwan anchor upstream supply, while cockpit controller assembly concentrates in German engineering corridors and Japanese automotive belts. Regulatory divergence across electromagnetic compatibility and AI risk-classification standards fragments certification pathways.
Germany
Stuttgart and Ingolstadt anchor tier-1 supplier ecosystems for digital instrument clusters and head-up display modules. ECE R10 electromagnetic compatibility standards tighten certification timelines for 5G-V2X connectivity modules. Bosch leverages its Stuttgart engineering base to sustain integrated cockpit controller production while automakers localize infotainment stack development.
Japan
METI software-defined vehicle standards accelerate over-the-air update capabilities across infotainment platforms. Edge-computing voice processing investments prioritize latency reduction for natural language inference. Nagoya and Tokyo corridors concentrate ASIL-D functional safety expertise among tier-1 suppliers.
United States
Fleet operators and mobility service providers specify open API access to infotainment stacks as procurement precondition. FCC emissions regulations govern Wi-Fi 6E and 5G connectivity module deployments. Michigan and California tech corridors host validation centers for hypervisor-enabled software stacks.
China
Domestic OEMs consolidate cockpit domain controller architectures onto multicore processors with automotive-grade Linux distributions. MIIT standards promote indigenous semiconductor substitution in display driver ICs. Yangtze River Delta clusters concentrate mini-LED substrate testing infrastructure.
India
PLI scheme incentives attract cockpit controller assembly away from traditional East Asian export bases. Aftermarket providers localize Bluetooth and Wi-Fi module production for cost-sensitive vehicle lines. Tamil Nadu and Gujarat manufacturing zones expand tier-2 component testing capacity.
Automotive Infotainment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in display, audio, and connectivity modules. The vendor base stratifies between consolidated domain controller providers and fragmented display driver suppliers. Three archetypes dominate: full-stack cockpit integrators, display module specialists, and edge-AI voice processing developers. Competitive moves center on strategic partnerships for software-defined vehicle architectures and backward integration into semiconductor sourcing.
Among German-based platform integrators, Robert Bosch GmbH and Continental AG occupy positions anchoring European cockpit controller supply. Harman International represents the premium audio and connected platform tier within Bavarian tech corridors. Panasonic Corporation exemplifies display module specialization serving tier-1 dashboard programs across multiple OEM lines.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Harman International |
| Panasonic Corporation |
| Denso Corporation |
| Alpine Electronics |
| Pioneer Corporation |
| Visteon Corporation |
| Aptiv PLC |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta maritime corridor connects Korean display substrate foundries to German cockpit controller assembly plants, with freight cost volatility transmitting directly into margin compression for mass-market infotainment modules and premium tier price differentiation for Stuttgart-engineered domain controllers.
Pricing Analysis
ECE R10 electromagnetic compatibility standards dictate the pricing tier structure across infotainment connectivity modules, separating ASIL-D certified edge-AI voice processors from uncertified cloud-dependent alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification grade and volume scale commitments from OEM platform programs. Cost compression in standard-tier display modules is intensifying because Korean mini-LED substrate allocation favors high-volume premium contracts. Fleet operators and mobility service providers exhibit highest price sensitivity through open API procurement preconditions, while German luxury OEMs absorb premium pricing for captive Stuttgart engineering.
Supply Chain Analysis
Tariff exposure between Taiwan and China dominates supply chain risk planning for automotive-grade display driver ICs and mini-LED substrate components. Raw material and component dependencies center on Korean OLED fabrication, Taiwanese semiconductor foundry capacity, and Japanese SiC MOSFET supply for high-voltage charging circuits. Distribution runs through tier-1 domain controller integrators in Stuttgart and Ingolstadt before final vehicle assembly, with aftermarket channels expanding through India's PLI-incentivized Tamil Nadu manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation toward open API specifications has shifted buyer power toward commercial vehicle segments, fragmenting traditional tier-1 supplier control over proprietary middleware layers.
For Market Incumbents: Insulate embedded software margins through captive certification investment in ISO 26262 ASIL-D functional safety expertise, concentrating engineering talent in Nagoya and Stuttgart corridors. Deepen upstream control over semiconductor sourcing for neural processing units to offset Korean foundry allocation risk from emerging edge-AI voice competitors.
For New Entrants and Emerging Players: India's PLI scheme manufacturing zones represent the most penetrable entry point for aftermarket Bluetooth and Wi-Fi module assembly serving cost-sensitive vehicle lines. Target commercial fleet telematics integration through route optimization app partnerships as the primary go-to-market angle for bypassing entrenched tier-1 supplier relationships.
For Investors and Strategic Acquirers: Edge-AI semiconductor specialists with automotive qualification pathways offer the strongest acquisition profile for capturing software-defined vehicle transition value. Monitor ECE R10 certification timeline extensions as the critical inflection signal for supplier consolidation pressure across 5G-V2X connectivity module programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables subscription revenue capture across ownership lifecycle for German OEMs. |
| Edge-AI Voice Processing Development | Reduces cloud dependency latency for METI-compliant Japanese automaker platforms. |
| Geographic Manufacturing Footprint Expansion | India's PLI scheme attracts cockpit controller assembly from East Asian bases. |
| Platform Standardization | Consolidates instrument cluster and HUD functions onto single Linux domain controllers. |
| Charging Infrastructure Partnership | Integrates high-voltage SiC circuits with infotainment thermal management systems. |
Research Approach
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distribution channel heads, and dealership operations managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings from listed automotive electronics suppliers, IHS Markit vehicle production databases, ECE regulatory submission records, and METI software-defined vehicle standard documentation. Bottom-up segment sizing triangulated against top-down macroeconomic automotive production forecasts.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling volume and value outputs through vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from fitted growth curves applied to segment-level penetration rates and replacement cycle assumptions. Industry-specific forecast inputs included ECE R10 certification timeline data and PLI scheme incentive phase schedules.
Practitioners should monitor Korean display substrate allocation shifts and EU AI Act enforcement patterns for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Next Generation in-Vehicle Networking (IVN) Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
Telematics Market