
 Hazardous Goods Logistics Market | 2026-2036
Hazardous Goods Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Goods Logistics Market Outlook
Compliance management software is broadening what hazardous goods carriers sell beyond pure freight movement. Deutsche Post DHL Group leverages its global certification network to anchor premium contracts across pharmaceutical cold chains. Kühne + Nagel International AG specializes in temperature-controlled dangerous goods, while DSV competes through aggressive geographic expansion in European chemical corridors.
Hazardous goods logistics encompasses the specialized planning, handling, storage, and transport of materials classified under UN dangerous goods codes, requiring temperature monitoring, segregation protocols, and emergency response systems with specified containment ratings. The primary purpose is to move flammable, toxic, corrosive, or radioactive substances without incident across multimodal networks. Transportation services generate the largest revenue pool due to fuel surcharges and specialized fleet requirements, though compliance management commands the fastest expansion as shippers outsource regulatory documentation. Warehousing for flammable materials remains structurally constrained by zoning laws, creating margin premiums in approved facilities.
EPA and DOT regulations in the United States mandate specific packaging, labeling, and routing for hazardous transport, while the EU's ADR treaty governs road carriage across member states with mandatory vehicle and driver certifications. China's MEE enforces increasingly strict emissions and safety standards for chemical logistics corridors, raising barriers for uncertified operators. Stakeholders must monitor how divergent national enforcement timelines affect cross-border fleet deployment and insurance costs.
Market Dynamics
Regulatory harmonization between ADR and IMDG codes is compressing certification timelines while fragmenting fleet deployment across multimodal corridors, forcing operators to consolidate compliance infrastructure or exit cross-border lanes entirely.
Growth Catalysts
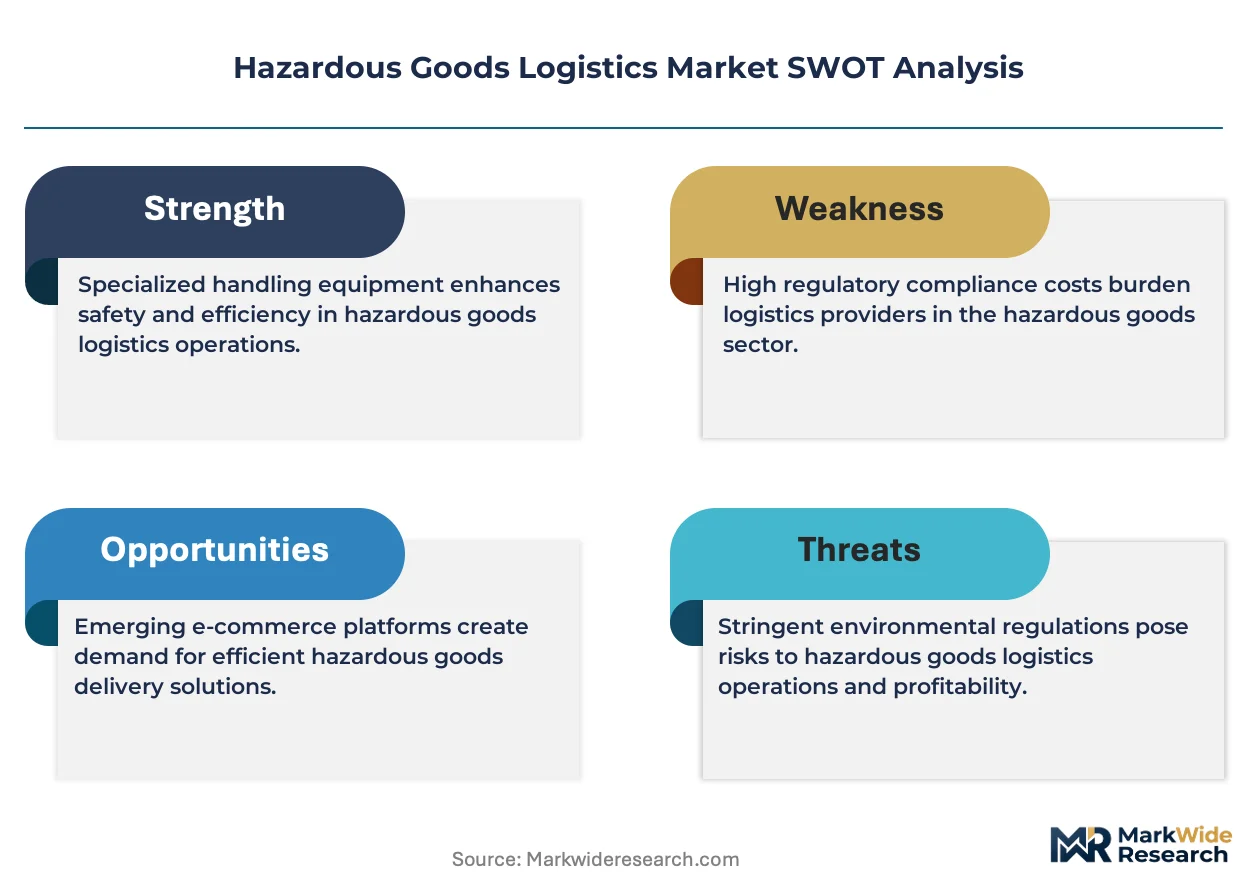
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics require GDP-compliant hazardous transport, pulling specialized reefer fleets into oncology and vaccine distribution networks across Germany and Switzerland.
- China's MEE emission standards:Stricter carbon intensity rules for chemical logistics are accelerating fleet replacement in the Shanghai-Ningbo corridor, creating demand for certified low-emission tank containers.
- ASEAN chemical manufacturing clusters:Indonesia and Vietnam are expanding petrochemical capacity, generating outbound hazardous cargo flows that exceed domestic logistics capabilities.
Market Restraints
- Specialized driver scarcity:ADR-certified operators face 18-24 month training pipelines, constraining fleet expansion faster than vehicle procurement cycles.
- Stainless steel tank container costs:Nickel price volatility directly impacts containment unit economics, squeezing margins on corrosive chemical contracts.
- Zoning law fragmentation:Municipal fire codes block flammable warehousing permits in Rotterdam, Antwerp, and Hamburg port zones simultaneously.
Strategic Opportunities
- India's chemical corridor buildout:Dahej and Mundra industrial zones lack integrated hazardous logistics parks, opening greenfield development for bonded warehousing with customs clearance.
- Digital twin integration:Real-time cargo monitoring combined with predictive maintenance is creating subscription-based risk management services beyond pure freight rates.
- Battery supply chain hazardous flows:Lithium-ion classification as Class 9 dangerous goods is generating new demand for thermal runaway containment systems in automotive logistics.
Industry Challenges
- Emergency response certification gaps:Fewer than 15% of European road carriers maintain active CHEMTREC protocols, exposing shippers to liability in incident scenarios.
- Legacy TMS integration:ERP systems at mid-sized chemical shippers lack dangerous goods documentation modules, delaying real-time customs filing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Goods Logistics Market |
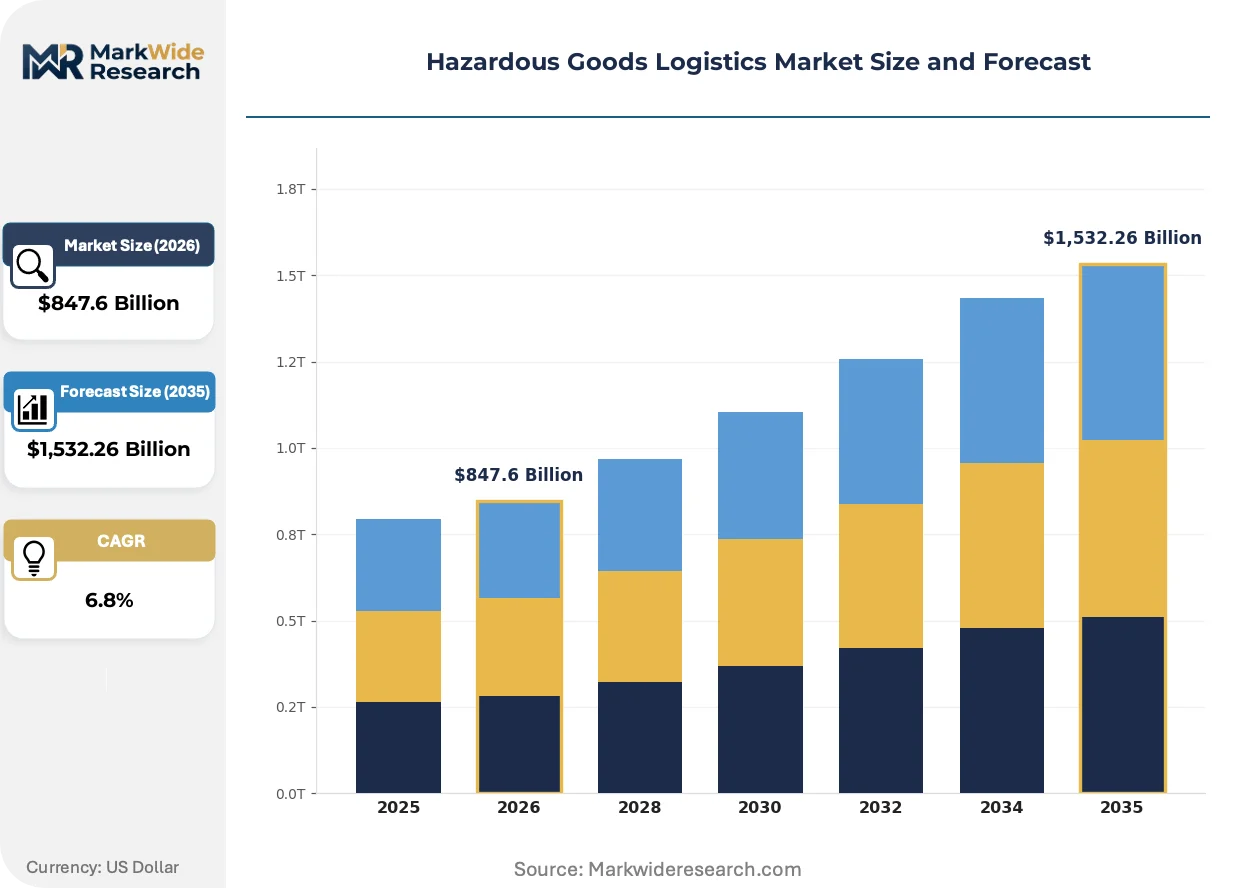
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,532.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Compliance Management End User: Pharmaceuticals, Chemicals, Energy, Manufacturing Product Type: Flammable Materials, Toxic Substances, Radioactive Materials, Corrosive Materials Delivery Mode: Road, Rail, Sea, Air |
| Companies Covered | Kühne + Nagel International AG, DB Schenker, Deutsche Post DHL Group, Bollore Logistics, Ceva Logistics, DSV, United Parcel Service Inc. (UPS), C.H. Robinson Worldwide Inc., FedEx Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Goods Logistics Market Strategic Shifts
Sensor density in cargo monitoring is climbing while regulatory APIs enable automated permit filing, compressing the gap between physical tracking and compliance documentation.
Blockchain-enabled documentation platforms are integrating customs declarations with dangerous goods manifests, creating immutable audit trails for lithium battery shipments. Automotive OEMs in South Korea and Germany are mandating these systems for inbound cathode material flows. The technology is integrating insurance underwriting with real-time cargo condition data, collapsing traditional risk-assessment timelines from weeks to hours.
REACH substance restriction updates are forcing reformulation of industrial coatings and adhesives, redirecting hazardous classification profiles across European chemical logistics networks. Downstream users in construction and electronics are scrambling to secure alternative supply chains before sunset dates. Specialty carriers with pre-certified alternative substance handling are capturing contract renewals at 40% premium spreads.
Shippers are unbundling compliance management from transportation procurement, engaging specialized software vendors for documentation while negotiating freight rates separately. Chemical manufacturers in Belgium and the Netherlands are leading this split, driving demand for API-first compliance platforms that integrate with existing TMS investments. The shift is most visible in pharmaceutical intermediates, where batch-level traceability requirements exceed standard carrier capabilities.
Hazardous Goods Logistics Market Segmentation
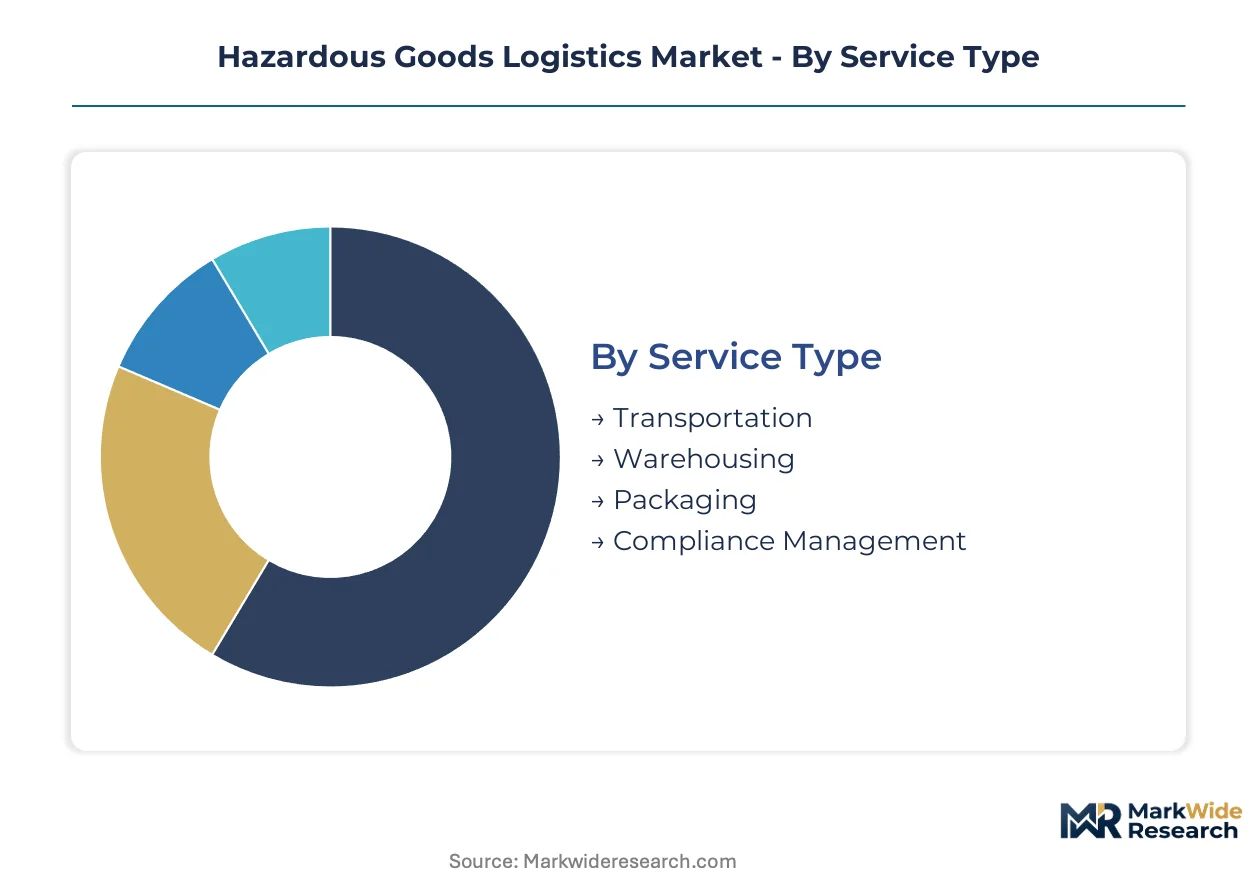
Hazardous goods logistics operators segment capabilities around containment ratings, modal certifications, and end-use regulatory intensity. Each service tier carries distinct capital requirements and margin profiles that reshape competitive positioning across chemical corridors.
Service Type:
Fleet replacement cycles and certification upgrades determine which service tiers absorb capital investment. Operators with aging road tankers face compressed timelines to meet evolving emissions and safety standards.
- Transportation:Road tankers, railcars, and intermodal containers rated for UN dangerous goods classes dominate capital deployment. Demand concentrates in Germany's Rhine-Ruhr chemical belt, where ADR-certified fleets serve BASF and Covestro facilities under long-term contracts. Nickel price volatility in stainless steel tank manufacturing squeezes procurement budgets for corrosive chemical haulage.
- Warehousing:Temperature-controlled storage with fire suppression systems and segregation protocols commands structural premiums. China's MEE emission standards are accelerating warehouse modernization in the Shanghai-Ningbo corridor, where flammable liquid storage permits face tightening zoning constraints.
- Packaging:UN-certified drums, IBCs, and flexible intermediate bulk containers with specified containment ratings. Pharmaceutical shippers in Switzerland and Belgium drive demand for GDP-compliant primary packaging with integrated temperature monitors.
- Compliance Management:Documentation software, customs filing APIs, and dangerous goods classification services. Chemical manufacturers in the Netherlands are unbundling this function from freight procurement, creating standalone subscription revenue pools.
Transportation sits at the top of the volume ranking, with compliance management climbing the fastest.
End User:
Customer concentration patterns vary sharply by regulatory intensity and shipment frequency. High-velocity shippers with batch-level traceability needs extract premium service tiers.
- Pharmaceuticals:Temperature-sensitive biologics and cytotoxic oncology compounds require GDP-validated cold chains with real-time deviation alerts. Roche and Novartis operations in Basel anchor specialized reefer fleet deployment across Alpine corridors into Italy and France.
- Chemicals:Petrochemical intermediates, agrochemicals, and specialty solvents generate the highest shipment volumes. Dahej and Mundra industrial zones in India lack integrated hazardous logistics parks, forcing reliance on fragmented domestic carriers.
- Energy:Lubricants, drilling fluids, and refinery catalysts with flammable or corrosive classifications. Offshore supply logistics in the North Sea and Gulf of Mexico require marine pollutant handling certifications.
- Manufacturing:Automotive coatings, electronics adhesives, and battery electrolytes. South Korean cathode material producers are mandating blockchain-enabled documentation for inbound lithium compound flows.
Chemicals anchors the revenue base by shipment volume, with pharmaceuticals expanding most quickly on cold chain premiums.
Product Type:
Containment specifications and emergency response protocols diverge substantially across hazard classes. Carrier certification portfolios determine which product categories operators may legally handle.
- Flammable Materials:Class 3 liquids and gases with flash point thresholds below 60°C. Rotterdam and Antwerp port zones face simultaneous municipal fire code restrictions on warehouse permitting, creating supply scarcity for approved storage.
- Toxic Substances:Class 6.1 poisons and infectious substances requiring sealed containment and specialized decontamination capabilities. Vaccine distribution networks during health emergencies pull certified carriers into government contingency contracts.
- Radioactive Materials:Class 7 shipments with dose rate limits and exclusive use vehicle requirements. Medical isotope logistics between European cyclotron facilities and hospitals operate on rigid scheduling with minimal carrier competition.
- Corrosive Materials:Class 8 acids and bases attacking living tissue or steel. Stainless steel tank container procurement costs fluctuate with nickel exchange prices, compressing margins on sulfuric acid and caustic soda contracts.
Flammable materials holds the largest shipment volume, with radioactive materials gaining share fastest on medical isotope demand.
Delivery Mode:
Modal choice reflects distance economics, regulatory harmonization, and cargo security requirements. Multimodal operators consolidate compliance infrastructure across ADR, RID, IMDG, and IATA codes.
- Road:ADR-certified vehicles with specified tank codes and driver training hours. The 18-24 month pipeline for qualified operators constrains fleet expansion faster than vehicle procurement cycles in European chemical corridors.
- Rail:RID-regulated tank wagons and intermodal tank containers on dedicated chemical trains. Rhine-Alpine freight corridors connect Antwerp and Rotterdam to Swiss chemical producers with lower carbon intensity than road alternatives.
- Sea:IMDG Code compliance for containerized and bulk hazardous cargo. Indonesia and Vietnam petrochemical export growth exceeds domestic logistics capabilities, pulling international tank container operators into ASEAN lanes.
- Air:IATA Dangerous Goods Regulations limit quantities per package and mandate cargo-only aircraft for highest-risk classes. Pharmaceutical cold chain expansion pulls certified freighter capacity into oncology and vaccine distribution networks.
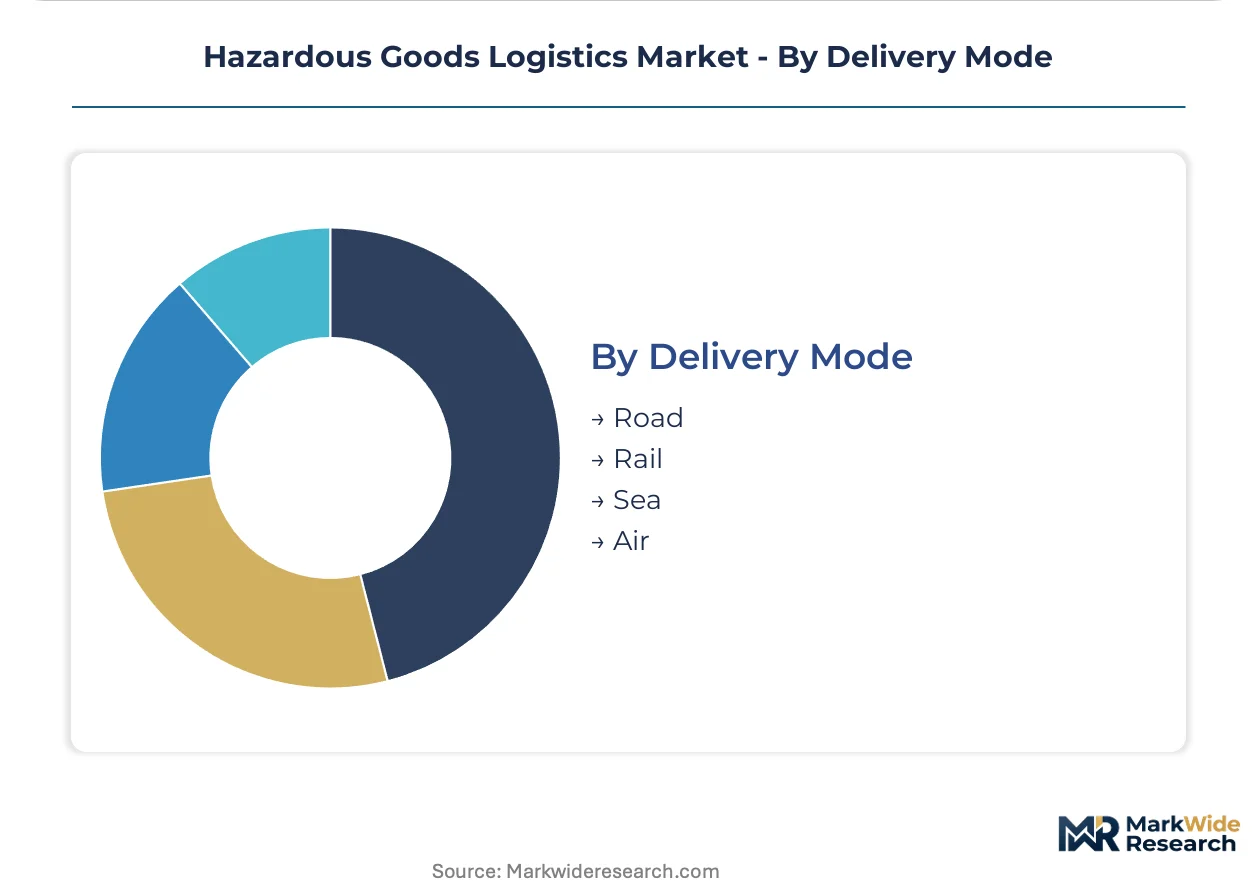
Road commands the highest shipment frequency, with sea freight scaling fastest on ASEAN chemical export growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr chemical belt generates higher hazardous cargo volumes per capita than the United States Gulf Coast, yet both corridors face tightening emissions standards that favor certified low-emission fleets.
United States
Pharmaceutical cold chain expansion and shale-derived petrochemical exports drive hazardous logistics demand. EPA and DOT regulations mandate specific packaging and routing protocols. The Houston Ship Channel anchors tank container deployment for Gulf Coast refineries and chemical producers.
Germany
BASF and Covestro facilities generate continuous flows of corrosive and flammable intermediates. ADR treaty requirements govern road carriage with mandatory vehicle and driver certifications. The Rhine-Ruhr chemical belt concentrates ADR-certified fleet deployment under long-term industrial contracts.
China
Shanghai-Ningbo industrial corridor expansion outpaces domestic certified logistics capacity. MEE emission standards accelerate fleet replacement and warehouse modernization. Zhejiang province chemical manufacturers increasingly outsource compliance management to specialized operators.
Switzerland
Roche and Novartis operations require GDP-validated cold chains for cytotoxic oncology compounds. Swissmedic regulations enforce batch-level traceability exceeding standard carrier capabilities. Basel anchors specialized reefer fleet deployment across Alpine corridors into Italy and France.
India
Dahej and Mundra petrochemical zones lack integrated hazardous logistics infrastructure. CDSCO and central pollution control standards raise barriers for uncertified warehouse operators. Gujarat state industrial corridors attract greenfield bonded warehousing development with customs clearance integration.
Hazardous Goods Logistics Market Competitive Environment
Top-tier vendors anchor premium certification networks, while mid-scale operators compete on corridor-specific density. The vendor base stratifies across global integrators, regional chemical specialists, and asset-heavy tank container operators. Three archetypes dominate: certification-anchored premium service providers, temperature-controlled dangerous goods specialists, and geographic expansion-driven consolidators. Capacity replacement and compliance infrastructure consolidation represent the dominant competitive vectors.
Within the global integrator tier, Deutsche Post DHL Group and Kühne + Nagel International AG exemplify certification-anchored positioning, while DSV occupies a scale-driven expansion archetype. Deutsche Post DHL leverages global certification networks to secure pharmaceutical cold chain contracts. Kühne + Nagel represents temperature-controlled dangerous goods specialization. DSV exemplifies geographic consolidation strategy across European chemical corridors.
| Leading Market Players |
|---|
| Kühne + Nagel International AG |
| DB Schenker |
| Deutsche Post DHL Group |
| Bollore Logistics |
| Ceva Logistics |
| DSV |
| United Parcel Service Inc. (UPS) |
| C.H. Robinson Worldwide Inc. |
| FedEx Corporation |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical shippers unbundling compliance management from freight procurement are forcing carriers to restructure service offerings and absorb documentation costs into rate negotiations. This procurement shift concentrates pricing power with operators holding pre-certified GDP and ADR networks.
Pricing Analysis
Capacity additions in Germany's Rhine-Ruhr corridor are reshaping price floors for ADR-certified road tanker services. Three-tier pricing structure across premium certification, standard compliance, and economy brokerage levels dominates contract structures. Price differentiation hinges on real-time cargo monitoring integration and driver training hour thresholds. Cost compression in standard-tier haulage is intensifying because nickel price volatility inflates stainless steel tank procurement budgets. Chemical manufacturers exhibit highest price sensitivity, while pharmaceutical cold chain buyers prioritize deviation-alert capabilities over rate competition.
Supply Chain Analysis
Dual-sourcing mandates from BASF and Covestro facilities require carriers to maintain parallel certification networks across ADR, RID, and IMDG codes. Supply concentration centers on Germany, China, and the Netherlands for specialized tank container manufacturing. Raw material dependencies draw from stainless steel nickel alloys, fire suppression system components, and GDP-validated reefer units. Single-source vulnerability persists in ADR-certified driver training pipelines. Distribution runs through port-centric warehousing clusters in Rotterdam, Antwerp, and Hamburg with bonded customs clearance integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where MEE emission standards in China compress margins for domestic operators faster than EU ADR compliance costs rise, favoring cross-border fleet deployment into Shanghai-Ningbo lanes.
For Market Incumbents: Anticipate certification harmonization between ADR and IMDG codes compressing compliance infrastructure investments into consolidated platforms. Defensive consolidation around temperature-controlled dangerous goods capabilities anchors premium contract renewal rates. Capacity addition in India's Dahej-Mundra corridor offsets European zoning law constraints on warehouse permitting. For New Entrants and Emerging Players: Capture greenfield bonded warehousing demand in Gujarat state industrial zones where integrated hazardous logistics parks remain underdeveloped. India's chemical corridor buildout represents the most penetrable geography for asset-heavy entrants. Go-to-market positioning through customs clearance integration with CDSCO documentation protocols differentiates against fragmented domestic carriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale operators holding regional certification density in ASEAN chemical export lanes. Long-term viability rests on fleet replacement cycles aligning with low-emission tank container standards. Acquisition targets with active CHEMTREC emergency response protocols signal defensible margin structures. Watch lithium-ion Class 9 classification enforcement as inflection indicator for thermal runaway containment system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Consolidation | ADR-RID-IMDG harmonization reduces redundant compliance costs for Rhine-Alpine multimodal operators. |
| Greenfield Warehouse Development | Bonded hazardous logistics parks in Dahej and Mundra capture customs-integrated demand from petrochemical expansions. |
| Digital Twin Integration | Real-time cargo monitoring subscriptions create recurring revenue beyond transactional freight rates. |
| Low-Emission Fleet Replacement | MEE-compliant tank containers in Shanghai-Ningbo corridor secure contract renewals from Zhejiang chemical manufacturers. |
| Emergency Response Certification | CHEMTREC protocol activation differentiates carriers in pharmaceutical liability-sensitive segments. |
Study Parameters
Direct dialogue with ADR-certified fleet operators, pharmaceutical logistics procurement leads, chemical plant supply chain directors, and customs brokerage specialists grounded qualitative findings. Secondary validation drew from EU ADR treaty documentation, China MEE emission standard filings, IMDG Code amendment records, and customs trade flow databases. Bottom-up carrier capacity assessments and top-down chemical production volume projections were triangulated against documented contract structures.
Segment-level revenue estimates across transportation, warehousing, packaging, and compliance management services were generated across the analysis window. Mode-specific modeling incorporated road tanker deployment, rail tank wagon utilization, and intermodal container flows. End-use segmentation tracked pharmaceutical cold chain, petrochemical intermediate, and battery supply chain hazardous flows. CAGRs were derived from capacity replacement cycles, certification upgrade timelines, and regional chemical production growth trajectories.
Regulatory enforcement timeline shifts, nickel price volatility spikes, and ADR-certified driver training pipeline disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about harmonization pace between regional dangerous goods codes and emission standard implementation schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
Mexico Logistics Market
Logistics and Shipping
US Hazardous Goods Logistics Market