
 Automotive Digital Cockpit Market | 2026-2036
Automotive Digital Cockpit Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Cockpit Market Intelligence
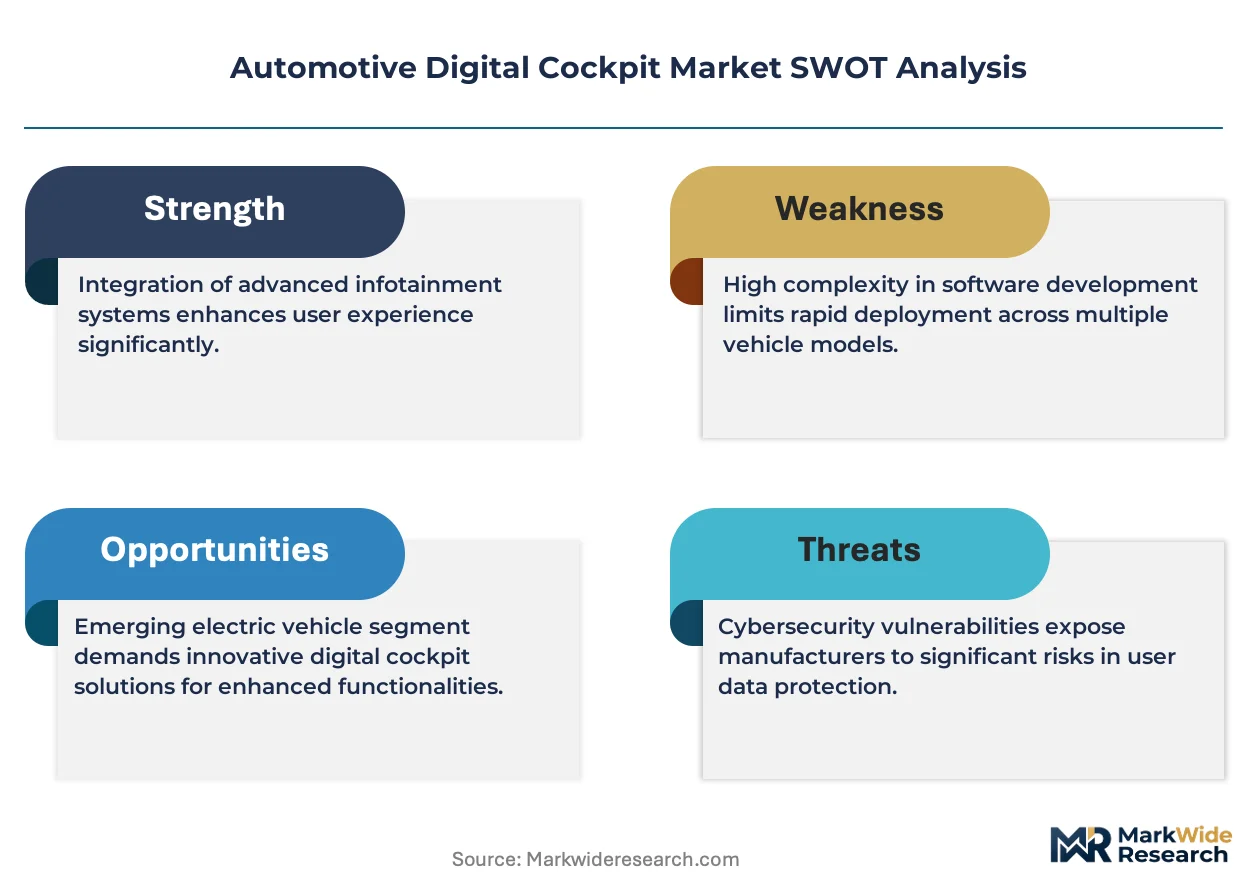
The EU AI Act is consolidating the cost-of-entry calculus for automotive digital cockpit suppliers by mandating algorithmic transparency and risk classification for AI-driven interfaces. Continental AG leverages its embedded software heritage to sustain compliance leadership across European OEM programs. Robert Bosch GmbH anchors its position through in-house semiconductor sourcing for display controllers. Visteon Corporation competes on modular platform architectures that reduce integration complexity for North American and Asian vehicle manufacturers.
An automotive digital cockpit integrates multiple electronic display surfaces, instrument clusters, head-up projections, and AI-driven human-machine interfaces within a unified software-defined architecture, typically operating on centralized compute platforms with 20-40 GB/s internal data throughput to synchronize real-time vehicle telemetry with infotainment and navigation content. Its primary commercial purpose is to consolidate discrete control domains into a seamless user experience that reduces driver cognitive load while enabling subscription-based feature monetization for OEMs. Display systems and head-up displays command the dominant share of current bill-of-material value as OEMs prioritize screen real estate differentiation in showrooms. Artificial intelligence and augmented reality segments are expanding fastest as automakers deploy predictive interfaces and AR navigation overlays to justify premium pricing tiers. The electric vehicle application category is pulling disproportionate investment because EV architectures natively support centralized compute and over-the-air update pipelines that digital cockpits require.
FDA scrutiny of driver monitoring systems, ECE R79 requirements for steering interface safety, and China's GB standards for in-vehicle software security collectively shape product development roadmaps and homologation timelines across major supply bases. NHTSA distraction guidelines and the EU Green Deal's embedded carbon reporting through CSRD extend compliance obligations upstream to display panel and semiconductor suppliers. Stakeholders must monitor divergence between European algorithmic accountability mandates and Chinese data localization rules to determine whether single global software stacks remain viable or regional variants become mandatory.
Market Dynamics
Centralized compute architectures are collapsing legacy domain-separated electronics into unified software-defined platforms, forcing tier-one suppliers to abandon discrete instrument cluster and infotainment silos in favor of consolidated cockpit controllers with 20-40 GB/s internal throughput.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Risk classification requirements for AI-driven interfaces are accelerating OEM demand for pre-validated software stacks from established European suppliers.
- Electric vehicle platform pull:Native centralized compute and over-the-air update pipelines in EV architectures eliminate retrofit barriers that constrain ICE vehicle cockpit upgrades.
- Germany's automotive electronics manufacturing clusters:Concentrated OEM headquarters around Stuttgart, Munich, and Wolfsburg generate localized demand for integrated display system sourcing.
Market Restraints
- Semiconductor supply concentration:Display controller and high-bandwidth memory sourcing remains captive to Taiwan and South Korean foundry capacity, exposing programs to allocation volatility.
- ECE R79 steering interface validation:Software verification timelines for force-feedback and automated steering integration extend homologation cycles by 8-14 months.
- AMOLED panel cost structure:Premium substrate and driver IC costs constrain adoption to flagship vehicle trims, limiting volume scale economies.
Strategic Opportunities
- China's GB standards for in-vehicle software security:Mandatory cybersecurity certification creates captive demand for localized software engineering and compliance consulting services.
- Augmented reality head-up display convergence:Integration of navigation overlays with ADAS visual warnings opens subscription monetization channels for OEMs.
- Direct-to-OEM software licensing:Bypassing tier-one hardware integrators to sell AI-driven HMI modules directly to vehicle manufacturers compresses margin extraction layers.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates in Germany and Japan, creating recruitment bottlenecks for new market entrants.
- Legacy CAN bus integration friction:Harmonizing 500 kbps vehicle network protocols with zonal Ethernet architectures requires expensive gateway hardware and software abstraction layers.
- Cross-border data governance fragmentation:Divergent GDPR, PIPL, and state-level privacy mandates force redundant software variants and regional cloud infrastructure duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Cockpit Market |
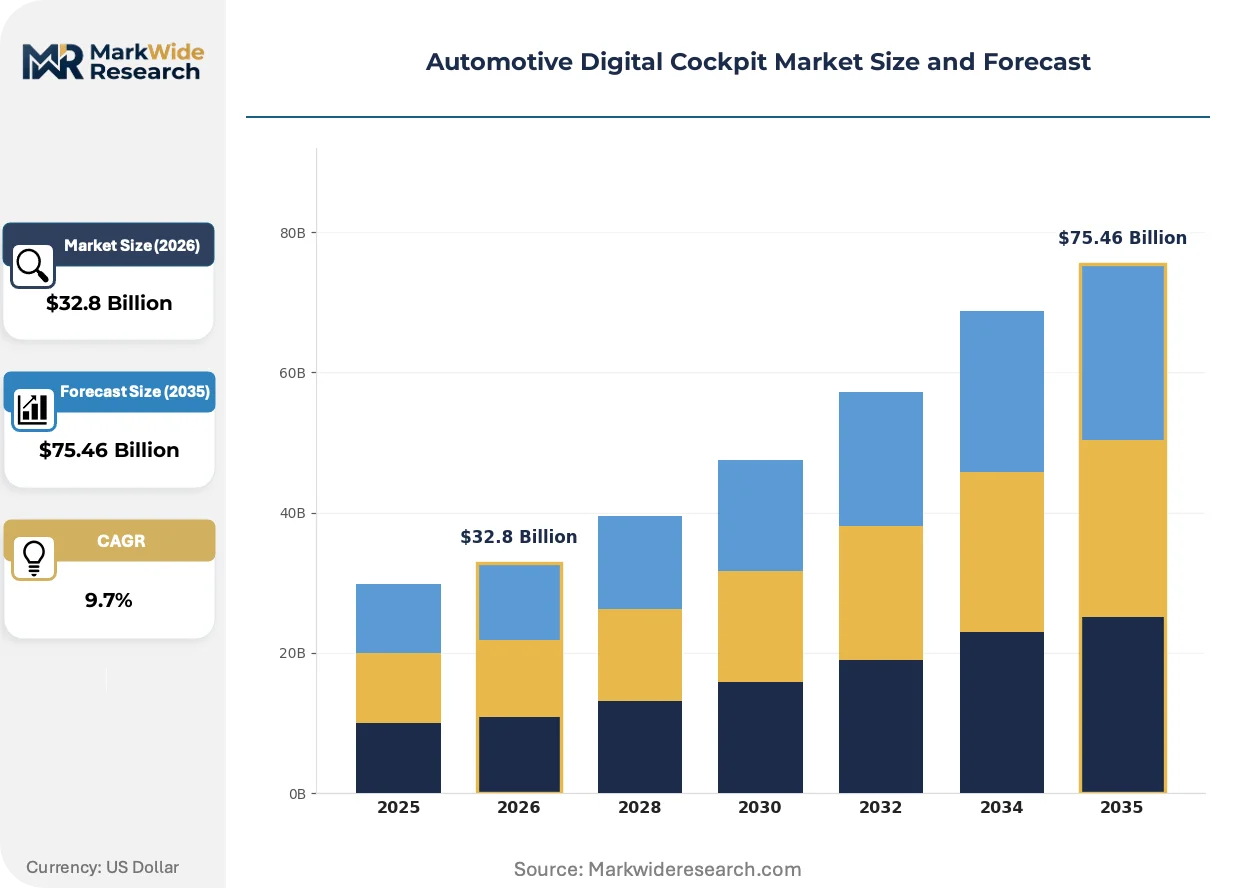
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $75.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Systems, Instrument Clusters, Multi-Functional Displays, Head-Up Displays Technology: Artificial Intelligence, IoT Connectivity, Advanced Driver Assistance Systems, Augmented Reality End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Connected Vehicles |
| Companies Covered | Visteon Corporation, Hyundai Mobis, Continental AG, Aptiv PLC, Panasonic Holdings Corporation, Robert Bosch GmbH, Harman International, ZF Friedrichshafen AG, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Cockpit Market Strategic Shifts & Innovations
Software-defined vehicle architectures are dissolving hardware boundaries between instrument clusters, infotainment, and climate controls, creating new competitive arenas for operating system vendors and cloud service providers.
Qualcomm's Snapdragon Cockpit Platforms are rewriting the silicon economics of dashboard integration by consolidating GPU, AI acceleration, and 5G modem functions onto single SoC die. Premium passenger vehicle OEMs in Germany and the United States are adopting these controllers at 18-month refresh cycles, compressing the traditional 5-7 year electronics platform lifespan.
Europe's CSRD embedded carbon reporting requirements are extending compliance obligations upstream to display panel and semiconductor suppliers. Manufacturers must now document Scope 3 emissions from glass substrate production and wafer fabrication, with German OEMs demanding supplier certification by 2027.
Fleet operators and mobility-as-a-service providers are unbundling cockpit feature subscriptions from vehicle purchase price. Commercial vehicle buyers in North America now expect over-the-air activation of navigation, driver monitoring, and entertainment functions on monthly terms, shifting revenue recognition patterns for tier-one integrators.
Automotive Digital Cockpit Market Segmentation
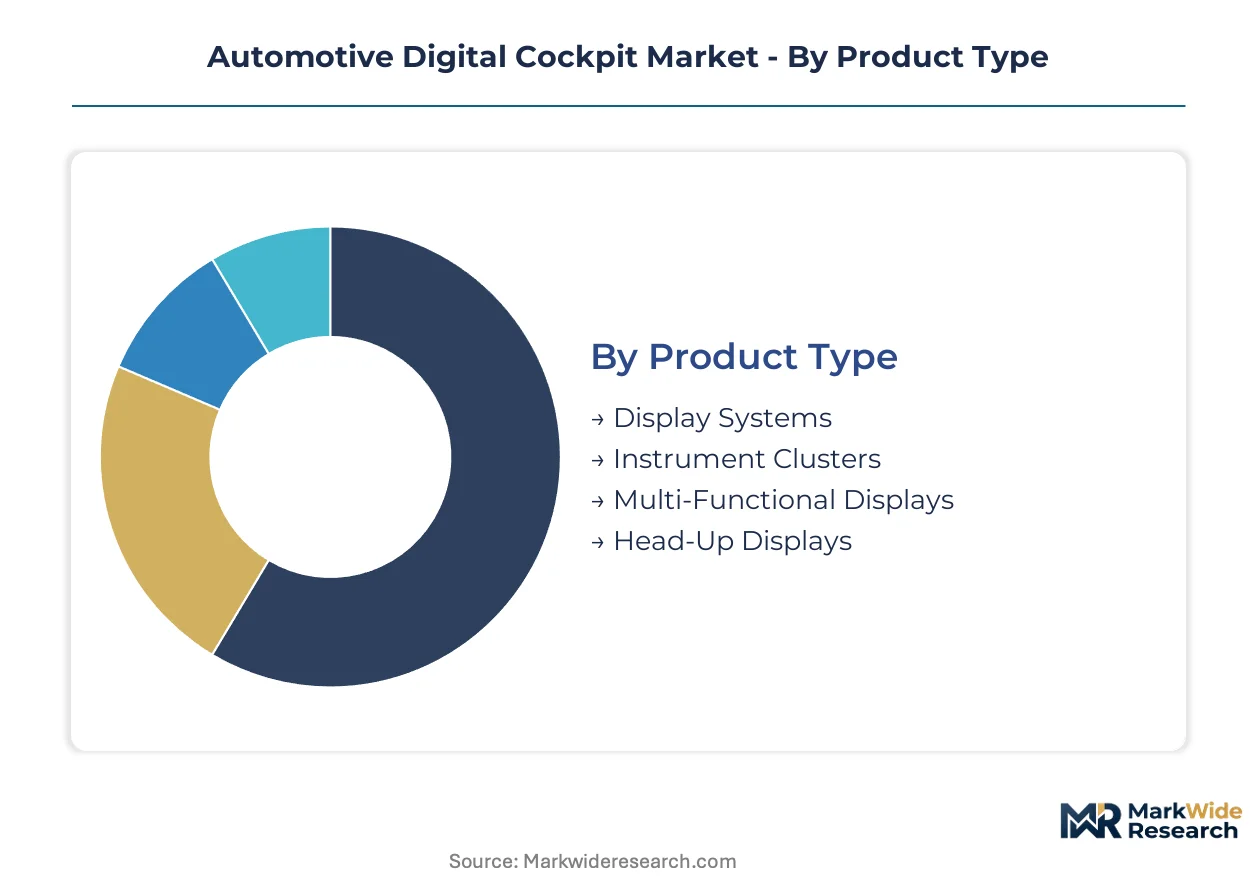
Segmentation in automotive digital cockpits reveals how capital allocation and technical complexity concentrate across display hardware, software layers, and integration services. Suppliers must align R&D budgets with the specific cost structures and validation requirements of each segment tier.
Product Type:
Display Systems and Head-Up Displays demand the heaviest upfront capital commitment due to AMOLED substrate investments and precision optical component tooling.
- Display Systems:Large-format curved panels with local dimming zones and haptic feedback layers dominate bill-of-material value. German OEMs in Stuttgart and Munich specify these for flagship sedans where screen real estate drives showroom differentiation.
- Head-Up Displays:Windshield projection systems with augmented reality overlays require waveguide optics and high-brightness laser diode arrays. Demand clusters in premium electric vehicle programs where AR navigation justifies subscription pricing tiers.
- Instrument Clusters:Digital gauge replacements with ASIL-B safety ratings.
- Multi-Functional Displays:Consolidated touch surfaces replacing physical climate and media controls.
Most installed capacity flows through Display Systems. Expansion is steepest in Head-Up Displays.
Technology:
Software-intensive segments carry lower fixed asset requirements than hardware but demand sustained engineering payroll for algorithm development and regulatory validation.
- Artificial Intelligence:Predictive HMI engines and natural language processing modules personalize driver interfaces through behavioral learning. China's GB standards for algorithmic accountability and the EU AI Act risk classification are concentrating procurement with European and Chinese suppliers who maintain dedicated compliance teams.
- Augmented Reality:Real-time navigation overlays fused with ADAS visual warnings reduce driver cognitive load. North American OEMs deploy these in connected vehicle fleets to enable usage-based insurance partnerships.
- IoT Connectivity:5G-V2X integration and cloud-edge synchronization protocols.
- Advanced Driver Assistance Systems:Camera fusion and sensor integration middleware for cockpit visualization.
Artificial Intelligence captures the majority of current R&D expenditure. Augmented Reality is climbing the fastest.
End User:
Customer type determines contract structure and margin profile, with direct OEM relationships offering volume scale but stringent qualification timelines.
- OEMs:Vehicle manufacturers specifying complete cockpit platforms for new vehicle programs. Volkswagen Group and BMW in Germany consolidate sourcing through multi-year framework agreements that lock in semiconductor allocation priority.
- Tier-1 Suppliers:System integrators assembling sub-assemblies for OEM delivery. These intermediaries in the United States and Japan manage regulatory homologation burden across multiple OEM customers.
- Aftermarket Providers:Retrofit specialists serving vehicle modification shops and fleet upgraders.
- Vehicle Assemblers:Contract manufacturers building white-label or regional-brand vehicles.
OEMs absorb the largest share of production volume. Aftermarket Providers are gaining share fastest.
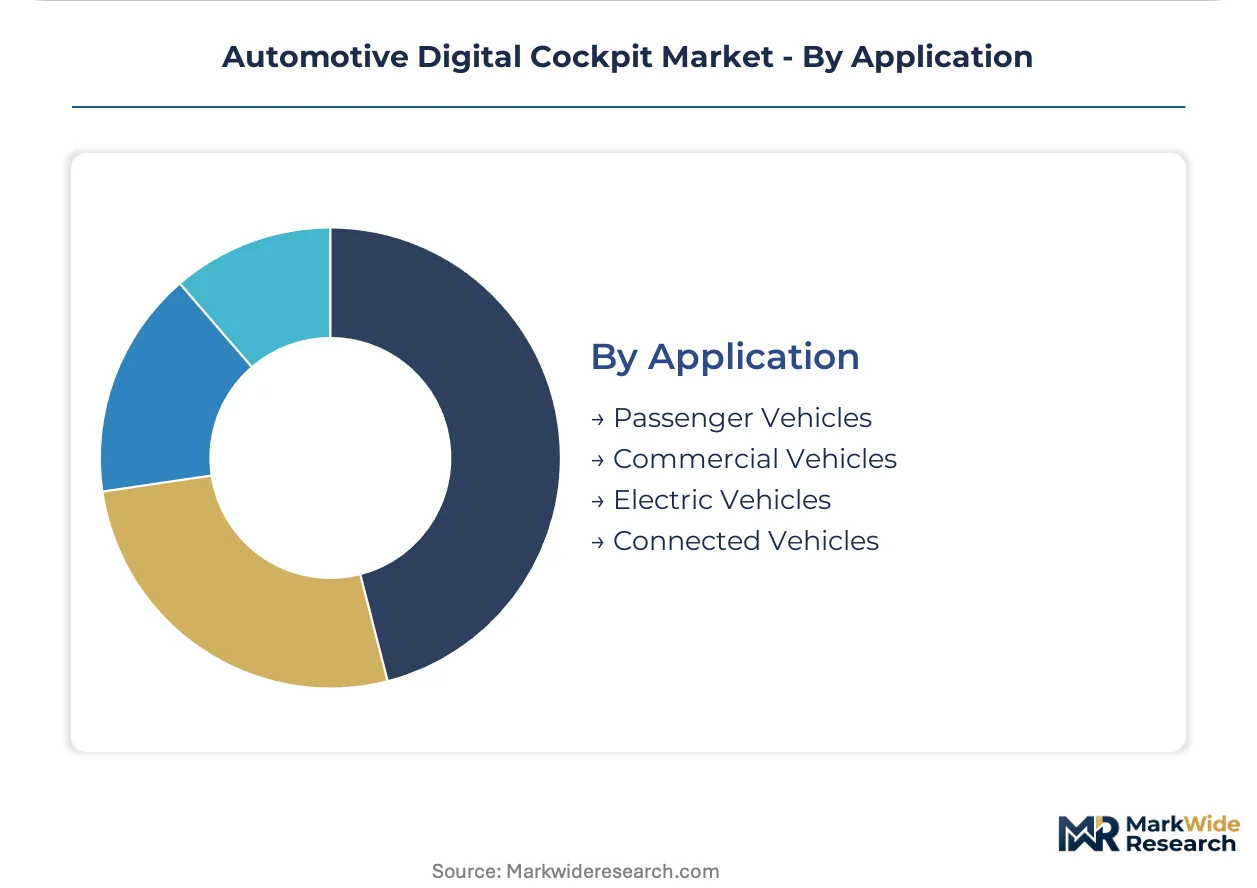
Application:
Vehicle electrification status and connectivity level reshape cockpit architecture requirements and update cadence.
- Electric Vehicles:Native centralized compute platforms with zonal Ethernet architectures support over-the-air software pipelines. Chinese EV manufacturers in Shenzhen and Shanghai specify digital cockpits as standard equipment across all trim levels.
- Connected Vehicles:Always-online architectures enabling real-time traffic, remote diagnostics, and feature subscriptions. German and United States OEMs deploy these in premium segments where recurring revenue offsets hardware margin pressure.
- Passenger Vehicles:Private ownership models with personalization-focused interfaces.
- Commercial Vehicles:Fleet-optimized layouts prioritizing durability and driver monitoring compliance.
Electric Vehicles channel the bulk of new platform investment. Connected Vehicles show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional safety engineers cluster in Germany and Japan, creating talent scarcity elsewhere that shapes regional investment patterns. This concentration dictates where cockpit controller validation work flows and which supply bases capture premium platform programs.
Germany
Stuttgart, Munich, and Wolfsburg host OEM headquarters driving integrated display system sourcing. ECE R79 steering regulations mandate extended software verification timelines for force-feedback interfaces. Continental AG and Robert Bosch GmbH anchor supplier networks across Baden-Württemberg and Bavaria.
China
Shenzhen and Shanghai EV manufacturers specify digital cockpits as standard equipment across all trim levels. GB standards for in-vehicle software security require mandatory cybersecurity certification. Display panel and semiconductor suppliers concentrate in the Yangtze River Delta and Pearl River Delta manufacturing corridors.
United States
Michigan and California house automotive electronics clusters around Detroit and Silicon Valley. NHTSA distraction guidelines influence human-machine interface design constraints. Qualcomm's Snapdragon Cockpit Platforms drive silicon consolidation among premium passenger vehicle OEMs in the Midwest and West Coast.
Japan
ISO 26262 ASIL-D certification expertise concentrates in Nagoya and Tokyo metropolitan areas. METI industrial policy supports next-generation cockpit controller development. Denso Corporation and Panasonic Holdings Corporation maintain embedded software heritage across Chubu and Kanto regions.
South Korea
Seoul Capital Area and Busan-Ulsan corridor host high-bandwidth memory and display controller foundry capacity. MFDS regulatory frameworks for embedded systems shape validation requirements. Hyundai Mobis anchors tier-one integration capabilities for domestic and export vehicle programs.
Automotive Digital Cockpit Market Key Industry Players
The competitive structure tilts toward diversified technology conglomerates with captive semiconductor sourcing. Tier-one suppliers compete on pre-validated software stacks that compress OEM homologation cycles. Three archetypes dominate: European embedded software specialists, Asian diversified electronics groups, and North American modular platform architects. Consolidation pressure intensifies through strategic partnerships for centralized compute silicon and geographic expansion into Chinese EV supply chains.
Among European-based suppliers, Continental AG and Robert Bosch GmbH exemplify the embedded software heritage archetype, occupying positions sustained by compliance leadership across EU AI Act mandates. Visteon Corporation represents the modular platform approach, sitting within the North American supplier tier that competes on integration complexity reduction for multinational OEM programs.
| Leading Market Players |
|---|
| Visteon Corporation |
| Hyundai Mobis |
| Continental AG |
| Aptiv PLC |
| Panasonic Holdings Corporation |
| Robert Bosch GmbH |
| Harman International |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
Europe's CSRD embedded carbon reporting gates qualified supply access and premium-tier pricing for cockpit display systems, forcing German OEMs to certify suppliers by 2027 while AMOLED panel costs constrain adoption to flagship trims. This sustainability mandate bifurcates the supplier base between certified premium providers and excluded commodity players.
Pricing Analysis
The bundled-vs-unbundled service split separates traditional hardware-transactional contracts from emerging subscription models for AI-driven HMI features. Pricing stratifies across premium, standard, and economy tiers based on ASIL certification grade and display panel technology. Cost compression in standard-tier instrument clusters intensifies as Chinese EV manufacturers drive volume scale. Fleet operators show highest price sensitivity, while German luxury OEMs absorb premium-tier hardware costs without negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen Group and BMW, bypassing traditional tier-one integrators for software modules. Taiwan and South Korea anchor display controller and high-bandwidth memory sourcing, drawing from glass substrate foundries and precision optical component suppliers. Single-source vulnerability in AMOLED driver ICs exposes programs to allocation volatility. Distribution runs through consolidated electronics manufacturing clusters around Stuttgart, Shenzhen, and Detroit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential as software-defined architectures shift revenue toward recurring subscription streams and away from hardware-only transactions. Centralized compute platforms reduce bill-of-material complexity while enabling feature monetization.
For Market Incumbents: Deploy pre-validated software stacks to compress OEM homologation cycles threatened by ECE R79 verification timeline extensions. Deepen backward integration into semiconductor sourcing to secure allocation priority against foundry capacity constraints. Lock in multi-year framework agreements with German OEMs before Chinese EV manufacturers consolidate alternative supplier relationships. For New Entrants and Emerging Players: China's GB standards for in-vehicle software security open a window for localized compliance consulting services and cybersecurity certification partnerships. Target aftermarket retrofit specialists serving fleet upgraders in North America as the most penetrable entry point. Lead with direct-to-OEM AI-driven HMI licensing to bypass established tier-one margin extraction layers. For Investors and Strategic Acquirers: Valuations sit cheapest among modular platform architects with exposure to North American OEM refresh cycles. Five-to-ten year viability hinges on capturing subscription revenue share from software-defined vehicle architectures. Monitor divergence between European algorithmic accountability mandates and Chinese data localization rules as the inflection signal for regional software stack viability.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Qualcomm's Snapdragon Cockpit Platforms consolidate GPU, AI acceleration, and 5G modem functions onto single SoC die. |
| Geographic Manufacturing Footprint | Yangtze River Delta and Pearl River Delta corridors capture Chinese EV manufacturer standard-equipment demand. |
| Platform Standardization | Continental AG leverages embedded software heritage to sustain compliance leadership across EU AI Act mandates. |
| Battery Supply Agreement | Electric vehicle platform pull eliminates retrofit barriers that constrain ICE vehicle cockpit upgrade timelines. |
| Charging Infrastructure Partnership | Over-the-air update pipelines in EV architectures enable subscription monetization for tier-one integrators. |
Research Approach
Coverage spans Germany, China, the United States, Japan, and South Korea, with primary inputs from each regional automotive electronics cluster. The analysis combines structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and customs records. Bottom-up segment sizing triangulates against top-down market reconstruction across the analysis window.
Granularity-level modeling disaggregates volume and value outputs by vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from segment-specific growth trajectory analysis incorporating electric vehicle penetration curves, software subscription adoption rates, and regulatory compliance timeline impacts. Industry-specific forecast inputs include semiconductor allocation forecasts and AMOLED panel capacity expansion schedules.
Revisions become necessary when macroeconomic shocks, regulatory divergence, or technology substitution materialize outside modeled assumptions. Forecasts reflect documented assumptions about EV platform standardization timelines and OEM software stack consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Automotive Logging Device Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Vehicle Networking Market