
 Connected Car Devices Market | 2026-2036
Connected Car Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Car Devices Market Intelligence
Procurement patterns for in-vehicle connectivity hardware is shifting from a model dominated by OEM direct sourcing to a more complex ecosystem involving Tier-1 suppliers and aftermarket specialists. Robert Bosch GmbH leverages its extensive portfolio across vehicle domains to offer integrated solutions. Continental AG specializes in system-level integration of telematics and infotainment. Qualcomm Technologies dominates the underlying cellular modem and processor technology, supplying critical components to multiple tiers of the value chain.
Connected car devices are electronic modules that equip vehicles with communication capabilities, enabling data exchange with other vehicles, infrastructure, and cloud services. These units typically integrate cellular modems, such as 5G NR modules, and high-precision GNSS receivers. Their primary function is to support applications ranging from safety and navigation to telematics. While established infotainment systems form a large part of the market, Advanced Driver Assistance Systems and Vehicle-to-Everything modules are seeing accelerated adoption.
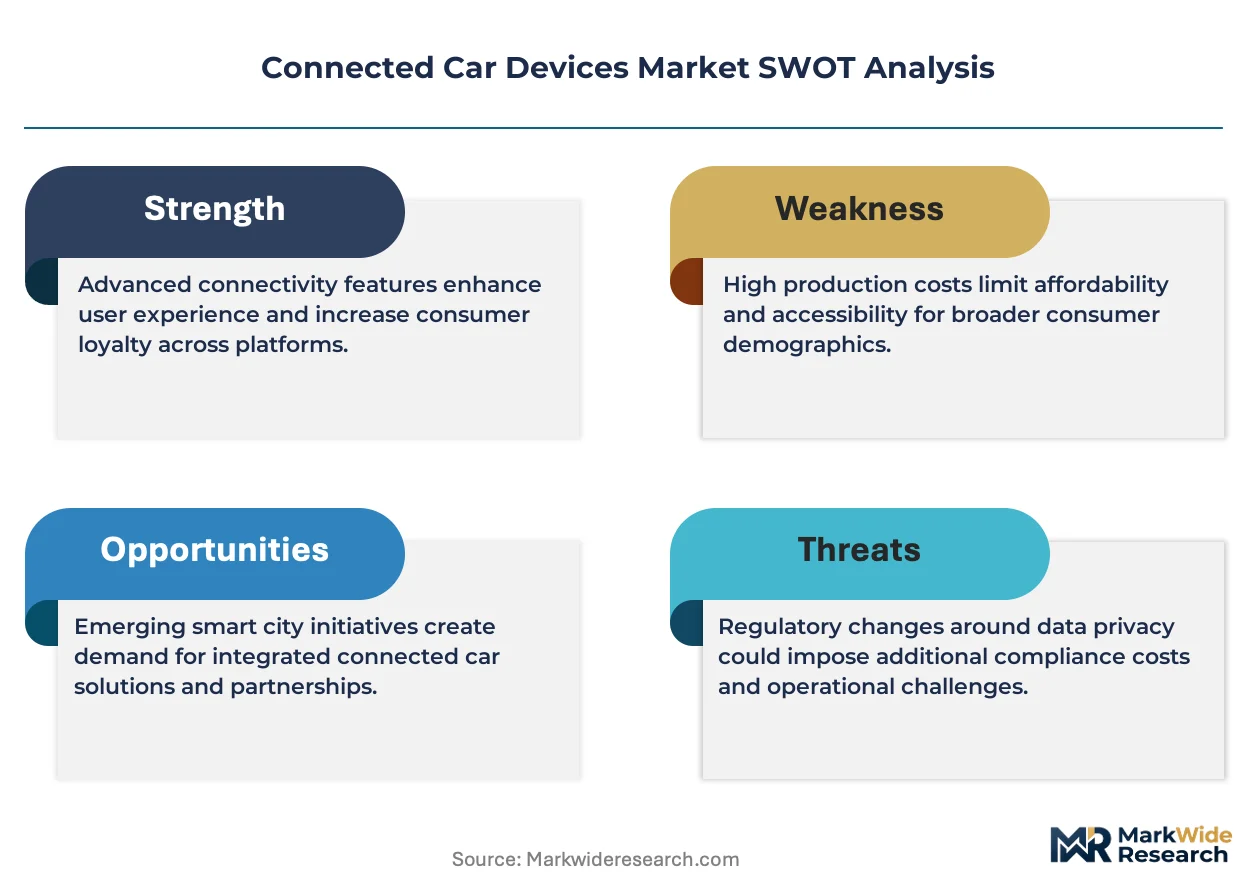
Multiple regulatory frameworks govern market access and product design. The EU's GDPR imposes strict rules on personal data collected from vehicles, while the US FCC allocates specific spectrum for V2X communications to ensure interoperability. In parallel, China's MIIT sets technical standards for intelligent connected vehicles. The critical decision for automakers and suppliers now revolves around investing in proprietary ecosystems versus aligning with emerging open-standard platforms for long-term scalability.
Market Dynamics
The transition to 5G NR connectivity is the central structural force shaping the market, enabling the high-throughput, low-latency communication required for advanced autonomous features and massive data exchange between vehicles, infrastructure, and cloud platforms.
Growth Catalysts
- Government Initiatives:China's MIIT standards for intelligent connected vehicles and smart transportation systems create a large, mandated market for V2X and telematics hardware, accelerating domestic adoption.
- 5G NR Technology:The deployment of 5G New Radio networks provides the necessary bandwidth and reduced latency for real-time applications, including cooperative driving and high-definition map updates, which are essential for ADAS evolution.
- Commercial Fleet Telematics:Demand from commercial fleet operators for solutions that improve fuel efficiency, monitor driver behavior, and optimize logistics provides a consistent and growing revenue stream for telematics device manufacturers.
Market Restraints
- Component Cost Structure:The high acquisition cost of automotive-grade 5G modems and high-precision, multi-constellation GNSS receivers remains a barrier to mass-market adoption in economy vehicle segments.
- Cybersecurity Vulnerabilities:The increasing connectivity of vehicles creates a larger attack surface for malicious actors, with the complexity of securing over-the-air (OTA) software updates posing a significant technical and liability risk.
- Regulatory Fragmentation:Navigating disparate data privacy regulations, such as the EU's GDPR, alongside differing V2X spectrum allocations like those from the US FCC, complicates product design and increases development costs for global automakers.
Strategic Opportunities
- V2X for Smart Cities:Integrating Vehicle-to-Everything communication modules to interact with intelligent traffic lights and pedestrian alerts offers a new value stream tied to municipal smart city infrastructure projects.
- Sensor Fusion with AI:The convergence of high-precision GNSS data with inputs from camera and radar sensors, processed by on-board AI, creates opportunities for more reliable and sophisticated Advanced Driver Assistance Systems.
- Aftermarket Upgrades:A significant opportunity exists in the aftermarket segment to offer plug-and-play connectivity devices that bring modern telematics and infotainment features to the vast existing fleet of older, non-connected vehicles.
Industry Challenges
- Legacy System Integration:Integrating advanced connectivity modules with older, non-standardized vehicle electronic architectures and CAN bus systems presents significant engineering challenges and increases implementation costs.
- Platform Standardization:The conflict between automakers developing proprietary, closed ecosystems and the push for open, interoperable standards delays widespread V2X deployment and limits cross-brand functionality.
- Specialized Talent Scarcity:A shortage of engineers possessing a combined skillset in automotive engineering, cellular communications, and embedded systems cybersecurity constrains product development capacity across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Car Devices Market |
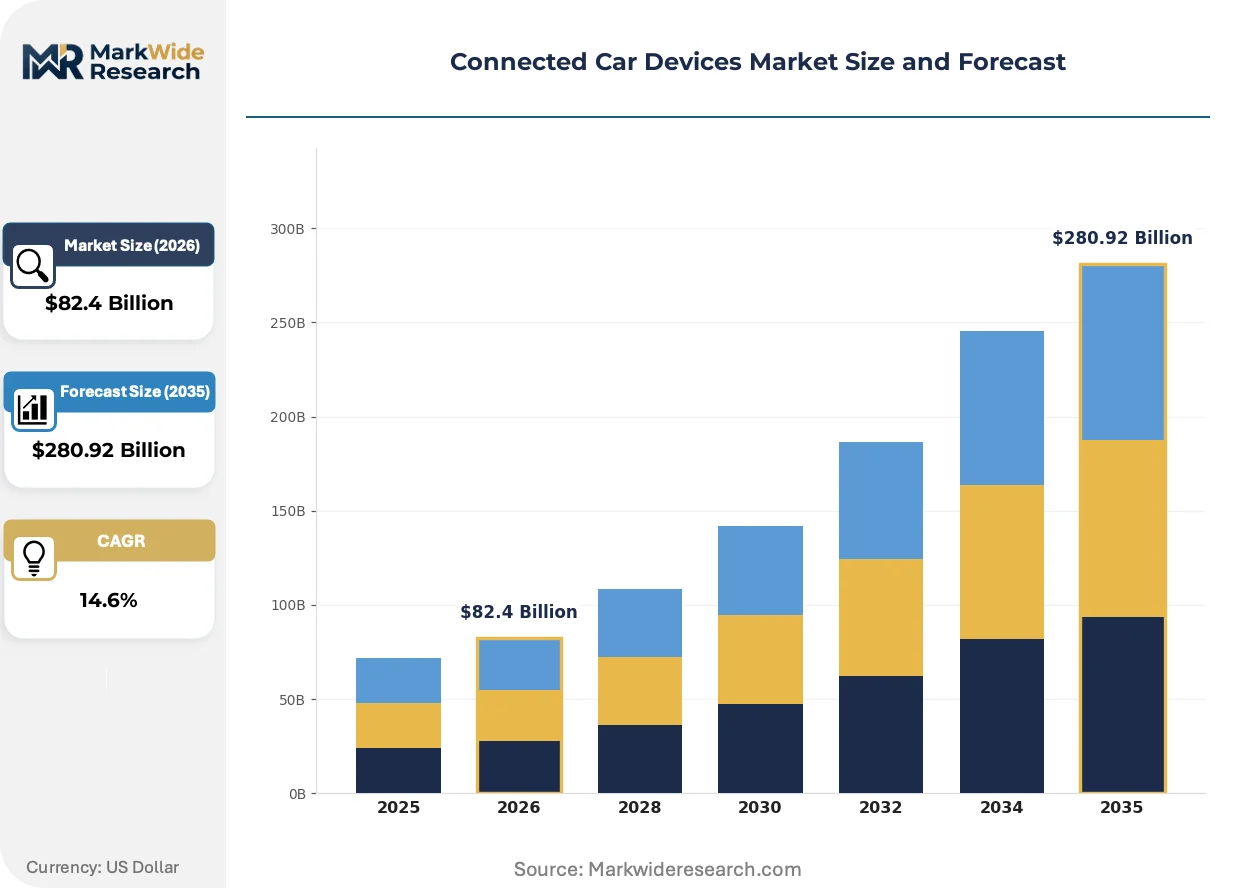
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $280.92 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Telematics Control Units, Infotainment Systems, Advanced Driver Assistance Systems, Vehicle-to-Everything Modules, Onboard Diagnostics Devices Connectivity Technology: 4G LTE, 5G NR, Dedicated Short Range Communications, Wi-Fi, Bluetooth, Satellite Communication Application: Fleet Management Solutions, Usage-Based Insurance, Predictive Maintenance, Real-Time Traffic Updates, Remote Vehicle Diagnostics End User: Original Equipment Manufacturers, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Service Providers |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, Harman International, Visteon Corp., Valeo SA, Autoliv Inc., Qualcomm Technologies, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Car Devices Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental architectural shift in vehicle data processing. Computation is moving from centralized cloud servers to the network edge, embedding more intelligence directly within the vehicle's own electronic hardware to enable real-time decision-making.
Edge computing, integrated directly into Telematics Control Units and infotainment head units, serves to process sensor data locally before transmission. Automakers are rapidly adopting this architecture for latency-sensitive ADAS functions and V2X safety applications that cannot tolerate cloud round-trip delays. This architectural evolution is decentralizing processing intelligence away from the cloud and into the vehicle itself, enhancing system responsiveness and reliability.
In Europe, the General Data Protection Regulation (GDPR) imposes strict requirements on the collection, processing, and storage of personal data generated by connected vehicles. This forces automakers and service providers to design systems with privacy-by-design principles, offering users granular control over their data. The luxury and premium vehicle segments are most affected, responding by implementing transparent consent management dashboards for drivers.
A notable behavioral change is the unbundling of connectivity features from the initial vehicle purchase price. Automakers are increasingly utilizing embedded connectivity hardware to sell subscription-based services, such as remote vehicle control, advanced navigation, and Wi-Fi hotspots, as recurring revenue streams. This model is most prevalent in the North American and European markets, where it is reshaping the consumer's relationship with vehicle ownership.
Connected Car Devices Market Segmentation
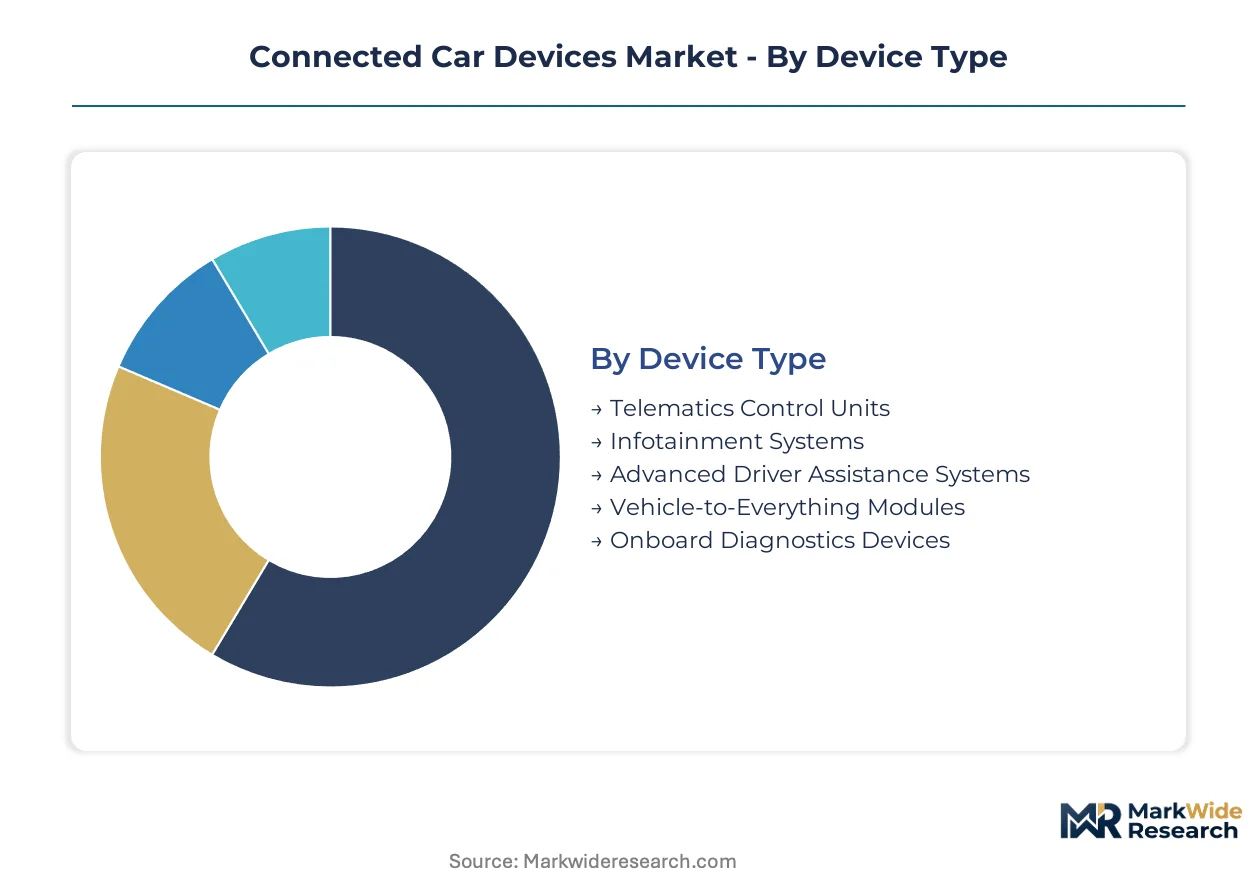
The Connected Car Devices Market exhibits diverse segmentation across critical functional and technological dimensions. Understanding these segments provides clarity on demand drivers, technological dependencies, and value chain dynamics within the automotive sector. This detailed analysis highlights the specific characteristics and growth trajectories of each market component.
Device Type:
The capital intensity of developing and manufacturing connected car devices varies significantly across different types, reflecting the complexity of embedded hardware and software integration. Specialized testing infrastructure is required for advanced systems.
- Telematics Control Units:These embedded communication modules facilitate data exchange for services like eCall, remote diagnostics, and stolen vehicle recovery. Demand concentrates in commercial fleets, driven by operational efficiency and regulatory compliance across Europe.
- Advanced Driver Assistance Systems:ADAS modules integrate sensors, processors, and software to enhance vehicle safety and automate driving functions, such as adaptive cruise control. Adoption accelerates in premium segments globally, responding to consumer safety demands and regulatory mandates.
- Infotainment Systems:Integrated units providing navigation, multimedia, and connectivity, often with smartphone mirroring.
- Vehicle-to-Everything Modules:Hardware enabling communication between vehicles, infrastructure, and pedestrians for intelligent transport systems.
- Onboard Diagnostics Devices:These devices monitor vehicle performance and emissions, providing data for maintenance and regulatory compliance.
Telematics Control Units absorb the bulk of installed capacity; Advanced Driver Assistance Systems are expanding most quickly.
Connectivity Technology:
The application focus dictates the choice of connectivity technology, with different protocols optimized for specific data rates, latency requirements, and communication ranges. Real-time safety applications demand ultra-low latency solutions.
- 5G NR:This fifth-generation cellular technology offers ultra-low latency, high bandwidth, and massive connectivity, essential for autonomous driving and real-time V2X. Deployment concentrates in urban centers of China and Germany, supporting smart city initiatives.
- 4G LTE:Long Term Evolution technology provides reliable, high-speed mobile broadband connectivity, widely used for infotainment, telematics, and OTA updates. Its mature infrastructure supports broad market penetration across North America and Europe.
- Dedicated Short Range Communications:DSRC facilitates direct vehicle-to-vehicle and vehicle-to-infrastructure communication over short distances for safety applications.
- Wi-Fi:Provides local area network connectivity within the vehicle for passenger devices and supports diagnostics.
- Bluetooth:Enables short-range wireless connections for hands-free calling, audio streaming, and device pairing.
- Satellite Communication:Offers global coverage for emergency services, remote diagnostics, and navigation where cellular networks are absent.
5G NR is poised for significant future adoption, while 4G LTE maintains broad market penetration.
Application:
Different customer types drive demand for specific connected car applications, with commercial entities prioritizing operational efficiency and cost savings, while individual consumers seek convenience and safety features. Regulatory incentives also shape adoption patterns.
- Fleet Management Solutions:These comprehensive platforms enable tracking, monitoring, and optimizing commercial fleets, improving logistics, driver behavior, and fuel efficiency. Demand is strong among logistics companies and public transport providers in the United States and Germany.
- Predictive Maintenance:Utilizing vehicle sensor data and AI, this application forecasts potential mechanical failures, allowing proactive servicing and minimizing downtime. Adoption increases in high-utilization commercial vehicles and luxury segments in Japan.
- Usage-Based Insurance:Telematics data informs insurance premiums based on driving behavior, promoting safer habits.
- Real-Time Traffic Updates:Provides dynamic information on road conditions and congestion, optimizing navigation.
- Remote Vehicle Diagnostics:Allows off-board assessment of vehicle health, facilitating proactive service scheduling.
Commercial operators prioritize fleet management solutions, whereas individual consumers value real-time updates and vehicle health monitoring.
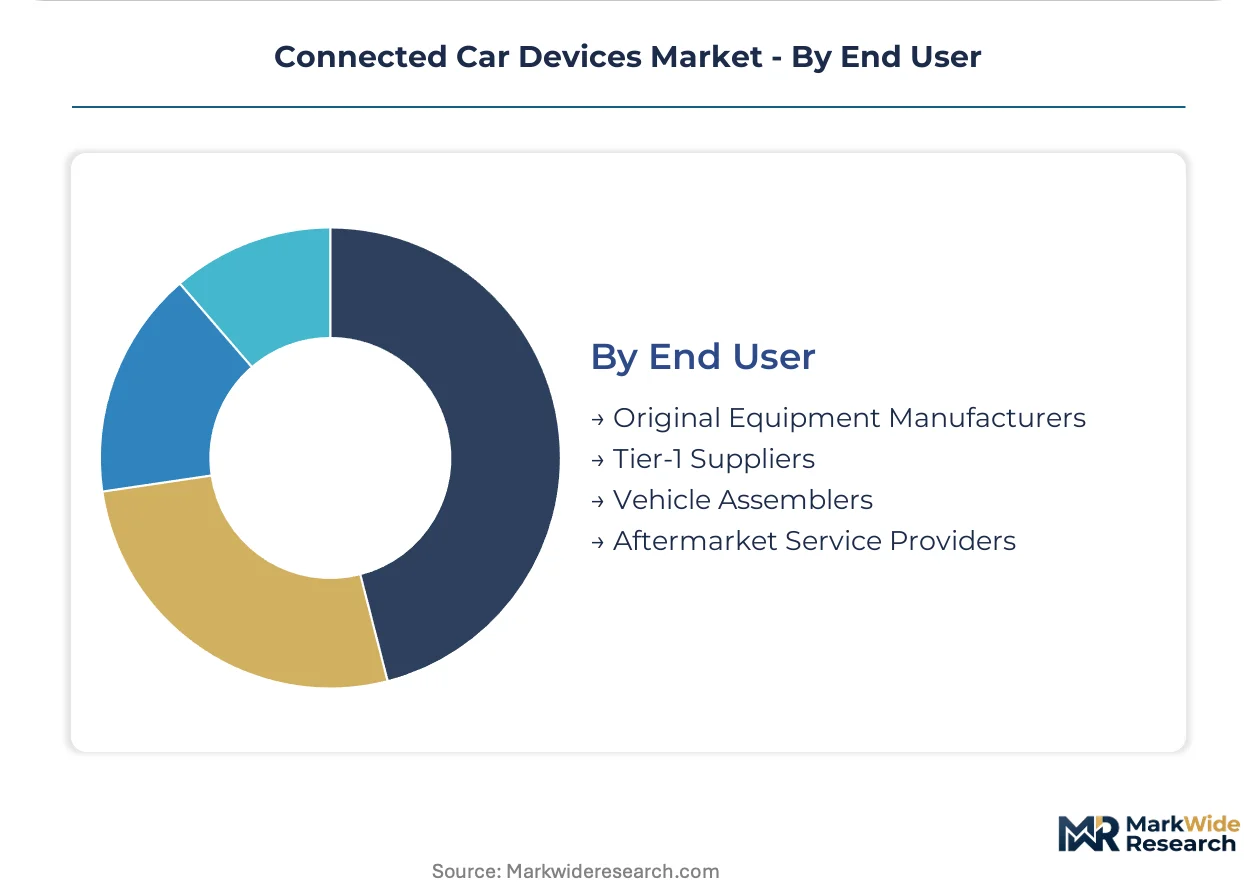
End User:
Supply concentration within the connected car devices market reflects the established automotive supply chain, where large manufacturers and their direct suppliers dominate initial integration. Smaller players often cater to specialized niche segments.
- Original Equipment Manufacturers:OEMs integrate connected car devices directly into new vehicles during manufacturing, controlling design, software, and branding. Automakers like BMW and General Motors invest heavily in proprietary platforms.
- Tier-1 Suppliers:These companies develop and supply complex sub-systems and modules, including telematics control units and ADAS components, directly to OEMs. Continental AG and Robert Bosch GmbH are critical for innovation and supply chain efficiency.
- Vehicle Assemblers:Companies focused on final vehicle assembly, integrating components from OEMs and Tier-1 suppliers.
- Aftermarket Service Providers:These entities offer connected car solutions for existing vehicles, extending connectivity to older models.
Original Equipment Manufacturers and Tier-1 suppliers form the core of the initial installation market, with aftermarket providers addressing the existing vehicle fleet.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration notably shapes the Connected Car Devices Market across key global regions. Government initiatives and robust automotive manufacturing bases drive significant adoption of these advanced technologies. Regulatory frameworks in each region also play a crucial role in steering market development and product design.
China
China's market for connected car devices experiences high demand from government initiatives for intelligent transportation systems and smart city infrastructure. The Ministry of Industry and Information Technology (MIIT) sets technical standards for intelligent connected vehicles, creating a mandated market. Major automotive and technology clusters in the Yangtze River Delta region, including Shanghai, are developing advanced V2X communication platforms.
Germany
Germany represents a significant market for connected car devices, driven by stringent safety regulations and the country's strong automotive manufacturing base. European Union regulations such as GDPR influence data privacy aspects for in-vehicle systems. Stuttgart and Munich, key automotive hubs, focus on developing and integrating sophisticated ADAS and 5G NR connectivity solutions.
United States
The United States market demonstrates robust demand for commercial fleet telematics solutions and advanced infotainment systems. The Federal Communications Commission (FCC) allocates specific spectrum for V2X communications, ensuring interoperability for safety applications. Silicon Valley and Detroit serve as innovation centers, fostering advancements in autonomous driving and embedded connectivity.
Japan
Japan exhibits strong demand for connected car devices, particularly in predictive maintenance and advanced navigation systems for luxury vehicle segments. The Ministry of Economy, Trade and Industry (METI) promotes smart mobility initiatives and supports automotive technology development. Tokyo and Nagoya, major industrial centers, lead in the integration of high-precision GNSS and sensor fusion technologies.
Connected Car Devices Market Key Industry Players
Established producers occupy the standard tier, offering comprehensive hardware and software solutions; emerging entrants pursue specialized niches like cybersecurity or AI-driven analytics. The market structure features a mix of vertically integrated automotive suppliers and technology specialists. Dominant competitive moves include portfolio diversification to cover multiple vehicle domains and strategic partnerships to integrate complex systems.
Tier-1 suppliers like Continental AG and Robert Bosch GmbH exemplify broad portfolio strategies, providing integrated solutions across telematics and infotainment. Component technology specialists such as Qualcomm Technologies occupy a critical position, supplying underlying cellular modem and processor technology to multiple tiers of the value chain. These companies anchor market development through continuous innovation in communication and processing capabilities.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Harman International |
| Visteon Corp. |
| Valeo SA |
| Autoliv Inc. |
| Qualcomm Technologies |
| NXP Semiconductors |
| Others |
Cost & Logistics Intelligence
China's MIIT standards for intelligent connected vehicles mandate a large market, compelling suppliers to meet specific technical requirements. This demand for specialized components influences device pricing, particularly for V2X modules, due to certification and development costs.
Pricing Analysis
Volume-driven segments like 4G LTE-based infotainment hardware operate on tighter margins, while advanced 5G NR modules command higher pricing. The market employs a hybrid pricing model, combining per-unit transactional sales for hardware with subscription-based services for features like remote vehicle control. Customization level for OEM integration and after-sales service bundles drive significant price differentiation. Pricing softness stems from the high acquisition cost of automotive-grade 5G modems, making economy vehicle segments highly price-sensitive compared to premium OEM buyers.
Supply Chain Analysis
China's domestic content mandates for intelligent connected vehicles significantly reshape sourcing strategies for components. Supply concentration centers on manufacturing hubs in China, Germany, and the United States, which produce critical hardware. The supply chain relies heavily on specialized inputs like cellular modems, high-precision GNSS receivers, and embedded processors. Single-source vulnerability for advanced semiconductor components presents a structural risk, while distribution runs primarily through established Tier-1 suppliers to Original Equipment Manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Connected Car Devices Market is supply-constrained, primarily due to the limited availability and high cost of automotive-grade 5G NR modems. This capacity bottleneck props up pricing for advanced connectivity solutions, influencing market entry strategies.
For Market Incumbents: Cement market leadership through continuous portfolio diversification across vehicle domains, offering integrated hardware and software solutions. Strategic partnerships are essential for integrating complex systems, particularly for V2X and ADAS. Invest heavily in R&D for edge computing capabilities to enhance real-time processing, mitigating threats from emerging specialized cybersecurity firms. This approach secures long-term OEM relationships against competitive pressure.
For New Entrants and Emerging Players: Commercial fleet operators in emerging markets represent an underserved buyer archetype for cost-effective telematics. Target the aftermarket segment with plug-and-play connectivity devices for existing, non-connected vehicles, offering modern features via subscription. Focus on specialized V2X modules for smart city infrastructure projects, leveraging open-standard platforms for broader compatibility. This go-to-market angle bypasses established OEM channels.
For Investors and Strategic Acquirers: The window for entry favors specialized component technology providers with proven intellectual property in 5G NR and high-precision GNSS. Long-term viability over the next 5-10 years remains robust, driven by regulatory mandates for safety and the continued evolution of autonomous driving. Target acquisition profiles include firms with strong cybersecurity expertise for embedded systems. Widespread adoption of open-standard V2X platforms will be a critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization Investment | Investing in open-standard platforms reduces fragmentation and accelerates widespread V2X deployment across automakers. |
| Cybersecurity Solution Development | Developing robust cybersecurity measures protects connected vehicles from increasing vulnerabilities and liability risks. |
| Edge AI Integration | Embedding AI processing directly into vehicle hardware enables real-time decision-making for latency-sensitive ADAS functions. |
| 5G NR Module Manufacturing Expansion | Scaling production of automotive-grade 5G NR modules addresses component cost structures and supply constraints. |
| Smart City Infrastructure Partnership | Collaborating with municipalities on V2X deployments creates new value streams tied to urban development projects. |
Research Approach
Independent corroboration across EU GDPR filings, US FCC spectrum allocation documents, and China MIIT technical standards underwrites the qualitative findings. Primary interviews with automotive OEM platform engineers, Tier-1 suppliers, telematics service providers, and regulatory affairs specialists provided crucial insights. This research combined bottom-up data aggregation with top-down market sizing for comprehensive validation.
The forecast window was anchored to historical reference periods, establishing a baseline for future projections. The analytical framework modeled market dynamics across the analysis window, segmenting by device type, connectivity technology, application, end-user, and regional adoption patterns. Compound Annual Growth Rates derived from a growth model integrating demand drivers and market restraints. Key forecast inputs included 5G NR network deployment rates and ADAS regulatory mandates.
Revisions become necessary when geopolitical disruptions impacting semiconductor supply or shifts in V2X spectrum allocations materialize. Forecasts reflect assumptions regarding technological adoption curves and regulatory stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Display Unit in Vehicle Infotainment Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Automotive Steer-By-Wire System (Sbw) Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
ADAS Supplier Ecosystem Market
Automotive Electronics & Wiring
Vehicle Networking Market