
 Automotive Roof Rack Market | 2026-2036
Automotive Roof Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Roof Rack Market Analysis
Modular cross bar and cargo basket bundling is rebalancing buyer choice away from single-component purchases toward integrated roof systems. Thule Group leverages its vertical integration across design, testing, and retail distribution to sustain premium positioning in North America and Europe. JAC Products anchors its competitive stance through deep OEM supply relationships with Detroit Three automakers, while Yakima Products Inc differentiates via specialized bike and ski rack architectures targeting outdoor recreation channels.
An automotive roof rack is a load-bearing framework mounted atop a vehicle, typically constructed from extruded aluminum alloys or glass-reinforced nylon composites, engineered to distribute dynamic loads up to specified weight limits while minimizing aerodynamic drag and cabin noise. Its primary commercial purpose spans cargo augmentation for passenger vehicles, enabling transport of bicycles, skis, cargo boxes, and work equipment beyond trunk capacity. Cross bars and cargo baskets lead product type revenue due to universal fitment compatibility across SUV and crossover platforms, while composite materials represent the fastest-growing material segment as manufacturers pursue weight reduction targets without sacrificing torsional rigidity. Aftermarket Providers capture significant margin pools through installation services and accessory bundling, whereas OEM factory-fit programs concentrate volume through vehicle purchase integration.
NHTSA governs roof rack safety through Federal Motor Vehicle Safety Standard 111 rear visibility and dynamic load testing protocols, while EPA regulations on coating emissions constrain manufacturing process chemistry for painted steel components. Europe's REACH and RoHS frameworks restrict hazardous substance content in surface treatments and fasteners, compelling suppliers to reformulate corrosion-resistant coatings. Stakeholders must monitor evolving UN ECE R14 anchorage strength standards and assess how pending revisions to roof load certification testing will reshape product development timelines and regional market access requirements.
Market Dynamics
Europe's F-Gas Regulation and REACH compliance are forcing material transitions across the supplier base, accelerating reformulation of corrosion-resistant coatings and redirecting procurement toward low-emission aluminum alloys and recyclable composites.
Growth Catalysts
- Outdoor recreation demand:Enthusiasts purchasing SUVs and crossovers for cycling, skiing, and overlanding activities are driving factory-fit and aftermarket adoption of integrated roof systems.
- REACH and RoHS frameworks:Europe's hazardous substance restrictions are compelling suppliers to develop compliant surface treatments, creating first-mover advantages for certified coating technologies.
- Aluminum alloy innovation:Extruded 6000-series alloys with improved torsional rigidity are displacing heavier steel alternatives in premium cargo basket architectures.
Market Restraints
- Raw material volatility:Aluminum ingot price swings and specialty polymer feedstock constraints are compressing margin stability for composite component manufacturers.
- Supply concentration:Germany's dominance in OEM factory-fit programs creates dependency risk for aftermarket providers lacking direct automaker relationships.
- Aerodynamic penalty thresholds:Cabin noise and fuel efficiency degradation beyond specified drag coefficients limit load capacity expansion for certain vehicle platforms.
Strategic Opportunities
- Electric vehicle compatibility:Range-conscious EV owners present untapped demand for ultra-lightweight carbon-reinforced racks that minimize battery drain.
- Digital retail integration:Direct-to-consumer configurators with virtual fitment verification are bypassing traditional brick-and-mortar distribution for accessory bundling.
- UN ECE R14 anchorage standards:Pending revisions to roof load certification testing create entry pathways for suppliers with advanced dynamic testing capabilities.
Industry Challenges
- Cross-functional engineering talent:Shortages of specialists combining aerodynamic simulation expertise with structural load analysis are extending product development cycles.
- Multi-jurisdiction certification:Simultaneous compliance with NHTSA rear visibility protocols, EPA coating emissions, and ECE anchorage standards fragments testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Roof Rack Market |
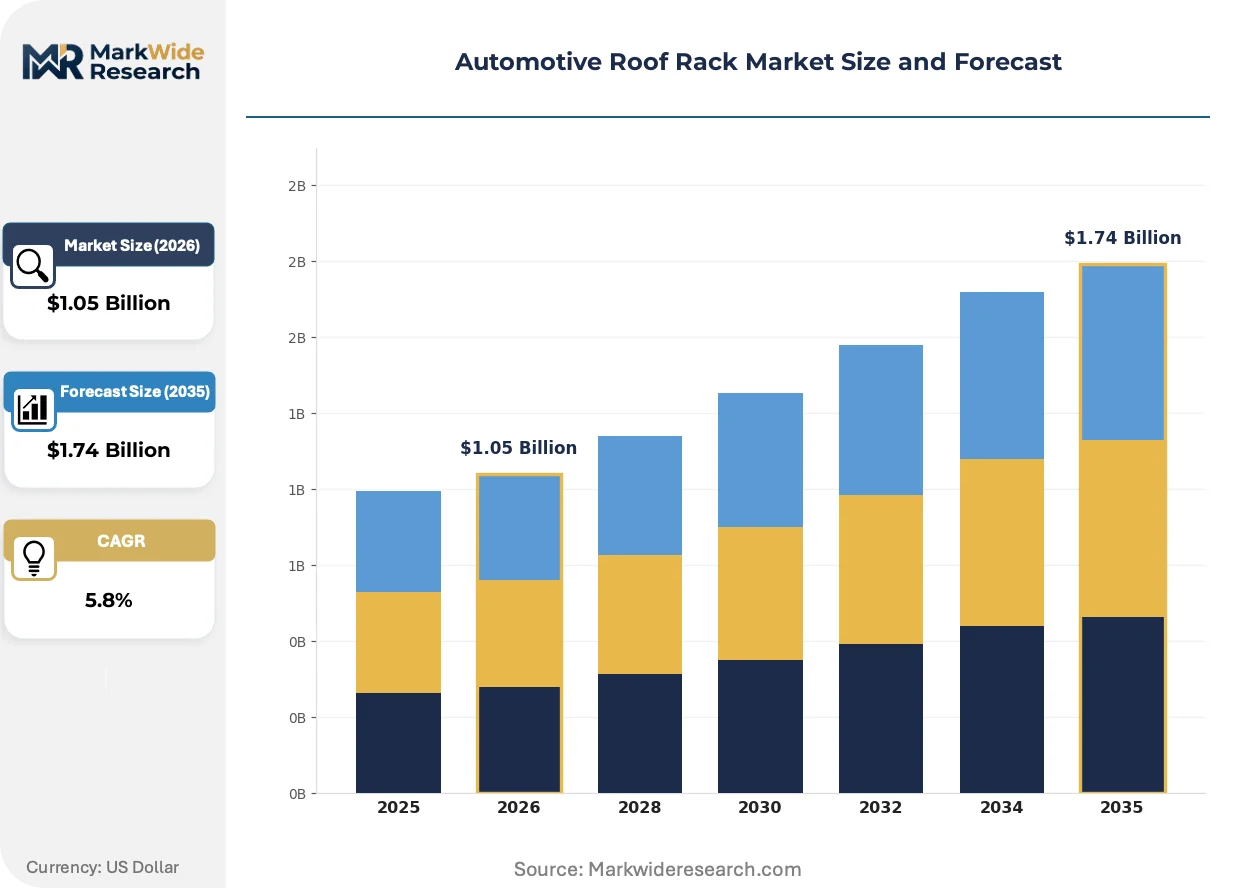
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.74 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross Bars, Cargo Baskets, Ski Racks, Bike Racks Material: Aluminum, Steel, Plastic, Composite Installation Type: Permanent, Removable, Adjustable, Fixed End User: OEMs, Aftermarket Providers, Retail Customers, Fleet Operators |
| Companies Covered | Cruzber SA, JAC Products, Thule Group, Malone Auto Racks, Kuat Innovations, Yakima Products Inc, Atera GmbH, ACPS Automotive GmbH, Rhino-Rack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Roof Rack Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry constraints are converging to reshape how roof rack systems are engineered, tested, and brought to market across passenger vehicle segments.
Glass-reinforced nylon composites with embedded continuous fiber architectures are consolidating position in mid-tier cargo basket applications. Outdoor recreation buyers seeking weight reduction without load capacity sacrifice are adopting these systems at accelerating rates. The shift is compressing traditional metal-forming supply chains while elevating polymer compounding capabilities among tier suppliers.
Europe's F-Gas Regulation restricting fluorinated greenhouse gases in manufacturing processes is forcing coating reformulation across the supply base. Industrial consequence includes accelerated R&D spend on waterborne and powder alternatives to solvent-based corrosion protection. Painted steel component suppliers serving German OEM programs are most affected, with several pursuing in-house electrocoating investments to maintain factory-fit contracts.
Buyer preference for integrated system purchases over single-component transactions is restructuring aftermarket revenue models. Specialty retailers and direct channels are displacing traditional automotive parts distributors for cross bar and cargo basket bundling. This pattern is most visible in North American outdoor recreation markets, where consumers prioritize compatibility-assured configurations over mix-and-match approaches.
Automotive Roof Rack Market Segmentation
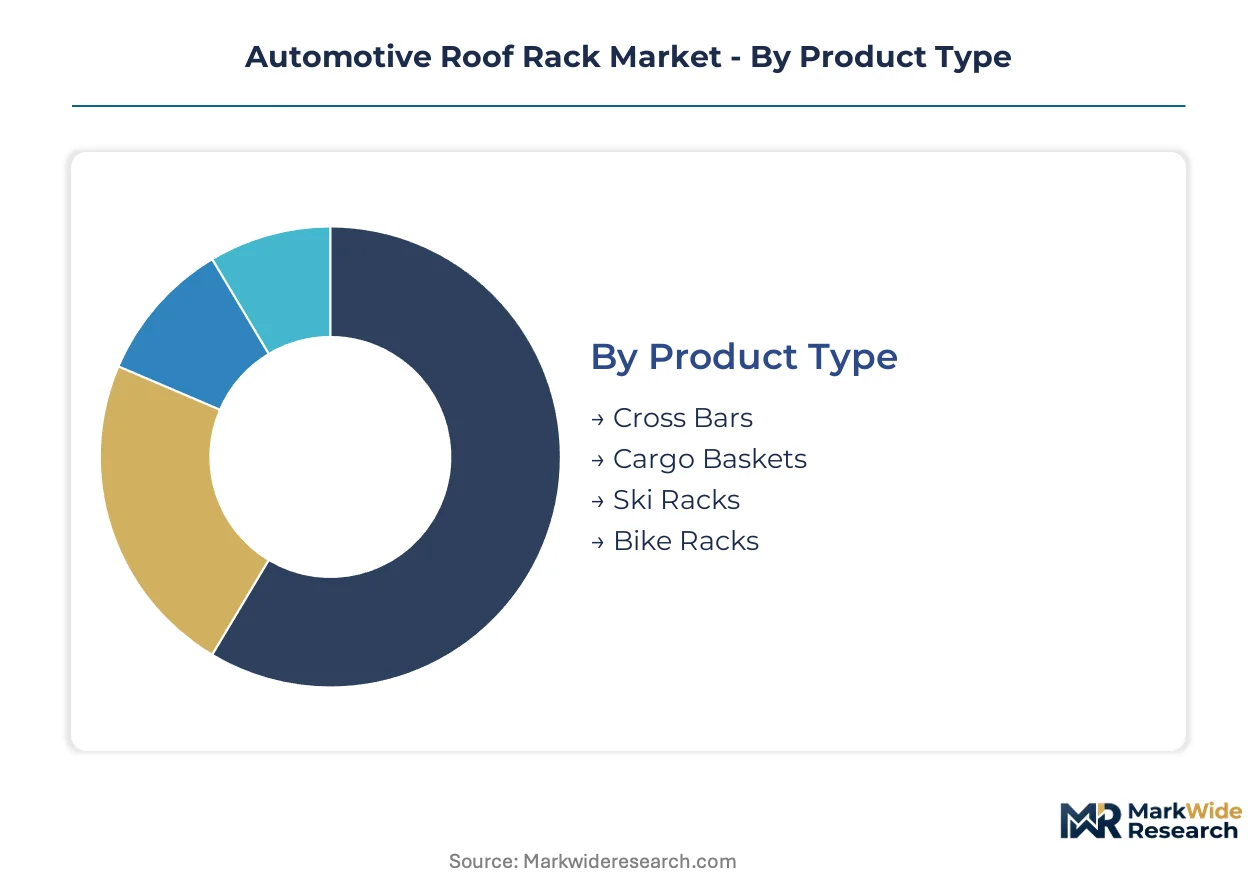
Roof rack segmentation reveals how supplier capabilities and buyer requirements diverge across mounting architectures, material science, and channel economics. Understanding these fault lines exposes where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Supply concentration in cross bar manufacturing creates scale advantages for extrusion specialists serving SUV and crossover platforms.
- Cross Bars:Universal mounting rails engineered from extruded 6000-series aluminum span vehicle roof widths to anchor modular accessories. German OEM factory-fit programs and North American outdoor recreation channels concentrate procurement for integrated cargo systems.
- Cargo Baskets:Platform-style carriers constructed from welded aluminum tubing or glass-reinforced composites augment rooftop capacity for overlanding and work equipment. Demand clusters in aftermarket specialty retail where bundling with aerodynamic fairings commands premium positioning.
- Ski Racks:Low-profile clamping mechanisms secure winter sports equipment with padded contact points and locking security.
- Bike Racks:Fork-mount and wheel-tray configurations accommodate frame geometries across road, mountain, and e-bike categories.
Today's leader: Cross Bars. Tomorrow's challenger: Cargo Baskets.
Material:
Cost tier stratification separates premium aluminum architectures from commodity steel alternatives in buyer selection patterns.
- Aluminum:Extruded and cast alloys deliver strength-to-weight ratios critical for dynamic load ratings and fuel efficiency compliance. REACH and F-Gas Regulation constraints in Europe accelerate procurement shifts toward recyclable 6000-series grades with low-emission surface treatments.
- Composite:Glass-reinforced nylon with continuous fiber architectures displaces metal in mid-tier cargo baskets where torsional rigidity must persist under vibration fatigue. Outdoor recreation buyers seeking weight reduction without capacity sacrifice are expanding this segment most quickly.
- Steel:Painted tubular constructions retain position in budget cargo baskets and commercial fleet applications.
- Plastic:Injection-molded ABS and polypropylene components reduce cost in accessory mounting hardware and protective trim.
Aluminum commands volume leadership. Composite materials present the steepest expansion trajectory.
Installation Type:
Application context determines whether buyers prioritize theft resistance, aerodynamic optimization, or multi-vehicle flexibility.
- Removable:Clamp-on and clip-fit systems enable rapid detachment for garage clearance and fuel economy restoration. Aftermarket channels serving cyclists and skiers concentrate demand where seasonal use patterns dominate.
- Permanent:Factory-welded or bolted architectures integrate with vehicle roof structures for maximum load certification. OEM supply relationships in Germany anchor procurement for luxury SUV platforms.
- Adjustable:Telescoping cross bars accommodate varying roof widths across vehicle generations.
- Fixed:Non-modular configurations serve commercial fleet operators with standardized equipment mandates.
Removable systems capture aftermarket margin. Permanent installations concentrate OEM volume.
End User:
Customer type segmentation exposes divergent procurement economics between integrated vehicle purchase decisions and post-sale accessory investments.
- OEMs:Factory-fit programs bundle roof rack preparation and component installation into new vehicle transactions. German automakers anchor regional supply concentration through direct supplier relationships with extrusion and coating specialists.
- Aftermarket Providers:Specialty retailers and direct-to-consumer channels capture installation service revenue and accessory bundling margins. North American outdoor recreation markets concentrate demand for compatibility-assured system configurations.
- Retail Customers:Individual buyers purchasing through automotive parts distributors and e-commerce platforms.
- Fleet Operators:Commercial vehicle managers procuring standardized equipment for service and utility truck applications.
OEMs dominate unit economics. Aftermarket Providers control margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive roof rack manufacturing originated in post-war Germany, where precision metalworking traditions enabled the first extruded aluminum cross bar systems. Industrial clustering around Stuttgart and Munich established supply chain templates later replicated across North America and Asia-Pacific.
Germany
OEM factory-fit programs in Bavaria and Baden-Württemberg drive procurement concentration for premium SUV platforms. ECHA's REACH framework restricts hazardous substances in corrosion-resistant coatings, compelling suppliers to reformulate surface treatments. The Stuttgart industrial corridor hosts extrusion specialists serving direct automaker relationships with Mercedes-Benz and BMW.
United States
Outdoor recreation channels in Colorado and Pacific Northwest states concentrate aftermarket demand for bike and ski rack configurations. NHTSA's Federal Motor Vehicle Safety Standard 111 governs rear visibility compliance for factory-installed systems. Denver-based specialty retailers anchor distribution networks bundling cross bars with cargo baskets for overlanding enthusiasts.
China
Domestic SUV production in Yangtze River Delta and Pearl River Delta regions generates scale demand for cost-optimized steel and aluminum architectures. MIIT fuel efficiency standards constrain aerodynamic drag penalties for roof-mounted equipment. Shanghai's automotive supplier parks concentrate injection-molded composite component manufacturing for regional OEM programs.
Sweden
Winter sports culture sustains premium rack demand across Scandinavian markets, with specialized ski and cargo basket configurations dominating consumer preference. EU F-Gas Regulation restricts fluorinated greenhouse gases in coating processes, accelerating waterborne alternative adoption. Gothenburg's design-engineering clusters influence Nordic aesthetic standards for integrated roof systems.
Japan
Kei car and compact SUV segments in Kanto and Kansai regions require space-efficient removable rack architectures. METI energy conservation standards penalize aerodynamic inefficiency in accessory design. Nagoya's automotive supplier network specializes in lightweight composite solutions minimizing cabin noise transmission.
Automotive Roof Rack Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material sophistication and channel control dimensions. The vendor base stratifies into three tiers: vertically integrated design-to-retail specialists, OEM-captive supply relationships, and aftermarket-focused accessory bundlers. Consolidation pressure concentrates among mid-scale extrusion houses lacking direct automaker contracts. Dominant competitive moves include backward integration into aluminum smelting partnerships and direct-to-consumer digital platform investments.
Within the European specialist tier, Cruzber SA and Atera GmbH exemplify regional engineering-focused positioning, while Thule Group anchors premium-brand recognition across multiple continents. JAC Products occupies a position within the OEM-captive supply archetype through Detroit Three relationships. Yakima Products Inc represents the outdoor recreation channel specialist model concentrated in North American markets. These three archetypes—European engineering houses, OEM-integrated suppliers, and recreation-channel specialists—collectively define competitive fault lines.
| Leading Market Players |
|---|
| Cruzber SA |
| JAC Products |
| Thule Group |
| Malone Auto Racks |
| Kuat Innovations |
| Yakima Products Inc |
| Atera GmbH |
| ACPS Automotive GmbH |
| Rhino-Rack |
| Others |
Supply Flow & Price Mechanics
Aluminum ingot price volatility on the London Metal Exchange cascades through extrusion houses and coating specialists into three-tier pricing stratification across premium, standard, and economy levels. Buyers of factory-fit cargo systems absorb alloy cost pass-throughs more readily than aftermarket cyclists and skiers facing discretionary purchase decisions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Thule-grade integrated systems from mid-tier composite baskets and entry-level steel tubular racks. Price differentiation hinges on REACH-compliant coating certification and aerodynamic testing documentation, with German OEM programs commanding brand premiums. Cost compression in the economy tier is intensifying because Yangtze River Delta manufacturers are flooding export channels with unbranded aluminum extrusions. Fleet operators exhibit the highest price sensitivity, while overlanding enthusiasts purchasing through Colorado specialty retailers show minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Denver, and Shanghai anchor hub-and-spoke fulfillment patterns for cross bar and cargo basket inventories. Manufacturing concentrates in Germany, China, and the United States, with extruded 6000-series aluminum, glass-reinforced nylon pellets, and corrosion-resistant coating chemicals as critical inputs. Single-source vulnerability around German OEM coating specialists threatens supply continuity as ECHA enforcement tightens. Distribution runs through direct-to-consumer digital platforms and outdoor recreation specialty retailers, bypassing traditional automotive parts distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where outdoor recreation buyers are shifting specifications toward integrated cargo systems with aerodynamic fairings and theft-resistant locking architectures.
For Market Incumbents: Extend coating certification advantages by investing in-house electrocoating capacity to preserve German OEM factory-fit contracts against REACH-driven supplier disqualification. Deepen backward integration into recyclable aluminum smelting partnerships to offset LME volatility and defend margin position in the premium tier. Thule Group's captive design-to-retail infrastructure provides the template for channel control replication. For New Entrants and Emerging Players: Direct-to-consumer configurators with virtual fitment verification offer the lowest-friction entry path into North American outdoor recreation channels. Target EV-compatible ultra-lightweight carbon-reinforced rack architectures where range-conscious owners face unmet demand. White-space concentration sits with specialty bike and ski configurations for e-bike frame geometries not accommodated by incumbent clamping mechanisms. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale extrusion houses possessing advanced dynamic testing capabilities and pending UN ECE R14 certification. Long-term viability favors suppliers with demonstrated OEM relationship depth and compliant coating technology portfolios. The inflection signal to watch is revision timing for roof load certification standards, which will reshape competitive access barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Captive supply of recyclable 6000-series alloys insulates margin against LME volatility for German OEM programs. |
| Direct-to-Consumer Digital Platform Launch | Virtual fitment verification bypasses brick-and-mortar distributors for outdoor recreation accessory bundling in Colorado markets. |
| REACH-Compliant Coating Certification Investment | In-house electrocoating capacity preserves factory-fit contracts as ECHA enforcement disqualifies solvent-based suppliers. |
| EV-Compatible Ultra-Lightweight Architecture Development | Carbon-reinforced composite racks minimize battery drain for range-conscious electric vehicle owners. |
| Advanced Dynamic Testing Capability Buildout | UN ECE R14 anchorage strength certification creates entry pathways for suppliers serving pending regulatory revisions. |
Methodological Framework
Bottom-up outdoor recreation demand modeling reconciled against top-down extrusion and coating supply tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket specialty retailers, and coating formulation specialists combined with secondary validation against vehicle production databases, IHS Markit registration data, ECHA substance restriction filings, and customs trade records. Triangulation between demand-side adoption patterns and supply-side capacity announcements ensures cross-verified volume estimates.
Historical trendline analysis of cross bar and cargo basket shipments across the analysis window established baseline growth trajectories segmented by material type, installation architecture, and channel economics. The projection framework models vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derive from regression-adjusted trend extrapolation incorporating aluminum price elasticity, regulatory compliance cost pass-through assumptions, and outdoor recreation participation indices.
The model assumes a particular technology adoption path; alternative pathways for carbon-reinforced composite architectures would alter the outlook if material cost curves steepen unexpectedly. Forecasts reflect stated assumptions regarding REACH enforcement intensity, NHTSA rear visibility protocol stability, and EV penetration trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Steering Rack Market