
 Car Body Kit Market | 2026-2036
Car Body Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Car Body Kit Market Outlook
Supplier consolidation toward captive composite manufacturing is realigning procurement economics for body kit producers. ABT Sportsline leverages in-house carbon fiber prepreg capabilities to control material grade consistency. Mansory Design and Holding GmbH anchors its position through exclusive partnerships with European supercar marques. BRABUS GmbH sustains premium pricing by dominating engine-and-aero bundled programs for Mercedes-AMG platforms.
A car body kit comprises externally mounted aerodynamic and cosmetic components—front spoilers, side skirts, rear diffusers, and replacement bumpers—typically fabricated from carbon fiber, fiberglass, polyurethane, or ABS plastic through vacuum infusion, compression molding, or thermoforming processes. These assemblies reduce lift, improve high-speed stability, and personalize vehicle aesthetics for consumer and motorsport applications. Carbon fiber kits command the highest margin pools due to weight savings and motorsport provenance, while polyurethane dominates volume production for its impact resistance and paint adhesion properties. SUVs represent the fastest-expanding vehicle type segment as lifted aero packages gain traction among North American and Middle Eastern buyers seeking road presence.
Federal regulators in the United States—specifically NHTSA and EPA—enforce bumper height standards and emissions compliance that constrain body kit geometry and material density choices. Germany's TÜV and the European Union's REACH chemicals framework impose additional testing burdens on polyurethane resin formulations and surface coating VOC limits. Japan's Ministry of Land, Infrastructure, Transport and Tourism (MLIT) maintains strict exterior modification approval pathways that channel demand toward JIS-certified suppliers. Stakeholders must monitor divergent national homologation timelines and pre-certify component families in multiple jurisdictions to avoid market access delays.
Market Dynamics
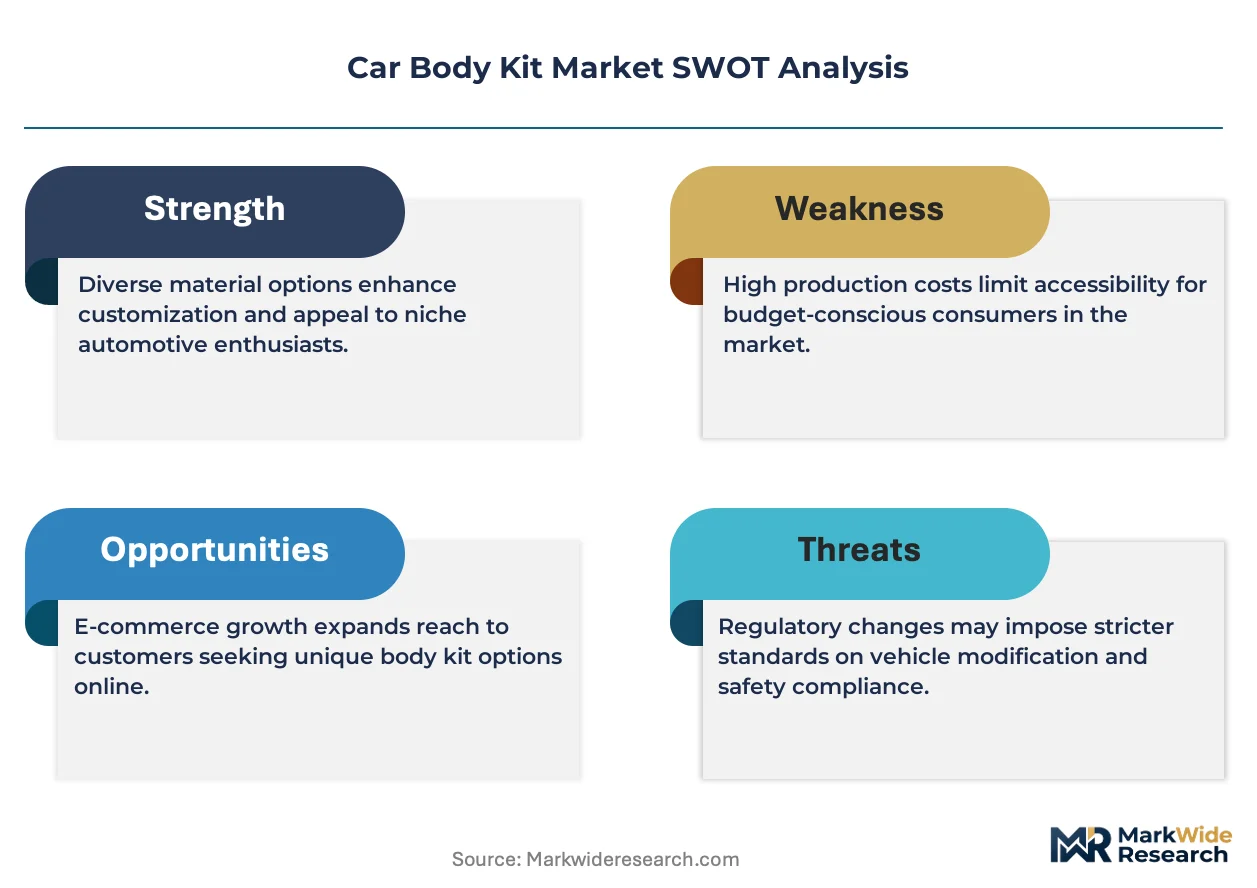
Captive carbon fiber prepreg manufacturing is consolidating supplier power among top-tier body kit producers, forcing mid-market competitors to absorb margin compression or exit premium segments entirely.
Growth Catalysts
- Motorsport Homologation Rules:FIA GT3 and GT4 certification requirements for aerodynamic components are pulling track-proven designs into street-legal aftermarket catalogs, elevating consumer willingness to pay for provenance.
- EPA Emissions Compliance Pathways:Lightweight body kits that reduce vehicle mass qualify for fuel economy credits under US Corporate Average Fuel Economy standards, creating OEM-adjacent demand channels.
- Polyurethane Formulation Advances:Two-component injection molding processes developed for automotive bumper cores are migrating into aftermarket body kit production, cutting cycle times versus hand-lay fiberglass.
Market Restraints
- Carbon Fiber Feedstock Concentration:Toray Industries, Mitsubishi Chemical, and SGL Carbon control 70% of aerospace-grade precursor supply, exposing kit manufacturers to allocation rationing during defense contract surges.
- TÜV Certification Burden:Germany's technical inspection association requires component-level crash testing and material traceability that adds 14-18 months to product launch timelines versus uncertified markets.
- Steel Stamping Substitution:OEMs are integrating more complex stamped aluminum and high-strength steel aerodynamic elements at factory level, compressing addressable aftermarket surface area for replacement bumpers and fenders.
Strategic Opportunities
- Electric Vehicle Aero-Optimization:Battery electric platforms with flat underbodies present unmet demand for integrated diffuser-and-skirt packages that improve range without factory engineering access.
- Digital Fitment Verification:3D scanning and augmented reality preview tools are converging with e-commerce platforms, reducing return rates and enabling direct-to-consumer sales in markets lacking distributor infrastructure.
- Japan's Designated Structure Modification Framework:MLIT's streamlined approval pathway for JIS-certified suppliers creates a regulatory moat for compliant foreign manufacturers seeking entry into the world's third-largest aftermarket.
Industry Challenges
- Composite Technician Scarcity:Vacuum infusion and autoclave operation skills concentrated in aerospace and motorsport clusters are not migrating fast enough to satisfy aftermarket production scaling.
- Multi-Jurisdiction Homologation Costs:Simultaneous NHTSA bumper standard, ECE R42 impact, and JIS exterior modification testing requires duplicate tooling and documentation sets that strain R&D budgets below $10 million.
- Paint Shop Integration Complexity:Polyurethane and carbon fiber substrates demand incompatible surface preparation protocols, forcing body shops to maintain dual process lines or outsource specialized finishing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Body Kit Market |
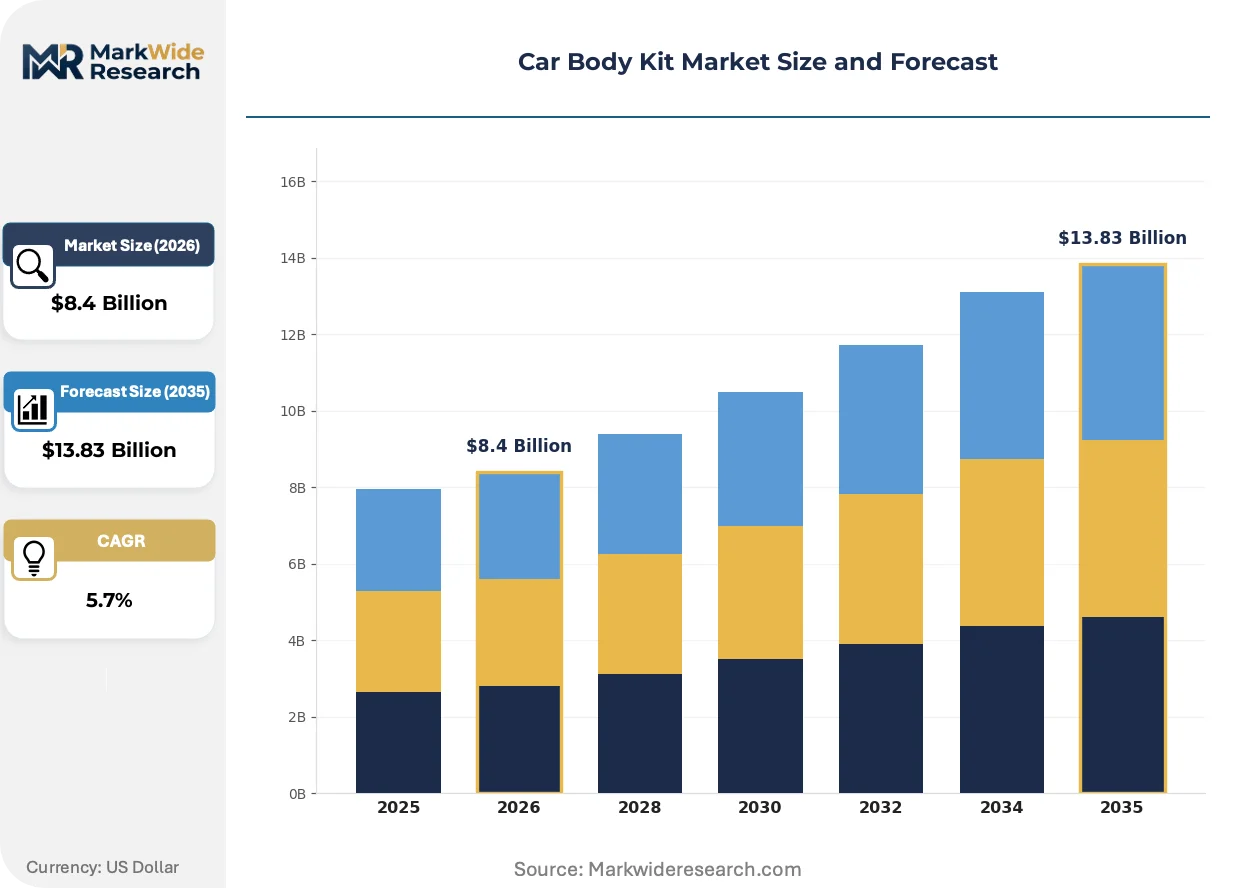
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Spoilers, Side Skirts, Rear Diffusers, Bumpers Material: Carbon Fiber, Fiberglass, Polyurethane, ABS Plastic Vehicle Type: SUVs, Sedans, Hatchbacks, Coupes Service Type: Custom Installation, Retail Sales, Online Sales, Reseller Distribution |
| Companies Covered | ABT Sportsline, Mansory Design and Holding GmbH, Novitec Group, Roush Performance Products, Liberty Walk Co., Ltd., BRABUS GmbH, TECHART Automobildesign GmbH, Vorsteiner, Larte Design, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Body Kit Market Strategic Shifts
Computational fluid dynamics simulation and additive manufacturing are compressing development cycles from concept to production validation, while regulatory fragmentation is forcing modular platform architectures that can adapt across certification regimes.
Continuous carbon fiber 3D printing is converging with topology optimization software to produce lattice-structured underbody panels that match woven prepreg stiffness at 40% lower material input. Aftermarket tuners in Germany and the United Kingdom are piloting these structures for diffuser applications where impact resistance requirements are secondary. The technology is converging with traditional hand-layup shops through hybrid workflows that print structural cores over which cosmetic carbon skins are laminated.
REACH chemicals framework amendments targeting isocyanate exposure limits are forcing polyurethane resin formulators to accelerate water-based and UV-curable alternatives through industrial validation. European compounders including Covestro and BASF are reallocating R&D capacity from automotive OEM coatings to aftermarket body kit compatible systems. Small-batch producers in Italy and Spain face reformulation costs that favor larger competitors with in-house polymer laboratories.
Direct-to-consumer fitment guarantee programs are displacing traditional distributor-wholesale relationships in North American and Australian markets. Buyers now expect AR-based preview tools, VIN-specific compatibility databases, and installation network referrals bundled with purchase. This pattern concentrates in SUV and light truck segments where lifted aero packages command price premiums but require suspension geometry verification that generic catalogs cannot provide.
Car Body Kit Market Segmentation
Body kit procurement decisions diverge sharply across installation channels and vehicle architectures, with certification requirements fragmenting addressable markets by regulator. Manufacturers must align product families to specific homologation pathways or forfeit entire national markets.
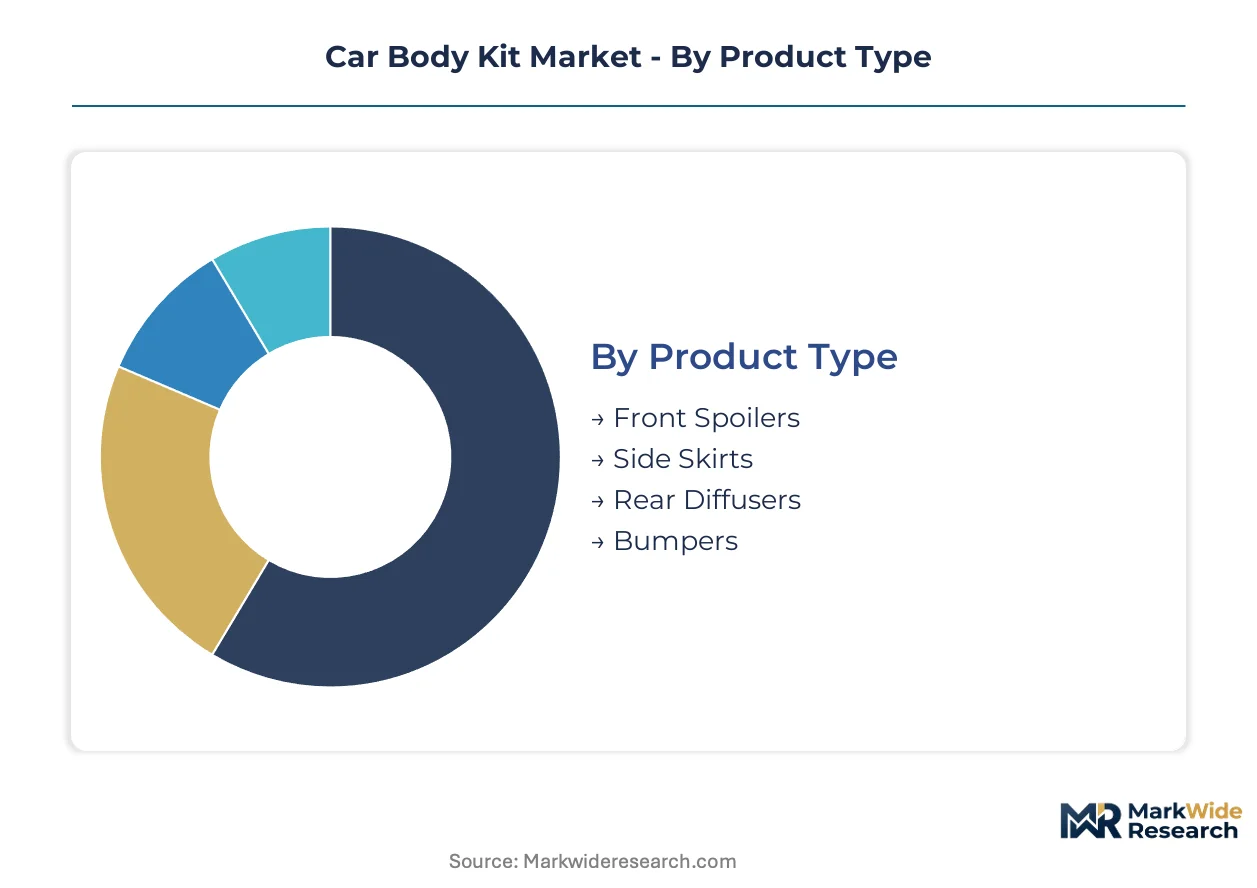
Product Type:
Germany's TÜV demands component-level crash testing for front and rear replacement panels, while side-mounted elements face lighter documentation burdens.
- Front Spoilers:Splitter assemblies and integrated lip designs require NHTSA bumper height compliance in the United States and ECE R42 impact certification in Europe. Track-focused motorsport designs from FIA GT3 homologation programs command premium positioning in Germany and the United Kingdom.
- Rear Diffusers:Underbody aerodynamic elements fabricated in carbon fiber or polyurethane improve high-speed stability and reduce drag. Demand concentrates among electric vehicle owners in California and Norway seeking range extension without factory engineering access.
- Side Skirts:Rocker panel extensions with simpler mounting protocols.
- Bumpers:Full replacement fascias with the heaviest certification burden.
Front spoilers sit at the top of the volume ranking, with rear diffusers climbing the fastest.
Material:
Cost tier stratification separates aerospace-grade supply from commodity resin systems, with REACH compliance adding reformulation overhead to European-sourced polyurethane.
- Carbon Fiber:Woven prepreg and forged composite variants deliver maximum stiffness-to-weight ratios for motorsport applications. TÜV-certified suppliers in Germany capture the premium tier, while Toray Industries and Mitsubishi Chemical ration aerospace-grade precursor during defense contract surges.
- Polyurethane:Two-component injection molding enables impact-resistant bumper cores with superior paint adhesion. BASF and Covestro are reallocating R&D capacity from OEM coatings to aftermarket-compatible water-based formulations under REACH isocyanate limits.
- Fiberglass:Hand-lay vacuum infusion dominates budget-oriented production in Italy and Spain.
- ABS Plastic:Thermoformed cosmetic covers for entry-level personalization.
Polyurethane dominates current volume, though carbon fiber gains share fastest among electric vehicle aero-optimization programs.
Vehicle Type:
Application-specific geometry requirements drive SKU proliferation, with lifted SUV packages demanding suspension verification that sedan catalogs avoid.
- SUVs:Raised ride heights and aggressive stance modifications require integrated skid plates and approach angle verification. North American and Middle Eastern buyers prioritize road presence, channeling demand toward polyurethane bumper replacements with integrated LED mounting points.
- Sedans:Lower center of gravity enables splitter-and-diffuser combinations that improve high-speed stability without ground clearance penalties. Japanese MLIT certification requirements channel demand toward JIS-certified suppliers for exterior modification approvals.
- Hatchbacks:Compact dimensions favor full aero kits with coordinated front, side, and rear elements.
- Coupes:Performance-oriented two-door platforms with factory motorsport heritage.
Sedans retain the largest installed base, though SUVs are expanding most quickly across distributor order books.
Service Type:
Customer type separates professional installation networks from direct-to-consumer channels, with fitment guarantee programs displacing traditional wholesale relationships.
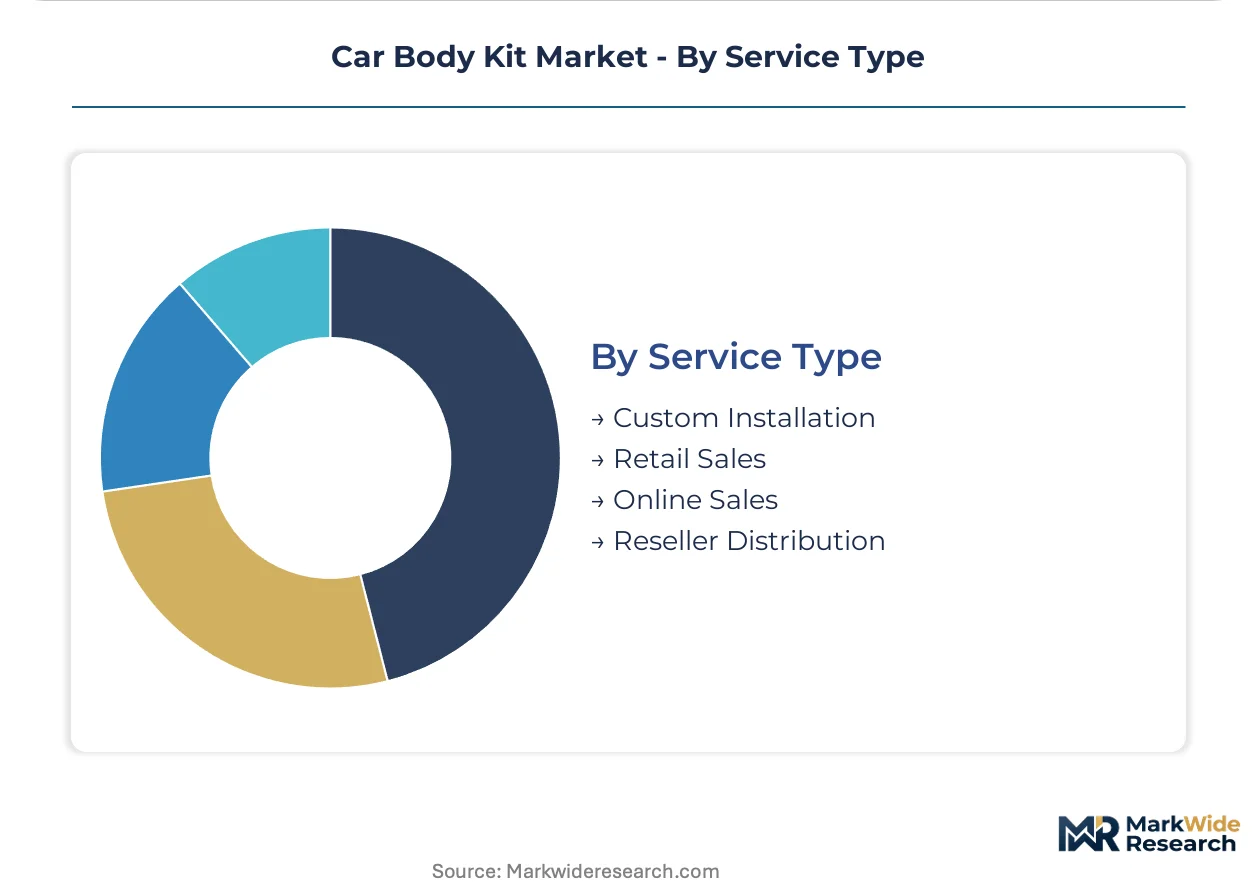
- Custom Installation:Specialist shops with paint booth integration and suspension geometry expertise command premium pricing. AR-based preview tools and VIN-specific compatibility databases now bundle with installation referrals in North American markets.
- Online Sales:Direct-to-consumer platforms with 3D scanning and augmented reality fitment verification reduce return rates. Australian and Canadian buyers lacking distributor infrastructure increasingly source through e-commerce with installation network partnerships.
- Retail Sales:Brick-and-mortar distributors with physical inventory for immediate pickup.
- Reseller Distribution:Traditional wholesale relationships with regional stocking obligations.
Custom installation captures the highest revenue per transaction, with online sales gaining share fastest among younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redirecting body kit production toward jurisdictions with streamlined homologation pathways. Manufacturers now pre-certify component families across multiple national regimes to avoid market-access delays.
United States
NHTSA bumper height standards and EPA emissions compliance constrain body kit geometry and material density choices. Motorsport enthusiasts in California and Texas drive demand for track-proven aerodynamic designs. Roush Performance Products anchors production in Michigan with bundled engine-and-aero programs for domestic muscle platforms.
Germany
TÜV certification requirements add 14-18 months to product launch timelines versus uncertified markets. REACH chemicals framework amendments targeting isocyanate exposure limits force polyurethane resin reformulation. ABT Sportsline and BRABUS GmbH dominate the premium tier from Baden-Württemberg with in-house carbon fiber prepreg capabilities.
Japan
MLIT's Designated Structure Modification Framework channels demand toward JIS-certified suppliers for exterior modification approvals. Liberty Walk Co., Ltd. exemplifies the regulatory-moat strategy from Kansai region operations. Compact hatchback and sedan owners in Tokyo and Osaka prioritize coordinated full aero kits with factory motorsport heritage.
United Kingdom
ECE R42 impact certification requirements align with EU standards while post-Brexit divergence creates parallel documentation burdens. Track-day culture in Silverstone and Brands Hatch clusters pulls GT3-homologated designs into street-legal catalogs. Specialist fabricators in Midlands industrial zones serve both domestic demand and export channels to Commonwealth markets.
United Arab Emirates
Road-presence preferences among SUV owners in Dubai and Abu Dhabi channel demand toward lifted aero packages with integrated LED mounting points. MOHAP vehicle safety standards intersect with GCC technical regulations for thermal and impact performance. Mansory Design and Holding GmbH maintains regional distribution partnerships serving supercar marque owners seeking exclusive carbon fiber personalization.
Car Body Kit Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electric vehicle aero-optimization and direct-to-consumer digital channels. The vendor base stratifies across three tiers: integrated composite manufacturers with captive carbon fiber supply, specialist tuners with exclusive OEM partnerships, and volume-oriented polyurethane molders serving price-sensitive segments. Dominant competitive moves include backward integration into prepreg manufacturing and geographic expansion through JIS or TÜV certification pre-qualification.
Among German-based fabricators, ABT Sportsline and Mansory Design and Holding GmbH exemplify the integrated-manufacturer archetype with in-house material grade control. BRABUS GmbH occupies a position within the engine-and-aero bundling specialist tier. Liberty Walk Co., Ltd. represents the JIS-certified export-oriented model, while Roush Performance Products anchors the domestic US muscle-car customization segment. TECHART Automobildesign GmbH and Vorsteiner sit within the premium-tier Porsche-platform specialization vector.
| Leading Market Players |
|---|
| ABT Sportsline |
| Mansory Design and Holding GmbH |
| Novitec Group |
| Roush Performance Products |
| Liberty Walk Co., Ltd. |
| BRABUS GmbH |
| TECHART Automobildesign GmbH |
| Vorsteiner |
| Larte Design |
| Others |
Value Chain & Pricing Dynamics
Composite technician scarcity in Baden-Württemberg and the Midlands industrial zones feeds labor-cost differentials that widen spreads between TÜV-certified premium tiers and hand-lay fiberglass economy offerings. Shop rates for autoclave operation and vacuum infusion skills run 40-60% above standard automotive body labor, compressing margins at mid-market producers unable to automate.
Pricing Analysis
Distributor margin layers absorb 35-45% of final consumer price in traditional wholesale channels, while direct-to-consumer platforms capture this spread through AR-enabled fitment guarantees. Three-tier pricing structure across premium, standard, and economy levels separates TÜV-certified carbon fiber kits from polyurethane volume production and hand-lay fiberglass budget alternatives. Price differentiation hinges on certification grade and captive prepreg manufacturing. Cost compression in the mid-market intensifies as BRABUS GmbH and ABT Sportsline bundle engine-and-aero programs that reset willingness-to-pay benchmarks. Fleet buyers and online-direct millennials exhibit lowest price sensitivity; independent body shops sourcing through distributors face highest.
Supply Chain Analysis
Germany's REACH chemicals framework and Japan's MLIT Designated Structure Modification Framework are reshaping sourcing toward JIS-certified and TÜV-prequalified component families. Aerospace-grade carbon fiber precursor concentrates in Japan, Germany, and the United States, with Toray Industries and Mitsubishi Chemical rationing supply during defense contract surges. Raw material dependencies span woven prepreg, two-component polyurethane resin systems, and UV-curable coating formulations. Single-source vulnerability runs through Toray's aerospace-grade precursor allocation. Distribution runs through specialist tuner networks in Germany, direct-to-consumer platforms in North America, and JIS-certified wholesale channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where TÜV certification and motorsport homologation heritage command expanding premium capture as SUV and electric vehicle buyers prioritize provenance over price.
For Market Incumbents: Deploy captive carbon fiber prepreg manufacturing to lock material grade consistency and defend against mid-market margin compression. Accelerate TÜV pre-certification for component families destined for electric vehicle aero-optimization programs. Counter steel stamping substitution threats from OEMs by bundling software-defined aerodynamic adjustment systems with hardware kits.
For New Entrants and Emerging Players: MLIT's Designated Structure Modification Framework in Japan opens a window for JIS-certified foreign manufacturers to establish regulatory-moat positions before incumbent German fabricators complete certification. Target electric vehicle diffuser-and-skirt packages for battery platforms with flat underbodies in California and Norway. Pursue direct-to-consumer channels with VIN-specific compatibility databases and AR preview tools to bypass distributor infrastructure gaps.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market polyurethane molders without certification moats or captive composite capabilities. Five-to-ten year viability favors integrated manufacturers with backward integration into prepreg supply and multi-jurisdiction homologation portfolios. Watch allocation rationing signals from Toray Industries and Mitsubishi Chemical as inflection indicators for margin expansion at captive-supply players.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Carbon Fiber Prepreg Manufacturing | ABT Sportsline and BRABUS GmbH control material grade consistency against aerospace supply rationing. |
| TÜV Pre-Certification Investment | Fourteen-to-eighteen month timeline premiums justify early component-family validation for German market access. |
| Direct-to-Consumer Platform Launch | AR fitment verification and VIN-specific databases reduce return rates in distributor-infrastructure gaps. |
| Electric Vehicle Aero-Optimization Programs | Flat underbody battery platforms create unmet demand for integrated diffuser-and-skirt range extension. |
| JIS Certification Pathway Completion | MLIT's streamlined framework creates regulatory moat for compliant foreign manufacturers entering Japan. |
Study Parameters
Multiple input streams — structured interviews with Tier 1 supplier procurement leads, aftermarket distributor operations heads, and composite manufacturing technicians, alongside OEM platform engineering disclosures and TÜV certification documentation — were reconciled against customs records, IHS Markit vehicle registration data, and REACH chemical framework amendments. Primary fieldwork captured vacuum infusion and autoclave operation capacity constraints in Baden-Württemberg and Midlands clusters. Bottom-up build from SKU-level pricing and top-down cross-reference against segment revenue pools enabled triangulation.
Historical volume trajectories were cross-referenced against panel input from motorsport homologation directors and EPA compliance officers to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include vehicle architecture, material grade tier, certification pathway, and installation channel. CAGRs derived from fitted trend extrapolation moderated by regulatory timeline constraints and raw material allocation risk factors. Electric vehicle production forecasts and TÜV certification queue lengths served as industry-specific demand and supply-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aerospace precursor rationing surges or REACH isocyanate limit acceleration. Forecasts reflect assumptions around certification timeline stability and composite technician training pipeline expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Automotive Activated Carbon Canister Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Automotive Cell Vent Spacer Market