
 Global Automotive Rear Mounted Tray Market | 2026-2036
Global Automotive Rear Mounted Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Rear Mounted Tray Market Intelligence
REACH is broadening the cost-of-entry calculus for interior component suppliers serving European automakers. Grupo Antolin leverages its polymer compounding expertise to sustain compliance across multiple substrate grades. Kasai Kogyo Co., Ltd. anchors its position through deep integration with Japanese OEM seating programs. Toyota controls captive demand through in-house production of rear convenience accessories for its SUV and minivan platforms.
An automotive rear mounted tray is a flat storage platform affixed to the backside of a vehicle seat or cargo partition, typically molded from polypropylene or ABS composites with load ratings between five and fifteen kilograms, designed to expand cabin utility for passenger and commercial applications. Plastic Trays dominate volume production due to their favorable strength-to-weight ratio and compatibility with injection molding cycles. SUVs represent the fastest-growing end use vehicle type as manufacturers expand three-row configurations with integrated rear passenger amenities. OEM Direct channels capture the highest margin pools through long-term supply agreements tied to platform life cycles.
The EPA governs volatile organic compound thresholds for automotive interior assemblies in the United States, while ECHA administers REACH substance restrictions across European supply chains. China's SAMR enforces GB standards for passenger vehicle interior air quality, creating a fragmented compliance landscape for multi-regional suppliers. Stakeholders must monitor evolving material certification requirements across these three jurisdictions to secure platform access without costly retrofit cycles.
Market Dynamics
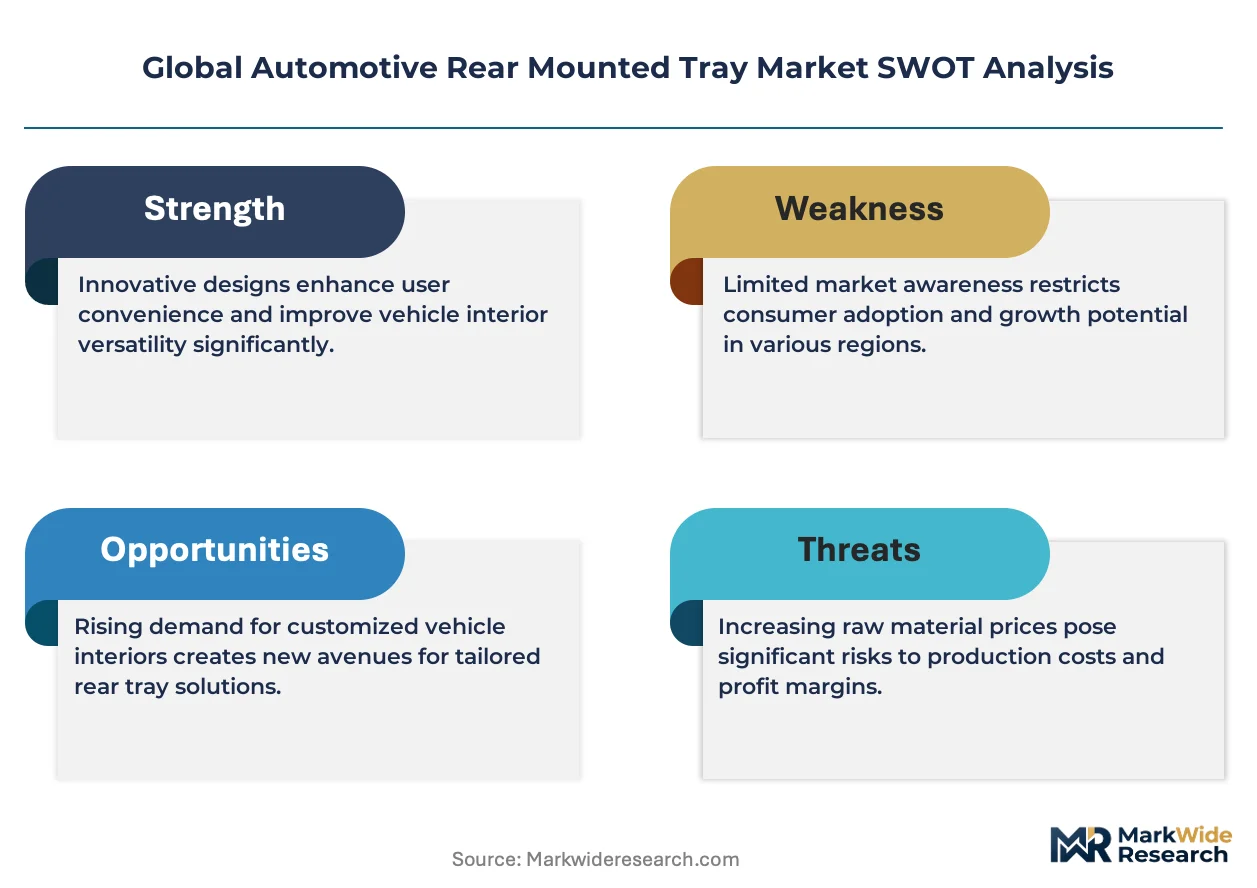
OEM direct procurement consolidation is compressing supplier margins while elevating technical compliance requirements across polypropylene and ABS substrate specifications. Tier-1 seating integrators now demand REACH-certified material traceability and load-testing documentation as baseline qualification criteria.
Growth Catalysts
- SUV platform proliferation:Three-row vehicle configurations from Detroit and Stuttgart automakers are standardizing rear convenience modules as factory-installed equipment.
- ECHA REACH substance restrictions:European emission thresholds for interior volatiles are accelerating compliant substrate development across supplier R&D programs.
- Injection molding cycle efficiency:Thin-wall polypropylene processing advances are reducing unit production costs for high-volume tray programs.
Market Restraints
- Petrochemical feedstock volatility:Propylene monomer price swings directly compress gross margins on polymer tray production.
- Tooling capex concentration:Multi-cavity mold investments for Class-A surface finishes lock suppliers into single-platform dependencies.
- Steel cargo solutions substitution:Upfitters in commercial van segments promote metal racking systems that bypass OEM tray integration.
Strategic Opportunities
- India PLI scheme automotive incentives:Domestic SUV production subsidies create localized supply openings for tray module assembly.
- Modular seat-back ecosystems:Convergence of tray, tablet holder, and charging pad functions enables higher per-vehicle content capture.
- Aftermarket digital channels:Direct-to-consumer configurators for universal-fit accessories bypass traditional distribution markups.
Industry Challenges
- Cross-platform validation timelines:OEM seat-back angle tolerances vary by millimeter-grade specifications, forcing iterative fitment testing cycles.
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing UV stability, impact resistance, and emission compliance command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Rear Mounted Tray Market |
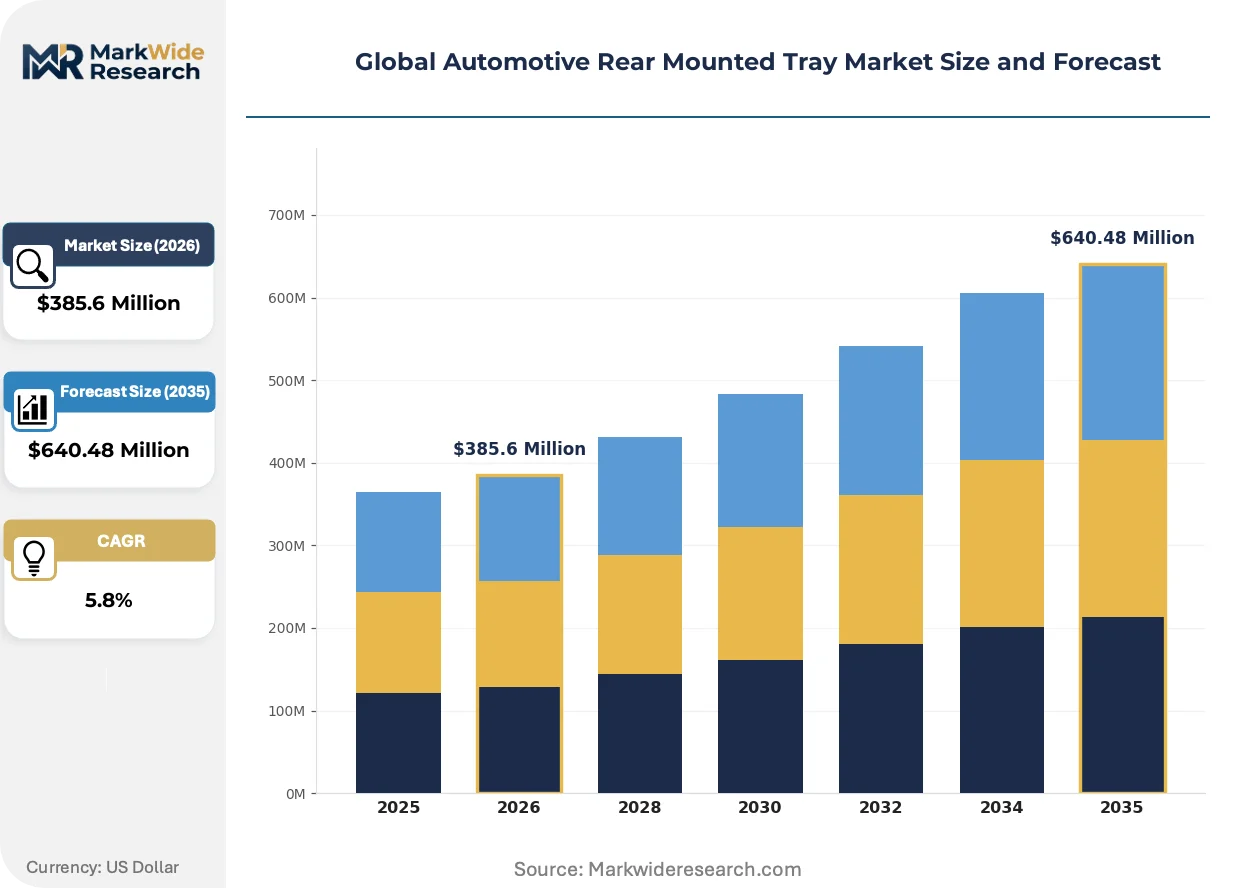
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Trays, Metal Trays, Plastic Trays, Wood Trays End Use Vehicle Type: Passenger Vehicles, Commercial Vans, SUVs, Pickup Trucks Installation Method: Clip-On, Screw Mounted, Adhesive Fixed, Snap Fit Distribution Channel: OEM Direct, Aftermarket Suppliers, E-commerce Platforms, Automotive Parts Retailers |
| Companies Covered | Sanko Gosei, Trim India Pvt. Ltd., Grupo Antolin, Kasai Kogyo Co., Ltd., AD Plastics d.d. Solin, Dongfeng Motor Parts & Components (Group) Co., Ltd., Lih Feng Jiing Enterprise Co., Ltd., Toyota, Rochling Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Rear Mounted Tray Market Strategic Shifts & Innovations
Active grille shutter technology is migrating into cabin climate management, reshaping how interior airflow interacts with storage compartment thermal profiles. Material science advances and regulatory emission protocols are simultaneously redefining substrate qualification pathways.
Natural fiber-reinforced polypropylene compounds are integrating flax and hemp fillers to reduce petroleum dependency while maintaining five-kilogram load ratings. BMW and Volvo seating programs have adopted these biocomposites for their European SUV lines. This material transition is integrating sustainability metrics directly into OEM supplier scorecards, compressing conventional ABS market share.
China's SAMR GB standards for passenger vehicle interior air quality are mandating formaldehyde and benzene emission caps that exceed prior industry norms. Domestic suppliers in Shanghai and Guangdong are retrofitting compounding lines with real-time volatile monitoring. Tier-1 seating manufacturers serving BYD and Geely platforms face accelerated recertification deadlines to maintain program access.
Fleet operators and rental car aggregators are consolidating specification authority previously held by individual procurement departments. Hertz and Enterprise Holdings now issue unified tray durability standards across their SUV acquisition programs. This buyer concentration is most visible in the United States, where direct OEM negotiations are displacing regional distributor relationships.
Global Automotive Rear Mounted Tray Market Segmentation
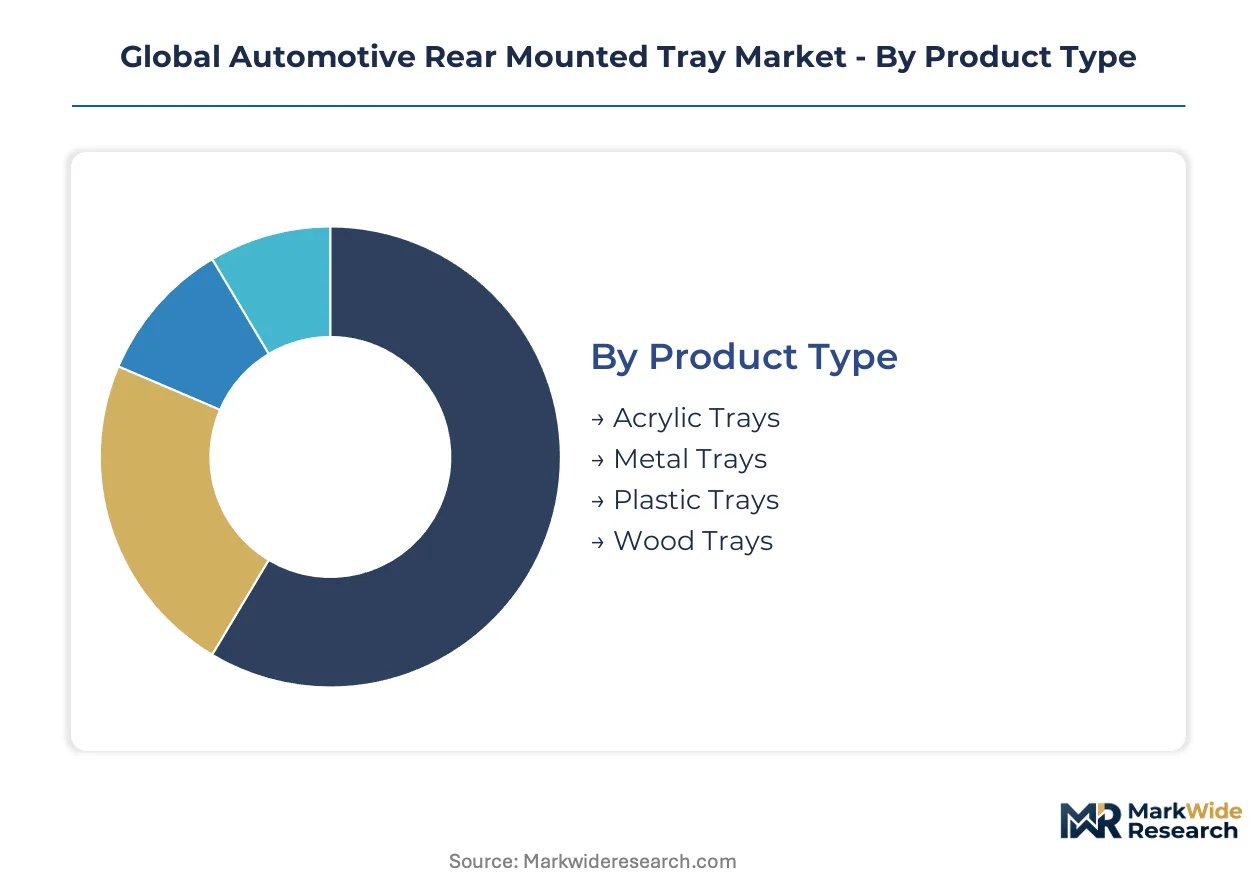
Rear mounted tray procurement patterns diverge sharply across substrate grades and vehicle platforms. OEMs configure material specifications and mounting systems to align with platform cost targets and regional regulatory thresholds.
Product Type:
Supply concentration favors polymer processors with captive compounding capabilities and Class-A surface finishing expertise.
- Plastic Trays:Injection-molded polypropylene and ABS composites dominate high-volume programs through favorable strength-to-weight ratios and sub-30-second cycle times. Detroit and Stuttgart automakers specify these substrates for three-row SUV factory installations. ECHA REACH emission thresholds are accelerating compliant grade development among European compounders.
- Metal Trays:Stamped aluminum and steel configurations serve commercial van upfitters requiring fifteen-kilogram load ratings and impact resistance. Fleet operators in the United States specify metal trays for rental SUV programs where durability overrides weight penalties.
- Acrylic Trays:Transparent or tinted PMMA variants target premium interior aesthetics in luxury German marques.
- Wood Trays:Veneered or solid wood options remain niche, reserved for bespoke coachbuilder applications.
Today's leader: Plastic Trays. Tomorrow's challenger: Metal Trays.
End Use Vehicle Type:
Application requirements scale with cabin architecture complexity and passenger duty cycles.
- SUVs:Three-row configurations from BMW, Volvo, and domestic Chinese manufacturers standardize integrated rear convenience modules. SAMR GB interior air quality standards in China force substrate recertification for BYD and Geely platform access.
- Passenger Vehicles:Sedan and hatchback applications concentrate in entry and mid-market segments with clip-on universal fitment.
- Pickup Trucks:Crew cab configurations in the United States and Thailand incorporate factory-mounted trays behind split-folding rear seats.
- Commercial Vans:Mercedes-Benz Sprinter and Ford Transit upfitters favor steel racking systems that bypass OEM tray integration entirely.
SUVs command the steepest expansion trajectory as platform proliferation outpaces other vehicle formats.
Installation Method:
Mounting system selection reflects the tension between assembly line efficiency and aftermarket service flexibility.
- Clip-On:Tool-free attachment to seat-back frames enables rapid OEM line-side installation and consumer removability. Japanese seating integrators favor this method for minivan programs.
- Screw Mounted:Through-bolt fastening delivers maximum load security for heavy-duty commercial applications.
- Adhesive Fixed:Structural bonding suits composite seat-back structures where mechanical fastening risks substrate damage.
- Snap Fit:Integral plastic latches reduce part count and assembly labor in cost-sensitive volume programs.
Clip-On systems capture the largest installed base. Screw Mounted methods defend position in fleet-specified durability tiers.
Distribution Channel:
Channel economics separate captive OEM supply from fragmented aftermarket access.
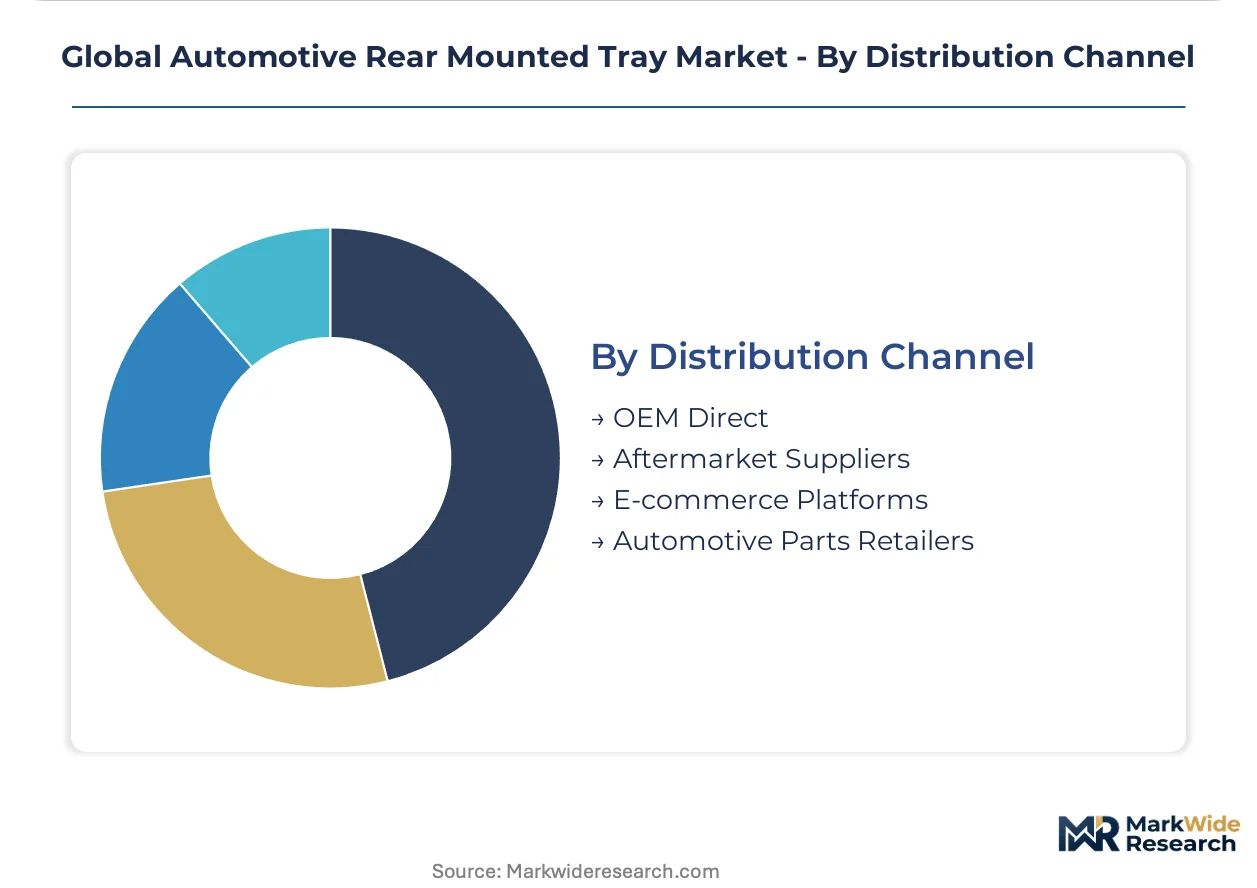
- OEM Direct:Long-term supply agreements tied to platform life cycles capture the highest margin pools. Tier-1 seating manufacturers like Grupo Antolin and Kasai Kogyo anchor these relationships with REACH-certified material traceability.
- Aftermarket Suppliers:Universal-fit tray distributors serve vehicle owners outside warranty periods with lower specification tiers.
- E-commerce Platforms:Direct-to-consumer configurators bypass traditional distribution markups, particularly visible in United States digital retail.
- Automotive Parts Retailers:Brick-and-mortar chains stock standardized SKUs for immediate replacement demand.
OEM Direct channels concentrate value capture. E-commerce Platforms are gaining share fastest as buyer behavior shifts online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding expertise clusters in Germany, Japan, and the United States anchor the industry's technical workforce. These concentrations shape regional supply capabilities and compliance specialization across major automotive production zones.
United States
Three-row SUV production from Detroit automakers drives factory-installed tray demand across Michigan and Ohio assembly corridors. EPA volatile organic compound thresholds govern interior assembly specifications for vehicles sold domestically. Hertz and Enterprise Holdings in Florida consolidate fleet procurement standards that reshape OEM negotiation dynamics.
Germany
Luxury SUV platforms from Stuttgart and Munich manufacturers integrate premium rear convenience modules as standard equipment. ECHA REACH substance restrictions mandate compliant substrate traceability across supplier networks. Bavaria's polymer compounders specialize in emission-certified polypropylene grades for European OEM seating programs.
China
BYD and Geely scale three-row SUV production for domestic and export markets, accelerating tray module demand. SAMR enforces GB standards for passenger vehicle interior air quality with formaldehyde and benzene caps. Shanghai and Guangdong suppliers retrofit compounding lines with real-time volatile monitoring to maintain platform access.
Japan
Minivan and SUV production for domestic and Southeast Asian markets sustains integrated rear accessory demand. METI industrial standards coordinate with OEM specifications for interior component durability. Toyota's in-house production of rear convenience accessories in Aichi Prefecture controls captive demand for its vehicle platforms.
India
Domestic SUV production subsidies under the PLI scheme attract localized tray module assembly investments. BIS certification requirements align with OEM quality benchmarks for interior components. Maharashtra and Gujarat manufacturing clusters host emerging seating integrators serving Maruti Suzuki and Mahindra platforms.
Global Automotive Rear Mounted Tray Market Key Industry Players
The competitive structure tilts toward integrated seating specialists with captive polymer compounding capabilities. Tier-1 suppliers dominate OEM direct channels through long-term platform agreements, while regional fabricators serve aftermarket and commercial van segments. Two archetypes prevail: multinational seating integrators with REACH-certified material traceability, and captive OEM production units controlling in-house demand. Consolidation pressure is mounting through OEM procurement rationalization and cross-border qualification requirements.
Among Japanese seating specialists, Sanko Gosei and Kasai Kogyo Co., Ltd. exemplify the integrated tier-1 archetype with deep OEM program relationships. Grupo Antolin represents the European multinational model, leveraging polymer compounding expertise across multiple substrate grades for compliance-heavy markets. These three anchors illustrate how geographic specialization and regulatory proximity shape competitive positioning in a procurement environment that privileges material certification and platform-scale supply security.
| Leading Market Players |
|---|
| Sanko Gosei |
| Trim India Pvt. Ltd. |
| Grupo Antolin |
| Kasai Kogyo Co., Ltd. |
| AD Plastics d.d. Solin |
| Dongfeng Motor Parts & Components (Group) Co., Ltd. |
| Lih Feng Jiing Enterprise Co., Ltd. |
| Toyota |
| Rochling Group |
| Others |
Cost & Logistics Intelligence
Polymer compounding chemists with REACH certification expertise cluster in Bavaria and Aichi Prefecture, and this workforce concentration propagates labor-cost differentials across three distinct pricing tiers for European and Japanese OEM supply contracts.
Pricing Analysis
Bundled material-certification-and-testing packages command premium positioning against unbundled tray-only supply. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European compounders from mid-tier Asian processors and unbranded aftermarket distributors. Price differentiation hinges on emission compliance documentation and Class-A surface finish capability. Pricing pressure stems from Detroit automakers consolidating procurement volumes through long-term platform agreements. Fleet operators like Hertz and Enterprise Holdings exhibit highest price sensitivity, while luxury German marques maintain lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Transoceanic freight cost volatility has compressed margin buffers for polypropylene resin shipments from Middle Eastern feedstock hubs to injection molding facilities in Germany, Japan, and the United States. Raw material dependencies center on propylene monomer, ABS pellet grades, and natural fiber fillers from flax and hemp cultivators. Single-source vulnerability concentrates in multi-cavity mold fabrication for Class-A surface finishes, locking suppliers into single-platform dependencies. Distribution runs through captive OEM direct channels for factory-installed programs, with aftermarket e-commerce platforms gaining share in replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story where OEM procurement consolidation favors suppliers with proven emission compliance, justified by fleet operators consolidating specification authority around unified durability standards.
For Market Incumbents: To counter margin compression from OEM direct procurement consolidation, Grupo Antolin and Kasai Kogyo should deepen captive compounding capabilities in emission-certified substrate grades while securing long-term platform agreements with three-row SUV manufacturers. Backward integration into polymer formulation secures supply security against propylene monomer volatility. For New Entrants and Emerging Players: Capture localized assembly opportunities under India's PLI scheme automotive incentives before established seating integrators establish regional compounding footholds. Target domestic SUV production subsidies in Maharashtra and Gujarat with modular tray-tablet holder-charging pad convergence offerings. Pursue direct-to-consumer digital configurators to bypass traditional aftermarket distribution markups. For Investors and Strategic Acquirers: Tier-1 seating manufacturers with REACH-certified material traceability are the most active acquirer in this space, seeking polymer compounding specialists to fill capability gaps. Long-term viability favors integrated suppliers with platform-scale supply security over fragmented aftermarket fabricators. Watch for SAMR GB standard recertification deadlines as inflection indicators for Chinese supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Certified Material Traceability Investment | ECHA compliance documentation secures access to BMW and Volvo European SUV platform programs. |
| Modular Seat-Back Ecosystem Development | Tray-tablet holder-charging pad convergence raises per-vehicle content capture in three-row configurations. |
| India PLI Scheme Localization | Domestic SUV production subsidies in Maharashtra create supply openings for tray module assembly. |
| Real-Time Volatile Monitoring Retrofit | Shanghai and Guangdong compounding lines meet SAMR GB formaldehyde and benzene emission caps for BYD access. |
| Natural Fiber-Reinforced Polypropylene Adoption | Flax and hemp fillers reduce petroleum dependency while maintaining load ratings for BMW European lines. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, polymer compounding technical directors, and fleet specification managers with secondary validation from vehicle production databases, IHS Markit registration data, customs trade records, and EPA emission filing repositories. Bottom-up tray shipment estimates triangulated against top-down automotive production forecasts across the analysis window.
Segment-weighting approaches distributed volume and value projections across substrate grade tiers, vehicle class architectures, installation method categories, and regional production clusters. CAGRs derived from regression analysis of historical shipment patterns and OEM platform lifecycle commitments, with propylene monomer price indices and REACH certification adoption curves serving as automotive-specific forecast inputs throughout the modeling period.
Feedstock price volatility, regulatory recertification timelines, and OEM platform cancellation decisions are the dominant revision risks to trajectory assumptions. A model refresh is warranted upon material change in ECHA REACH substance restriction amendments or SAMR GB standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Africa Automotive Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Global Automotive Oem Market