
 Automotive Cross Member Market | 2026-2036
Automotive Cross Member Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cross Member Market Outlook
Multi-material chassis engineering is fragmenting traditional steel-dominated supply chains for structural automotive components. Gestamp Automoción leverages hot-stamping expertise to sustain competitive positioning in high-strength steel cross members. ThyssenKrupp AG anchors European supply through integrated flat-steel-to-component production. Magna International Inc. competes across aluminum and composite architectures, extending its role as a full-vehicle-systems integrator.
An automotive cross member is a transverse structural beam, typically spanning 800–1,400 mm in passenger vehicles, that connects the left and right side rails of a vehicle frame or unibody to provide torsional rigidity, crash energy management, and mounting points for suspension or powertrain components. Front cross members in steel remain the volume backbone due to established stamping infrastructure and cost efficiency, while aluminum load-bearing cross members capture expanding margin pools as OEMs pursue mass reduction targets. Composite bracket cross members represent the fastest-growing material trajectory, though from a smaller base, driven by electric vehicle platform demands for corrosion resistance and parts consolidation.
The EPA enforces Corporate Average Fuel Economy standards that directly incentivize lightweight chassis components, while NHTSA crashworthiness regulations mandate minimum structural integrity thresholds that cross member designs must satisfy. EMA and REACH in Europe impose substance restrictions and end-of-life accountability that favor recyclable aluminum over certain polymer composites. Stakeholders must monitor how pending revisions to these frameworks, particularly around lifecycle carbon accounting, will reshape material qualification timelines and supplier certification requirements.
Market Dynamics
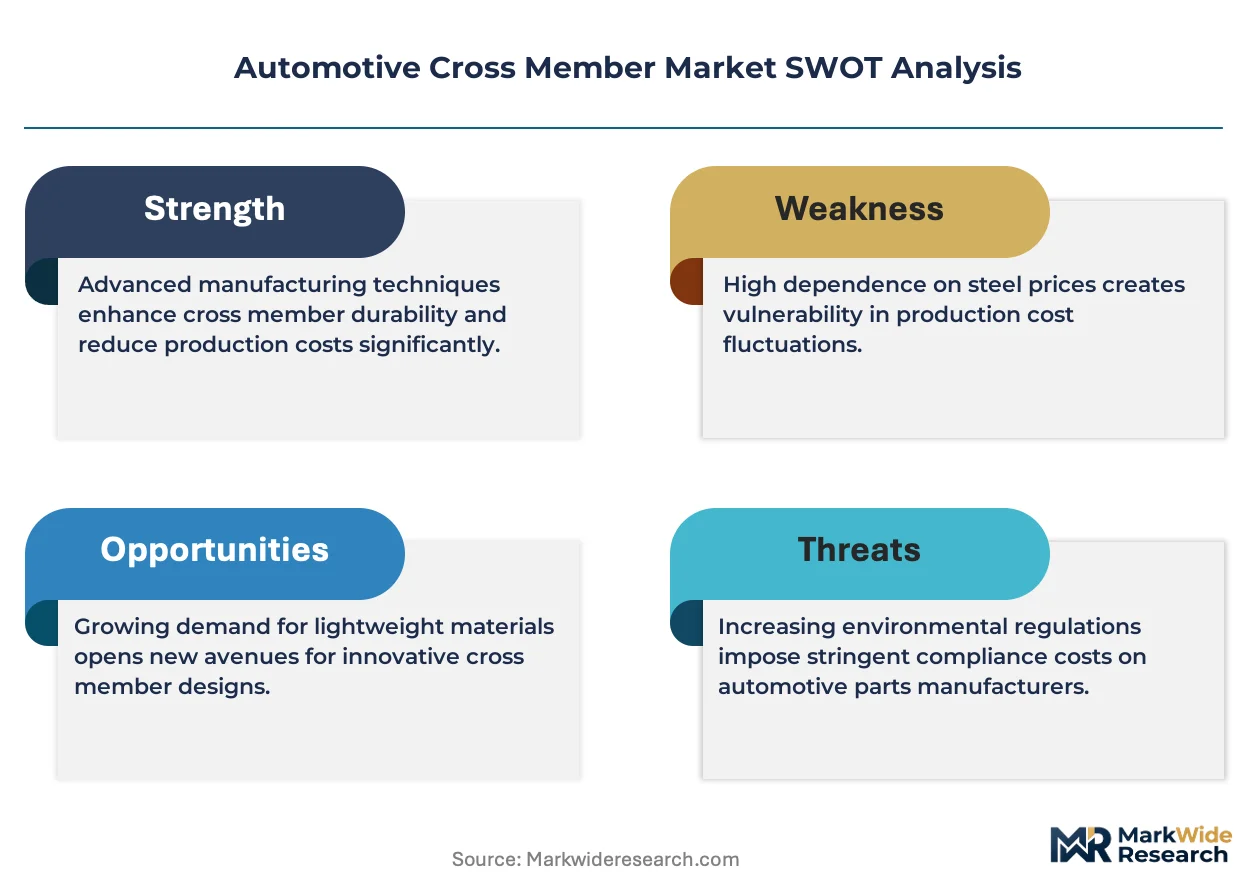
Platform electrification is collapsing legacy chassis architectures and forcing cross member suppliers to requalify materials for battery-integrated vehicle structures. This structural shift compresses development cycles while expanding the addressable market for lightweight alternatives to conventional steel stampings.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:US OEMs face escalating penalties for fleet inefficiency, accelerating aluminum cross member adoption in mid-size vehicle programs to hit mass reduction targets.
- Battery electric vehicle platform proliferation:Dedicated EV architectures from multiple OEMs require corrosion-resistant front subframe modules that accommodate battery protection zones without traditional engine mounting loads.
- Germany:Dense automotive engineering clusters around Stuttgart and Munich anchor prototype-to-production pipelines for composite cross member validation, shortening supplier qualification timelines.
Market Restraints
- Aluminum price volatility:London Metal Exchange aluminum contract swings directly compress margin pools for stamped cross member suppliers locked into annual OEM pricing agreements.
- High-strength steel tooling amortization:Existing press-hardening lines in Lower Saxony and Bavaria represent sunk capital that resists premature replacement despite composite performance gains.
- REACH substance restrictions:ECHA scrutiny of certain epoxy resin hardeners complicates thermoset composite qualification for structural crash members in European vehicle programs.
Strategic Opportunities
- India:PLI scheme incentives for advanced automotive components create entry pathways for aluminum cross member suppliers establishing local stamping capacity near Chennai and Pune manufacturing corridors.
- Modular electric skateboard platforms:Convergence of structural battery enclosures with front cross member functions enables parts consolidation and tier-one supplier scope expansion.
- EU Green Deal lifecycle carbon accounting:Pending methodology revisions favor recyclable aluminum over glass-fiber composites in public procurement-weighted OEM supplier scorecards.
Industry Challenges
- Multi-material joining expertise:Shortage of process engineers skilled in friction stir welding and structural adhesive specification slows hybrid steel-aluminum cross member ramp-ups.
- Crash certification timeline compression:NHTSA and Euro NCAP protocol updates require simultaneous structural validation across frontal offset and small overlap test modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cross Member Market |
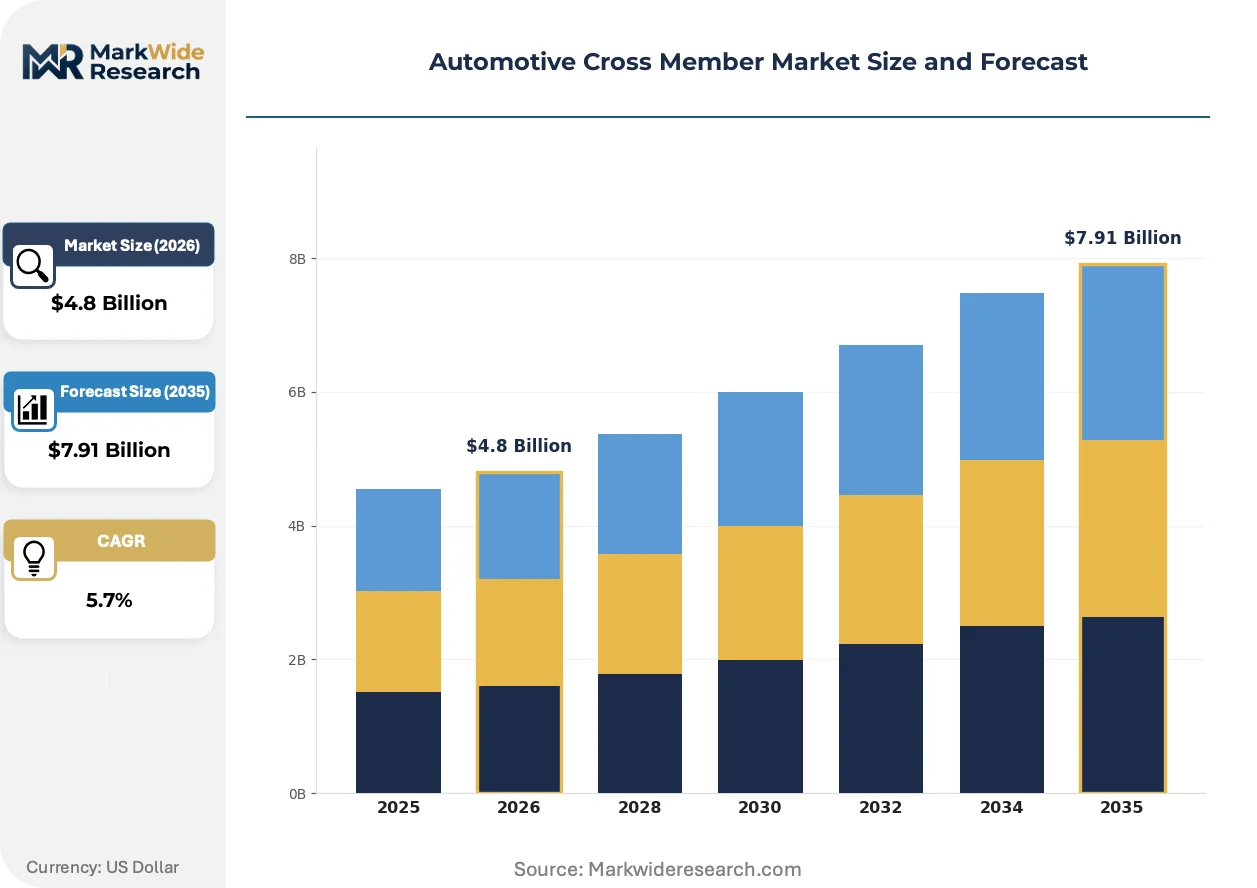
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Cross Member, Rear Cross Member, Load-Bearing Cross Member, Bracket Cross Member Material: Steel, Aluminum, Composite, Plastic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Manufacturing Stage: Stamping, Welding, Assembly, Coating |
| Companies Covered | Magna International Inc., Benteler Automotive, KIRCHHOFF Automotive GmbH, Gestamp Automoción, ThyssenKrupp AG, CIE Automotive, Tower International, Metalsa S.A. de C.V., Yorozu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cross Member Market Strategic Shifts
Material science advances are dissolving traditional boundaries between metallic and polymer structural solutions. Suppliers now compete on integrated subsystem design rather than commodity component supply.
Carbon fiber-reinforced polymer hybrid structures are hybridizing conventional cross member engineering by embedding continuous fiber tapes into injection-molded brackets for localized stiffness tuning. Tier-one integrators targeting premium EV platforms deploy these solutions to eliminate bolted joints and reduce assembly labor content. The technology is hybridizing competitive positioning around subsystem integration depth rather than standalone component cost.
REACH substance restriction expansions through ECHA's 2024-2025 candidate list updates are disqualifying legacy adhesive chemistries from structural bonding applications. Automotive suppliers face reformulation costs and requalification delays for crash-durable epoxy systems. Cross member programs serving European OEMs are responding with accelerated screening of bio-based polyurethane alternatives.
Consolidated sourcing agreements are compressing supplier bases as OEM chassis engineering teams reduce qualified vendor lists from twelve to four partners per platform. Tier-one integrators with full aluminum-to-composite capability capture expanded scope. This concentration is most visible in Germany where Volkswagen Group and BMW have centralized cross member procurement under single-source subsystem contracts.
Automotive Cross Member Market Segmentation
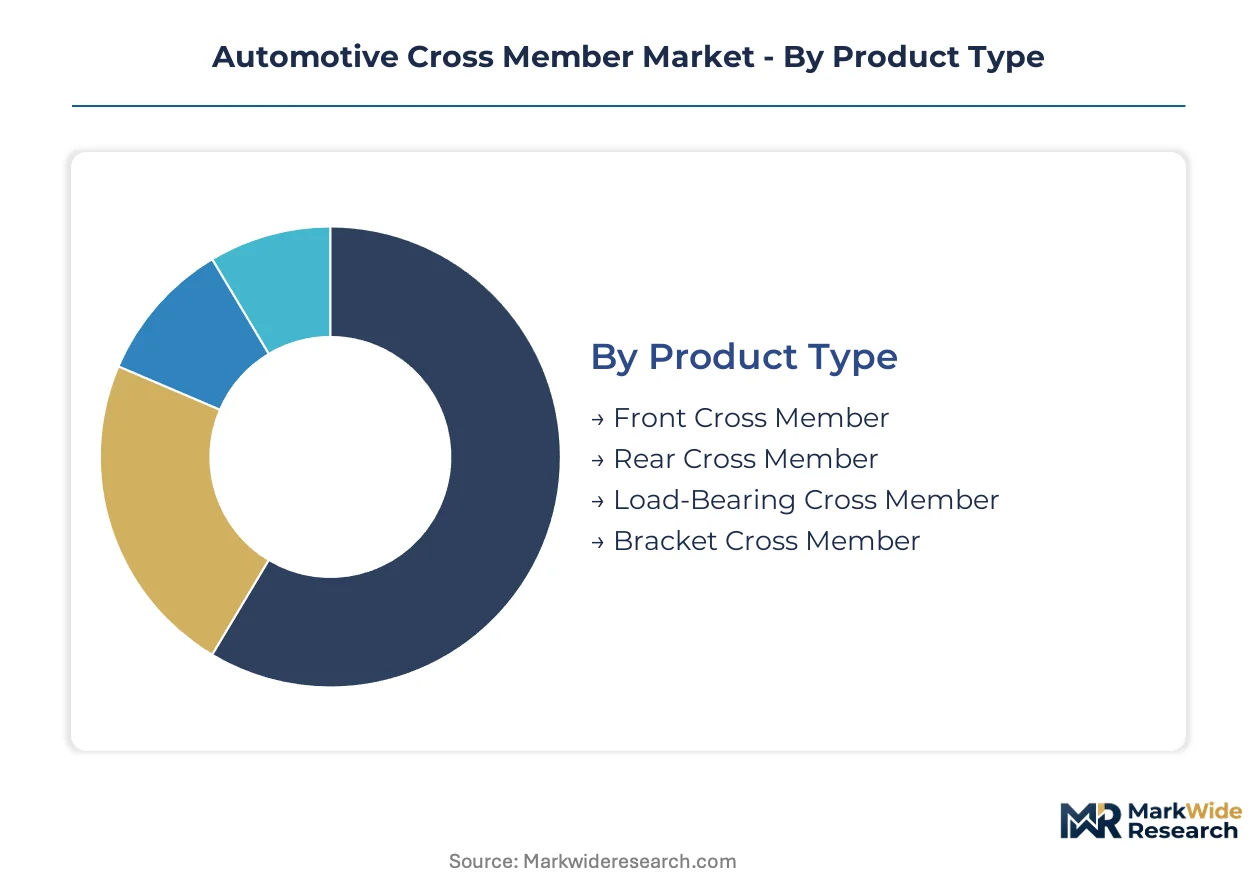
Cross member segmentation reveals how material substitution and manufacturing complexity fragment supplier economics. Product architecture and end-user procurement power determine margin structures across the value chain.
Product Type:
Application positioning separates structural load-bearing functions from bracket mounting roles in chassis design.
- Front Cross Member:Transverse beam spanning 800–1,400 mm that anchors suspension mounting points and manages frontal crash energy. German OEMs concentrate procurement for mid-size ICE platforms where press-hardened steel retains cost advantages.
- Load-Bearing Cross Member:Directly supports powertrain or battery mass with torsional rigidity specifications exceeding 15 kN·m/degree. Aluminum extrusions capture expanding share as EV platforms eliminate engine loads while adding battery protection requirements.
- Rear Cross Member:Closes the rear subframe structure and provides axle attachment geometry.
- Bracket Cross Member:Localized mounting interface for steering racks or cooling modules rather than primary structural member.
Front cross members command the established base. The steepest expansion runs through load-bearing architectures.
Material:
Cost tier and mass reduction targets drive qualification timelines across metallic and polymer alternatives.
- Steel:Hot-stamped boron grades achieve 1,500 MPa tensile strength at 60% lower raw material cost than aluminum. Existing press infrastructure in Lower Saxony and Bavaria sustains volume dominance despite mass penalties.
- Composite:Glass-fiber-reinforced thermoplastics enable 40% mass reduction versus steel with corrosion immunity for battery-adjacent mounting. REACH scrutiny of epoxy hardeners delays European qualification for structural crash members.
- Aluminum:Extruded and cast alloys balance recyclability credentials against LME price volatility.
- Plastic:Injection-molded brackets serve non-structural routing and isolation functions.
Steel retains the volume anchor. Composites are climbing the fastest on EV platform penetration.
End User:
Customer type concentration determines pricing power and contract structure across the supply hierarchy.
- OEMs:Volkswagen Group and BMW centralize cross member procurement under single-source subsystem contracts covering aluminum-to-composite capability. Consolidated vendor lists compress from twelve to four qualified partners per platform.
- Tier-1 Suppliers:Gestamp and Magna extend scope from component supply to full front-module integration, capturing design responsibility and assembly labor content.
- Vehicle Assemblers:Contract manufacturers with limited chassis engineering resources.
- Aftermarket Providers:Collision repair channels for legacy vehicle parc.
OEM direct procurement anchors revenue concentration. Tier-1 integrators are gaining share fastest through subsystem scope expansion.
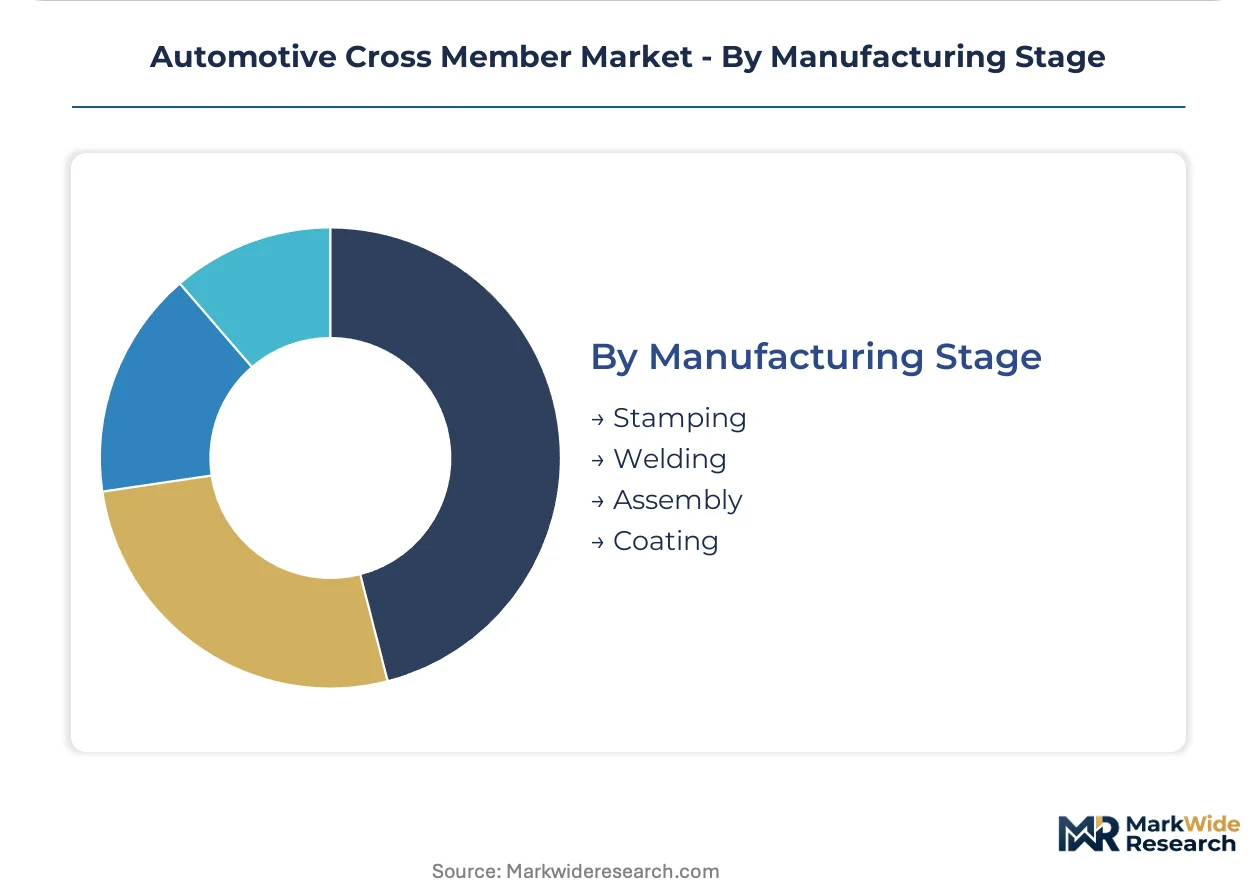
Manufacturing Stage:
Process maturity and capital intensity segment supplier capabilities across the production chain.
- Stamping:Progressive die and transfer press operations form the high-volume backbone with cycle times under 10 seconds per part. Press-hardening lines represent sunk capital that resists displacement despite composite performance gains.
- Welding:Friction stir and laser joining of multi-material assemblies demands scarce process engineering expertise.
- Assembly:Module integration of cross members with suspension or steering subsystems.
- Coating:E-coat and cathodic dip processes for corrosion protection.
Stamping commands the established base. Welding capacity is expanding most quickly on hybrid material adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEM procurement power concentrates among German and US-based chassis engineering teams, with tier-one suppliers anchoring production capacity near Stuttgart, Detroit, and Shanghai manufacturing corridors.
United States
EPA Corporate Average Fuel Economy standards pressure Detroit-based OEMs toward aluminum-intensive cross member architectures for mid-size truck and SUV platforms. NHTSA crashworthiness protocols mandate simultaneous validation across frontal offset and small-overlap test modes. Michigan and Ohio stamping clusters retain steel volume dominance despite EV platform disruption.
Germany
Volkswagen Group and BMW centralize procurement under single-source subsystem contracts covering aluminum-to-composite capability. EU Green Deal lifecycle carbon accounting favors recyclable aluminum over glass-fiber composites in supplier scorecards. Stuttgart and Munich engineering clusters anchor prototype-to-production pipelines for composite validation.
China
Domestic EV platform proliferation from BYD and NIO drives demand for corrosion-resistant front subframe modules accommodating battery protection zones. MIIT dual carbon goals accelerate material substitution timelines. Yangtze River Delta stamping capacity expands to serve battery-integrated vehicle structures.
India
PLI scheme incentives for advanced automotive components create entry pathways for aluminum cross member suppliers establishing local capacity. Maruti Suzuki and Tata Motors source front cross members for compact vehicle programs. Chennai and Pune manufacturing corridors attract tier-one stamping investments.
Japan
Toyota and Honda chassis engineering teams specify hybrid steel-aluminum architectures for next-generation platforms. METI carbon neutrality roadmaps favor closed-loop aluminum recycling systems. Nagoya and Tokyo supplier clusters specialize in friction stir welding for multi-material joining.
Automotive Cross Member Market Competitive Environment
Channel-controlling players compete with product-specialist players across material tiers and manufacturing stages. Tier-one integrators with full aluminum-to-composite capability capture expanded scope through subsystem contracts, while steel-focused stampers defend volume positions in legacy ICE platforms. Three archetypes dominate: full-systems integrators, material-specific specialists, and regional stamping houses. Competitive moves concentrate on M&A for technology access and capacity expansion near OEM assembly plants.
Among European-anchored fabricators, Gestamp Automoción and ThyssenKrupp AG exemplify the integrated steel-to-component archetype, while Magna International Inc. occupies a position spanning multiple material systems. These three represent the tier-one integrator category that has captured procurement consolidation from twelve to four qualified partners per platform. Specialists in composite and hybrid architectures sit within a separate tier, competing on subsystem design depth rather than commodity stamping scale.
| Leading Market Players |
|---|
| Magna International Inc. |
| Benteler Automotive |
| KIRCHHOFF Automotive GmbH |
| Gestamp Automoción |
| ThyssenKrupp AG |
| CIE Automotive |
| Tower International |
| Metalsa S.A. de C.V. |
| Yorozu Corporation |
| Others |
Value Chain & Pricing Dynamics
Press-hardening capacity concentration in Lower Saxony and Bavaria anchors steel cross member supply, concentrating margin pools with tier-one integrators capable of multi-material qualification while compressing pricing power for commodity stampers locked into annual OEM contracts.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate tier-one supplier agreements, creating margin volatility when raw material swings outpace contractual adjustment windows. Price differentiation separates hot-stamped steel grades from aluminum extrusions based on mass reduction certification tiers, with EV platform procurement showing lowest price sensitivity due to lifecycle carbon scoring requirements. Pricing pressure intensifies in legacy ICE programs where high-strength steel tooling amortization resists displacement despite composite performance gains.
Supply Chain Analysis
Export-control scrutiny of friction stir welding equipment and structural adhesive chemistries under ECHA REACH candidate list updates constrains technology transfer into European manufacturing corridors. Supply concentration centers on Germany, China, and Mexico, with raw material dependencies spanning LME-traded aluminum, hot-rolled boron steel, and glass-fiber-reinforced thermoplastics. Single-source vulnerability around qualified epoxy hardeners for crash-durable bonding creates qualification bottlenecks. Distribution runs through consolidated subsystem contracts directly to OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive cross member procurement is consolidating under platform-economics logic, where battery-integrated vehicle architectures collapse legacy chassis boundaries and reward subsystem integrators with full aluminum-to-composite capability across shared EV skateboard designs.
For Market Incumbents: Build switching-cost moats through captive friction stir welding expertise and structural adhesive formulation libraries. Gestamp and Magna extend competitive insulation by securing single-source subsystem contracts covering front-module integration, while ThyssenKrupp defends steel volume through press-hardening capacity additions near Stuttgart assembly corridors. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized aluminum stamping corridor near Chennai and Pune, where Maruti Suzuki and Tata Motors source front cross members for compact vehicle programs with limited incumbent qualification. Target composite bracket architectures for battery-adjacent mounting functions where corrosion immunity outweighs structural crash certification burdens. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European stamping houses holding stranded high-strength steel tooling in Bavaria and Lower Saxony. Long-term viability hinges on multi-material retrofit capability or geographic redeployment toward Indian manufacturing corridors. Watch for EU Green Deal lifecycle carbon accounting methodology revisions as the signal forcing aluminum qualification acceleration over glass-fiber composites.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Shared EV skateboard architectures enable parts consolidation across OEM vehicle programs. |
| Battery Supply Agreement | Structural battery enclosure integration with cross member functions expands tier-one scope. |
| Software-Defined Vehicle Investment | Digital twin validation compresses crash certification timelines for multi-material designs. |
| Geographic Manufacturing Footprint | Local stamping capacity near Chennai and Pune captures PLI scheme incentives for aluminum components. |
| Charging Infrastructure Partnership | Corrosion-resistant composite architectures align with battery protection zone requirements. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, tier-one supplier procurement directors, aftermarket distributors, and dealership operations managers, then refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed suppliers, and customs records for aluminum and steel trade flows. Bottom-up segmentation modeling triangulated with top-down macroeconomic overlays anchored volume and value estimates.
Demand-supply balance framing across the projection horizon modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with OEM platform rollout schedules and battery electric vehicle penetration assumptions. Forecast inputs incorporated EPA Corporate Average Fuel Economy compliance trajectories and EU Green Deal carbon accounting methodology evolution.
Macroeconomic conditions sit as an overlay; deviation in aluminum price volatility, interest rate environments affecting automotive capex cycles, or geopolitical trade restriction intensity would shift the trajectory. Material shifts in ECHA REACH substance restriction scope or NHTSA crashworthiness protocol updates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Automotive Frame Machine Market