
 Automotive Frame Machine Market | 2026-2036
Automotive Frame Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Frame Machine Market Analytics
Direct-to-shop distribution is tilting as manufacturers bypass traditional jobber networks to sell frame machines straight to high-volume collision repair groups. Snap-on Incorporated (Kansas Jack) leverages its captive financing arm to lock in multi-year equipment contracts with national MSO chains. Car-O-Liner Group AB anchors its position through factory-trained technician certification programs that bind shops to its measurement software ecosystem. Chief Automotive Technologies competes by extending its North American field service density to same-day calibration support in top metro markets.
An automotive frame machine is a heavy-duty shop fixture that clamps, measures, and hydraulically pulls damaged vehicle structural components back to factory dimensional tolerances, typically achieving pull forces exceeding ten tons through hardened anchor towers and chain assemblies. Its core commercial purpose is to restore crash-damaged unibody or frame-rail geometry so that advanced driver-assistance system sensors recalibrate correctly and the vehicle passes post-repair safety inspections. Hydraulic machines dominate installed base volume due to their proven reliability under continuous shop-floor cycles, while computerized machines with integrated laser measurement represent the fastest-expanding segment as insurers mandate documentation of pre- and post-repair dimensional data. Specialty repair centers focused on aluminum-intensive vehicle architectures command disproportionate margin pools because their frame machines require isolated bays and non-ferrous tooling that generalist shops rarely stock.
The US Department of Transportation through NHTSA enforces repair procedure transparency rules that push shops toward documented, measurable frame restoration rather than visual approximation. In Europe, CE marking under the Machinery Directive and REACH substance restrictions on hydraulic fluids constrain equipment import specifications and ongoing maintenance chemistry choices. China's SAMR enforces GB standards for workshop equipment safety that foreign manufacturers must certify before domestic sale. Stakeholders must monitor how OEM repair network exclusivity clauses and insurer direct-repair program equipment mandates reshape shop purchasing autonomy.
Market Dynamics
Computerized frame straightening systems are compressing repair cycles and forcing collision shops to abandon manual measurement methods, while insurer mandates for dimensional documentation accelerate capital replacement across the installed base.
Growth Catalysts
- ADAS Recalibration Mandates:Advanced driver-assistance system sensors require precise structural restoration, compelling shops to invest in laser-measurement-equipped frame machines that document geometric accuracy to manufacturer specifications.
- CE Marking Compliance:European collision repair networks under Machinery Directive enforcement must maintain certified equipment, creating recurring demand for factory-validated frame straightening systems with traceable calibration records.
- Aluminum Architecture Proliferation:OEM vehicle platforms increasingly incorporate aluminum-intensive unibody designs, requiring isolated bay configurations and non-ferrous tooling that generalist shops cannot retrofit.
Market Restraints
- Hydraulic Fluid Chemistry Constraints:REACH substance restrictions on hydraulic fluids limit maintenance chemistry choices and increase ongoing operating costs for European equipment operators.
- Specialized Technician Scarcity:Factory-trained certification programs for measurement software ecosystems create bottlenecks, constraining deployment velocity for advanced frame machine installations.
- Capital Equipment Intensity:Computerized systems with integrated laser measurement demand substantial upfront investment, extending payback periods for independent collision repair shops.
Strategic Opportunities
- Chinese Domestic Certification:SAMR enforcement of GB standards for workshop equipment safety creates a regulated entry pathway for manufacturers achieving domestic certification ahead of competitors.
- Direct Distribution Channels:Equipment manufacturers bypassing traditional jobber networks to sell straight to high-volume collision repair groups capture margin and lock in multi-year service contracts.
- Aluminum-Intensive Specialization:Repair centers developing isolated bay infrastructure for non-ferrous vehicle architectures command disproportionate margin pools unavailable to generalist competitors.
Industry Challenges
- Technician Certification Timelines:Factory-trained programs for measurement software ecosystems bind shops to specific vendor platforms, creating switching friction and skill silos.
- Field Service Density Requirements:Same-day calibration support in top metro markets demands substantial North American field service investment, compressing margins for regional equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Frame Machine Market |
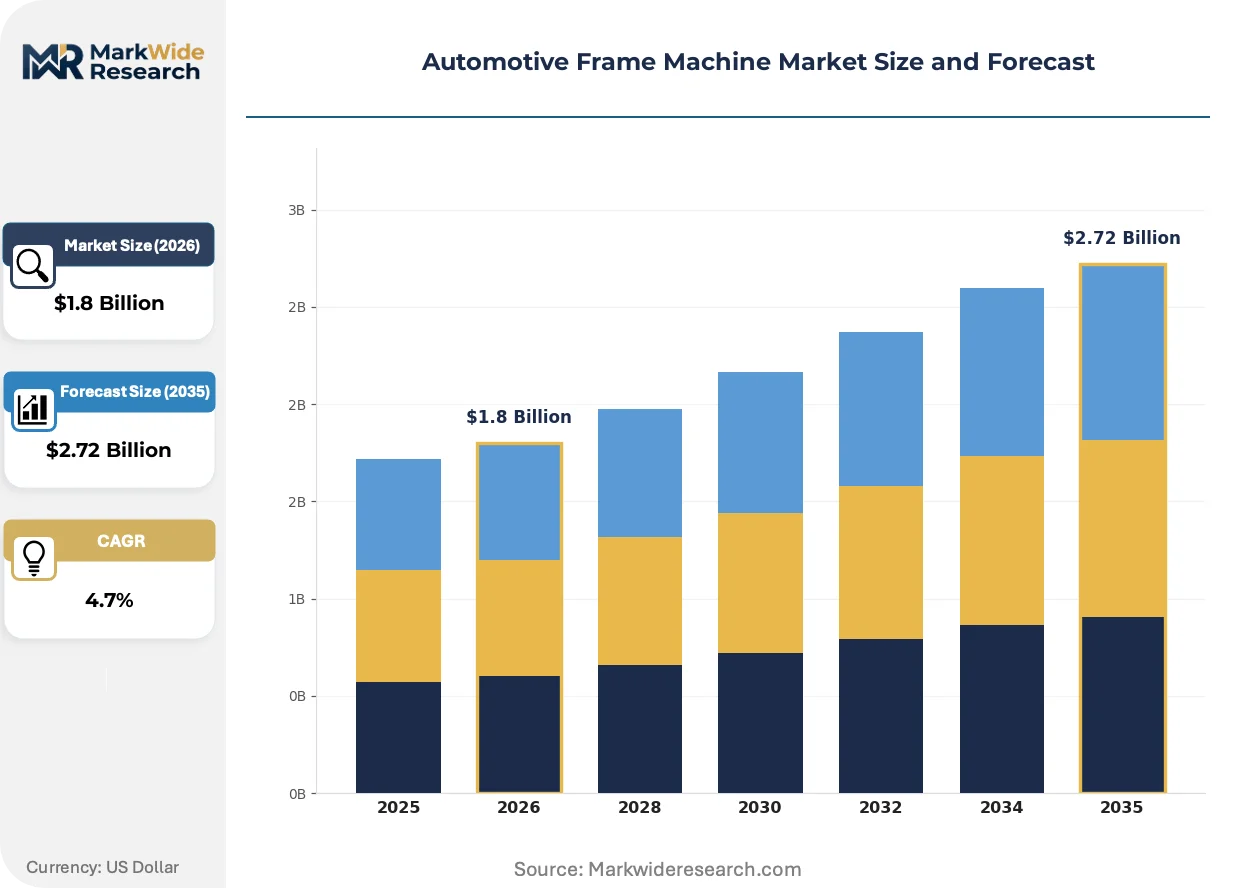
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Machines, Pneumatic Machines, Manual Frame Machines, Computerized Machines End User: Commercial Garages, Automotive Manufacturers, Vehicle Repair Shops, Specialty Repair Centers Technology: Laser Measurement, 3D Alignment, Traditional Methods, Ultrasonic Testing Size: Small Machines, Medium Machines, Large Machines, Specialty Machines |
| Companies Covered | Snap-on Incorporated (Kansas Jack), Globaljig North America LLC, Car-O-Liner Group AB, Autorobot Finland Oy, Chassis Liner Supply, Celette France, SAS, Blackhawk Automotive, Yantai Jintuo Automobile Technology Co., Ltd., Chief Automotive Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Frame Machine Market Evolving Landscape
Measurement technology and distribution architecture are converging to reshape how collision repair shops acquire, operate, and justify frame straightening equipment to insurer partners and OEM certification programs.
Laser-integrated measurement systems are hybridizing hydraulic pull architectures with real-time dimensional capture, enabling continuous geometric verification during structural pulls. High-volume collision repair groups in Germany and the United States are adopting these configurations fastest. This convergence is compressing the distinction between manual and computerized frame machine categories, forcing mid-tier suppliers to choose specialization or exit.
NHTSA repair procedure transparency rules are mandating documented, measurable frame restoration rather than visual approximation. Collision repair shops across the United States must now maintain pre- and post-repair dimensional records to satisfy insurer direct-repair program requirements. The aftermarket collision repair channel is responding by prioritizing equipment with integrated documentation capabilities.
Captive financing arms are displacing traditional equipment leasing through multi-year contracts that bundle machinery, software licenses, and maintenance into single obligations. National MSO chains in the United States and commercial garage networks in China are gravitating toward these consolidated arrangements. This bundling is most visible where insurer direct-repair program equipment mandates reduce shop purchasing autonomy.
Automotive Frame Machine Market Segmentation
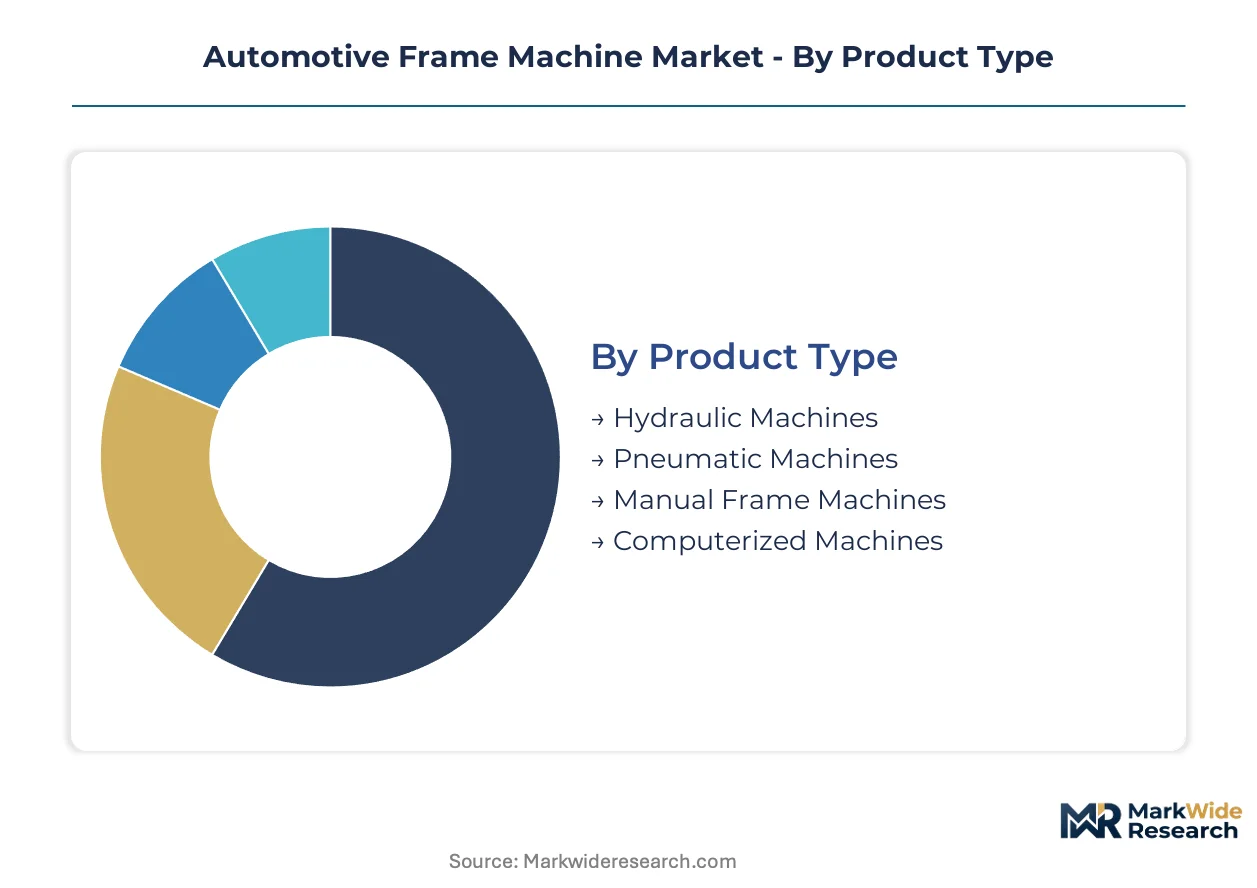
Frame machine segmentation reflects divergent service intensity requirements across repair modalities. Equipment configuration directly determines calibration frequency, field service dependency, and software subscription attach rates that manufacturers monetize over multi-year ownership cycles.
Product Type:
After-sales-service intensity varies sharply across product architectures, with measurement-integrated systems demanding continuous software validation and hydraulic platforms requiring scheduled fluid analysis.
- Hydraulic Machines:These systems deploy hardened anchor towers and chain assemblies delivering pull forces exceeding ten tons through continuous shop-floor cycles. Commercial garages across Germany and the United States concentrate demand here for proven reliability under high-volume collision repair schedules. Factory-trained technician programs bind operators to specific vendor ecosystems, creating recurring calibration revenue streams.
- Computerized Machines:Laser-measurement-equipped platforms integrate real-time dimensional capture with hydraulic pull architectures, enabling continuous geometric verification during structural restoration. Collision repair shops facing insurer mandates for pre- and post-repair documentation drive fastest adoption in this segment, accepting extended payback periods for compliance capabilities.
- Pneumatic Machines:Compressed-air-driven systems serve lower-volume repair environments with reduced capital requirements and simpler maintenance protocols.
- Manual Frame Machines:Visual approximation methods persist in emerging market workshops with limited insurer oversight and minimal ADAS recalibration requirements.
By volume, Hydraulic Machines lead. By growth pace, Computerized Machines are expanding most quickly.
End User:
Customer type determines procurement autonomy, with national MSO chains leveraging consolidated financing against independent shops facing capital constraints.
- Commercial Garages:Multi-bay operations serving fleet maintenance and high-throughput collision repair prioritize equipment uptime and same-day calibration support. These buyers negotiate multi-year service contracts bundling machinery, software licenses, and maintenance into single obligations through captive financing arms.
- Specialty Repair Centers:Isolated bay configurations for aluminum-intensive vehicle architectures command disproportionate margin pools through non-ferrous tooling and OEM certification requirements that generalist competitors cannot replicate. I-CAR and automaker program mandates in the United States concentrate demand here.
- Vehicle Repair Shops:Independent collision repair facilities balance capital equipment intensity against insurer direct-repair program equipment mandates that reduce purchasing autonomy.
- Automotive Manufacturers:OEM repair network exclusivity clauses drive equipment standardization within certified facility programs, creating captive demand for factory-validated systems.
Commercial Garages generate highest absolute revenue. Specialty Repair Centers capture steepest margin expansion.
Technology:
Measurement modality selection fixes shops to specific software ecosystems, generating switching friction and skill silos that vendors exploit for recurring revenue.
- Laser Measurement:Real-time dimensional capture systems document geometric accuracy to manufacturer specifications, satisfying NHTSA repair procedure transparency rules and insurer direct-repair program requirements. These platforms demand continuous software validation and field service density for same-day calibration support in top metro markets.
- 3D Alignment:Spatial coordinate mapping enables comprehensive unibody geometry restoration for ADAS sensor recalibration, concentrating demand among shops serving advanced driver-assistance system-equipped vehicles.
- Traditional Methods:Visual approximation and manual measurement persist where regulatory enforcement remains limited and documentation requirements are minimal.
- Ultrasonic Testing:Non-destructive evaluation techniques support structural integrity verification in specialty aluminum repair applications.
Laser Measurement dominates new equipment specifications. 3D Alignment is gaining share fastest among premium shop certifications.
Size:
Equipment scale correlates with bay configuration requirements and technician certification complexity, fragmenting vendor go-to-market approaches.
- Large Machines:Heavy-duty fixtures accommodating commercial vehicle and full-size truck structural restoration require dedicated bay space and specialized anchoring infrastructure. These systems generate highest per-unit revenue but demand extended installation timelines and factory-supervised commissioning.
- Medium Machines:Standard passenger vehicle configurations represent the installed base majority, balancing pull capacity against shop floor footprint constraints.
- Small Machines:Compact units serve mobile repair operations and space-constrained urban facilities with reduced pull force specifications.
- Specialty Machines:Aluminum-isolated bay configurations with non-ferrous tooling address OEM vehicle platform proliferation requiring contamination-controlled environments.
Medium Machines constitute the volume core. Specialty Machines show the steepest expansion trajectory as aluminum architecture proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA repair procedure transparency rules in the United States anchor the regulatory framework that collision repair shops navigate across major automotive markets. Equipment certification requirements and insurer documentation mandates create divergent compliance pathways in each geography.
United States
Collision repair shops face I-CAR and automaker program certification requirements that standardize equipment specifications. NHTSA enforces documented frame restoration rather than visual approximation. Chicago and Detroit clusters concentrate demand for high-throughput hydraulic systems serving fleet maintenance networks.
Germany
Commercial garages prioritize CE-marked equipment under Machinery Directive enforcement with traceable calibration records. KBA vehicle safety standards intersect with REACH substance restrictions on hydraulic fluids. Stuttgart and Munich industrial corridors drive fastest adoption of laser-measurement-integrated platforms.
China
SAMR enforces GB standards for workshop equipment safety that foreign manufacturers must certify before domestic sale. Dual carbon goals accelerate demand for energy-efficient hydraulic architectures. Yangtze River Delta repair networks in Shanghai and Suzhou expand computerized system procurement.
Japan
METI industrial standards and JIS certification requirements structure equipment import specifications for collision repair facilities. PMDA does not regulate this equipment class; METI technical standards dominate. Nagoya and Osaka manufacturing belts concentrate specialty aluminum repair center development.
United Kingdom
Post-Brexit regulatory alignment with EU Machinery Directive maintains CE marking requirements for frame straightening systems. The national automotive safety regulator enforces equipment traceability standards. Midlands collision repair clusters in Birmingham and Coventry drive replacement demand for measurement-integrated platforms.
Automotive Frame Machine Market Competitive Landscape
Integrated-system vendors and component-specialist fabricators split the market into distinct competitive tiers. The vendor base concentrates around three strategic archetypes: captive-financing equipment bundlers, software-ecosystem platform owners, and regional field-service specialists. Consolidation pressure intensifies as multi-year service contracts displace spot equipment purchases. Technology licensing partnerships and geographic certification-first expansion represent dominant competitive vectors.
Among North American equipment providers, Snap-on Incorporated and Chief Automotive Technologies exemplify the captive-financing archetype through multi-year contract structures. Car-O-Liner Group AB represents the software-ecosystem model with factory-trained certification programs. Yantai Jintuo Automobile Technology Co., Ltd. occupies a position within the Asia-Pacific fabrication tier.
| Leading Market Players |
|---|
| Snap-on Incorporated (Kansas Jack) |
| Globaljig North America LLC |
| Car-O-Liner Group AB |
| Autorobot Finland Oy |
| Chassis Liner Supply |
| Celette France, SAS |
| Blackhawk Automotive |
| Yantai Jintuo Automobile Technology Co., Ltd. |
| Chief Automotive Technologies |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese hydraulic component manufacturing is compressing supplier margins and tilting pricing power toward collision repair groups with multi-year contract leverage. This utilization imbalance feeds into divergent regional pricing postures, with European CE-marked systems commanding premiums against commoditized Asian supply.
Pricing Analysis
Price spreads between German-engineered laser-measurement systems and Asian hydraulic platforms exceed three-to-one at the equipment tier. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling intensity. Cost compression in the economy tier is intensifying because captive financing arms are subsidizing upfront hardware to capture software subscription streams. National MSO chains exhibit lowest price sensitivity due to consolidated procurement scale, while independent vehicle repair shops face acute capital constraints.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized metal fabrication houses in Shandong Province and precision machining clusters around Stuttgart. Geographic supply concentration centers on China, Germany, and the United States for anchor tower castings, laser measurement modules, and hydraulic pump assemblies. Raw material dependencies draw from high-grade steel alloys, optical sensor components, and REACH-compliant hydraulic fluids. Single-source vulnerability persists in laser interferometer sourcing from German optics specialists. Distribution runs through direct-to-shop channels displacing traditional jobber networks for high-volume collision repair groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive frame machine penetration sits at early-cycle expansion, with ADAS recalibration mandates forcing capital replacement across the installed base faster than natural depreciation schedules.
For Market Incumbents: Harden software-ecosystem lock-in by expanding factory-trained technician certification pipelines that bind shops to proprietary measurement platforms. Deepen backward integration into laser sensor module production to reduce dependency on German optics suppliers and defend margin position against Asian competitors subsidizing hardware to capture service revenue. For New Entrants and Emerging Players: Establish a beachhead in aluminum-intensive specialty repair centers, where isolated bay requirements and non-ferrous tooling create certification barriers that generalist competitors cannot replicate. Target the Chinese domestic certification pathway through SAMR GB standards compliance ahead of multinational rivals, leveraging local fabrication partnerships to undercut landed cost structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across computerized measurement-integrated platforms as software validation and field service density requirements escalate. Long-term viability favors vendors with captive financing capabilities and recurring calibration revenue streams. Monitor I-CAR certification mandate expansion as the inflection signal indicating accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Ecosystem Platform Integration | Factory-trained certification programs bind collision repair shops to proprietary measurement data architectures. |
| Direct-to-Shop Distribution Expansion | Bypassing jobber networks captures margin and locks multi-year service contracts with national MSO chains. |
| Aluminum-Intensive Bay Specialization | Isolated non-ferrous configurations command premium pricing unavailable to generalist competitors. |
| Captive Financing Arm Development | Consolidated equipment-software-maintenance bundles extend payback periods while securing recurring revenue. |
| Field Service Density Investment | Same-day calibration support in top metro markets satisfies insurer direct-repair program mandates. |
Research Methodology
Desk research of equipment specification databases, regulatory filing repositories, and collision repair industry trade publications preceded structured interviews with collision repair shop operators, OEM certification program directors, insurer direct-repair network managers, and hydraulic systems procurement leads. Primary fieldwork combined telephone and video interviews with bottom-up validation against customs records and capital expenditure disclosures. Secondary triangulation drew from NHTSA repair procedure documentation, CE marking certification registries, and SAMR GB standards filings.
Assumptions regarding ADAS penetration rates, OEM certification mandate timelines, and insurer documentation requirements were held fixed across baseline scenarios while aluminum architecture adoption curves and REACH regulatory stringency were stress-tested. Segmentation modeling spanned product architecture, end-user procurement autonomy, measurement technology modality, and equipment scale tier. CAGR derivation rested on installed base replacement cycles and greenfield collision repair facility formation rates across the projection horizon.
Stress conditions across aluminum platform adoption velocity, hydraulic fluid chemistry regulatory shifts, and technician certification bottleneck severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM repair network exclusivity enforcement and insurer equipment mandate expansion. Quarterly review of I-CAR certification requirement updates and SAMR domestic certification approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Activated Carbon Canister Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Africa Automotive Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
China Automotive Heat Exchanger Market