
 Automotive Steering Rack Market | 2026-2036
Automotive Steering Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Steering Rack Market Analytics
EPS-grade precision specifications is unwinding legacy hydraulic architectures across passenger vehicle platforms. Nexteer Automotive Corporation leverages its integrated column-and-rack systems to control supply timelines for North American OEM programs. ZF Friedrichshafen AG anchors European production through its mechatronic rack portfolio, while JTEKT Corporation dominates Asian supply chains with high-volume manufacturing scale.
An automotive steering rack converts rotational input from the steering wheel into linear motion that articulates the road wheels, typically machined from alloy steel with rack teeth cut to module 1.5-3.0 precision and hardened to 58-62 HRC for wear resistance. Electronic assist variants embed torque sensors, brushless motors, and ECUs to deliver variable boost without parasitic engine load. Rack and pinion configurations lead installed base owing to packaging efficiency and direct feedback, while electronic assist is displacing hydraulic architectures fastest as OEMs chase CO2 reduction targets. Aluminum material grades are capturing margin pools where weight savings justify premium pricing over conventional steel forgings.
NHTSA Federal Motor Vehicle Safety Standards govern steering system integrity and occupant protection thresholds in the United States, while EPA corporate average fuel economy mandates indirectly force rack lightweighting to help OEMs avoid penalties. Germany's KBA enforces type approval for steering systems under UN ECE regulations, creating compliance barriers for non-certified suppliers. Stakeholders must monitor how software-defined vehicle architectures integrate steer-by-wire protocols that could eliminate mechanical rack linkages entirely.
Market Dynamics
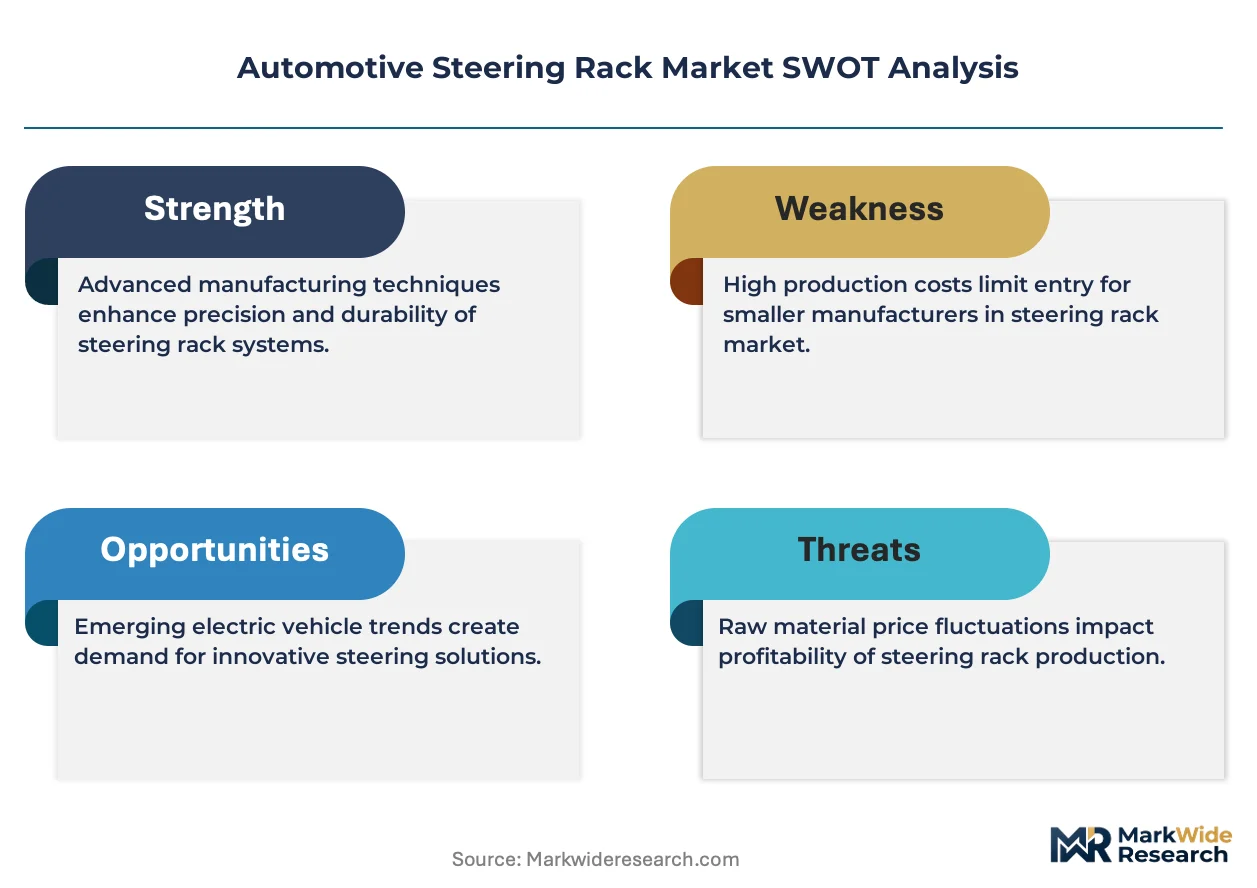
The transition from hydraulic to electric power steering architectures is compressing supplier margins while demanding simultaneous investments in torque sensor calibration, brushless motor integration, and ECU software validation.
Growth Catalysts
- EPA Fuel Economy Mandates:Corporate average fuel economy penalties force OEMs to eliminate parasitic engine loads from hydraulic pumps, accelerating rack electrification across light-duty platforms.
- Aluminum Forging Advances:Heat-treatable 6xxx and 7xxx series alloys now achieve 58-62 HRC surface hardness after nitriding, enabling 30-40% mass reduction in rack housings without sacrificing tooth durability.
- Stuttgart-Wolfsburg Engineering Corridor:Germany's concentrated OEM engineering presence creates localized demand for mechatronic rack prototypes, compressing development cycles from 36 to 24 months for European programs.
Market Restraints
- Neodymium Supply Concentration:Brushless EPS motors depend on rare-earth permanent magnets where 85% of global separation capacity sits in China's Jiangxi and Inner Mongolia processing zones, exposing OEMs to export quota volatility.
- UN ECE Type Approval Barriers:KBA certification requirements for steering system integrity create 18-24 month validation timelines that lock out non-European suppliers lacking local homologation infrastructure.
- Steer-by-Wire Substitution Threat:Software-defined vehicle architectures from Tesla and Hyundai-Kia eliminate mechanical rack linkages entirely, collapsing addressable market for traditional pinion systems by 2035.
Strategic Opportunities
- Commercial Vehicle Electrification:Medium-duty electric trucks in California and the EU's Rhine-Alpine corridor present unserved demand for high-torque EPS racks rated above 12 kN steering force.
- Remanufacturing Channel Expansion:Independent aftermarket distributors in Poland and Mexico are capturing warranty-expired rack replacement volume previously monopolized by OEM dealer networks.
- IRA Clean Vehicle Tax Credits:North American assembly requirements for EV components create tariff-advantaged production locations for rack suppliers establishing US-based forging and motor winding operations.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineers certified to ISO 26262 ASIL-D standards command 40% salary premiums, constraining Tier-2 suppliers' ECU development timelines.
- Legacy Hydraulic Inventory Stranding:Suppliers with sunk capacity in power steering pump and hose production face asset write-downs as OEMs terminate hydraulic architectures mid-platform lifecycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Steering Rack Market |
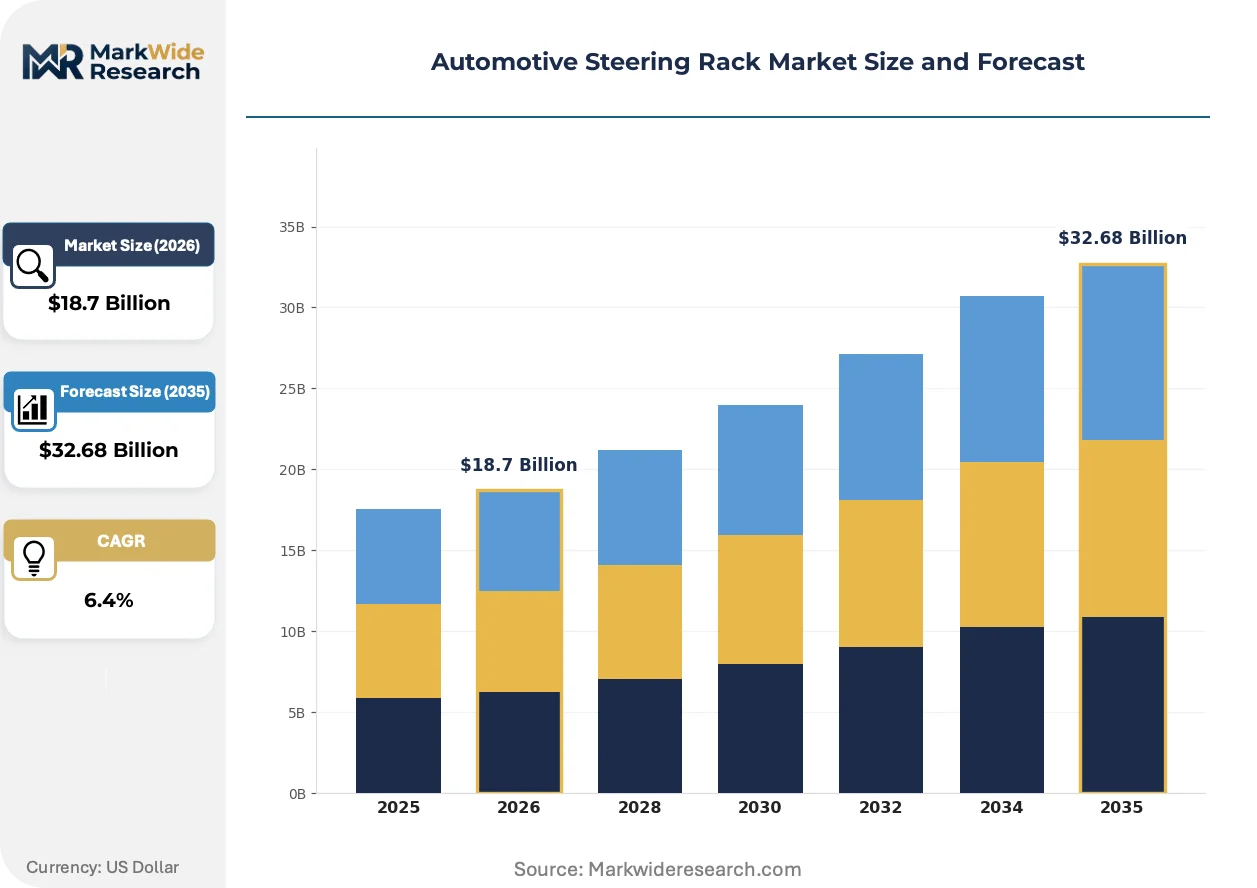
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack and Pinion, Recirculating Ball, Electronic Assist, Hydraulic Assist End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Modified Vehicles Distribution Channel: OEMs, Aftermarket, Online Retail, Specialty Stores Material: Steel, Aluminum, Composite, Others |
| Companies Covered | Nexteer Automotive Corporation, Mando Corporation, JTEKT Corporation, NSK Ltd., Hyundai Mobis Co. Ltd., ZF Friedrichshafen AG, Thyssenkrupp AG, Schaeffler Group, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Steering Rack Market Evolving Landscape
Steering rack engineering is bifurcating between mechanical precision manufacturing and software-defined control systems, forcing suppliers to build dual competencies in metallurgy and embedded systems simultaneously.
Variable-ratio rack tooth profiles is decomposing fixed-geometry steering kinematics. BMW and Mercedes-Benz program teams specify continuously varying rack modules from 1.5 to 3.0 across the travel range, enabling reduced hand-wheel angles during parking without sacrificing highway stability. This compression of mechanical complexity into software-calibrated torque maps is eliminating discrete steering gear variants per platform.
NHTSA Federal Motor Vehicle Safety Standard 203 governs steering column displacement during frontal impact. The regulation's 2025 proposed amendments mandate reduced intrusion thresholds, forcing rack suppliers to integrate collapsible intermediate shaft designs that add 12-15% bill-of-materials cost. US-based light-truck programs are responding with aluminum yoke castings that sacrifice some crash energy absorption for mass savings.
Fleet operators now specify total cost of ownership pricing rather than unit procurement for steering components. Amazon's Rivian delivery van contracts and DHL's StreetScooter programs bundle rack replacement intervals, remanufacturing rights, and telematics-based predictive maintenance. This unbundling of hardware from service liability is most advanced in Germany's last-mile logistics corridor, where municipal emissions zones accelerate electric van deployment.
Automotive Steering Rack Market Segmentation
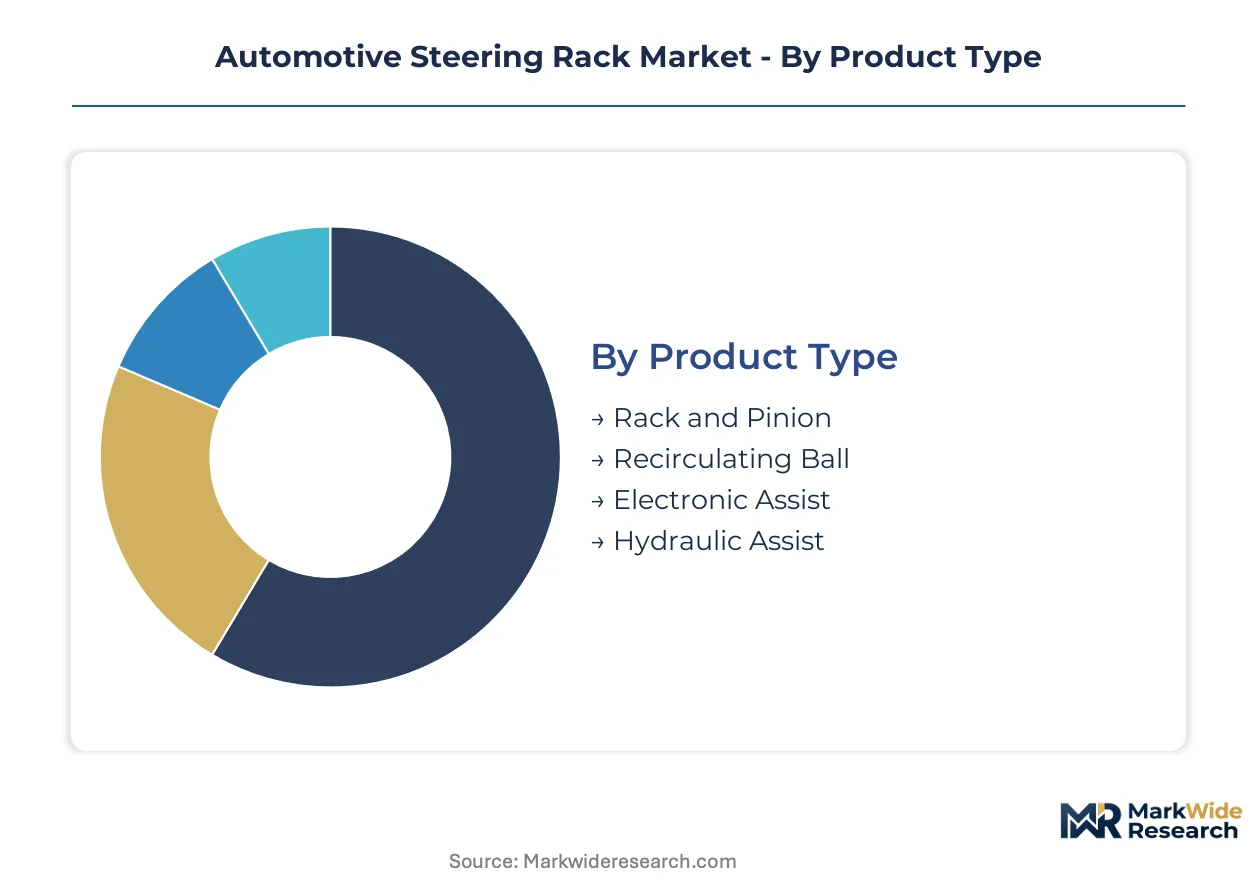
Steering rack segmentation reveals how supplier margins fragment across mechanical versus electronic architectures, with material substitution and channel control determining who captures value in a transitioning supply base.
Product Type:
Margin pools concentrate in electronic assist systems where torque sensor calibration and ECU software create defendable technology moats, while hydraulic architectures face accelerating price erosion as OEMs decontent legacy platforms.
- Electronic Assist:Brushless motor-integrated racks embed torque sensors and ECUs to deliver variable boost without parasitic engine load. Demand clusters around Stuttgart and Wolfsburg engineering programs where BMW and Mercedes-Benz specify continuously variable ratio maps. EPA fuel economy mandates accelerate displacement of hydraulic pumps across light-duty platforms.
- Rack and Pinion:Direct-feedback mechanical configurations machined from alloy steel with module 1.5-3.0 precision rack teeth remain the dominant installed base. Packaging efficiency sustains preference in compact passenger vehicles where steering column space constraints limit alternative architectures.
- Hydraulic Assist:Engine-driven pump systems face stranded asset risk as OEMs terminate mid-platform lifecycle.
- Recirculating Ball:Heavy-duty truck and commercial vehicle applications retain this architecture for high-load steering forces.
Rack and pinion holds installed capacity. Electronic assist is rotating up the share rankings.
End User:
Application mix determines calibration complexity and warranty exposure, with electric vehicle platforms demanding the most sophisticated torque mapping while commercial vehicles prioritize mean-time-between-failure metrics.
- Electric Vehicles:Dedicated EV platforms eliminate engine bay packaging constraints, enabling integrated rack-and-motor units with steer-by-wire readiness. California's medium-duty truck electrification mandates and the EU's Rhine-Alpine freight corridor generate unserved demand for racks rated above 12 kN steering force.
- Passenger Vehicles:Light-duty platforms drive volume concentration, with NHTSA FMVSS 203 compliance forcing collapsible intermediate shaft designs that expand bill-of-materials cost.
- Commercial Vehicles:Fleet operators now specify total cost of ownership pricing bundling replacement intervals and predictive maintenance telematics.
- Modified Vehicles:Aftermarket performance tuning creates niche demand for quick-ratio rack conversions.
Passenger vehicles hold installed capacity. Electric vehicles is climbing the fastest.
Distribution Channel:
Channel economics diverge sharply between captive OEM supply with long-term program commitments and aftermarket distributors capturing warranty-expired replacement volume through price-aggressive positioning.
- OEMs:Direct supply to vehicle manufacturers locks in 7-10 year program lifecycles with stringent PPAP validation requirements. Nexteer Automotive Corporation leverages integrated column-and-rack systems to control supply timelines for North American OEM programs.
- Aftermarket:Independent distributors in Poland and Mexico capture warranty-expired rack replacement volume previously monopolized by dealer networks. Remanufacturing economics favor steel housing recovery over aluminum variants.
- Online Retail:E-commerce platforms aggregate DIY installer demand with compressed delivery timelines.
- Specialty Stores:Performance-focused retailers serve modified vehicle segment with quick-ratio and custom-valving options.
OEMs hold installed capacity. Aftermarket is rotating up the share rankings.
Material:
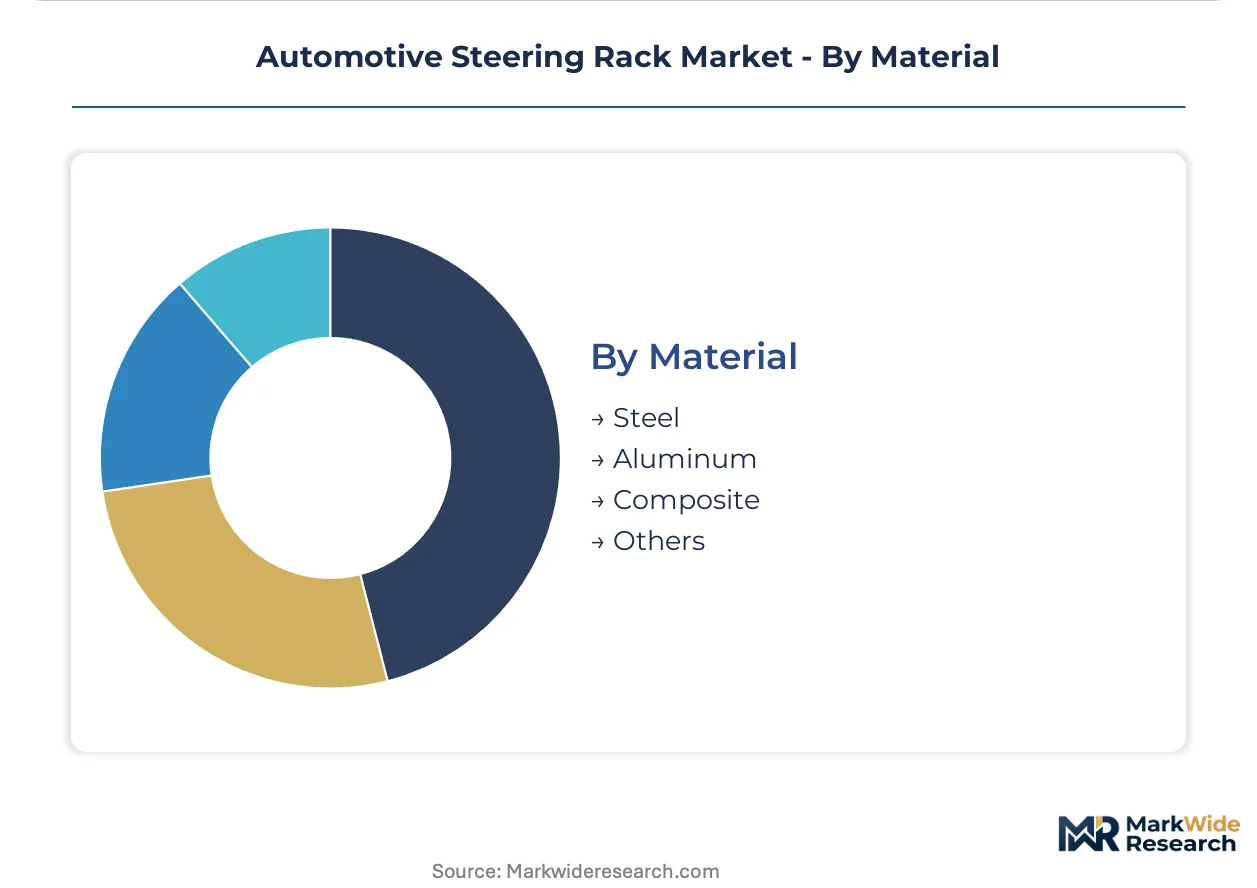
Material selection trades crash energy absorption against mass reduction credits, with aluminum grades capturing premium pricing where CAFE compliance value justifies higher forging costs.
- Aluminum:Heat-treatable 6xxx and 7xxx series alloys achieve 58-62 HRC surface hardness after nitriding, enabling 30-40% mass reduction in rack housings. NHTSA's proposed 2025 FMVSS amendments create tension between intrusion thresholds and lightweighting targets.
- Steel:Conventional alloy steel forgings dominate current installed base with proven tooth durability and lower unit economics. Remanufacturing infrastructure favors steel recovery and reconditioning cycles.
- Composite:Glass-fiber reinforced polymers emerge in non-structural rack components where vibration damping adds value.
- Others:Magnesium and titanium alloys occupy niche motorsport and ultra-premium applications.
Steel holds installed capacity. Aluminum is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in steering rack components concentrate manufacturing in automotive engineering corridors while tariff exposure reshapes supplier location decisions across major producing nations.
United States
Domestic EV production expansion and commercial vehicle electrification mandates in California drive demand for high-torque EPS systems. NHTSA Federal Motor Vehicle Safety Standard 203 amendments proposed for 2025 tighten steering column intrusion thresholds. Michigan and Ohio anchor supplier engineering centers serving Detroit Three OEM programs with accelerated PPAP validation timelines.
Germany
Stuttgart and Wolfsburg engineering corridors concentrate mechatronic rack prototyping for BMW and Mercedes-Benz platforms. KBA enforces UN ECE type approval requirements that create 18-24 month validation barriers for non-certified suppliers. Baden-Württemberg's supplier ecosystem compresses development cycles from 36 to 24 months for European premium vehicle programs.
China
Domestic EV platform proliferation and BYD's vertical integration strategy absorb record volumes of electronic assist racks. MIIT fuel consumption and new energy vehicle mandates accelerate hydraulic architecture displacement. Jiangxi and Inner Mongolia processing zones control 85% of global neodymium separation capacity for brushless EPS motor magnets.
Japan
Precision manufacturing heritage sustains leadership in torque sensor calibration and brushless motor integration for Tier-1 supply. METI carbon neutrality roadmaps push OEMs toward steer-by-wire architectures that may eliminate mechanical rack linkages. Toyota City and Hiroshima prefectures concentrate JTEKT and NSK production facilities serving Asian OEM networks.
Mexico
USMCA tariff advantages and IRA clean vehicle tax credit assembly requirements attract rack forging and motor winding investments. Aftermarket distributors in Nuevo León capture warranty-expired replacement volume for North American fleets. Bajío Region automotive clusters expand EPS module production for US-bound light-truck programs.
Automotive Steering Rack Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and R&D scale, creating a tiered structure where public companies anchor OEM supply contracts while private entities capture niche aftermarket channels. The market consolidates around integrated mechatronic system providers capable of torque sensor calibration, motor winding, and ECU software validation under single program responsibility. Three archetypes dominate: full-system integrators controlling column-to-rack architectures, component specialists supplying torque sensors or rack housings to Tier-1 assemblers, and aftermarket remanufacturers recovering steel housing value from warranty-expired units. Competitive moves concentrate on backward integration into rare-earth magnet supply chains and geographic expansion to qualify for IRA domestic content credits.
Within the full-system integrator tier, Nexteer Automotive Corporation and ZF Friedrichshafen AG exemplify the capital requirements for controlling OEM program timelines across multiple continents. JTEKT Corporation occupies a position bridging high-volume Asian supply with precision torque sensor technology. These three entities anchor the competitive structure through their representation of distinct geographic manufacturing concentrations and mechatronic integration depth.
| Leading Market Players |
|---|
| Nexteer Automotive Corporation |
| Mando Corporation |
| JTEKT Corporation |
| NSK Ltd. |
| Hyundai Mobis Co. Ltd. |
| ZF Friedrichshafen AG |
| Thyssenkrupp AG |
| Schaeffler Group |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
Long-term program offtake agreements between OEMs and Tier-1 rack suppliers lock in volume visibility and price stability across multi-year vehicle platforms, insulating producers from spot aluminum volatility while embedding cost pass-through clauses for rare-earth magnet inputs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that span 7-10 year vehicle program lifecycles. Three-tier pricing structure across premium, standard, and economy levels separates electronic assist systems with ASIL-D functional safety certification from hydraulic legacy architectures and unbranded aftermarket steel racks. Cost compression in hydraulic tiers is intensifying because OEMs are decontenting legacy platforms mid-lifecycle. Fleet procurement teams at Amazon and DHL demonstrate the lowest price sensitivity due to total cost of ownership bundling, while independent aftermarket distributors in Poland and Mexico face acute margin pressure from dealer network competition.
Supply Chain Analysis
Just-in-time delivery preferences dominate OEM assembly plant relationships, yet strategic stockpiling of neodymium permanent magnets has emerged among suppliers hedging against China's Jiangxi and Inner Mongolia export quota volatility. Manufacturing concentrates in Germany, China, and Mexico, with the latter capturing IRA clean vehicle tax credit advantages for US-bound production. Brushless EPS motors rest on rare-earth magnet supply chains, alloy steel forging capacity, and torque sensor calibration equipment. Single-source vulnerability in neodymium separation exposes the entire electronic assist tier to supply disruption. Distribution runs through captive OEM supply chains for original equipment, while independent aftermarket channels capture warranty-expired replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steer-by-wire substitution from Tesla and Hyundai-Kia platforms threatens to collapse mechanical rack demand, forcing incumbents to defend their position through software-defined vehicle integration capabilities and mechatronic system control.
For Market Incumbents: Compound backward integration into rare-earth magnet supply chains to offset China's export quota volatility, while accelerating ECU software validation capacity to capture steer-by-wire transition contracts. Nexteer Automotive Corporation's integrated column-and-rack approach exemplifies how controlling supply timelines defends OEM program access against emerging Asian competitors.
For New Entrants and Emerging Players: Lead with commercial vehicle electrification white space in California and the EU's Rhine-Alpine corridor, where medium-duty electric truck demand for racks rated above 12 kN steering force remains unserved by incumbent passenger vehicle specialists. Target remanufacturing economics in Poland and Mexico where steel housing recovery infrastructure is underdeveloped.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-system integrators bundling hardware with predictive maintenance telematics contracts for fleet operators. Long-term viability hinges on software-defined vehicle architecture readiness rather than mechanical precision manufacturing scale. Acquisition candidates should demonstrate torque sensor calibration in-house and ECU development certified to ISO 26262 ASIL-D. The signal to watch is OEM steer-by-wire platform announcements that eliminate mechanical rack linkages entirely.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Variable-ratio rack tooth profiles reduce discrete gear variants per BMW and Mercedes-Benz programs. |
| Battery Supply Agreement | Neodymium magnet offtake contracts with Chinese processors secure brushless EPS motor production. |
| Software-Defined Vehicle Investment | Steer-by-wire protocol development positions suppliers for mechanical linkage elimination. |
| Geographic Manufacturing Footprint | Mexico-based forging and motor winding operations qualify for IRA domestic content credits. |
| Charging Infrastructure Partnership | Medium-duty electric truck rack specifications align with California electrification mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations heads; and secondary validation through vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed suppliers, and NHTSA FMVSS regulatory filings. Bottom-up triangulation across rack shipment volumes by vehicle platform and top-down reconciliation against OEM production schedules ensured cross-verification of market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions including propulsion architecture, vehicle class, content per vehicle, and regional production cluster. CAGRs were derived from platform-level build forecasts and electronic assist penetration curves by OEM. Forecast inputs incorporated EPA fuel economy mandate compliance trajectories and UN ECE type approval timelines for steering system integrity.
The analysis sits within stated boundaries; outcomes outside NHTSA regulatory amendment adoption, neodymium supply stability, or steer-by-wire platform rollout schedules would require recalibration. Forecasts reflect documented assumptions about OEM platform lifecycle timing and material substitution economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Armrest Market