
 Marine Fasteners Market | 2026-2036
Marine Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fasteners Market Intelligence
A scarcity of specialized metallurgists with expertise in saltwater corrosion is reorganizing product development and material qualification cycles. Harken leverages its brand strength in the high-performance yachting segment by focusing on lightweight titanium hardware. West Marine dominates the North American recreational aftermarket through its extensive retail and online presence. Marine Fasteners specializes in a broad catalog of stainless steel and bronze components for commercial shipyards.
Marine fasteners are specialized mechanical components designed to join parts on ships, offshore structures, and other marine equipment. These components must exhibit high tensile strength and superior resistance to galvanic corrosion, often achieved through specific material grades like 316 stainless steel or silicon bronze. Within the material segments, stainless steel fasteners command the largest share, but titanium is gaining traction in high-performance applications like yachts. Shipbuilding applications represent the largest volume, while the offshore platform segment offers higher margins due to stringent certification requirements.
Product quality and material traceability are governed by standards from the International Organization for Standardization (ISO) and classification societies like DNV and the American Bureau of Shipping (ABS). The European Union's REACH regulation imposes strict chemical compliance requirements on coatings and alloys used in fasteners sold within the EU. Supplier selection will increasingly hinge on demonstrated compliance with evolving environmental standards and lifecycle material documentation.
Market Dynamics
The market's central dynamic is the performance gap between conventional fasteners and the requirements of deep-sea energy exploration. This gap drives demand for advanced, corrosion-resistant alloys, concentrating manufacturing expertise among a few suppliers with validated material science capabilities.
Growth Catalysts
- Offshore Infrastructure Expansion:The construction of deep-water oil and gas platforms and offshore wind farms, particularly in the North Sea and the Gulf of Mexico, requires high-specification fasteners capable of withstanding extreme pressures and corrosive environments.
- Shipbuilding Concentration:Naval and commercial shipbuilding programs concentrated in South Korea and expanding in India create large, predictable volume orders for certified fasteners, allowing suppliers to optimize production runs.
- Advanced Material Adoption:The specification of titanium and copper-nickel alloys in high-performance yachting and specialized naval vessels creates a high-margin segment that pulls innovation from the broader market.
Market Restraints
- Input Cost Volatility:Price fluctuations for critical alloying elements like nickel, chromium, and titanium directly impact fastener manufacturing costs, creating margin pressure that is difficult to pass on in long-term supply contracts.
- Regulatory Compliance Burden:The European Union's REACH regulation imposes stringent chemical documentation requirements on alloys and coatings, creating a significant compliance barrier for manufacturers outside the EU.
- Substitution from Non-Metals:In certain non-structural marine applications, particularly on recreational craft, advanced polymer composites and high-strength adhesives present a viable substitute, reducing weight and eliminating galvanic corrosion risk.
Strategic Opportunities
- Aftermarket in Southeast Asia:Expanding commercial shipping and fishing fleets in nations like Vietnam and Indonesia represent an underpenetrated service and replacement market for certified, traceable fasteners.
- Digital Traceability Integration:Embedding RFID chips or QR codes onto high-value fasteners offers an opportunity to provide digital, unalterable material traceability that links directly to classification society certifications from DNV or ABS.
- Aquaculture Sector Growth:The development of large-scale offshore aquaculture farms requires vast quantities of highly corrosion-resistant structural fasteners, creating a completely new end-use application for marine-grade components.
Industry Challenges
- Specialized Talent Scarcity:A limited pool of metallurgists and corrosion engineers with expertise in saltwater environments creates a bottleneck for new product development, material qualification, and failure analysis.
- Lengthy Certification Cycles:Gaining approval from classification societies like the American Bureau of Shipping for a new fastener material or design is a multi-year, capital-intensive process that can deter innovation.
- Standardization Gaps:A lack of uniform standards for fasteners used in emerging sectors like floating solar or tidal energy systems often leads to costly, project-specific engineering and procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fasteners Market |
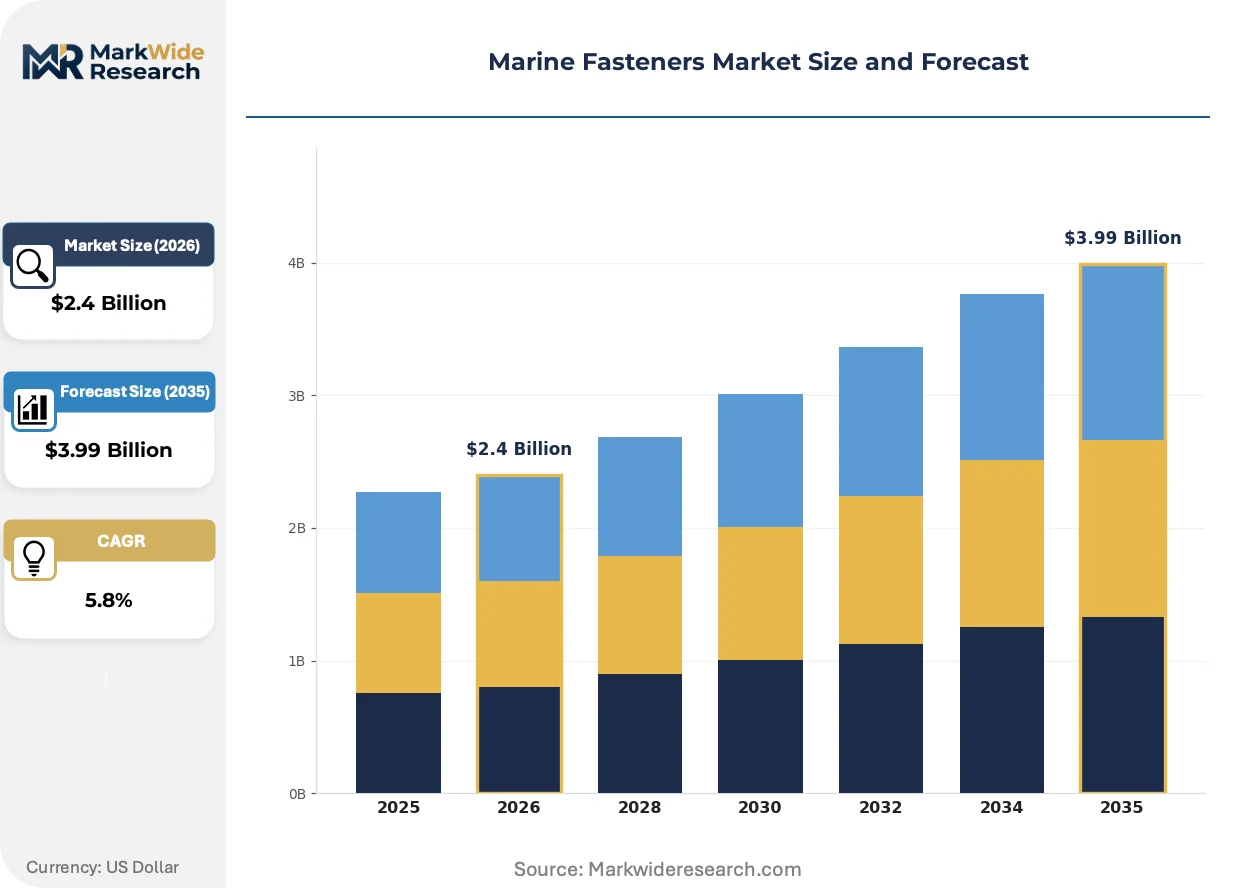
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Screws, Nuts, Washers, Rivets, Pins Material: Stainless Steel, Brass, Titanium, Bronze, Aluminum, Copper Application: Shipbuilding, Offshore Platforms, Yachts, Submarines, Ferries, Docks End User: Shipyards, Naval Forces, Shipping Companies, Marine Equipment Manufacturers, Harbor Authorities |
| Companies Covered | Marine Fasteners, Ningbo Jinding, Go2marine, Gem-Year, Changshu City Standard Parts, Harken, Shanghai Prime Machinery, Xingyi Fasteners, West Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fasteners Market Strategic Shifts & Innovations
Material science advancements and digital traceability are transforming the competitive landscape. The focus is shifting from simple tensile strength to proven, long-term performance and lifecycle data integrity, especially within high-stakes offshore and naval applications.
Advanced Alloy Proliferation
Specialized alloys like super duplex stainless steel and copper-nickel offer superior resistance to pitting and crevice corrosion compared to traditional materials. Offshore energy and naval vessel programs increasingly mandate these materials for critical submerged systems. This adoption is decomposing the market's previous structure, which was based on common stainless steel grades, into a new premium segment defined by certified metallurgical performance.
Lifecycle Documentation Mandates
Regulatory frameworks, including the EU's REACH and CSRD directives, are compelling manufacturers to provide extensive documentation on chemical composition and environmental lifecycle. This forces greater transparency throughout the supply chain, from raw metal sourcing to final coating application. Fastener suppliers targeting European shipbuilding and offshore wind projects are most affected, prompting significant investment in material data management systems.
System-Level Procurement
End-users in high-value sectors are shifting from transactional component purchasing to demanding integrated systems with performance guarantees. This change disrupts the traditional distributor model that relies on catalog sales, favoring suppliers who offer engineering support and certified material passports for entire fastener assemblies. This trend is most pronounced in the construction of LNG transport ships and complex offshore platforms.
Marine Fasteners Market Segmentation
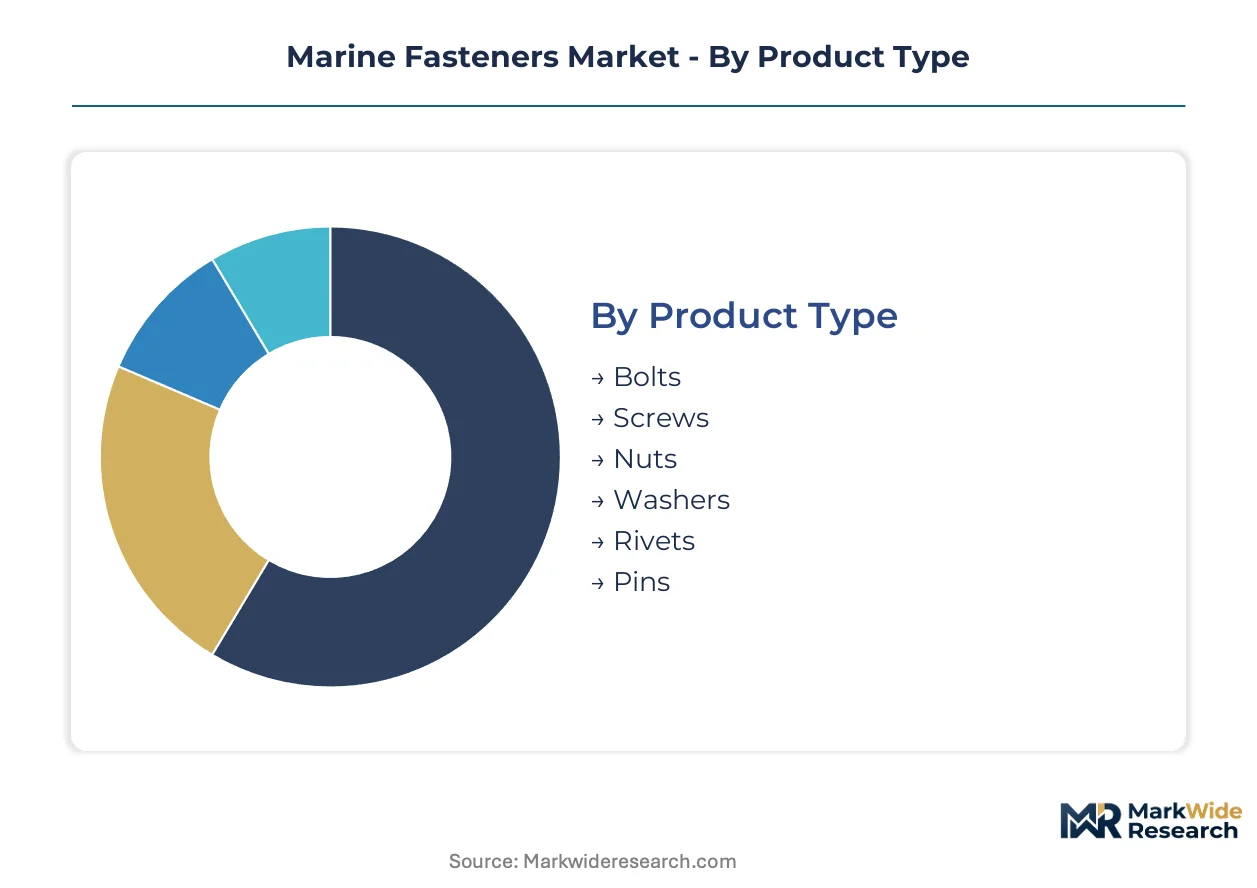
The marine fasteners market is highly differentiated, reflecting the diverse operational environments and performance requirements across various maritime applications. Understanding these segments provides clarity on demand drivers, material specifications, and regulatory pressures influencing product development and procurement.
Product Type:
Certain conventional fastener types face stronger substitution pressure from advanced joining methods, particularly in non-structural or weight-sensitive applications. However, structural integrity demands ensure traditional fasteners maintain core market share.
- Bolts:These threaded mechanical fasteners secure components requiring high tensile strength and clamping force, often used with nuts and washers. Demand concentrates in offshore platform construction and large commercial shipbuilding projects requiring robust, disassemblable connections.
- Screws:Characterized by an external helical ridge, screws are designed for direct insertion into material or pre-drilled holes, offering ease of assembly. Recreational yachting and general marine equipment manufacturing drive demand for corrosion-resistant screws due to their versatility and installation speed.
- Nuts:Internally threaded fasteners designed to mate with bolts, providing the necessary clamping force for secure joints. Commercial vessel repair and maintenance operations frequently procure a broad range of marine-grade nuts.
- Washers:Flat, thin plates typically used to distribute the load of a threaded fastener, prevent loosening, or provide insulation. Shipyards and marine fabricators utilize various washer types for structural and electrical applications.
- Rivets:Permanent mechanical fasteners consisting of a smooth cylindrical shaft with a head on one end, deformed to create a new head on the other. Specialized naval vessel construction and certain traditional shipbuilding techniques still rely on high-strength rivets.
- Pins:Cylindrical fasteners used to align, secure, or pivot components, often relying on friction or interference fit. Marine engine manufacturers and specialized equipment builders integrate pins for precision alignment and shear resistance.
Bolts anchor the volume base while Rivets gain share at the steepest rate in specialized structural applications.
Material:
Supply concentration for marine fastener materials is heavily influenced by the availability and processing capabilities for specific corrosion-resistant alloys, driving pricing and innovation. This dictates which materials are viable for high-performance applications.
- Stainless Steel:Alloys containing a minimum of 10.5% chromium, providing corrosion resistance through a passive oxide layer, with grades like 316 offering enhanced saltwater protection. Commercial shipbuilding and general marine equipment manufacturing represent the largest demand for stainless steel fasteners due to their balance of cost and performance.
- Titanium:A lightweight, high-strength metal with exceptional corrosion resistance, particularly in chloride-rich environments like seawater, making it ideal for extreme conditions. Naval vessels and high-performance yachts increasingly specify titanium fasteners for critical structural and submerged components where weight and longevity are paramount.
- Brass:An alloy primarily of copper and zinc, offering good corrosion resistance in freshwater environments and aesthetic appeal. Decorative marine hardware and non-structural fittings on recreational craft frequently use brass.
- Bronze:An alloy primarily of copper, usually with tin as the main additive, providing excellent corrosion resistance and strength, especially silicon bronze. Traditional boat building and specialized underwater equipment utilize bronze fasteners for their durability.
- Aluminum:A lightweight metal known for its high strength-to-weight ratio and resistance to certain corrosive environments, often anodized for enhanced protection. Aluminum fasteners find use in lightweight marine structures and specific recreational boat applications.
- Copper:A reddish-orange metal prized for its electrical conductivity and natural resistance to biofouling, though less common for structural fasteners. Specialized electrical connections and anti-fouling applications sometimes incorporate copper components.
The supply chain for marine fastener materials reflects a balance between established bulk production and specialized alloy manufacturing.
Application:
Application complexity significantly influences fastener specifications, with high-stakes environments demanding more rigorous material science and certification. This drives differentiation in product design and material selection.
- Shipbuilding:Encompasses the construction of various commercial and naval vessels, requiring fasteners with diverse specifications for structural integrity, deck fittings, and interior components. Commercial shipping fleets and naval programs in South Korea and India are major procurement hubs.
- Offshore Platforms:Includes fixed and floating structures for oil and gas extraction, as well as offshore wind farms, demanding fasteners capable of withstanding extreme pressures, temperatures, and corrosive deep-sea environments. Deep-water energy exploration in the North Sea and Gulf of Mexico drives demand for highly specialized fasteners.
- Yachts:High-performance recreational vessels that prioritize lightweight, aesthetic, and corrosion-resistant fasteners, often utilizing advanced materials like titanium. The luxury yacht market demands premium, custom-engineered fastening solutions.
- Submarines:Highly specialized underwater vessels requiring fasteners with extreme pressure resistance, stealth characteristics, and superior corrosion protection in enclosed, critical environments. Military and research submarine programs have stringent material and certification requirements.
- Ferries:Passenger and vehicle transport vessels operating in coastal and inland waters, requiring durable and reliable fasteners for structural elements, passenger areas, and propulsion systems. Public transport infrastructure projects drive demand for ferry construction.
- Docks:Fixed or floating structures providing mooring and access for vessels, requiring robust fasteners resistant to constant exposure to water, weather, and heavy loads. Port infrastructure development and waterfront expansion projects require substantial fastener volumes.
Application diversity spans high-volume construction to highly specialized, mission-critical installations.
End User:
Procurement patterns vary significantly across end-user segments, from direct bulk purchases to intricate supply chains for specialized components. This influences supplier relationships and distribution strategies.
- Shipyards:Companies engaged in building and repairing ships, procuring large volumes of fasteners directly from manufacturers or specialized distributors for various vessel types. New shipbuilding orders and vessel maintenance cycles directly impact shipyard fastener demand.
- Naval Forces:Military organizations operating navies, requiring fasteners that meet stringent military specifications (MIL-spec) for performance, durability, and traceability in defense applications. Global defense spending and fleet modernization initiatives influence naval fastener procurement.
- Shipping Companies:Operators of commercial cargo and passenger vessels, primarily procuring fasteners for maintenance, repair, and overhaul (MRO) activities. Routine vessel upkeep and unexpected repairs drive a consistent demand for replacement fasteners.
- Marine Equipment Manufacturers:Companies producing engines, propulsion systems, navigation equipment, and other components for marine vessels, integrating fasteners into their assemblies. Innovation in marine technology translates into demand for specialized fasteners from these manufacturers.
- Harbor Authorities:Entities responsible for managing ports and harbors, procuring fasteners for the construction and maintenance of docks, piers, and other port infrastructure. Port expansion projects and routine infrastructure upkeep generate demand for robust marine fasteners.
End-user segments range from large-scale builders to specialized maintenance and repair operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's REACH regulation significantly influences material specifications for marine fasteners, particularly for products sold within its member states. This regulatory framework drives demand for compliant alloys and coatings, impacting global supply chains. Beyond Europe, diverse regional demands shape procurement patterns and material adoption.
South Korea
South Korea's robust naval and commercial shipbuilding programs consistently generate large volumes of fastener orders. National shipbuilding policies often mandate stringent material traceability and performance certifications for these critical components. Major shipyards in Ulsan and Geoje concentrate procurement, driving efficiency in certified fastener supply.
United States
Demand for marine fasteners in the United States stems from offshore platform construction in the Gulf of Mexico and a robust recreational aftermarket. The American Bureau of Shipping (ABS) governs certification requirements for structural fasteners in offshore and commercial vessels. Houston serves as a hub for offshore energy suppliers, while Florida's extensive coastline supports a significant recreational marine equipment sector.
Germany
Germany's market requires high-specification fasteners for North Sea offshore wind farm construction and advanced naval vessel projects. The EU's REACH regulation imposes strict chemical compliance for all fasteners used or sold within the country. Shipyards in Hamburg and Rostock focus on integrating certified, corrosion-resistant components into their specialized maritime builds.
India
India's expanding commercial and naval shipbuilding initiatives create substantial demand for certified marine fasteners. The Bureau of Indian Standards (BIS) establishes quality benchmarks, while 'Make in India' policies encourage domestic sourcing for defense projects. Major shipyards in Visakhapatnam and Mumbai are increasing procurement volumes for a broad range of structural and specialized fasteners.
Norway
Norway's market for marine fasteners is driven by deep-water oil and gas exploration and the growth of offshore aquaculture farms. DNV certification is paramount for fasteners used in critical offshore infrastructure operating in the harsh North Sea environment. Stavanger and Bergen represent key centers for suppliers supporting advanced offshore energy and marine technology projects.
Marine Fasteners Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the marine fasteners market. The market exhibits a tiered structure, ranging from high-volume generalists to niche providers focused on advanced materials and specific applications. Key strategic archetypes include large-scale commercial suppliers, high-performance material innovators, and aftermarket distributors. Competitive moves focus on material science advancements and expanding digital traceability solutions to meet evolving regulatory and end-user demands.
Specialists in high-performance applications include Harken, which represents innovation in lightweight titanium hardware for yachting. Marine Fasteners exemplifies the large-scale commercial supplier archetype, offering a broad catalog of stainless steel and bronze components for commercial shipyards. West Marine occupies a dominant position within the North American recreational aftermarket, leveraging its extensive retail and online presence for widespread distribution.
| Leading Market Players |
|---|
| Marine Fasteners |
| Ningbo Jinding |
| Go2marine |
| Gem-Year |
| Changshu City Standard Parts |
| Harken |
| Shanghai Prime Machinery |
| Xingyi Fasteners |
| West Marine |
| Others |
Cost & Logistics Intelligence
Long-term supply contracts for high-specification fasteners lock in both supply access and price visibility for critical marine infrastructure projects. These agreements mitigate the impact of raw material fluctuations for both manufacturers and large-scale buyers.
Pricing Analysis
Geographic price spreads reflect regional regulatory burdens and local labor costs. Contract-based long-term offtake agreements dominate procurement for large commercial shipyards and offshore platform developers. Price differentiation stems from certification levels from DNV or ABS and the specific material grade, such as titanium versus 316 stainless steel. Pricing pressure arises from input cost volatility for critical alloying elements like nickel and titanium. Recreational aftermarket buyers demonstrate higher price sensitivity compared to high-stakes offshore energy projects.
Supply Chain Analysis
Strategic stockpiling of specialized alloys ensures component availability for projects with lengthy lead times. The supply chain for marine fasteners draws from raw material concentrations in countries like China for stainless steel and Australia for titanium. Key dependencies include nickel, chromium, and copper for various corrosion-resistant alloys. Regulatory restrictions, particularly the European Union's REACH regulation, represent a significant structural risk for manufacturers. Distribution runs through direct manufacturer-to-shipyard sales for large volumes and specialized distributors for MRO and aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine fasteners market presents a high-growth disruption, driven by the increasing demand for advanced corrosion-resistant materials in deep-sea energy exploration.
For Market Incumbents:
Compound existing brand strength by investing further in advanced material science R&D, particularly for super duplex stainless steel and copper-nickel alloys. Develop comprehensive lifecycle documentation solutions to meet evolving regulatory mandates like the European Union's CSRD, mitigating the threat of non-compliant competitors. Vertical integration into specialized alloy processing or advanced coating technologies can secure material supply and enhance performance guarantees.
For New Entrants and Emerging Players:
Anchor in niche, high-margin segments like the aquaculture sector or the aftermarket in Southeast Asia, which are less saturated. The recreational craft segment offers white-space opportunities for polymer composite fasteners in non-structural applications. Offer integrated engineering support and certified material passports for entire fastener assemblies to differentiate from catalog distributors.
For Investors and Strategic Acquirers:
Specialized alloy manufacturers with validated material science capabilities represent attractive long-term acquisition targets due to the market's shift towards high-performance applications. Digital traceability solution providers offering RFID or QR code integration for high-value fasteners also present strong potential. The increasing adoption of advanced materials in offshore wind farm construction serves as a key signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Alloy R&D | Develops proprietary materials for extreme deep-sea environments, enhancing product performance and market differentiation for offshore platforms. |
| Expand Digital Traceability Solutions | Ensures compliance with stringent classification society certifications from DNV and ABS, building trust and transparency in critical applications. |
| Target Offshore Aquaculture Sector | Captures early market share in a nascent but high-growth end-use application requiring specialized corrosion-resistant components. |
| Acquire Specialized Coating Technology | Enhances fastener longevity and performance in harsh marine environments, improving resistance to galvanic and crevice corrosion. |
| Establish Southeast Asia Aftermarket Hub | Penetrates an under-served region with expanding commercial shipping fleets, securing a consistent revenue stream for MRO fasteners. |
Research Approach
Operator-level perspectives from shipyard procurement managers, offshore platform engineers, marine equipment R&D leads, and classification society representatives anchored the qualitative base. This primary research was triangulated with extensive secondary validation from DNV/ABS certification databases, ISO standards, EU REACH documentation, and relevant trade association reports. Both bottom-up and top-down approaches were employed to ensure robust data integrity.
Sensitivity analysis framed the forecast framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, material, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, projected demand drivers, and anticipated technological advancements. Key industry-specific forecast inputs included global shipbuilding order books and offshore energy investment forecasts.
Underlying assumptions cover material availability, regulatory stability, and consistent investment in marine infrastructure, with deviation risk concentrated in raw material price volatility and geopolitical shifts impacting shipbuilding. Revision becomes warranted when key economic or regulatory conditions cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Global Discount-Marine Trenchers Market
Marine
Marine Base Steering Gear Market
Marine
Submarine Propulsion Systems Market
Marine
Europe Recreational Boating Market
Marine
Shipbuilding Market
Marine
Europe Marine Communication Systems Market
Marine
Autonomous Ships Market
Marine
Marine Electronics Market
Marine
Marine Growth Removal Tool Market
Marine
Integrated Bridge System for Ships Market
Marine
Electric Outboard Engines Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Hydraulic Marine Cranes Market
Marine
Global Maritime Information Market
Marine
Marine Big Data Market
Marine
Marine Pipes Market