
 Automotive Die-Stamping Equipment Market | 2026-2036
Automotive Die-Stamping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Die-Stamping Equipment Market Analysis
Equipment leasing and project finance is reshaping competitive dynamics in automotive die-stamping, lowering capital barriers for mid-tier vehicle assemblers. Schuler Group GmbH leverages its European manufacturing base to sustain hydraulic press dominance. AMADA HOLDINGS CO.,LTD. anchors Asia-Pacific demand through servo press specialization. AIDA Engineering Ltd. differentiates via precision press technology leadership.
Automotive die-stamping equipment comprises mechanical, hydraulic, servo, and precision presses engineered to apply controlled force ranging from hundreds to thousands of tons against hardened dies, transforming sheet metal into complex geometries for vehicle structures. These systems operate at stroke rates from 10 to over 1,000 per minute depending on press type and part complexity, serving the primary purpose of producing high-volume, dimensionally consistent metal components for vehicle assembly. Servo press technology captures expanding margin pools as OEMs demand programmable slide motion for advanced high-strength steel forming. Tier-1 suppliers represent the fastest-growing end-user channel as outsourcing of stamped component production accelerates. Body components applications dominate current installed base value while chassis parts manufacturing drives replacement demand.
EPA emissions standards and the EU Green Deal F-Gas Regulation are tightening energy efficiency requirements for industrial press operations, directly influencing servo motor adoption rates and hydraulic fluid specifications. NHTSA vehicle safety standards and ISO 9001 quality frameworks mandate dimensional tolerances that stampers must achieve through precision press investments. Stakeholders must monitor how carbon border adjustments and evolving crashworthiness protocols alter material specifications and press capability requirements.
Market Dynamics
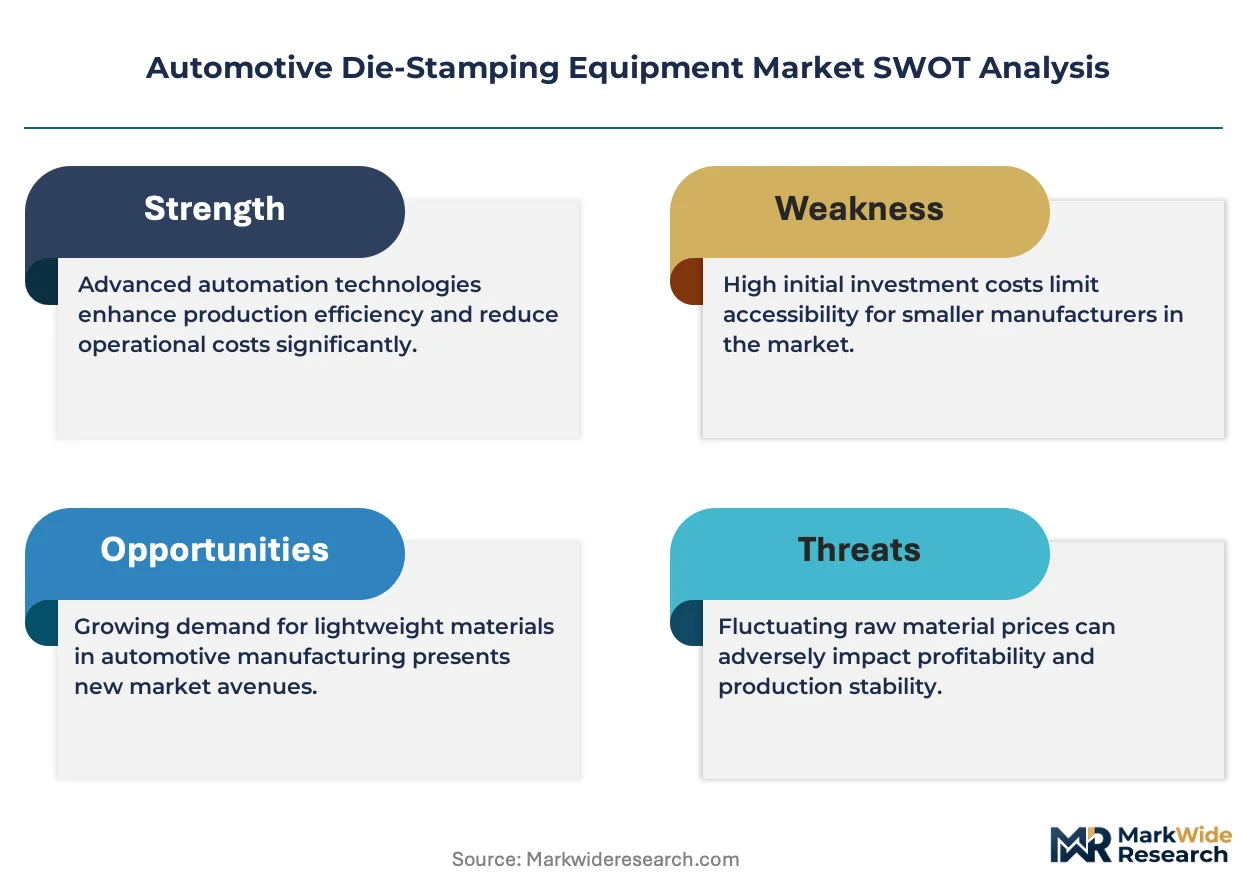
Servo press technology is hybridizing mechanical and hydraulic architectures, forcing incumbent suppliers to retool R&D roadmaps while OEMs rewrite equipment specifications for advanced high-strength steel forming cycles.
Growth Catalysts
- EU Green Deal F-Gas Regulation:The regulation mandates fluorinated gas phase-downs in industrial equipment, compelling stampers to replace hydraulic systems with servo-electric presses that eliminate hydraulic fluid leakage risks and energy waste.
- Electric vehicle body-in-white expansion:Battery electric vehicle OEMs in Germany and China are commissioning dedicated stamping lines for aluminum-intensive closures and structural components, creating dedicated capacity demand distinct from legacy internal combustion platforms.
- Advanced high-strength steel (AHSS) forming:Third-generation AHSS grades now constitute critical mass in A- and B-pillar designs, requiring programmable slide motion and real-time tonnage control that only servo architectures deliver at production scale.
Market Restraints
- Capital intensity concentration:Precision servo press lines require three to five times the upfront investment of conventional mechanical alternatives, restricting independent Tier-2 stampers from capability upgrades without project finance or OEM co-investment.
- Control system supplier concentration:Motion control hardware and servo drive software for multi-axis press coordination concentrates among a narrow base of European and Japanese automation specialists, creating single-source vulnerability for line integrators.
- Skilled technician scarcity:Servo press commissioning, die tryout, and predictive maintenance demand electromechanical expertise that mechanical press technician pools lack, elongating deployment timelines and inflating service contract premiums.
Strategic Opportunities
- India automotive manufacturing expansion:Domestic OEMs and Korean transplant operations in Chennai and Pune are greenfielding stamping capacity without legacy hydraulic infrastructure, enabling direct servo adoption without replacement cycle friction.
- Chassis component outsourcing acceleration:Subframe and suspension arm stampers represent an underpenetrated application segment where Tier-1 suppliers can displace in-house OEM operations through dedicated precision press cells and die engineering services.
- Equipment-as-a-service commercial models:Leasing structures with per-stroke or per-part pricing are emerging in Germany and the United States, lowering capital barriers for mid-volume vehicle assemblers and expanding addressable customer pools beyond top-tier OEMs.
Industry Challenges
- Die engineering talent compression:Tool and die design expertise for complex draw forming and springback compensation is retiring faster than apprenticeship pipelines replenish, particularly for hot-forming die concepts required by next-generation AHSS grades.
- Legacy press integration complexity:Brownfield installations must synchronize new servo lines with existing mechanical press sequencing, material handling automation, and quality inspection stations without disrupting running production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Die-Stamping Equipment Market |
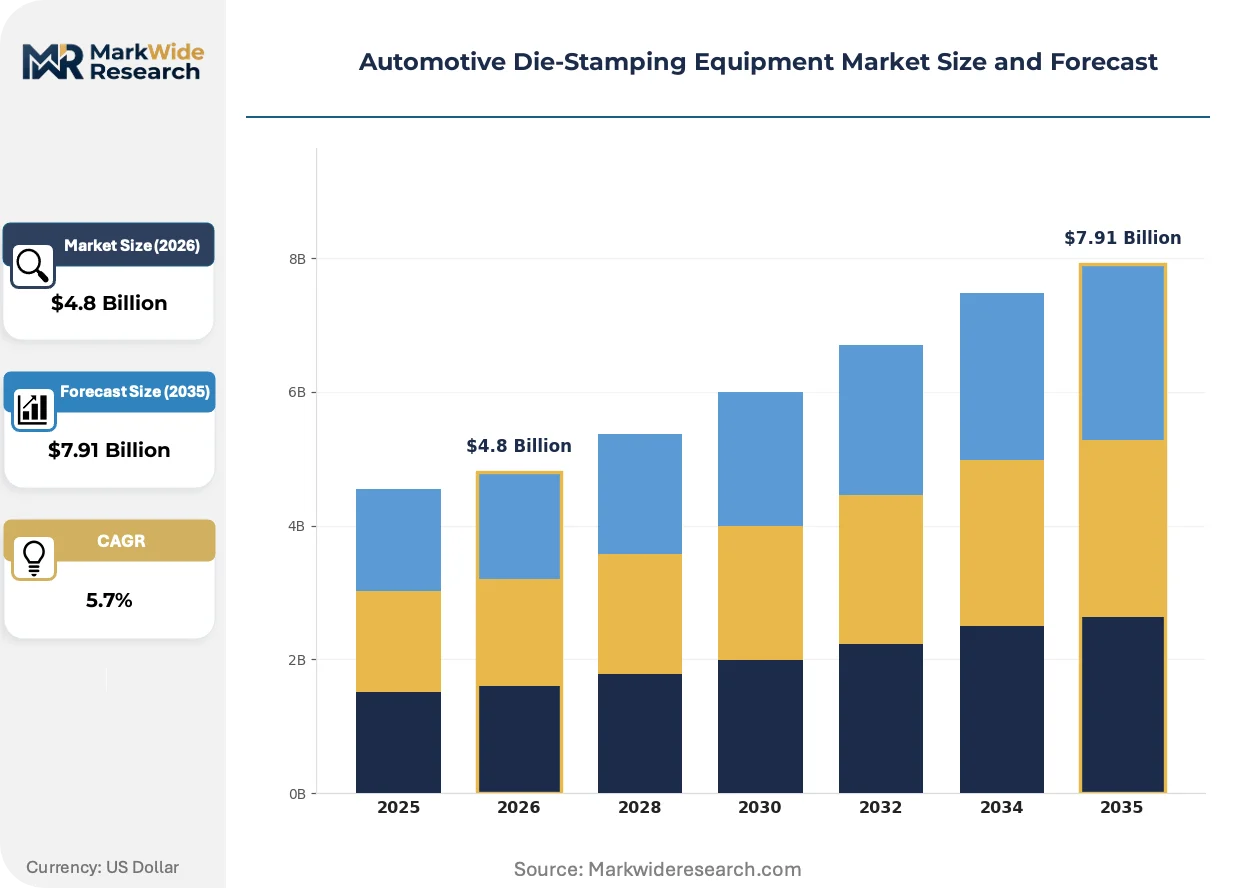
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Press, Mechanical Press, Servo Press, Precision Press End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Stamping, Deep Drawing, Blanking, Forming Application: Body Components, Chassis Parts, Engine Components, Electrical Components |
| Companies Covered | AIDA Engineering Ltd., AMADA HOLDINGS CO.,LTD., Schuler Group GmbH, Komatsu Ltd., Macrodyne Technologies Inc, Andritz AG, BRUDERER AG, SHIEH YIH Machinery Industry Co., Ltd., SIMPAC America Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Die-Stamping Equipment Market Emerging Trajectories
Programmable motion control and carbon-accounting transparency are converging to redefine equipment procurement criteria, with buyers now evaluating total forming energy per part alongside traditional stroke-rate metrics.
Servo press technology is hybridizing the speed advantages of mechanical flywheel drives with the force modulation of hydraulic systems through independently controlled servo motors on each slide corner. Tier-1 chassis suppliers in Germany and Japan are adopting these architectures for third-generation advanced high-strength steel forming. The technology is compressing die tryout cycles from weeks to days while enabling part consolidation that eliminates downstream welding operations.
The EU Green Deal F-Gas Regulation and EPA emissions standards are tightening energy efficiency mandates for industrial press operations, directly influencing hydraulic fluid specifications and motor efficiency class requirements. Stamping lines in Germany and the United States now face carbon border adjustment exposure on exported vehicle components, forcing energy consumption documentation at the equipment specification stage. Servo press vendors are responding with ISO 50001-aligned energy monitoring packages as standard offerings rather than options.
Automotive OEM procurement organizations are unbundling after-sales service contracts from initial equipment purchases, creating standalone multi-year service agreements with performance-based uptime guarantees. Tier-1 suppliers in China and the United States are driving this shift, pressuring equipment vendors to maintain regional spare parts inventories and dedicated response teams. The model is most visible in Germany, where stampers now contract directly with automation integrators for line-wide maintenance rather than siloed press-only service.
Automotive Die-Stamping Equipment Market Segmentation
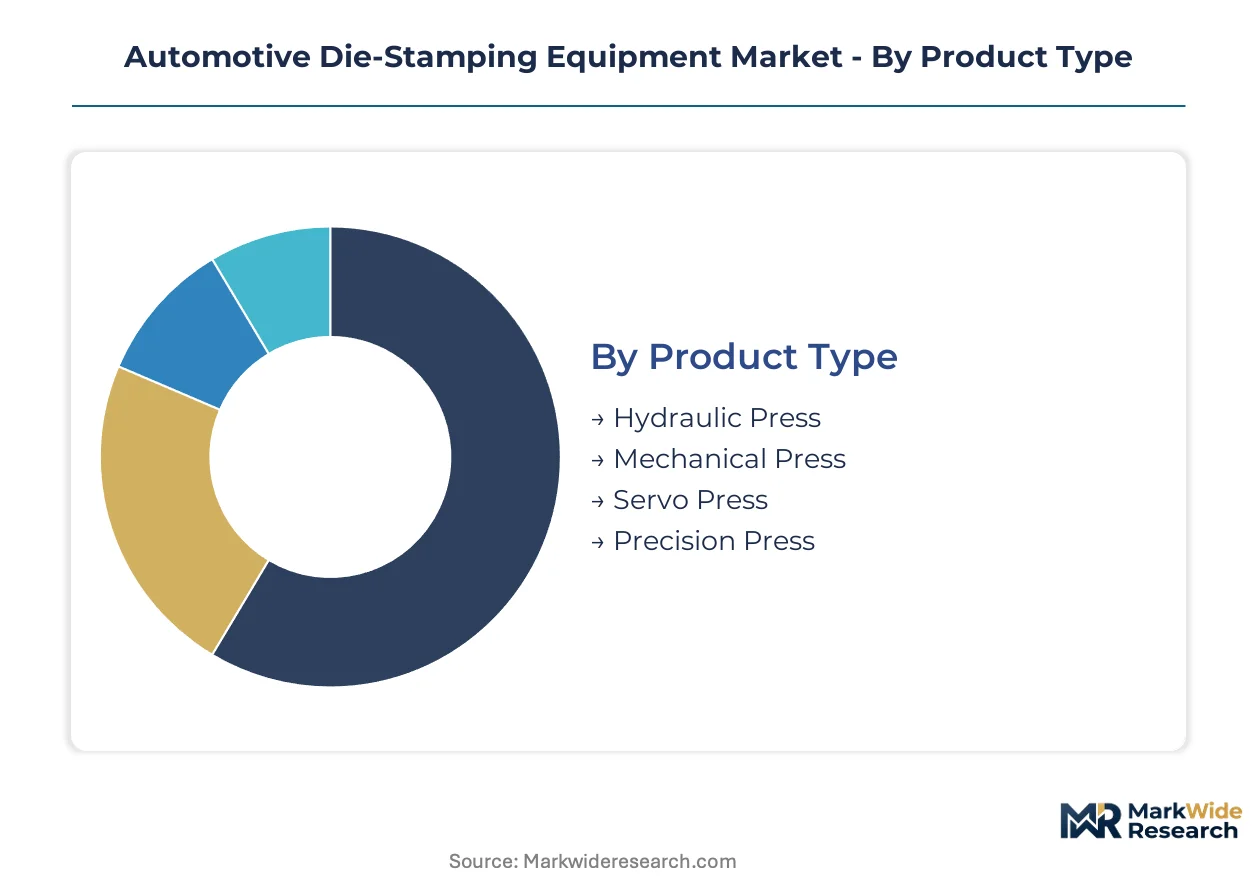
Segmentation reveals how equipment specifications diverge across customer sophistication tiers and forming complexity requirements. Procurement patterns in this market stratify sharply between high-volume OEMs seeking programmable servo architectures and cost-constrained assemblers prioritizing mechanical press reliability.
Product Type:
Cost tier determines technology access, with capital intensity creating distinct buyer strata from premium servo adopters to economy mechanical purchasers.
- Servo Press:Independently controlled servo motors on each slide corner enable programmable motion profiles for advanced high-strength steel forming. German and Chinese electric vehicle OEMs commission these systems for aluminum-intensive body-in-white lines where slide velocity modulation prevents springback in complex draw geometries.
- Hydraulic Press:Fluid-powered force generation delivers sustained tonnage across extended stroke lengths for deep-draw chassis components. The EU Green Deal F-Gas Regulation accelerates displacement of these systems as stampers face fluorinated gas phase-down mandates and hydraulic leakage liability.
- Mechanical Press:Flywheel-driven crank mechanisms achieve stroke rates exceeding 1,000 per minute for high-volume body panel blanking. Tier-2 stampers in India and Southeast Asia favor these systems for their lower commissioning complexity and established technician training pipelines.
- Precision Press:Rigid frame construction and closed-loop tonnage monitoring maintain dimensional tolerances within microns for electrical connector stamping. Japanese automotive electronics suppliers anchor demand for these systems in multi-slide progressive die applications.
Mechanical press lines command the established base across emerging manufacturing economies. The steepest expansion runs through servo press architectures as programmable forming becomes non-negotiable for next-generation vehicle platforms.
End User:
Customer type shapes procurement scale, service expectations, and financing structure from captive OEM operations to independent contract manufacturers.
- Tier-1 Suppliers:Independent stampers such as Gestamp and Tower International operate dedicated press cells across multiple OEM contracts, requiring flexible die changeover capabilities and part-to-part traceability systems. These firms represent the fastest-expanding equipment demand channel as outsourcing of stamped component production accelerates.
- OEMs:Captive stamping operations at Volkswagen, Toyota, and BYD maintain in-house capacity for proprietary body architectures and strategic volume security. These buyers specify line-wide automation integration and multi-decade spare parts commitments.
- Vehicle Assemblers:Low-volume manufacturers and specialty EV startups lease press capacity or deploy compact servo lines for niche production runs. Equipment-as-a-service models are emerging specifically for this segment in Germany and the United States.
- Aftermarket Providers:Independent stampers serving collision repair and restoration markets operate refurbished mechanical presses for limited-run reproduction panels. Price sensitivity dominates procurement criteria for this fragmented segment.
OEMs command the established installed value through decades of captive capacity accumulation. The steepest expansion trajectory belongs to Tier-1 suppliers as vehicle assemblers divest in-house stamping operations.
Technology:
Forming complexity separates commodity blanking operations from value-added precision processes requiring dedicated press configurations.
- Stamping:General-purpose force application transforms flat sheet into three-dimensional geometries through single-station or progressive die sequences. This foundational process dominates body panel production across all vehicle segments and manufacturing scales.
- Deep Drawing:Controlled material flow into die cavities creates enclosed sections such as fuel tanks, transmission pans, and structural rails. Third-generation advanced high-strength steel grades now challenge conventional deep draw limits, forcing press specification upgrades.
- Blanking:Shear-based separation produces flat blanks from coil stock for subsequent forming operations or finished shims and gaskets. High-speed mechanical presses with precision feed systems optimize this high-volume, lower-margin application.
- Forming:Bending, flanging, and coining operations refine part geometry without material separation. Multi-axis servo presses enable complex in-die forming sequences that consolidate legacy secondary operations.
Blanking retains the broadest installed base across mechanical press fleets. The steepest capability investment flows into deep drawing as chassis component complexity escalates.
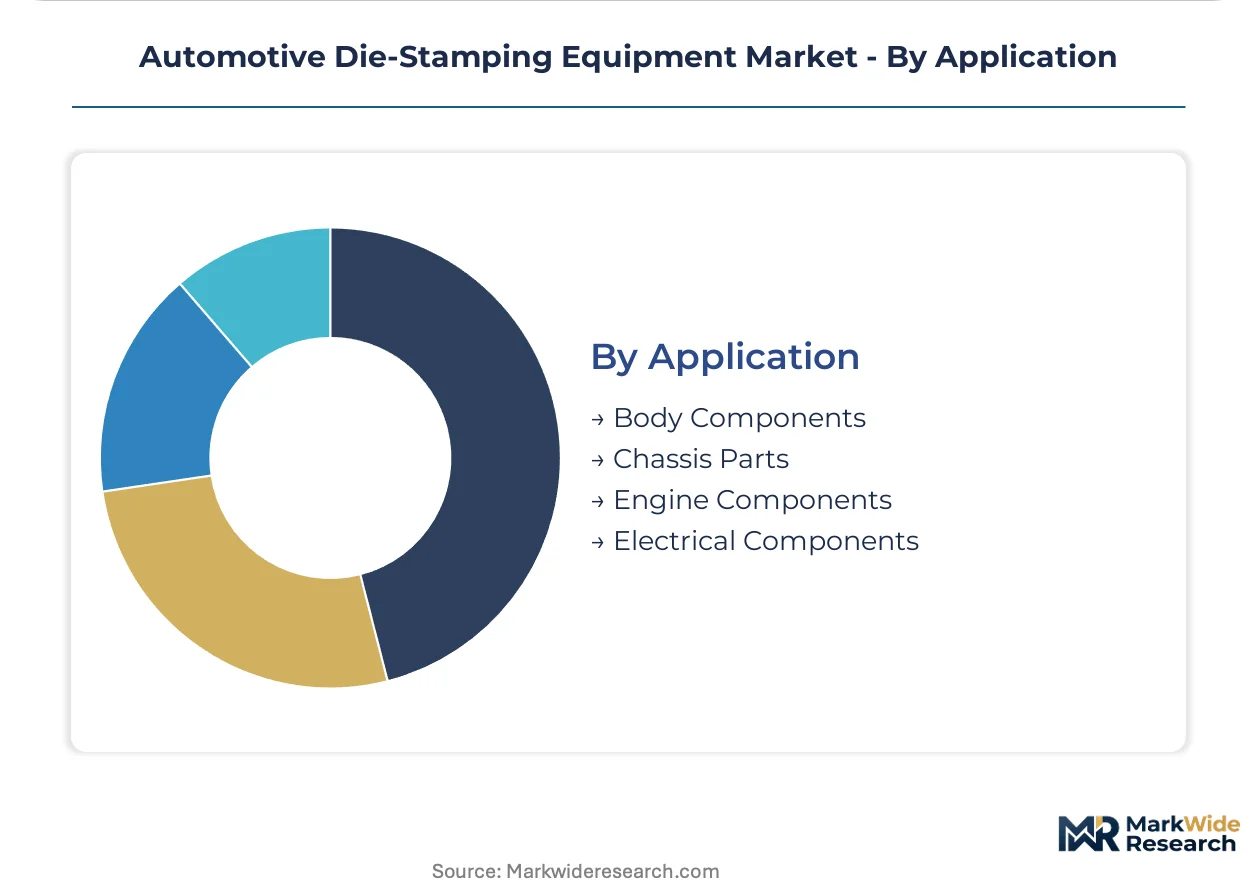
Application:
Part function determines material specification, tolerance requirements, and forming energy intensity from cosmetic closures to structural crash members.
- Body Components:Hoods, doors, fenders, and roof panels demand cosmetic surface quality and dimensional repeatability across million-unit annual volumes. Aluminum closure stamping for electric vehicles drives servo press adoption in Germany and China.
- Chassis Parts:Subframes, control arms, and suspension links require high-strength steel forming with fatigue-resistant edge conditions. Tier-1 suppliers are expanding dedicated capacity here as OEMs outsource structural component manufacturing.
- Engine Components:Oil pans, valve covers, and transmission housings combine deep draw geometries with sealing surface precision. Declining internal combustion powertrain investment compresses growth in this historically significant segment.
- Electrical Components:Motor laminations, battery enclosure terminals, and busbar connectors require micron-level stamping precision for conductive performance. Electric vehicle powertrain electrification redirects demand from engine parts toward e-motor and battery hardware.
Body components command the established value concentration across installed press capacity. The steepest demand expansion runs through chassis parts as platform electrification reshapes structural requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government electrification mandates and industrial decarbonization programs are redirecting stamping equipment procurement toward servo-electric architectures across major manufacturing economies. National regulators are tightening energy efficiency standards for heavy industrial machinery. OEMs are consolidating stamping capacity in jurisdictions offering clean energy infrastructure and skilled tool-and-die workforces.
Germany
Volkswagen Group and BMW are commissioning dedicated aluminum stamping lines for electric vehicle body-in-white production. The EU Green Deal F-Gas Regulation accelerates hydraulic press phase-outs in Baden-Württemberg and Bavaria. Stuttgart and Munich industrial clusters concentrate servo press adoption for third-generation advanced high-strength steel forming.
China
BYD and NIO are expanding captive stamping capacity for battery electric vehicle platforms. MIIT energy efficiency standards for industrial equipment mandate servo motor adoption in new press installations. Yangtze River Delta manufacturing corridors in Shanghai and Jiangsu province concentrate domestic equipment procurement for aluminum closure stamping.
United States
Ford and General Motors are retooling Detroit-area stamping plants for electric truck body architectures. EPA emissions standards for industrial operations tighten hydraulic fluid specifications and motor efficiency requirements. Southeast manufacturing corridors in Tennessee and Kentucky attract Tier-1 supplier investments for EV structural component outsourcing.
Japan
Toyota and Honda are integrating servo press lines for hybrid and battery electric vehicle body component production. METI carbon neutrality roadmaps for manufacturing equipment accelerate displacement of conventional mechanical presses. Nagoya and Osaka industrial clusters concentrate precision press demand for automotive electronics and motor lamination stamping.
India
Hyundai and Tata Motors are greenfielding stamping capacity in Chennai and Pune for domestic electric vehicle production. The PLI scheme for automotive manufacturing subsidizes advanced equipment adoption without legacy hydraulic infrastructure constraints. Gujarat and Maharashtra industrial corridors enable direct servo press deployment for aluminum-intensive vehicle architectures.
Automotive Die-Stamping Equipment Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers differentiated by technology specialization and geographic manufacturing footprint. European and Japanese equipment fabricators dominate premium servo press architectures through proprietary motion control integration. Mid-tier mechanical press suppliers compete on commissioning speed and established service networks in emerging manufacturing economies. Competitive dynamics center on strategic partnerships with automation integrators and portfolio diversification into equipment-as-a-service commercial models.
Within the precision technology tier, AIDA Engineering Ltd. and AMADA HOLDINGS CO.,LTD. occupy positions reflecting Japanese electromechanical specialization, while Schuler Group GmbH anchors European hydraulic-to-servo transition capabilities. These three exemplify divergent strategic archetypes: servo-native engineering heritage, metalworking equipment diversification, and automotive OEM captive supply relationships. Their collective positioning illustrates how technology lineage shapes competitive access to electric vehicle platform procurement cycles.
| Leading Market Players |
|---|
| AIDA Engineering Ltd. |
| AMADA HOLDINGS CO.,LTD. |
| Schuler Group GmbH |
| Komatsu Ltd. |
| Macrodyne Technologies Inc |
| Andritz AG |
| BRUDERER AG |
| SHIEH YIH Machinery Industry Co., Ltd. |
| SIMPAC America Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European servo press manufacturing is tightening supplier pricing power while compressing lead times for Tier-1 stampers seeking EU Green Deal-compliant equipment upgrades. This utilization squeeze propagates through contract structures, forcing buyers to accept longer-term offtake commitments or risk slot allocation to competitors.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with ISO 50001-aligned energy monitoring packages and CE-marked safety architectures commanding substantial premiums over baseline mechanical alternatives. Three-tier pricing structure across premium servo-electric, standard hydraulic, and economy mechanical levels reflects divergent capability requirements rather than brand positioning alone. Cost compression in mid-tier hydraulic systems is intensifying because fluorinated gas phase-down mandates accelerate replacement demand without corresponding supply expansion. Vehicle assemblers and specialty EV startups exhibit the highest price sensitivity, captive OEM operations the lowest.
Supply Chain Analysis
High-grade cast iron feedstock and rare-earth servo motor magnets draw from concentrated extraction and processing corridors in China, Germany, and Japan. Motion control hardware and servo drive software hinge on European and Japanese automation specialists, creating single-source vulnerability for line integrators assembling multi-axis press systems. Tariff exposure on precision-machined components and carbon border adjustment liability on exported vehicle parts represent structural supply chain risks. Distribution runs through direct OEM procurement teams and Tier-1 supplier engineering departments rather than traditional industrial equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat sustained by regulatory entrenchment: EU Green Deal F-Gas mandates and EPA emissions standards create switching costs that lock stampers into approved supplier relationships and certified equipment architectures.
For Market Incumbents: Insulate installed base relationships through captive spare parts inventory commitments and multi-decade service agreements with performance-based uptime guarantees. Backward integration into motion control software development defends against automation specialist concentration risk. Capacity addition in Chennai and Pune industrial corridors captures India greenfield demand without legacy hydraulic replacement friction.
For New Entrants and Emerging Players: Mid-volume vehicle assemblers in Germany and the United States represent the most penetrable entry point, as equipment-as-a-service commercial models lower capital barriers and expand addressable customer pools beyond top-tier OEMs. Chassis component outsourcing acceleration offers a second white-space target, with subframe and suspension arm stampers seeking dedicated precision press cells. A go-to-market angle anchored to per-stroke or per-part pricing structures differentiates from incumbent capital-sale dominance.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment-as-a-service sub-segments as leasing structures proliferate. Acquisition targets should exhibit servo-native engineering heritage with established automation integrator partnerships and regional spare parts distribution. The signal to watch is OEM procurement unbundling of after-sales service contracts from initial equipment purchases, which accelerates standalone multi-year service agreement proliferation.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo Press Technology Licensing | Enables Tier-2 stampers to access programmable slide motion without full capital commitment. |
| Backward Integration into Motion Control | Reduces single-source vulnerability from European and Japanese automation specialists. |
| Equipment-as-a-Service Launch | Captures mid-volume vehicle assemblers excluded from traditional capital-sale markets. |
| Regional Spare Parts Hub Expansion | Supports unbundled after-sales service contracts with performance-based uptime guarantees. |
| Die Engineering Services Acquisition | Addresses tool and die design talent compression for hot-forming AHSS grades. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing OEM platform engineers, Tier-1 supplier procurement leads, aftermarket service heads, and plant maintenance directors at stamping operations. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of publicly traded equipment fabricators, and customs records of press machinery trade flows. Bottom-up equipment shipment tallies and top-down automotive production forecasts were triangulated to anchor market sizing.
Calibration against historical capacity utilization rates and replacement cycle patterns shaped analytical framework development across the projection horizon. Segmentation dimensions modeled include press type, end-user category, forming technology, and application function, with regional regulatory cluster effects explicitly incorporated. CAGRs were derived from equipment shipment trajectories mapped to vehicle platform electrification timelines and AHSS grade adoption curves.
Practitioners should monitor EU Green Deal implementation pace and EPA emissions standard enforcement intensity for early signals of regulatory-driven replacement demand acceleration. Forecasts reflect assumptions regarding servo motor cost curves and apprenticeship pipeline replenishment rates for electromechanical technician expertise. Material shifts in carbon border adjustment scope or third-generation AHSS forming feasibility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market