
 Global Aerodynamic Automotive Market | 2026-2036
Global Aerodynamic Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerodynamic Automotive Market Intelligence
The transition from single-source component supply to a multi-source strategy for aerodynamic parts is restructuring OEM procurement. Magna International Inc. leverages its broad portfolio to serve diverse OEM needs. Tesla differentiates through its integrated approach to design and software-controlled active systems. Valeo SA specializes in embedding advanced sensor technology within aerodynamic modules.
Aerodynamic automotive design involves shaping vehicle bodies and adding components to minimize the coefficient of drag (Cd). The primary purpose is to reduce air resistance, thereby improving fuel efficiency and extending electric vehicle range. Active aerodynamics, including deployable spoilers and grille shutters, are gaining share over passive systems. Within applications, while fuel efficiency remains the dominant driver, noise reduction is an increasingly important factor for luxury and electric vehicle segments.
Regulations are a primary market accelerant, with the US EPA's fuel economy standards and the EU's CO2 emission performance standards directly mandating efficiency gains. China's dual carbon goals further pressure automakers to adopt advanced aerodynamic solutions. OEMs now face a critical decision between investing in complex active systems versus optimizing passive designs to meet performance and cost targets.
Market Dynamics
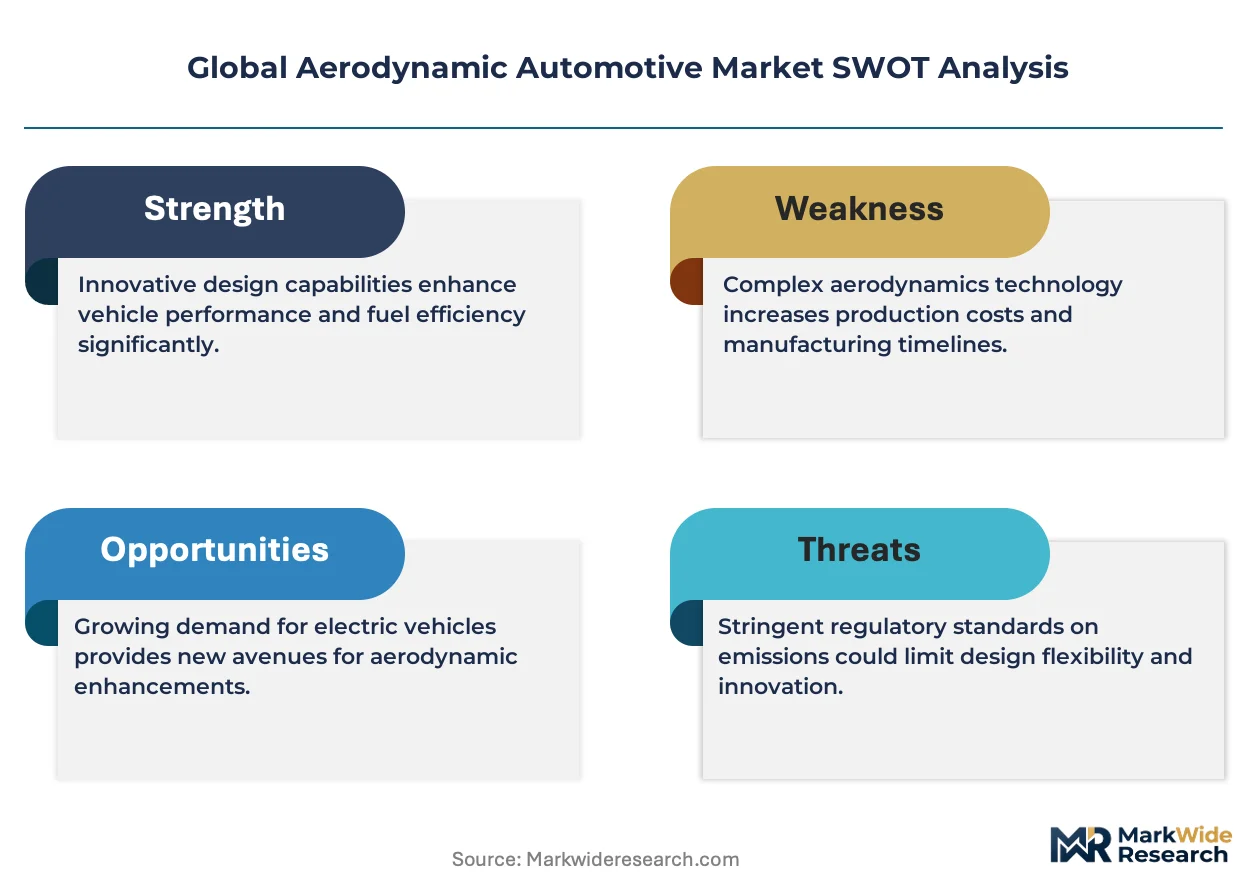
The market's central dynamic is the collision between regulatory mandates for lower emissions and the technical demands of electric vehicle range extension. This pressure forces a strategic pivot from passive, fixed-body shaping toward investment in complex, mechatronic active aerodynamic systems across vehicle segments.
Growth Catalysts
- EV Range Anxiety:Consumer and manufacturer focus on maximizing electric vehicle battery range acts as a powerful incentive for adopting advanced aerodynamic designs, as every reduction in drag directly translates to longer driving distances.
- Emissions Regulations:Frameworks like the EU's CO2 emission performance standards and China's dual carbon goals directly compel automakers to improve vehicle efficiency, making aerodynamic optimization a critical compliance pathway.
- Active System Adoption:The increasing integration of active aerodynamic technologies, such as adaptive spoilers and grille shutters, provides measurable performance and efficiency benefits, driving their adoption beyond niche performance cars into mainstream models.
Market Restraints
- Component Cost and Complexity:Active aerodynamic systems, incorporating sensors, actuators, and control units, carry a significant cost premium and add complexity to vehicle design, manufacturing, and long-term maintenance.
- Material and Supply Constraints:The reliance on lightweight materials like carbon fiber composites for high-performance aerodynamic components faces supply chain limitations and high input costs, restricting their use in mass-market vehicles.
- Design Trade-offs:Optimizing for aerodynamics can conflict with other design priorities, such as aesthetics, interior space, cooling requirements for powertrains, and pedestrian safety regulations, creating difficult engineering compromises.
Strategic Opportunities
- Commercial Vehicle Aerodynamics:Applying advanced aerodynamic principles and technologies to heavy-duty trucks and last-mile delivery vans presents a significant opportunity for fuel savings and emissions reduction in the logistics sector.
- Sensor Integration:The convergence of aerodynamics with autonomous driving is creating opportunities to embed LiDAR, radar, and camera sensors seamlessly within aerodynamic components, improving both function and aesthetics.
- Aftermarket Solutions:There is a developing market for certified aftermarket aerodynamic kits for popular EV and fleet models, allowing owners to upgrade their vehicles for improved efficiency and range.
Industry Challenges
- Software and System Integration:The effective operation of active aerodynamic systems requires complex software that must be flawlessly integrated with other vehicle control modules, posing a significant software development and validation challenge.
- Specialized Talent Scarcity:A shortage of engineers possessing dual expertise in computational fluid dynamics (CFD) and the mechatronics of active systems creates a bottleneck for R&D and product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerodynamic Automotive Market |
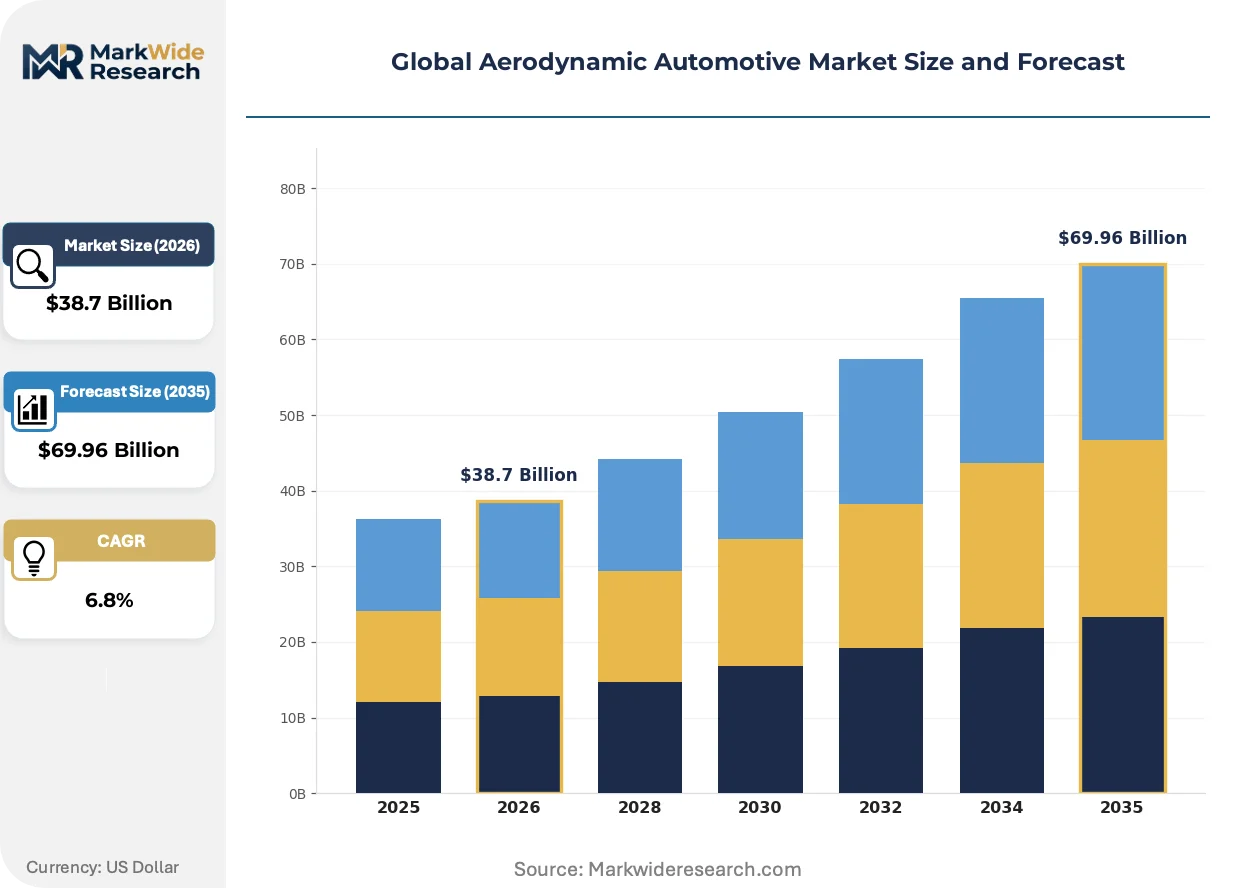
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Coupe, Hatchback, Convertible Technology: Active Aerodynamics, Passive Aerodynamics, Computational Fluid Dynamics, Wind Tunnel Testing Application: Performance Enhancement, Fuel Efficiency, Stability Control, Noise Reduction End User: OEMs, Aftermarket Suppliers, Tier-1 Specialists, Vehicle Assemblers |
| Companies Covered | Röchling Automotive, Hyundai Motor Company, Magna International Inc., Tesla, Mercedes-Benz Group AG, Valeo SA, Forvia SE, Hexcel, Plastic Omnium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerodynamic Automotive Market Strategic Shifts & Innovations
Intelligent airflow management is replacing static design as the core principle of automotive aerodynamics. The evolution is toward vehicles that actively and continuously adapt their aerodynamic profile in response to driving conditions, prioritizing efficiency, stability, or cooling as needed.
Software-defined active aerodynamics use an array of sensors and actuators to modify a vehicle's shape in real time. Premium electric vehicle manufacturers are rapidly adopting these systems to gain a competitive edge in range and performance. This technology is decentralizing aerodynamic control from a single, fixed vehicle shape to a distributed network of intelligent components, enabling mode-specific optimization for different driving scenarios.
United States EPA regulations on greenhouse gas emissions and Corporate Average Fuel Economy (CAFE) standards create a powerful incentive for drag reduction. These rules compel automakers to pursue every available avenue for efficiency improvement to meet fleet-wide targets. The truck and SUV segments, which are critical to profitability for many OEMs in North America, are most affected, accelerating the adoption of features like active grille shutters.
A notable shift in purchasing behavior involves the unbundling of aerodynamic features into distinct option packages. This disrupts the traditional model where aerodynamics were baked into a specific trim level, instead allowing customers to select packages focused on either efficiency or performance styling. This trend is most pronounced in the European premium vehicle market, where consumer demand for personalization influences OEM product strategy.
Global Aerodynamic Automotive Market Segmentation
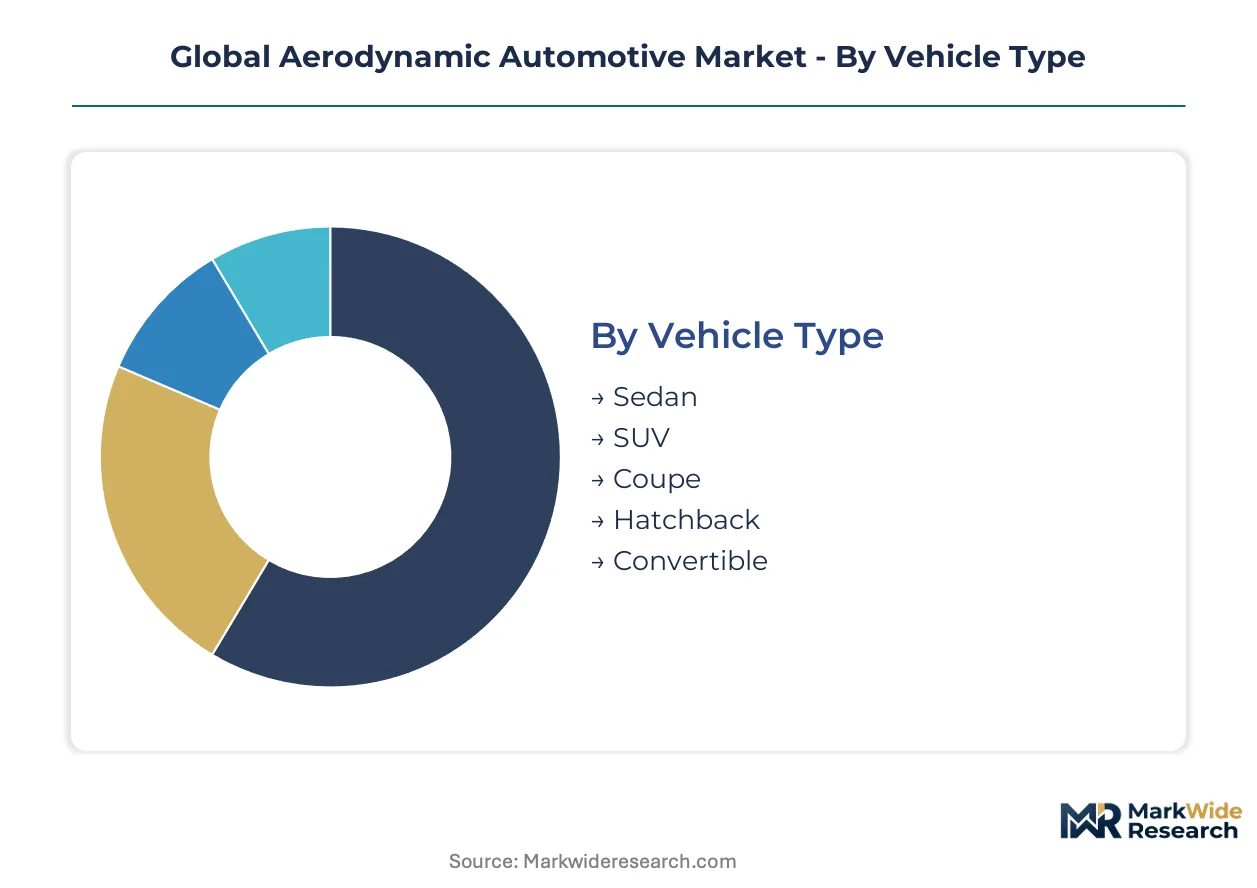
The global aerodynamic automotive market categorizes solutions by vehicle type, underlying technology, primary application, and the end-user segment. This segmentation provides a granular view of demand drivers and competitive landscapes, allowing stakeholders to identify specific growth pockets.
Vehicle Type:
The vehicle type segmentation highlights varying regulatory compliance pathways for aerodynamic efficiency, with different vehicle classes facing distinct certification burdens.
- Sedan:These vehicles often prioritize sleek profiles and low drag coefficients to meet fuel economy standards, especially in markets driven by stringent emissions regulations like the EU's CO2 targets. Demand concentrates in regions with high passenger car sales, including China and Germany.
- SUV:Larger frontal areas and higher ground clearance in SUVs present greater aerodynamic challenges, making drag reduction critical for improving range in electric variants and meeting EPA fuel economy standards in the United States. This segment experiences significant investment in active aerodynamic features.
- Coupe:Design aesthetics and high-speed stability are paramount for coupe aerodynamics, often incorporating subtle bodywork enhancements and active spoilers.
- Hatchback:Aerodynamic optimization for hatchbacks focuses on managing airflow detachment at the rear to reduce drag and improve fuel efficiency for urban driving cycles.
- Convertible:Solutions for convertibles address both closed-roof drag reduction and managing cabin airflow during open-top driving for passenger comfort.
SUV sits at the top of the volume ranking, with Convertible climbing the fastest.
Technology:
Technology adoption within aerodynamic automotive design reflects diverse application needs across the industry.
- Active Aerodynamics:These systems dynamically alter a vehicle's shape using sensors and actuators to optimize airflow for varying conditions, crucial for extending electric vehicle range and enhancing high-speed stability. Demand is concentrating in premium and electric vehicle segments in Europe and California.
- Passive Aerodynamics:Fixed design elements, such as body shaping, underbody panels, and fixed spoilers, reduce drag through permanent structural modifications, providing cost-effective efficiency gains. This technology remains fundamental across all vehicle classes globally.
- Computational Fluid Dynamics:CFD software simulates airflow around vehicle designs, enabling rapid prototyping and optimization of aerodynamic properties before physical testing. Automotive R&D departments widely utilize this tool for early-stage design validation.
- Wind Tunnel Testing:Physical testing in controlled environments provides empirical data on aerodynamic performance, validating CFD models and fine-tuning designs for production vehicles.
Passive Aerodynamics offers cost-effective solutions, while Active Aerodynamics commands a premium margin due to its complexity.
Application:
Understanding the primary application drivers informs customer type prioritization for aerodynamic solutions.
- Fuel Efficiency:This application focuses on minimizing drag to reduce fuel consumption in internal combustion engine vehicles and extend battery range in electric vehicles. Regulations from the US EPA and EU Green Deal compel automakers to prioritize this area.
- Performance Enhancement:Aerodynamic components improve vehicle handling, downforce, and stability at high speeds, critical for sports cars and racing applications. High-performance vehicle manufacturers in Germany and Italy drive demand here.
- Stability Control:Managing airflow to maintain vehicle stability, particularly in crosswinds or during high-speed maneuvers, is a key function of aerodynamic design. This application is vital for larger vehicles and trucks.
- Noise Reduction:Aerodynamic shaping minimizes wind noise, enhancing cabin comfort, especially important for luxury and electric vehicles where powertrain noise is absent.
Fuel Efficiency solutions are widely distributed, whereas Performance Enhancement components show higher supply chain concentration among specialized suppliers.
End User:
End-user segments exhibit different cost tier sensitivities for aerodynamic components and systems.
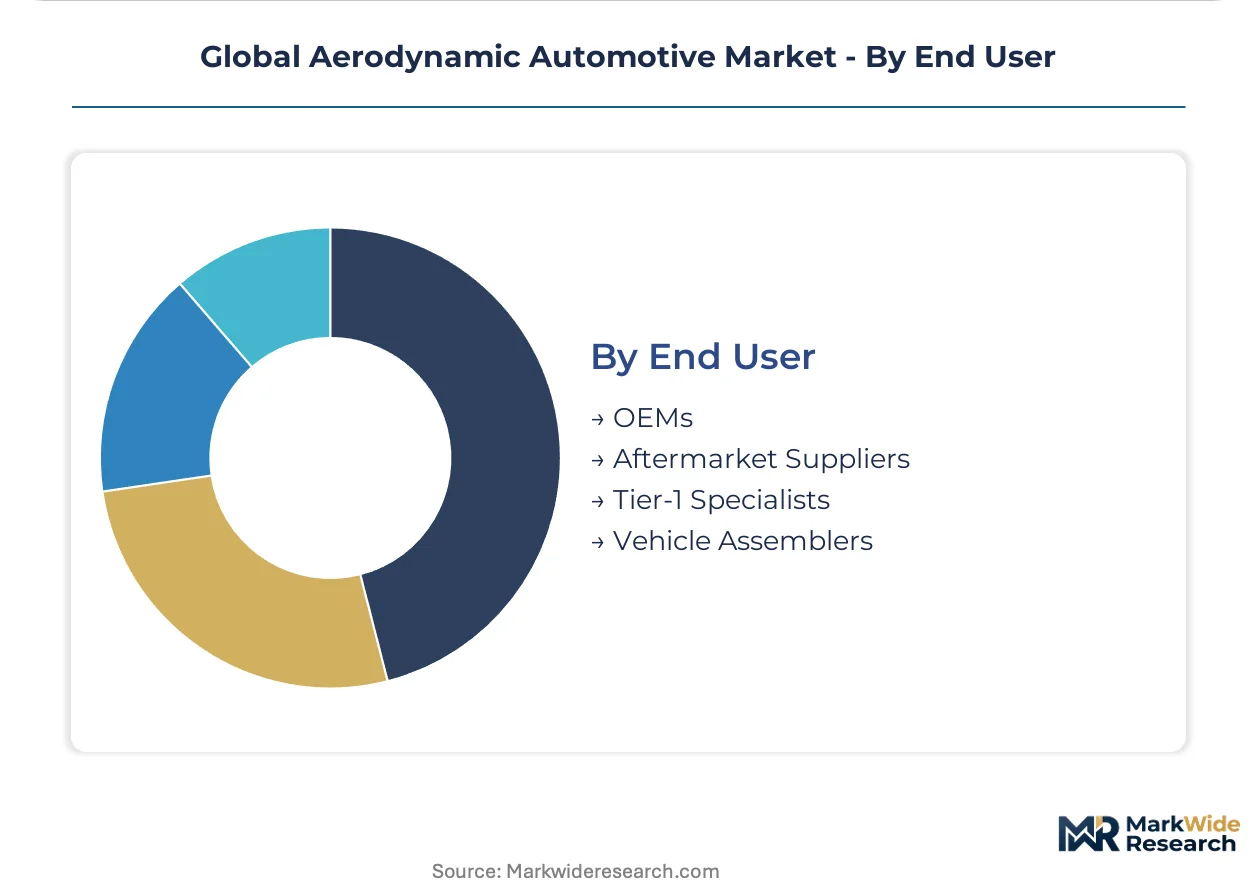
- OEMs:Original Equipment Manufacturers integrate aerodynamic solutions directly into new vehicle designs, seeking high-volume, cost-optimized components that meet stringent performance and safety standards. Major global automakers are the primary consumers.
- Aftermarket Suppliers:These companies provide aerodynamic kits and components for vehicle customization, performance upgrades, or efficiency improvements after the initial sale. This segment caters to niche markets and individual vehicle owners.
- Tier-1 Specialists:These suppliers develop and manufacture complex aerodynamic modules and systems, often incorporating active components, directly for OEMs. They possess specialized R&D capabilities and production expertise.
- Vehicle Assemblers:These entities focus on the final integration of components into complete vehicles, relying on suppliers for pre-assembled aerodynamic systems.
OEMs represent a mature segment, but Aftermarket Suppliers demonstrate significant growth potential for specialized aerodynamic kits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta region, a major automotive manufacturing hub, drives significant demand for aerodynamic solutions. This area's focus on electric vehicle production and advanced mobility systems positions it at the forefront of automotive design. Global regulatory pressures further accelerate the push for efficiency across all vehicle segments.
China
Demand for advanced aerodynamic components in China stems from its rapid electric vehicle expansion. The nation's dual carbon goals compel automakers to prioritize drag reduction for extended EV range and lower emissions. Shenzhen's tech ecosystem fosters innovation in active aerodynamic systems for new energy vehicles.
United States
Consumer preference for SUVs and trucks in the United States elevates the importance of aerodynamic efficiency. The US EPA's fuel economy standards and CAFE regulations mandate continuous improvements in vehicle drag coefficients. Detroit, Michigan, remains a key center for automotive R&D, integrating active aerodynamics into mainstream models.
Germany
European premium vehicle manufacturers in Germany emphasize aerodynamic design for high-speed stability and luxury comfort. The EU's CO2 emission performance standards directly influence the adoption of advanced airflow management systems. Bavaria's automotive cluster leads in developing complex mechatronic solutions for active aerodynamics.
Japan
Japanese automakers focus on aerodynamic optimization for fuel efficiency across their diverse vehicle portfolios. METI initiatives support research into lightweight materials and intelligent airflow management systems for next-generation vehicles. Nagoya's automotive industry drives advancements in passive aerodynamic shaping and underbody panels.
South Korea
South Korean OEMs prioritize aerodynamic design to enhance the range of their competitive electric vehicle offerings. The country's environmental regulations encourage investment in advanced drag reduction technologies for both domestic and export markets. Seoul's design centers are integrating sensor technology into aerodynamic modules for smart mobility solutions.
Global Aerodynamic Automotive Market Key Industry Players
Established producers occupy the standard tier, focusing on passive aerodynamic solutions and foundational components; emerging entrants pursue complex, mechatronic active aerodynamic systems. The market structure exhibits a blend of specialized component suppliers and integrated automotive groups. Strategic archetypes include traditional OEM suppliers, innovative tech-driven solution providers, and material specialists. Portfolio diversification, strategic partnerships, and targeted acquisitions for software expertise are dominant competitive moves.
Specialists in integrated design and advanced systems include Tesla, which exemplifies an OEM adopting a fully integrated approach to aerodynamic development, particularly for electric vehicles. Magna International Inc. represents a diversified Tier-1 supplier, leveraging its broad portfolio to serve various OEM needs across different vehicle segments, from passive components to active systems. Valeo SA, a French automotive supplier, occupies a position as an innovator embedding advanced sensor technology within aerodynamic modules, enhancing both function and aesthetics. These entities collectively drive innovation across passive and active aerodynamic solutions, shaping the market's technological trajectory.
| Leading Market Players |
|---|
| Röchling Automotive |
| Hyundai Motor Company |
| Magna International Inc. |
| Tesla |
| Mercedes-Benz Group AG |
| Valeo SA |
| Forvia SE |
| Hexcel |
| Plastic Omnium |
Cost & Logistics Intelligence
The EU Green Deal, coupled with EPA standards, gates access to premium aerodynamic solutions, influencing both qualified supplier selection and pricing power for advanced components.
Pricing Analysis
Input costs for specialized materials like carbon fiber composites and advanced mechatronic components are frequently passed through to OEMs. Pricing stratifies across premium, standard, and economy tiers, driven by technology complexity and software integration levels. R&D investments for active systems exert upward pricing pressure. Mass-market OEMs and aftermarket suppliers exhibit higher price sensitivity compared to premium electric vehicle manufacturers.
Supply Chain Analysis
Supply of critical active aerodynamic components rests heavily on specialized Tier-1 suppliers located in Germany for mechatronics and in China for EV-specific parts. Key dependencies include carbon fiber composites for lightweight structures and advanced sensors for active systems. Single-source vulnerability for highly integrated active modules presents a structural risk. Distribution runs through direct B2B channels from Tier-1 suppliers to Original Equipment Manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerodynamic automotive market presents a clear margin-expansion story, driven by the premiumization of active systems and increasing software integration. This shift allows for higher value capture per vehicle and specialized component.
For Market Incumbents: Hedge against component commoditization by investing in proprietary software for active aerodynamic control. Pursue strategic partnerships with sensor technology specialists to integrate advanced capabilities directly into modules, mitigating the threat from emerging tech-driven entrants. Expand manufacturing capacity for lightweight materials in key regions like Europe to secure supply. Focus R&D on multi-functional components that combine drag reduction with cooling or sensor housing.
For New Entrants and Emerging Players: Launch via certified aftermarket solutions for popular electric vehicle models, targeting range extension and efficiency improvements. Focus on niche segments like commercial vehicles or last-mile delivery vans, which present significant untapped potential for fuel savings. Develop modular, easy-to-install aerodynamic kits that simplify integration for fleet owners. Leverage advanced simulation tools like computational fluid dynamics to accelerate product development and validation.
For Investors and Strategic Acquirers: Valuations sit cheapest among traditional passive aerodynamic component manufacturers with strong OEM relationships but limited active system capabilities. The long-term viability favors firms with deep expertise in mechatronics and software for active aerodynamics. Target acquisition candidates possessing specialized intellectual property in intelligent airflow management or sensor integration. A critical signal to watch is the increasing attach rate of active grille shutters and adaptive spoilers in mainstream vehicle segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Aerodynamics Investment | Enhances vehicle performance and range through real-time adaptive control for premium EVs. |
| Lightweight Composite Material R&D | Reduces vehicle mass and improves fuel efficiency, critical for EV battery range extension. |
| Sensor Integration Partnerships | Embeds advanced sensors seamlessly into aerodynamic modules, improving autonomous driving capabilities. |
| Commercial Vehicle Aerodynamic Solutions | Unlocks significant fuel savings and emissions reduction opportunities for logistics fleets. |
| Modular Aftermarket Kit Development | Captures new revenue streams by offering efficiency upgrades for existing vehicle fleets. |
Research Approach
Multiple input streams — primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, and automotive R&D directors, alongside secondary data from vehicle production databases and regulatory filings — were reconciled. This approach combined qualitative insights from industry stakeholders with quantitative validation. Bottom-up data aggregation from individual vehicle segments and top-down market sizing provided triangulation.
Data-stream reconciliation informed the analytical framework used to project market trajectories across the analysis window. Segmentation dimensions modeled included vehicle type, technology, application, and end-user, plus content per vehicle. Compound Annual Growth Rates were derived from historical trends, projected technological adoption rates, and regulatory impact assessments. Key forecast inputs included electric vehicle production forecasts and future emissions standards.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or rapid shifts in raw material commodity prices. Forecasts reflect assumptions regarding regulatory stability and technological progression. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Argentina Automotive Engine Oils Market
Automotive Parts
North America Gear Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive Parts Aluminum Die Casting Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Wheel Arch Liner Market