
 China and Saudi Arabia Automotive Market | 2026-2036
China and Saudi Arabia Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
China and Saudi Arabia Automotive Market Outlook
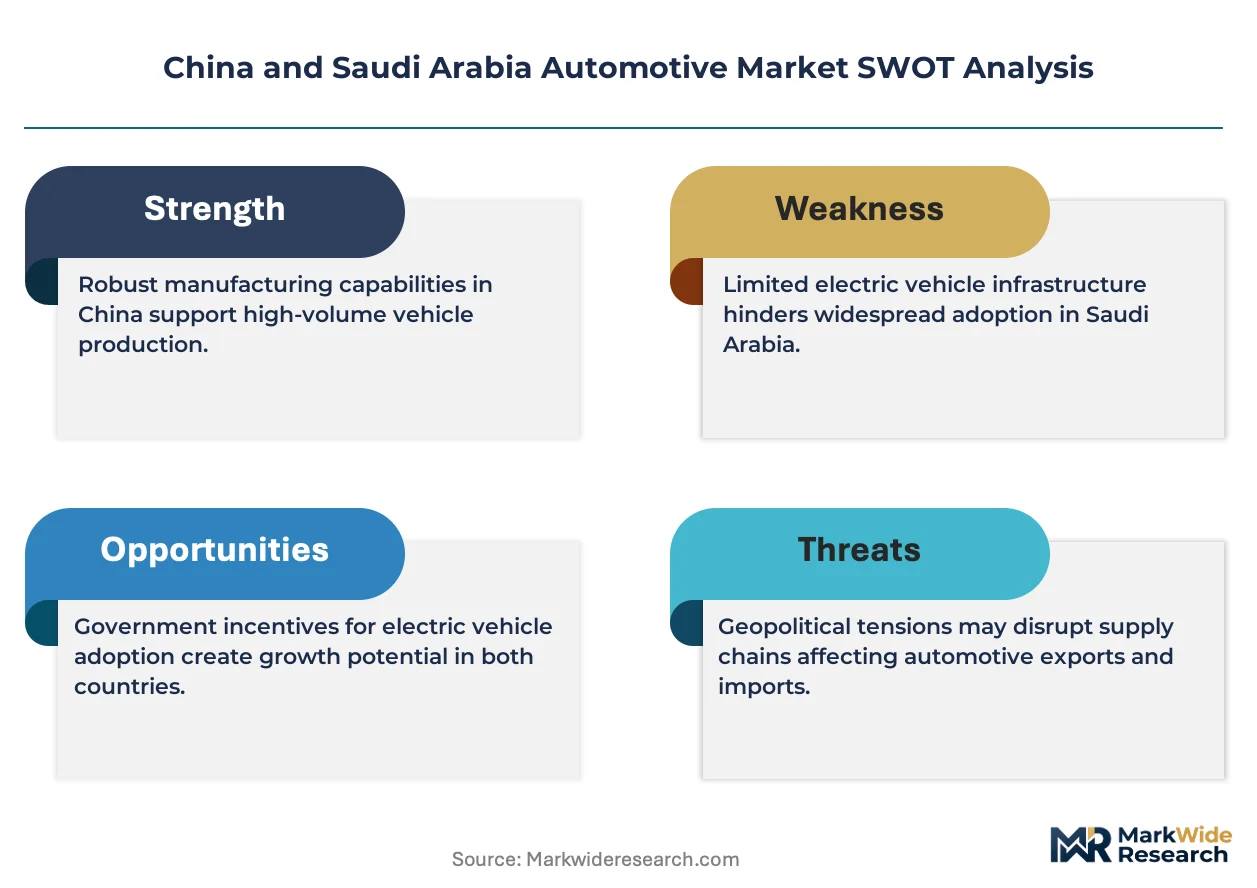
Project finance for battery-electric vehicle assembly is fragmenting the competitive landscape in both countries. BYD leverages its in-house cell production to control costs across Saudi distribution networks. Geely anchors its position through R&D intensity in hybrid powertrains tailored to regional fuel economics. Great Wall Motors specializes in SUV platforms that dominate desert-climate durability requirements.
The China and Saudi Arabia Automotive sector encompasses passenger and light commercial vehicles engineered to operate across extreme temperature ranges from minus 30°C to plus 50°C, with cooling systems, battery thermal management, and dust-sealing specifications exceeding baseline global platforms. Its primary purpose is to serve mobility and logistics demand across two of the world's largest vehicle procurement markets with divergent infrastructure maturity. SUV and electric fuel type segments are capturing margin pools as family-size vehicle preferences persist in China and Saudi Arabia's subsidy frameworks for new energy vehicles expand. Economy-tier sedans retain volume dominance through fleet sales to ride-hailing operators and government procurement channels.
China's MIIT enforces GB standards for new energy vehicle range certification and battery recycling accountability, while Saudi Arabia's national regulator mandates local content thresholds under industrial development licenses. These frameworks shape which foreign manufacturers qualify for preferential financing and which powertrain architectures receive import duty relief. Stakeholders must monitor how carbon-border adjustment mechanisms and bilateral trade protocols between Beijing and Riyadh redefine component sourcing rules.
Market Dynamics
Local content mandates under China's MIIT and Saudi Arabia's industrial licensing regime are forcing foreign assemblers to reconfigure supply footprints, accelerating joint ventures with domestic battery and chassis suppliers.
Growth Catalysts
- Dual carbon goals:China's binding emissions targets under MEE oversight mandate fleet electrification timelines, pulling forward procurement of NEV platforms by state-owned logistics operators.
- Vision 2030 transport targets:Saudi subsidy frameworks for new energy vehicles expand eligibility to commercial fleets, redirecting procurement budgets toward electric SUVs and light trucks.
- Desert-climate durability specifications:Battery thermal management systems engineered for 50°C ambient operation are unlocking fleet sales to mining and construction contractors across the Arabian Peninsula.
Market Restraints
- Lithium carbonate volatility:Cell-grade lithium input costs swing with spot-market exposure, compressing margin visibility for assemblers without captive mining offtake.
- Charging infrastructure gaps:Riyadh and Jeddah deployment lags vehicle registration growth, stranding fleet utilization rates for early electric adopters.
- GB standards compliance burden:China's MIIT range certification protocols require redundant testing cycles, extending product launch timelines for imported platforms.
Strategic Opportunities
- Eastern Province manufacturing zone:Saudi Arabia's King Salman Energy Park offers duty-free component import status for assemblers meeting 60% local value-add thresholds.
- Battery-swapping infrastructure:Taxi and ride-hailing fleets in Shanghai are piloting 90-second exchange stations, reducing downtime versus fast-charging cycles.
- Carbon-border adjustment alignment:Bilateral Beijing-Riyadh trade protocols may harmonize embodied-carbon accounting rules, simplifying cross-border component flows.
Industry Challenges
- Thermal engineering talent scarcity:Battery pack cooling system design expertise concentrates with Tier 1 suppliers, forcing OEMs to outsource core IP development.
- Recycling accountability compliance:China's MIIT battery passport requirements demand full lifecycle traceability, requiring IT system overhauls for legacy fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China and Saudi Arabia Automotive Market |
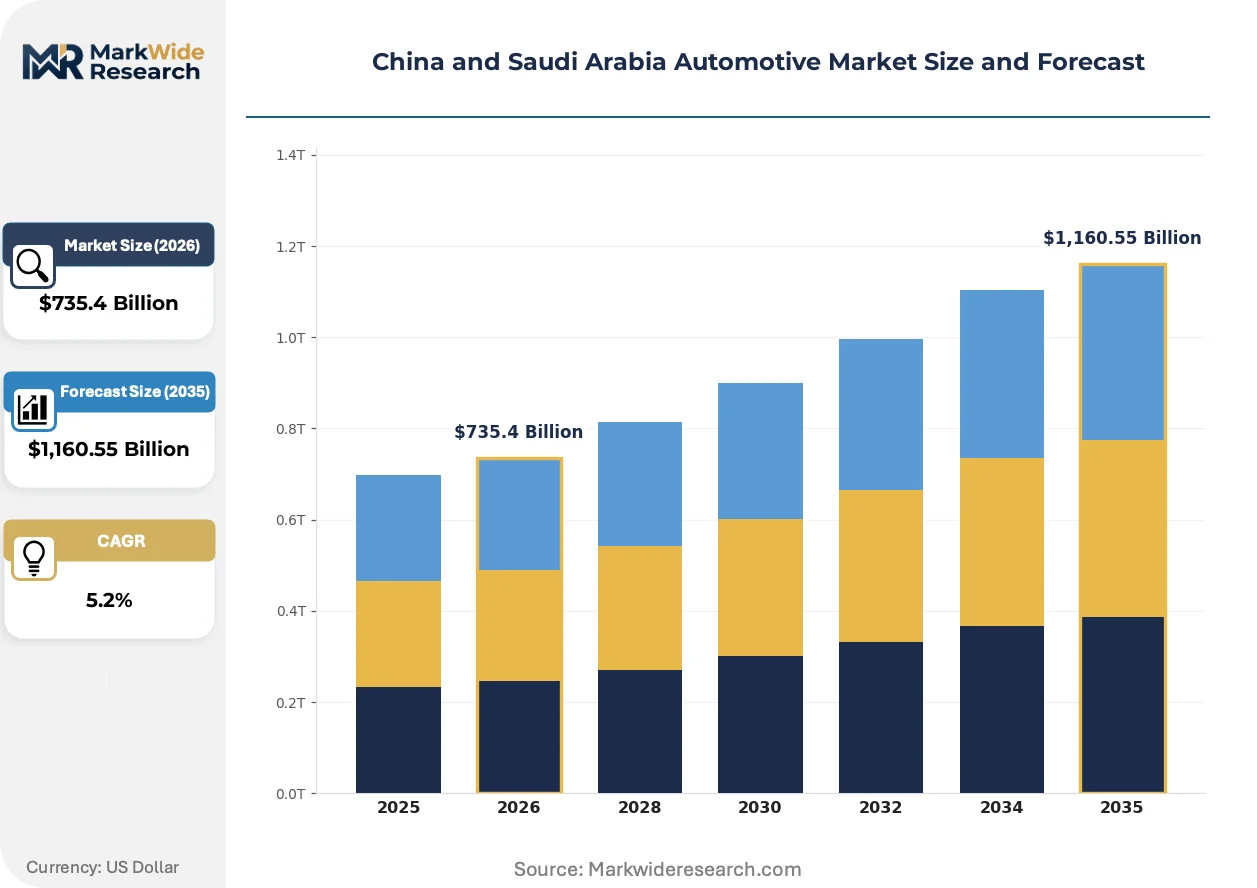
| Market Size in 2026 | $735.4 Billion |
| Market Size in 2035 | $1,160.55 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Pickup Fuel Type: Gasoline, Diesel, Electric, Hybrid Market Segment: Luxury, Economy, Mid-range, Sports Sales Channel: Online, Dealership, Auction, Direct |
| Companies Covered | Geely, MG Motor, BYD, Jetour, GAC Motor, Great Wall Motors, Chery, Haval, Changan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China and Saudi Arabia Automotive Market Strategic Shifts
Powertrain architecture decisions are increasingly governed by software-defined thermal management, with over-the-air calibration replacing hardware-heavy platform redesigns.
Silicon carbide inverters are replacing IGBT modules in 800-volt architectures, cutting switching losses by half. Premium SUV assemblers in Shanghai and Riyadh are adopting the technology for desert-range extension. This voltage-grade transition is digitizing the boundary between power electronics and vehicle control systems, collapsing traditional Tier 1-Tier 2 supplier hierarchies.
China's GB standards for new energy vehicle cybersecurity mandate over-the-air update capabilities and intrusion detection systems across all connected platforms. MIIT enforcement began with passenger vehicles and now extends to light commercial categories. Fleet operators in Guangdong and Zhejiang provinces are prioritizing compliant platforms to maintain government procurement eligibility.
Fleet managers are consolidating procurement authority into centralized sustainability offices, displacing decentralized regional buying. State-owned logistics groups in China and Saudi Aramco-affiliated transport operators now mandate lifecycle carbon reporting from shortlisted vendors. This buying-pattern shift is most visible in Riyadh, where fleet tenders now weight total-cost-of-ownership metrics above upfront vehicle pricing.
China and Saudi Arabia Automotive Market Segmentation
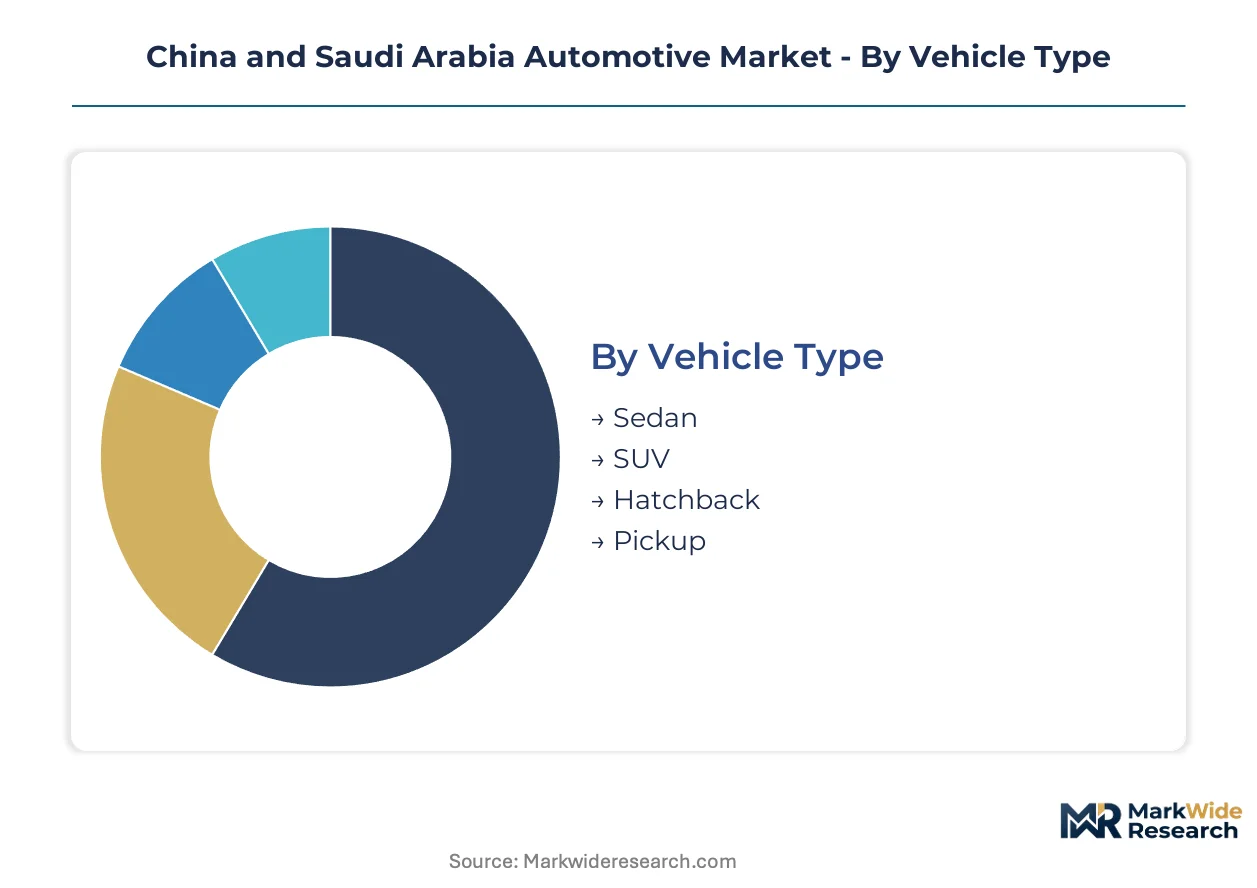
Segmentation in the China and Saudi Arabia Automotive Market reveals divergent procurement patterns shaped by climate engineering requirements and regulatory compliance pathways. Fleet operators and retail buyers prioritize different vehicle architectures based on thermal management specifications and local content eligibility.
Vehicle Type:
Cost tier differentiation across body styles determines margin pools and manufacturing localization incentives in both markets.
- Sedan:Three-box configurations dominate fleet procurement channels for ride-hailing operators in Shanghai and government tenders in Riyadh. Volume concentrates in economy-tier powertrains where dual carbon compliance and Vision 2030 subsidy eligibility intersect.
- SUV:Elevated ride height and reinforced suspension architectures address desert terrain requirements across the Arabian Peninsula. Battery thermal management systems engineered for 50°C ambient operation unlock fleet sales to mining contractors and state-owned logistics groups prioritizing durability specifications.
- Hatchback:Compact two-box designs serve urban density constraints in Shanghai's central districts with parking-optimized dimensions.
- Pickup:Ladder-frame construction with reinforced cargo beds targets construction sector procurement in Saudi Arabia's Eastern Province manufacturing zones.
SUV holds installed capacity. Sedan is rotating up the share rankings.
Fuel Type:
Application-specific duty cycles determine powertrain selection across passenger mobility and commercial logistics use cases.
- Gasoline:Port-injection and direct-injection variants retain volume dominance in Saudi Arabia's subsidy-adjusted fuel pricing environment. Fleet operators in Riyadh and Jeddah specify these powertrains for long-distance highway routes where charging infrastructure deployment remains incomplete.
- Electric:Battery-electric platforms with cell-to-pack architectures are capturing procurement mandates from state-owned logistics operators under China's MEE oversight and Saudi Aramco-affiliated transport groups. Range certification under GB standards and local content thresholds shape qualification for preferential financing.
- Diesel:Compression-ignition engines serve heavy-duty commercial applications with torque-optimized calibrations for desert climate operation.
- Hybrid:Series-parallel architectures bridge infrastructure gaps in secondary cities with dual-fuel flexibility and regenerative braking systems.
Gasoline holds installed capacity. Electric is climbing the fastest.
Market Segment:
Customer type stratification reflects divergent purchasing authority between centralized fleet sustainability offices and decentralized retail buyers.
- Economy:Steel-wheel, cloth-interior specifications with simplified infotainment systems serve price-sensitive procurement in government fleet channels. MIIT range certification requirements and Saudi industrial licensing local content thresholds filter supplier eligibility.
- Luxury:Nappa leather, active noise cancellation, and air suspension configurations target executive mobility services in Shanghai Pudong and Riyadh diplomatic quarters. Lifecycle carbon reporting mandates from consolidated procurement offices weight total-cost-of-ownership metrics above upfront vehicle pricing.
- Mid-range:Synthetic leather seating with partial ADAS suites captures family vehicle replacement cycles in Zhejiang province.
- Sports:Lowered suspension and reinforced chassis bracing address enthusiast demand in Guangdong province tuning culture.
Economy holds installed capacity. Luxury is gaining share fastest.
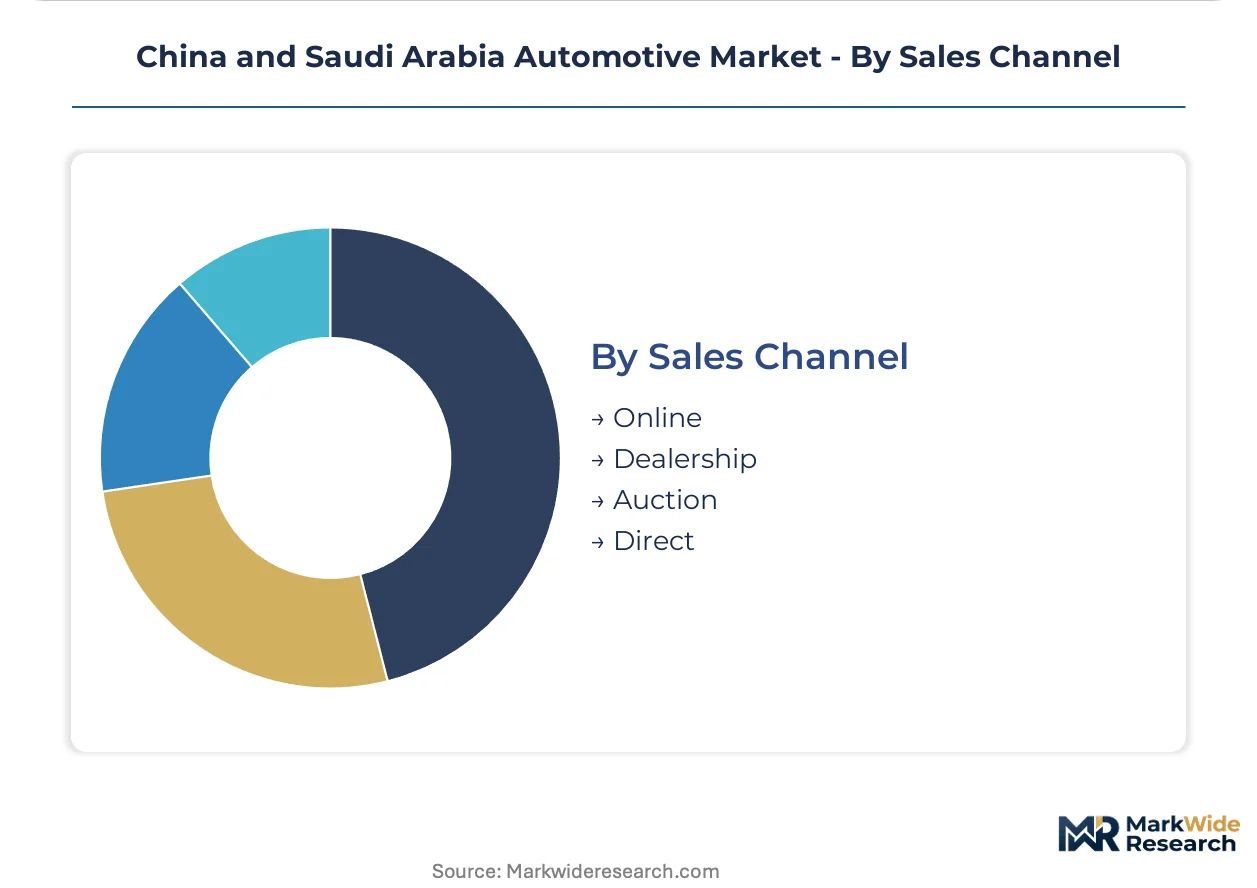
Sales Channel:
Supply concentration in digital platforms versus physical infrastructure shapes geographic reach and customer acquisition economics.
- Dealership:Brick-and-mortar showrooms with service bay integration dominate trust-sensitive transactions in Riyadh and Jeddah. Test drive access and warranty claim proximity influence procurement decisions from family buyers and small fleet operators.
- Online:Configurator-based ordering with home delivery logistics is displacing traditional retail in Shanghai's digitized consumer base. MIIT cybersecurity compliance for over-the-air update capabilities enables this channel shift for connected platforms.
- Direct:Manufacturer-owned stores with fixed pricing eliminate negotiation friction for subscription-based mobility services.
- Auction:Secondary market clearinghouses for fleet decommissioning and lease return volume concentrate in Guangdong province.
Dealership holds installed capacity. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and Saudi Arabia Automotive Market trade flows reflect divergent manufacturing capabilities. China exports complete knock-down kits and battery systems to Saudi assembly plants. Saudi Arabia's import dependency concentrates in Riyadh and Jeddah port corridors where customs clearance for automotive components operates under bilateral protocols.
China
Yangtze River Delta cluster anchors electric vehicle output with Shanghai-based battery pack assembly feeding both domestic and export channels. MIIT enforces GB standards for new energy vehicle range certification and cybersecurity over-the-air update mandates. Shenzhen and Guangzhou house silicon carbide inverter fabrication facilities supplying 800-volt architectures for desert-climate SUV platforms.
Saudi Arabia
Riyadh commands procurement authority for state-owned logistics fleet electrification under Vision 2030 transport targets. The national industrial regulator mandates local content thresholds under assembly licensing regimes. King Salman Energy Park in the Eastern Province offers duty-free component import status for assemblers meeting value-add requirements.
United Arab Emirates
Dubai serves as re-export hub for Chinese automotive components entering Saudi distribution networks. MOHAP oversees product safety registration for vehicles transiting through Jebel Ali free zones. Abu Dhabi investment authorities channel sovereign capital into battery-electric vehicle charging infrastructure joint ventures with Chinese equipment vendors.
South Korea
Busan-Ulsan industrial corridor supplies battery cell manufacturing equipment to Saudi gigafactory projects. MFDS regulatory alignment with Chinese GB cybersecurity standards facilitates component certification reciprocity. Seoul-based thermal management engineering firms contract with Saudi OEMs for desert-climate battery pack design.
Germany
Bavaria hosts power electronics specialists licensing silicon carbide inverter technology to Chinese platform integrators. KBA type-approval processes for vehicles exported to Saudi Arabia require adaptation to desert-climate durability specifications. Stuttgart engineering consultancies advise Saudi industrial licensing authorities on local content measurement methodologies.
China and Saudi Arabia Automotive Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in battery thermal management and power electronics. The vendor base stratifies between full-stack assemblers with captive cell production and modular suppliers of desert-climate cooling systems. Three archetypes dominate: vertically integrated battery producers, hybrid powertrain engineering houses, and SUV platform specialists optimized for extreme temperature operation. Competitive moves center on joint venture formation for local content compliance and licensing agreements for 800-volt silicon carbide architectures.
Among Chinese platform integrators, BYD and Geely occupy anchor positions in the battery-electric and hybrid segments respectively. BYD exemplifies the vertically integrated archetype with in-house cell production controlling cost structures across Saudi distribution networks. Geely represents the engineering-intensive hybrid specialist tailoring powertrain calibrations to regional fuel economics. Great Wall Motors anchors the SUV platform tier with desert-climate durability specifications that dominate mining and construction fleet procurement in the Arabian Peninsula.
| Leading Market Players |
|---|
| Geely |
| MG Motor |
| BYD |
| Jetour |
| GAC Motor |
| Great Wall Motors |
| Chery |
| Haval |
| Changan |
| Others |
Value Chain & Pricing Dynamics
Shanghai's Yangtze River Delta battery pack assembly cluster anchors cost structures across both domestic and export channels, with capacity utilization rates downstream directly translating to pricing leverage for OEMs negotiating cell supply contracts. Saudi Arabia's King Salman Energy Park duty-free status creates a parallel pricing corridor where local value-add thresholds determine component import economics for desert-climate SUV platforms.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on certification grade under China's MIIT GB standards and volume scale commitments. Price differentiation stems from thermal management specification tiers and after-sales service bundling for desert-climate durability. Cost compression in economy-tier sedans is intensifying because ride-hailing fleet operators consolidate procurement authority into centralized sustainability offices. State-owned logistics groups exhibit lowest price sensitivity due to lifecycle carbon reporting mandates, while independent dealership networks in Riyadh and Jeddah face highest sensitivity from charging infrastructure deployment gaps.
Supply Chain Analysis
Extended payment terms from Saudi industrial licensing authorities and supply-chain finance facilities anchored by Abu Dhabi investment channels are restructuring working capital requirements for component suppliers. Geographic supply concentration centers on China for cell-to-pack architectures, South Korea for battery cell manufacturing equipment, and Germany for silicon carbide inverter technology. Raw material dependencies draw from lithium carbonate spot markets, nickel cathode precursors, and rare-earth permanent magnet feedstocks. Single-source vulnerability concentrates in Tier 1 thermal management engineering talent pools. Distribution runs through Shanghai-based export channels feeding Riyadh and Jeddah port corridors under bilateral Beijing-Riyadh trade protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from modular desert-climate cooling system suppliers collapsing traditional Tier 1-Tier 2 hierarchies through software-defined thermal management platforms.
For Market Incumbents: Build captive cell production moats through backward integration into lithium mining offtake and in-house silicon carbide inverter fabrication, mirroring BYD's cost control across Saudi distribution networks. Consolidate hybrid powertrain engineering capabilities to defend against emerging pure-electric entrants exploiting GB standards compliance gaps. Priority investment in 800-volt architecture licensing agreements secures positioning as voltage-grade transitions accelerate.
For New Entrants and Emerging Players: Saudi Arabia's Eastern Province manufacturing zone offers underpenetrated white-space for battery-swapping infrastructure pilots targeting taxi and ride-hailing fleet operators. Secondary cities across Zhejiang province present parallel entry points for hybrid platforms bridging charging infrastructure gaps. Go-to-market execution through direct manufacturer-owned stores with fixed pricing eliminates negotiation friction against entrenched dealership networks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated battery producers with captive thermal management IP and long-term fleet service contracts. Five-to-ten year viability favors platform integrators controlling both cell supply and desert-climate durability specifications. Acquisition targets should demonstrate compliance pathway clarity under evolving MIIT battery passport requirements and Saudi local content thresholds. Monitor bilateral carbon-border adjustment mechanism negotiations as inflection indicator for cross-border component flow economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtake secures cost visibility under lithium carbonate volatility exposure. |
| Geographic Manufacturing Footprint | Eastern Province localization unlocks duty-free component status under Saudi industrial licensing. |
| Software-Defined Vehicle Investment | Over-the-air thermal calibration reduces hardware redesign cycles for desert-climate platforms. |
| Charging Infrastructure Partnership | Joint ventures with Chinese equipment vendors address Riyadh and Jeddah deployment gaps. |
| Platform Standardization | Modular SUV architectures span economy through luxury tiers under unified thermal management IP. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers and refined through secondary validation across MIIT regulatory filings, Saudi industrial development license databases, vehicle production registries, and bilateral trade protocol documentation. Bottom-up segment sizing triangulated against top-down macroeconomic indicators anchored the analytical framework.
Demand-supply-balance modeling across the analysis window integrated vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation dimensions. CAGRs were derived from installation base growth trajectories and replacement cycle dynamics. Forecast inputs incorporated charging infrastructure deployment schedules and local content threshold compliance pathways under evolving regulatory frameworks.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot pricing, sovereign subsidy allocation, or carbon-border adjustment implementation timelines would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Automotive Activated Carbon Canister Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Ball Joints Market