
 Modular Belt Drive Market | 2026-2036
Modular Belt Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Belt Drive Market Analysis
Food processing buyers are unwinding legacy flat-belt specifications in favor of modular designs that simplify sanitation compliance. Habasit sustains technology leadership through antimicrobial compound integration and open-hinge geometries. Martin Sprocket & Gear dominates North American distribution with captive foundry capacity and rapid custom sprocket turnaround. Intralox positions its ThermoDrive and Activated Roller Belt platforms to capture premium applications in protein processing and ready-meal assembly where cleanability standards intensify.
Modular belt drives consist of interlocking plastic, steel, or composite segments joined by hinge rods, engineered to specific pitch dimensions and load ratings for directional conveying, accumulation, or elevation tasks. The segment architecture permits localized replacement of damaged modules rather than full belt swaps, reducing maintenance downtime in continuous-flow operations. Plastic modular belts lead volume shipments across food processing and packaging lines where corrosion resistance and lightweight construction reduce motor sizing requirements. Steel modular belts anchor high-temperature and heavy-load segments in material handling and textile manufacturing, commanding margin premiums through extended service intervals under abrasive conditions. Hybrid modular belts represent the fastest-expanding category as OEMs blend polymer hygiene properties with metal structural elements for chemical processing and automotive component conveying.
ISO 22000 food safety management standards and EU Machinery Directive 2006/42/EC compliance obligations shape product design requirements for open surfaces and clean-in-place compatibility across European installations. The FDA's Food Contact Notification program and USDA equipment acceptance criteria dictate polymer formulations and surface finishes for belts deployed in North American meat, poultry, and dairy facilities. Stakeholders must monitor evolving PFAS restrictions in polymer compounding and emerging carbon-footprint disclosure mandates that threaten to segment supplier qualification criteria beyond mechanical performance alone.
Market Dynamics
Hygiene mandates from EU Machinery Directive and FDA food contact regulations are forcing stainless steel and antimicrobial belt specifications across food processing facilities, compressing legacy flat-belt procurement cycles and elevating modular designs to default status.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Open-surface and clean-in-place compatibility requirements accelerate modular belt replacement of sealed flat-belt systems in European meat and dairy facilities.
- Antimicrobial polymer compounding:Food-grade additive integration enables belt surfaces that resist biofilm formation, satisfying USDA equipment acceptance criteria for North American protein processors.
- German automotive component manufacturers:Precision conveying demands for electric drivetrain assembly drive premium modular belt procurement with tight pitch tolerances and load-specific engineering.
Market Restraints
- Polymer feedstock volatility:Engineering-grade thermoplastic resin prices fluctuate with crude oil derivatives, compressing margin stability for plastic modular belt fabricators.
- Steel supply concentration:Specialty stainless steel hinge rod production clusters in Chinese and Indian foundries, exposing European OEMs to tariff and logistics disruption risks.
- PFAS restriction uncertainty:Emerging European and North American bans on per- and polyfluoroalkyl substances threaten polymer formulations currently certified for food contact.
Strategic Opportunities
- India food processing expansion:Cold chain infrastructure buildout under PLI scheme incentives creates demand for corrosion-resistant modular conveying in dairy and ready-meal segments.
- Hybrid belt technology convergence:Polymer hygiene surfaces bonded to metal structural elements unlock chemical processing and battery component conveying applications previously closed to pure plastic designs.
- Direct OEM specification channels:Bypassing distributor networks to engineer belts into original bakery and protein equipment designs captures lifetime replacement revenue streams.
Industry Challenges
- ISO 22000 auditor certification timelines:Third-party food safety management system validation delays product launches for suppliers without pre-established certification infrastructure.
- Legacy flat-belt integration friction:Retrofitting modular systems into existing conveyor frames requires custom sprocket engineering and drive recalibration, extending sales cycles.
- Antimicrobial compound IP licensing:Proprietary additive formulations from chemical suppliers create royalty dependencies and supply exclusivity constraints for belt manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Belt Drive Market |
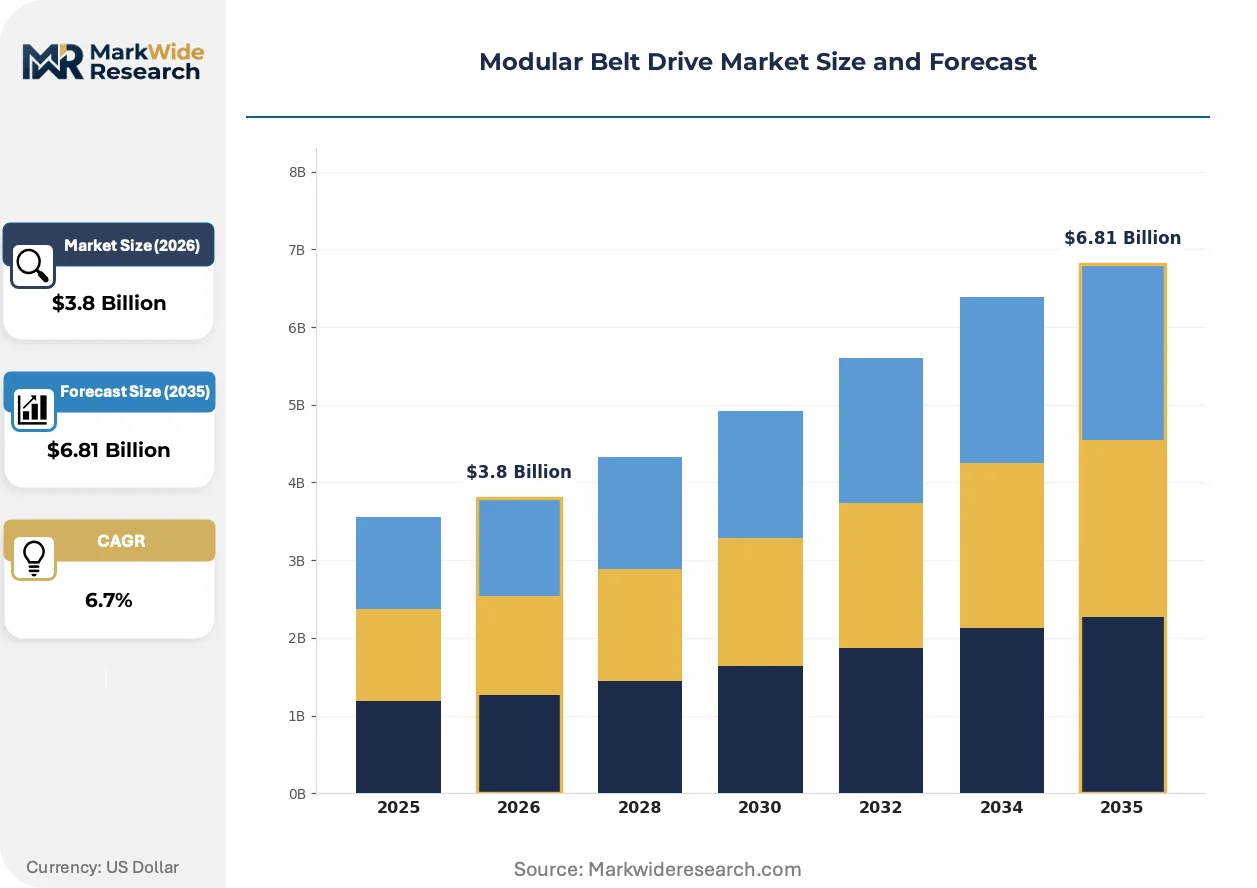
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Modular Belts, Steel Modular Belts, Hybrid Modular Belts, Specialty Modular Belts Surface Type: Non-Slip Surface, Smooth Surface, Textured Surface, Open Surface End User: Food Processing, Packaging, Material Handling, Textile Manufacturing Drive Mechanism: Electric Drive, Pneumatic Drive, Chain Drive, Gear Drive |
| Companies Covered | Martin Sprocket & Gear, Central Conveyor, ScanBelt, Habasit, Bode Belting GmbH, Intralox, ABB, Dunlop BTL, BEHA Belt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Belt Drive Market Emerging Trajectories
Active material science breakthroughs and regulatory disclosure mandates are fragmenting competitive positioning around hygiene performance verification rather than mechanical durability alone.
Hybrid modular belt architecture is decomposing the traditional plastic-versus-metal category boundary. Polymer surface layers deliver FDA-compliant food contact properties while stainless steel or aluminum structural cores handle abrasive loads and elevated temperatures. Bakery equipment OEMs in Germany and protein processors in Denmark specify these composite designs for clean-in-place cycles exceeding 80°C. The technology is decomposing procurement decisions into separate hygiene and mechanical performance specifications.
EU Green Deal carbon-footprint disclosure requirements and emerging CSRD scope 3 reporting obligations are mandating polymer supply chain documentation. Belt manufacturers must now quantify embodied carbon in raw resin and captive foundry energy consumption. German automotive suppliers and French dairy processors prioritize suppliers with verified lifecycle data, compressing qualification timelines for undocumented competitors.
Food processing buyers now unbundle after-sales service from initial equipment procurement. Maintenance departments contract directly with belt specialists for predictive replacement programs rather than relying on OEM service agreements. This pattern concentrates most visibly in Netherlands and Belgium, where large cooperatives operate integrated meat and dairy facilities with centralized engineering procurement functions.
Modular Belt Drive Market Segmentation
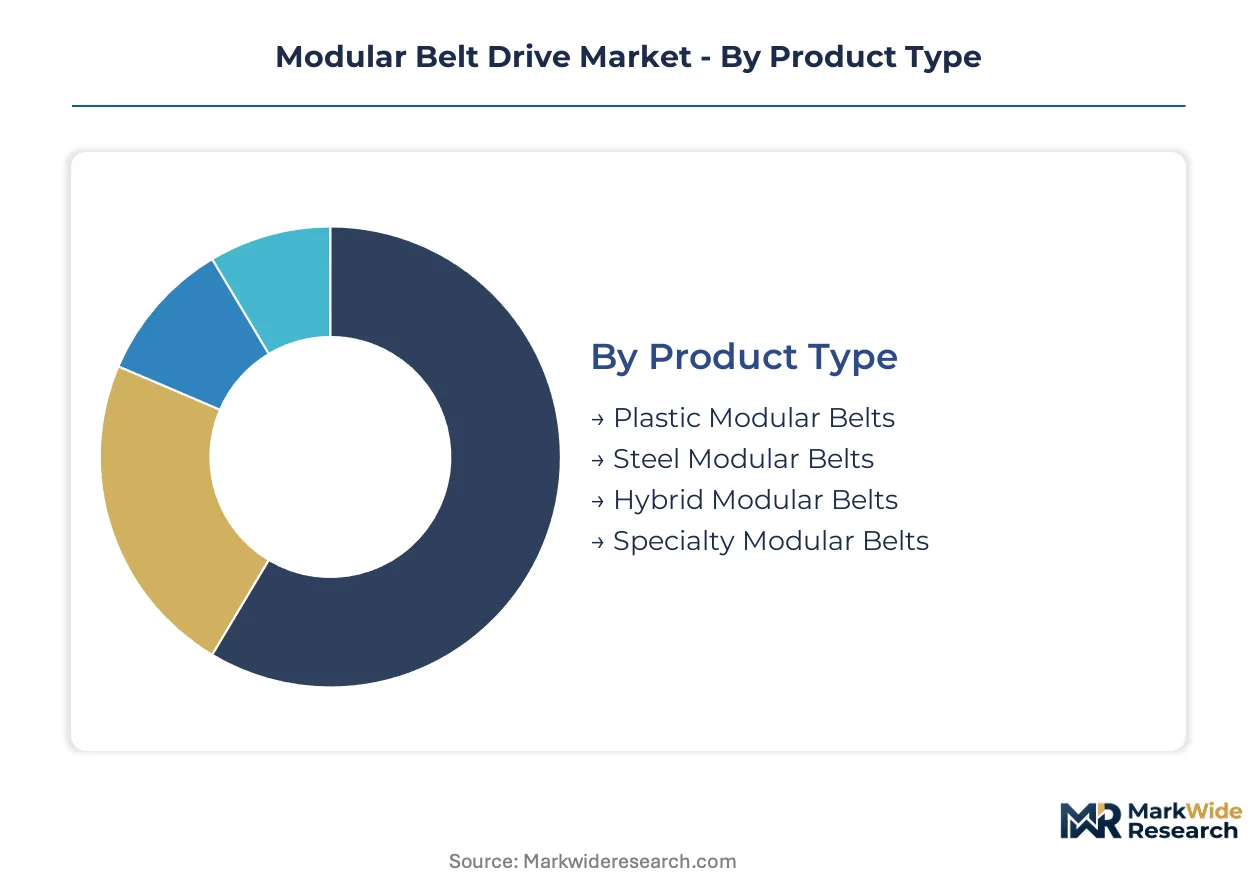
Modular belt drive procurement decisions fragment across material specifications, surface engineering, and drive mechanism compatibility. Each segmentation dimension carries distinct regulatory compliance burdens and total cost of ownership implications that reshape supplier qualification criteria.
Product Type:
FDA Food Contact Notification requirements and EU Machinery Directive surface specifications create divergent material certification pathways across polymer, metal, and composite constructions.
- Plastic Modular Belts:Engineered from acetal, polypropylene, or polyethylene segments with hinge rod interlocks. FDA-compliant formulations dominate North American meat and dairy installations where corrosion resistance and lightweight construction reduce motor sizing requirements. USDA equipment acceptance criteria dictate additive packages and surface finishes.
- Steel Modular Belts:Stainless steel or carbon steel segments with precision-machined hinge geometries withstand abrasive loads and temperatures exceeding 150°C. German automotive component manufacturers and textile processors specify these for extended service intervals under continuous operation. REACH compliance for surface coatings adds qualification complexity for European deployments.
- Hybrid Modular Belts:Polymer hygiene surfaces bonded to aluminum or stainless steel structural cores unlock chemical processing applications. Battery component conveying and pharmaceutical cleanrooms drive specification growth.
- Specialty Modular Belts:Custom-engineered segments with embedded sensors or magnetic properties serve automated sortation and quality control lines.
Plastic modular belts handle the majority of throughput across food processing installations; hybrid modular belts are the fastest mover on share as chemical and battery applications expand.
Surface Type:
Clean-in-place compatibility and biofilm resistance requirements concentrate demand in open and textured configurations that balance grip performance with drainage efficiency.
- Open Surface:Perforated or grid-pattern segments permit fluid drainage and air circulation through the belt plane. EU Machinery Directive mandates for clean-in-place accessibility elevate this specification to default status in European meat and dairy facilities. Bakery equipment OEMs specify open-hinge geometries to simplify sanitation validation.
- Textured Surface:Molded or machined patterns increase friction coefficients for inclined conveying and accumulation zones. Protein processors deploy these for raw poultry and fish lines where product stability intersects with washdown requirements.
- Smooth Surface:Flat segment faces minimize product marking and residue retention for packaged goods and baked items.
- Non-Slip Surface:Elastomer coatings or raised grip elements secure unstable loads on elevation changes and dynamic accumulation.
Open surface configurations dominate regulatory-compliant food processing procurement; textured surface demand is climbing the fastest as ready-meal assembly lines proliferate.
End User:
Industry-specific hygiene mandates and throughput requirements segment procurement patterns across continuous-flow operations and batch handling environments.
- Food Processing:Meat, poultry, dairy, and bakery facilities drive specification intensity through FDA, USDA, and EU Machinery Directive compliance obligations. Stainless steel and antimicrobial polymer formulations anchor procurement decisions.
- Material Handling:Distribution centers and parcel sortation facilities prioritize durability and speed over hygiene certification, expanding steel modular belt deployment.
- Packaging:Consumer goods and pharmaceutical lines balance cleanroom requirements with accumulation precision.
- Textile Manufacturing:High-temperature finishing and dyeing operations specify heat-resistant steel constructions with extended pitch dimensions.
Food processing commands the largest procurement volume; material handling is gaining share fastest as e-commerce fulfillment infrastructure expands.
Drive Mechanism:
Energy efficiency regulations and precision control requirements differentiate electric and mechanical drive specifications across application intensities.
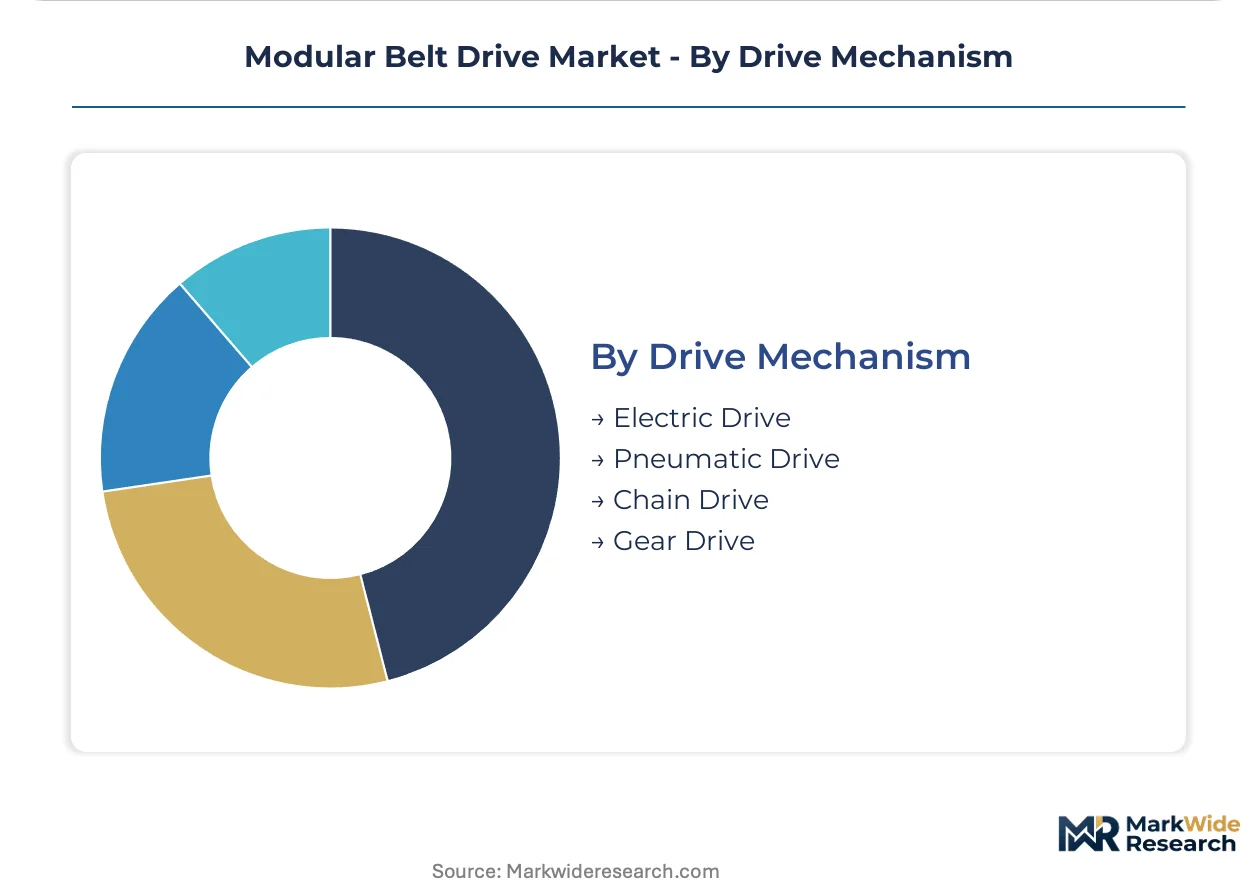
- Electric Drive:Servo and variable-frequency motor systems deliver precise speed control and regenerative braking for accumulation and sortation applications. German bakery equipment OEMs and Dutch dairy cooperatives specify these for synchronized line integration.
- Chain Drive:Roller chain and engineered chain systems transmit high torque in heavy-load material handling and textile manufacturing. Lower maintenance requirements under abrasive conditions sustain specification in steel-intensive segments.
- Gear Drive:Precision helical and bevel gearboxes handle high-starting-torque applications in inclined conveying and elevation changes.
- Pneumatic Drive:Compressed air systems serve explosion-sensitive environments and washdown-intensive protein processing lines where electrical enclosure costs escalate.
Electric drive systems anchor the majority of new installations; chain drive retains dominant share in retrofit and heavy-load extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty stainless steel hinge rod production clusters in Chinese and Indian foundries, exposing European OEMs to tariff and logistics disruption risks while German automotive suppliers anchor premium procurement.
Germany
Automotive component manufacturers and bakery equipment OEMs drive premium modular belt procurement with tight pitch tolerances. EU Machinery Directive 2006/42/EC mandates open-surface and clean-in-place compatibility, accelerating modular replacement of sealed flat-belt systems. The Baden-Württemberg industrial corridor concentrates precision conveying engineering for electric drivetrain assembly.
United States
Meat, poultry, and dairy facilities expand conveyor system upgrades to meet stricter hygiene mandates. FDA Food Contact Notification program and USDA equipment acceptance criteria dictate polymer formulations and surface finishes. Midwest protein processing clusters and California Central Valley dairy cooperatives concentrate antimicrobial belt specification demand.
India
Cold chain infrastructure buildout under PLI scheme incentives creates demand for corrosion-resistant modular conveying in dairy and ready-meal segments. FSSAI food safety standards and BIS certification requirements shape procurement qualification timelines. Maharashtra and Gujarat industrial zones anchor domestic fabrication capacity expansion for food processing OEM supply chains.
China
Battery component conveying and pharmaceutical cleanroom applications drive hybrid modular belt specification growth. NMPA pharmaceutical equipment standards and GB standards for food machinery dictate surface finish and material compliance requirements. Yangtze River Delta manufacturing clusters concentrate specialty stainless steel hinge rod foundry capacity serving global OEM procurement.
Netherlands
Large cooperatives operate integrated meat and dairy facilities with centralized engineering procurement functions. EU Green Deal carbon-footprint disclosure requirements mandate polymer supply chain documentation from belt manufacturers. Rotterdam port logistics and Eindhoven food technology clusters concentrate predictive replacement program contracting between maintenance departments and belt specialists.
Modular Belt Drive Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized belting fabricators competing across hygiene certification tiers. The vendor base spans captive foundry operators with rapid custom sprocket turnaround, antimicrobial compound integrators, and hybrid technology developers blending polymer surfaces with metal structural cores. Strategic moves center on direct OEM specification channel development and backward integration into polymer compounding to secure food-grade additive supply chains.
Among European-based fabricators, Habasit AG and Bode Belting GmbH exemplify the hygiene-specialist archetype through antimicrobial compound integration and open-hinge geometries. Martin Sprocket & Gear represents the North American distribution-dominant model with captive foundry capacity. Intralox occupies a position on the premium-application vector, positioning ThermoDrive and Activated Roller Belt platforms for protein processing and ready-meal assembly where cleanability standards intensify.
| Leading Market Players |
|---|
| Martin Sprocket & Gear |
| Central Conveyor |
| ScanBelt |
| Habasit |
| Bode Belting GmbH |
| Intralox |
| ABB |
| Dunlop BTL |
| BEHA Belt |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day hinge rod lead times from Asian foundries concentrate procurement leverage among buyers with forward-contracted inventory positions, compressing spot-market pricing power for European OEMs facing EU Machinery Directive compliance deadlines. This inventory-to-pricing linkage intensifies margin pressure on fabricators without captive foundry capacity or polymer compounding backward integration.
Pricing Analysis
EU Machinery Directive 2006/42/EC dictates the pricing tier structure across European installations, separating FDA Food Contact Notification-certified premium grades from standard economy specifications. Three-tier pricing structure across premium, standard, and economy levels reflects antimicrobial compound integration and clean-in-place validation depth. Cost compression in standard-grade plastic modular belts is intensifying because engineering-grade thermoplastic resin prices fluctuate with crude oil derivatives. Small-to-mid-sized bakery equipment OEMs exhibit highest price sensitivity, while German automotive component manufacturers absorb premium tiers for tight-tolerance electric drivetrain conveying.
Supply Chain Analysis
China and India anchor specialty stainless steel hinge rod foundry capacity serving global OEM procurement, with Yangtze River Delta and Maharashtra-Gujarat industrial zones concentrating production. Engineering-grade thermoplastic resins draw from petrochemical feedstocks in the Middle East and Southeast Asia, while antimicrobial additive formulations rest on licensed IP from European and North American chemical suppliers. Single-source vulnerability in Chinese foundry concentration exposes European fabricators to tariff and logistics disruption risks. Distribution runs through captive OEM specification channels and authorized distributor networks, with direct engineering procurement gaining share among Netherlands dairy cooperatives and German automotive suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular belt drive adoption sits in early-cycle expansion as food processing facilities unwind legacy flat-belt specifications under intensifying hygiene mandates. Hybrid technology convergence and direct OEM channel development represent underexploited penetration vectors with multi-year runway.
For Market Incumbents: Shield margin position by deepening backward integration into polymer compounding to secure food-grade additive supply chains against proprietary IP licensing constraints. Expand captive foundry capacity in Eastern European or North American locations to offset Chinese hinge rod concentration risk. Prioritize ISO 22000 auditor certification infrastructure to compress product launch timelines against competitors with pre-established validation frameworks.
For New Entrants and Emerging Players: Differentiate on carbon-footprint disclosure capabilities to capture EU Green Deal and CSRD scope 3 reporting obligations mandating polymer supply chain documentation. Target India cold chain infrastructure buildout under PLI scheme incentives, where corrosion-resistant modular conveying demand outpaces domestic fabrication capacity. Pursue predictive replacement program contracting directly with maintenance departments of Netherlands and Belgium dairy cooperatives, bypassing entrenched OEM service agreements.
For Investors and Strategic Acquirers: Long-term, this sits as a hygiene-certification compounder play because regulatory disclosure mandates fragment competitive positioning around verification capabilities rather than mechanical durability alone. Acquisition targets should display antimicrobial compound integration expertise plus open-hinge geometry engineering validated under USDA equipment acceptance criteria. Monitor PFAS restriction implementation timelines as inflection indicator for polymer formulation obsolescence risk and replacement technology valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Secures food-grade additive supply chains against proprietary licensing constraints from chemical suppliers. |
| Hybrid Belt Technology Development | Unlocks battery component conveying and pharmaceutical cleanroom applications previously closed to pure plastic designs. |
| Direct OEM Specification Channel Development | Captures lifetime replacement revenue streams by engineering belts into original bakery and protein equipment designs. |
| Predictive Replacement Program Contracting | Concentrates service revenue from Netherlands and Belgium dairy cooperative maintenance departments bypassing OEM agreements. |
| Carbon-Footprint Disclosure Infrastructure | Compresses qualification timelines for German automotive suppliers prioritizing verified lifecycle data under EU Green Deal mandates. |
Methodological Framework
A standing panel of plant engineers, OEM procurement teams, aftermarket service heads, and food safety compliance officers provided ongoing calibration across primary fieldwork, supplemented by customs and trade data, SEC filings, EU Machinery Directive implementation records, and FDA Food Contact Notification databases. Bottom-up volume builds from segment-level installation data triangulated against top-down macroeconomic indicators and industrial production indices.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation modeling across material type, surface engineering, end-use industry, and drive mechanism compatibility. CAGRs were derived from fitted growth curves incorporating regulatory compliance timeline assumptions, cold chain infrastructure investment flows, and automotive component conveying precision requirements.
The analysis sits within stated boundaries; outcomes outside sustained hygiene mandate intensification, polymer feedstock price stability, or PFAS restriction implementation would require recalibration. Forecasts reflect documented assumptions regarding EU Machinery Directive enforcement consistency and PLI scheme incentive continuity. Recalibration cycles align with material shifts in antimicrobial compound regulatory status and carbon-footprint disclosure mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Gear Oil Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Global Automotive Engine Cover Market
Powertrain
Turbocharger Actuators Market
Powertrain
Transmission Sales Market
Powertrain
Global Automotive Tappet Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Variable Displacement Compressor Market
Powertrain
Automotive Turbocharger Market
Powertrain
Global Automotive Pumps Market
Powertrain
Clutch Friction Plate Market
Powertrain
Clutch Market
Powertrain
Turbocharger Market
Powertrain
Natural Gas Engines Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
Electric Vehicle Powertrain Market