
 Global Automotive Cross Car Beam Market | 2026-2036
Global Automotive Cross Car Beam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Cross Car Beam Market Analysis
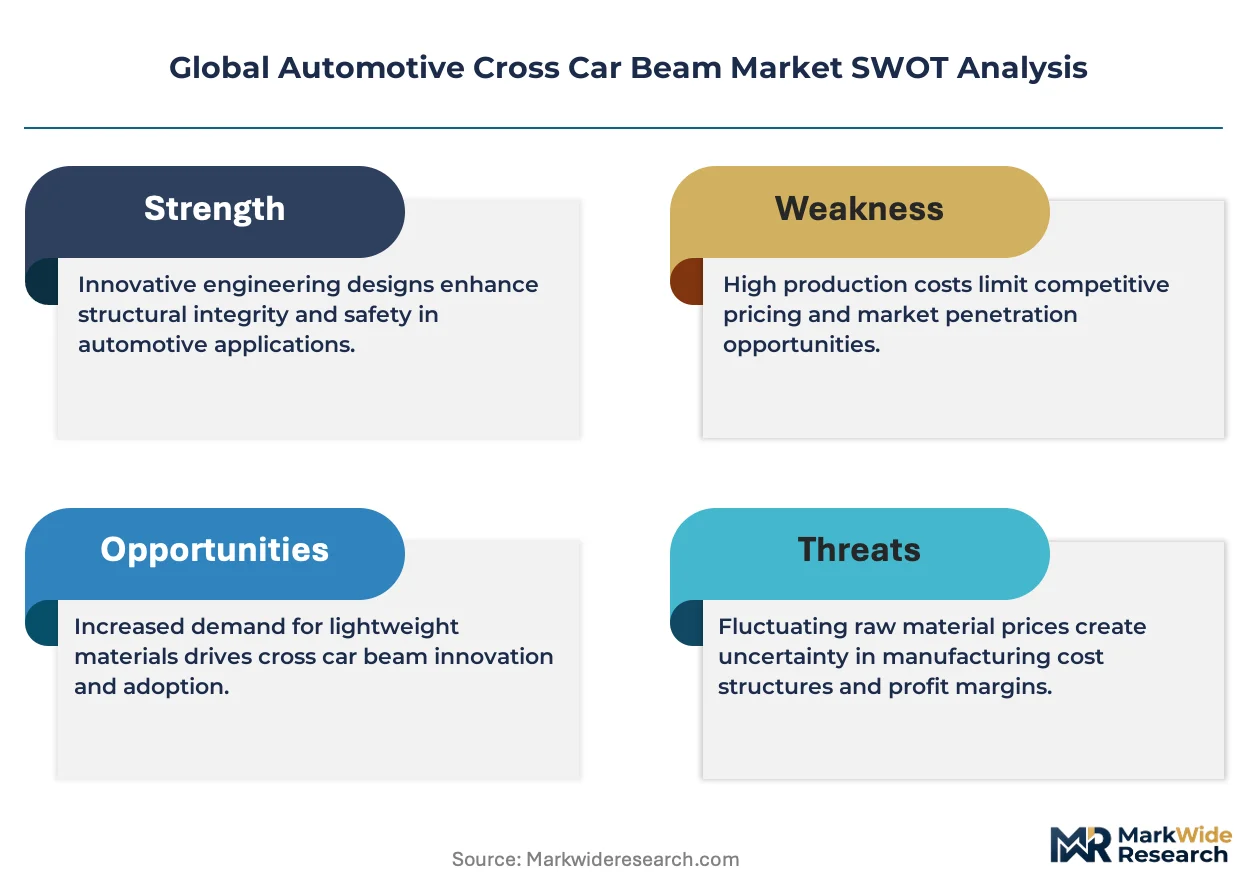
High-pressure aluminum die-casting and hot-stamped steel hybridization is reconfiguring cross car beam manufacturing economics across passenger vehicle architectures. Gestamp sustains extensive R&D programs in multi-material joining technologies for cockpit structural modules. Magna International anchors North American production capacity through vertically integrated stamping and assembly operations. KIRCHHOFF Automotive specializes in tailored cross car beam solutions for premium SUV platforms requiring enhanced torsional rigidity.
An automotive cross car beam is a transverse structural member spanning the vehicle width below the instrument panel, typically fabricated from stamped steel, extruded aluminum, or fiber-reinforced polymer matrices with wall thicknesses of 1.2-3.5 mm depending on load path requirements. This component integrates steering column support, HVAC ducting, and airbag deployment anchorage while maintaining occupant compartment integrity during frontal offset collisions. Metal segments retain dominant share in mass-market ICE vehicles where cost-per-kilogram metrics favor established stamping supply chains. Composite applications represent the fastest-expanding category as electric vehicle OEMs pursue 15-25% mass reduction in cockpit modules to offset battery pack weight penalties. Hybrid material configurations capture concentrated margin pools where aluminum-to-steel joining patents create supplier differentiation.
The EPA's Corporate Average Fuel Economy standards and NHTSA crashworthiness mandates jointly compel material lightweighting without compromising structural performance metrics. EMA's MDR-aligned expectations for automotive polymer traceability and China's GB standards for passenger vehicle frontal impact resistance create multi-jurisdictional compliance complexity for beam suppliers. Japan's METI circular economy guidelines and South Korea's MFDS material certification protocols add further regulatory layering for cross-border component sourcing. Stakeholders must monitor evolving battery-electric vehicle platform architectures where skateboard chassis designs redistribute structural loads away from traditional cross car beam mounting points.
Market Dynamics
Electric vehicle platform architectures are redistributing structural load paths away from traditional cockpit mounting points, forcing cross car beam suppliers to reengineer attachment geometries and material specifications for skateboard chassis integration.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Stringent fleet efficiency mandates compel OEMs to pursue 15-25% mass reduction in cockpit modules, accelerating aluminum and composite substitution for stamped steel cross car beams.
- Hot-stamped steel hybridization:Advanced joining techniques enable tailored strength-to-weight ratios that satisfy NHTSA frontal offset collision requirements while trimming kilograms from instrument panel support structures.
- Germany's cockpit engineering concentration:BMW, Volkswagen, and Mercedes-Benz maintain advanced R&D centers in Stuttgart, Munich, and Wolfsburg that drive specification upgrades across premium and mass-market vehicle platforms.
Market Restraints
- Aluminum ingot price volatility:Primary aluminum input costs fluctuate with LME trading patterns and Chinese smelter output decisions, compressing margins for die-cast cross car beam suppliers locked into annual OEM pricing agreements.
- REACH compliance complexity:ECHA substance restrictions on certain polymer additives and surface treatments force reformulation of fiber-reinforced composite matrices, extending qualification timelines by 18-24 months.
- Steel stamping supply chain concentration:Established tier-one metal formers in the US Midwest and Germany's Ruhr region control capacity for high-volume ICE platforms, creating entry barriers for alternative material specialists.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced manufacturing equipment enable greenfield aluminum die-casting facilities serving domestic EV platforms and export markets.
- Multi-material joining patents:Proprietary friction-stir welding and adhesive-bonding IP creates differentiation in hybrid aluminum-steel configurations where torsional rigidity requirements exceed single-material performance limits.
- Japan's METI circular economy guidelines:Design-for-recycling mandates favor thermoplastic composite matrices that enable closed-loop material recovery, positioning early adopters for preferred supplier status with Japanese OEMs.
Industry Challenges
- Multi-jurisdictional certification timelines:Simultaneous homologation against EPA fuel economy protocols, NHTSA crashworthiness mandates, and China's GB frontal impact standards strains engineering bandwidth and delays program launches.
- Skateboard chassis load path reconfiguration:Battery-electric platforms concentrate structural rigidity in the floor pan, requiring cross car beam suppliers to redesign attachment interfaces and validate new crash energy management strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Cross Car Beam Market |
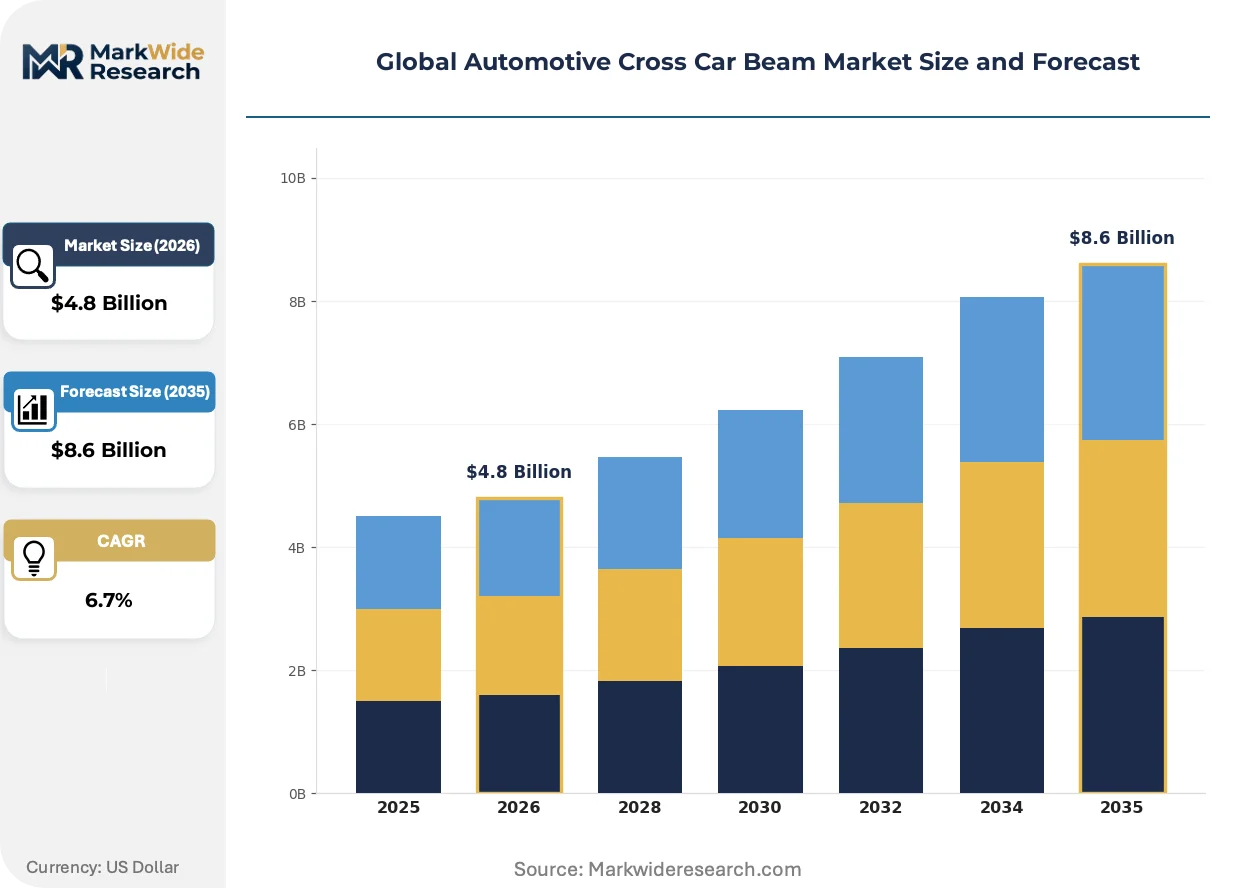
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Plastic, Composite, Hybrid End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Material: Aluminum, Steel, Carbon Fiber, Glass Fiber Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, SUVs |
| Companies Covered | Benteler Automotive, CIE Automotive, Dura-Shiloh, Elringklinger AG, Faurecia, Gestamp, KIRCHHOFF Automotive, Magna International, GF Casting Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Cross Car Beam Market Emerging Trajectories
Material science advances and regulatory pressure are converging to compress traditional manufacturing paradigms, with suppliers racing to deploy novel joining techniques and recyclable polymer formulations before qualification windows close on next-generation vehicle programs.
Continuous fiber-reinforced thermoplastic composites are collapsing the cost-performance gap with metal alternatives in electric vehicle cockpit modules. BMW and Mercedes-Benz specification engineers have accelerated composite validation programs from 36-month to 18-month cycles. This compression is enabling tier-two suppliers to bypass traditional steel stamping incumbents in platform sourcing decisions.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon blowing agents used in polyurethane structural foams, forcing beam suppliers to qualify CO2-based or hydrocarbon alternatives. ECHA enforcement of restricted substance lists in polymer matrices adds parallel compliance layers. Premium SUV platforms in Germany and Austria face the tightest reformulation deadlines as 2027 model year homologation gates approach.
Buyer concentration among battery-electric vehicle specialists is shortening supplier qualification cycles and compressing pricing negotiations. Start-up OEMs in California and Shanghai are bypassing traditional tier-one distributors to contract directly with composite material compounders and aluminum extruders. This disintermediation is most visible in China, where NIO and XPeng maintain captive engineering teams that specify cross car beam geometries without legacy supplier intermediation.
Global Automotive Cross Car Beam Market Segmentation
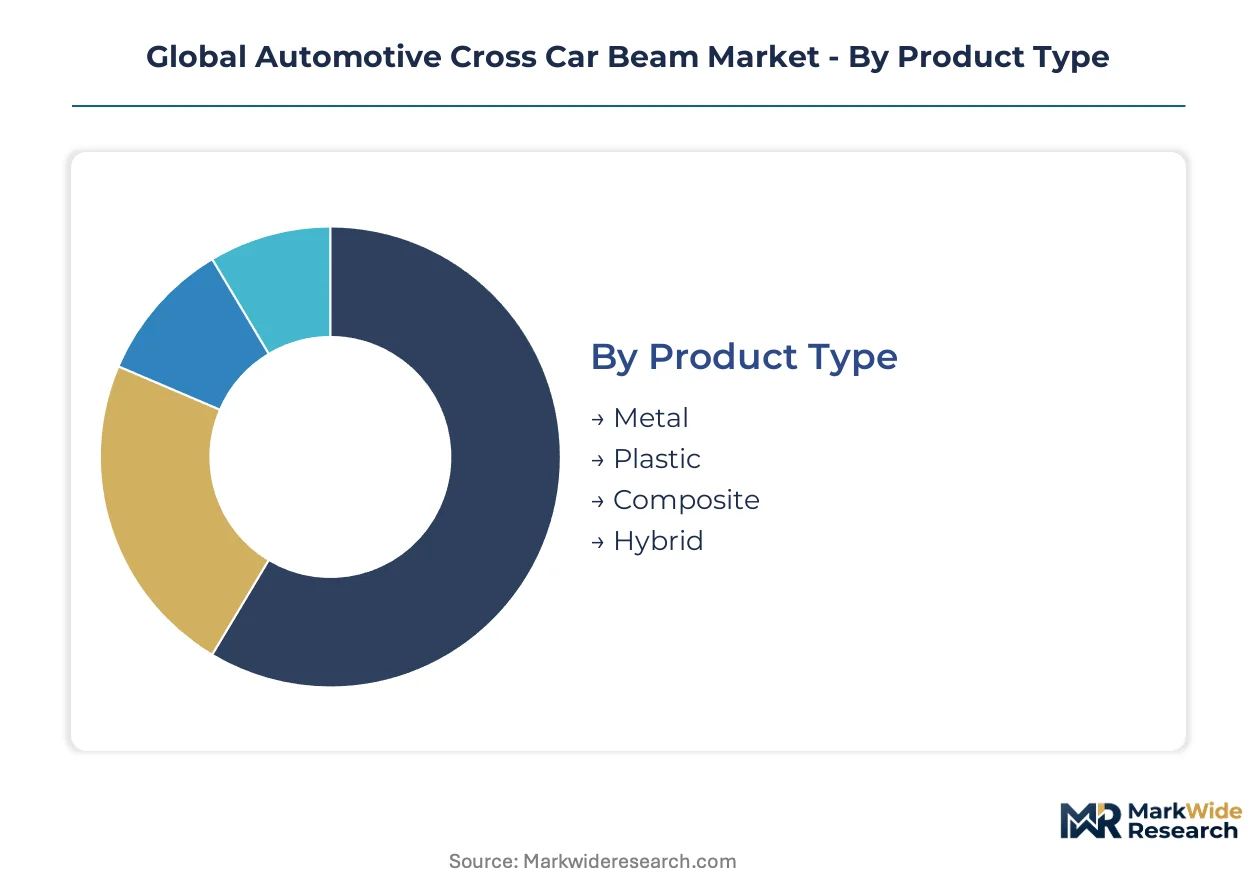
Cross car beam procurement cycles vary dramatically by material chemistry and platform type, with composite formulations refreshing every 18-24 months while steel architectures persist across multiple vehicle generations. Understanding these velocity differentials helps suppliers align capacity investments with actual revenue conversion timelines.
Product Type:
Cycle times compress from 48 months for stamped steel to 18 months for thermoplastic composites as OEM validation protocols adapt to electric vehicle development cadences.
- Metal:Stamped steel and extruded aluminum configurations retain dominance in mass-market internal combustion platforms where die tooling amortizes across million-unit programs. Demand concentrates in Germany's Ruhr region and the US Midwest, where tier-one metal formers maintain captive relationships with Volkswagen and Ford.
- Composite:Continuous fiber-reinforced thermoplastic matrices enable 15-25% mass reduction in electric vehicle cockpit modules, with BMW and Mercedes-Benz accelerating qualification cycles. Expansion concentrates in Stuttgart and Munich engineering centers pursuing range optimization.
- Plastic:Short-fiber reinforced polymer beams serve cost-sensitive compact segments in India and Brazil where BIS and ANVISA compliance costs favor established injection molding supply chains.
- Hybrid:Aluminum-to-steel joining configurations capture premium SUV platforms requiring tailored strength-to-weight ratios beyond single-material limits.
Metal dominates installed base. Composite is where expansion concentrates.
End User:
Procurement authority is shifting from traditional tier-one distributors to captive OEM engineering teams, particularly among battery-electric specialists.
- OEMs:BMW, Volkswagen, and Mercedes-Benz maintain direct specification control over cross car beam geometries, with Stuttgart and Wolfsburg engineering centers driving material upgrades across premium and volume platforms.
- Tier-1 Suppliers:Gestamp and Magna International anchor production capacity through vertically integrated stamping and assembly operations serving multiple OEM programs simultaneously.
- Vehicle Assemblers:Contract manufacturers in emerging markets source standardized beam configurations through consolidated procurement frameworks.
- Aftermarket Providers:Collision repair channels in the US and Germany stock replacement cross car beams for legacy platforms outside warranty coverage.
OEM direct sourcing commands premium pricing. Tier-1 intermediation retains volume concentration.
Material:
Input cost volatility and regulatory compliance burden create divergent margin profiles across metallic and non-metallic alternatives.
- Steel:Hot-stamped boron alloys satisfy NHTSA frontal offset requirements at lowest per-kilogram cost, with demand anchored in high-volume pickup and SUV platforms assembled in Michigan and Tennessee.
- Aluminum:High-pressure die-casting enables complex integration of HVAC ducting and steering column mounts, though LME price fluctuations compress margins for suppliers locked into annual OEM agreements.
- Carbon Fiber:Aerospace-grade precursors remain cost-prohibitive for mass-market applications, limiting deployment to low-volume performance variants.
- Glass Fiber:E-glass and S-glass reinforcements in thermoplastic matrices offer intermediate cost-performance positioning for electric vehicle programs in China and South Korea.
Steel retains volume leadership. Aluminum is climbing the fastest.
Application:
Platform electrification is redistributing structural load paths and reshaping beam specification priorities across vehicle categories.
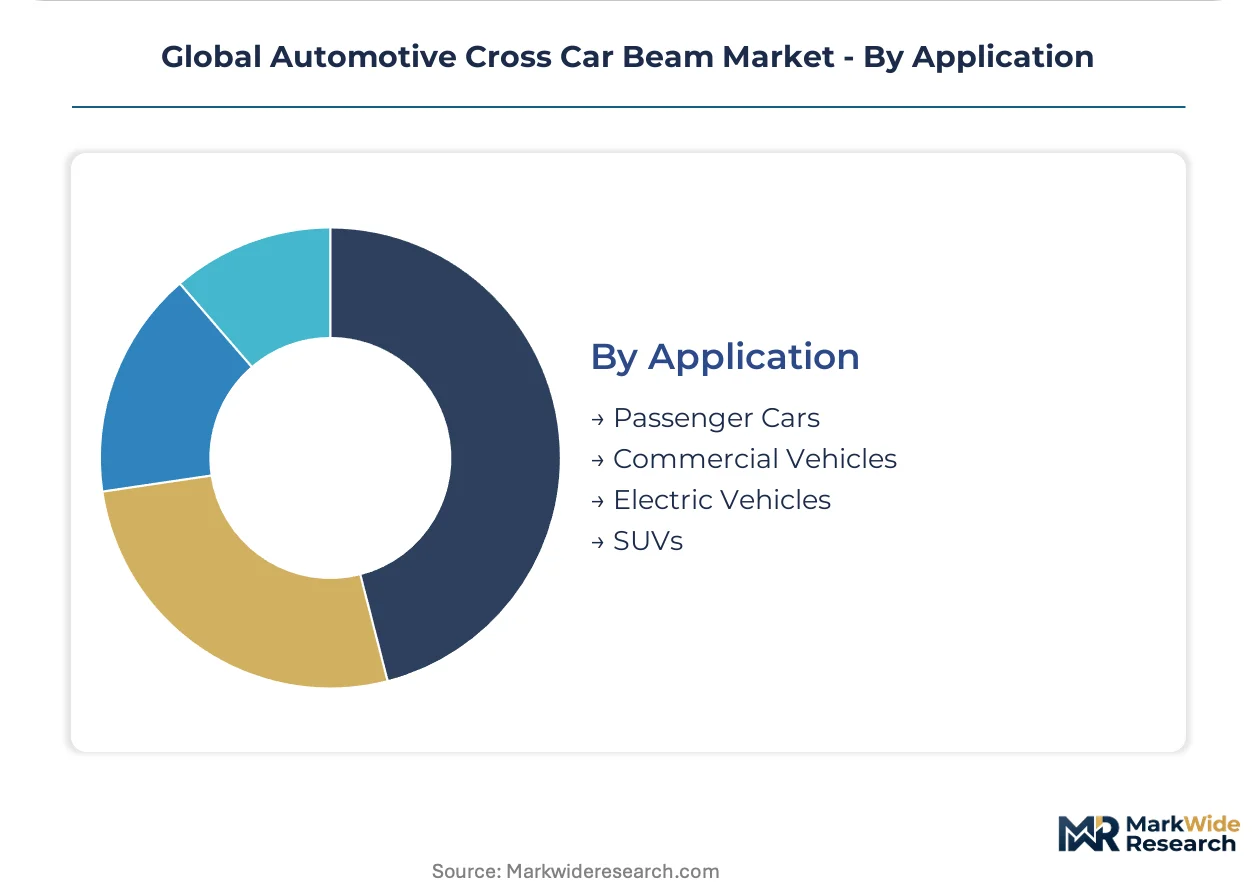
- Electric Vehicles:Skateboard chassis architectures concentrate rigidity in the floor pan, forcing cross car beam redesign for attachment interface compatibility with battery pack enclosures. NIO and XPeng engineering teams in Shanghai specify geometries without legacy supplier intermediation.
- SUVs:Premium platforms from BMW and Mercedes-Benz demand enhanced torsional rigidity for off-road capability, driving hybrid material adoption in Germany and Austria.
- Passenger Cars:Compact and mid-size segments in India and Brazil prioritize cost minimization through standardized steel stamping configurations.
- Commercial Vehicles:Heavy-duty truck cabins require reinforced cross car beams for regulatory compliance with NHTSA and UN ECE crashworthiness mandates.
Passenger cars anchor current volume. Electric vehicles show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross car beam trade flows favor established manufacturing clusters with captive OEM relationships. Germany and China run structural surpluses in high-value aluminum and composite configurations. The United States and Japan balance imports of specialized geometries against domestic stamping capacity for mass-market platforms.
Germany
BMW, Volkswagen, and Mercedes-Benz engineering centers in Stuttgart, Munich, and Wolfsburg drive specification upgrades for aluminum and hybrid material beams. REACH compliance and ECHA substance restrictions force polymer matrix reformulation timelines. The Ruhr region retains dense concentrations of tier-one metal formers serving Volkswagen Group volume programs.
China
NIO and XPeng engineering teams in Shanghai specify cross car beam geometries directly without legacy supplier intermediation. GB standards for passenger vehicle frontal impact resistance create homologation complexity for foreign suppliers. The Yangtze River Delta clusters aluminum die-casting capacity serving domestic EV platforms and export markets.
United States
Ford and General Motors pickup and SUV platforms anchor demand for hot-stamped steel configurations. NHTSA crashworthiness mandates and EPA fuel economy standards jointly compel lightweighting investments. Michigan and Tennessee host vertically integrated stamping operations with captive relationships to Detroit OEMs.
Japan
Toyota and Honda maintain conservative material specifications for mass-market hybrid platforms. METI circular economy guidelines favor thermoplastic composite matrices enabling closed-loop material recovery. Nagoya and Tokyo engineering centers concentrate R&D for design-for-recycling protocols.
India
Maruti Suzuki and Tata Motors domestic EV platforms drive aluminum die-casting demand. PLI scheme production-linked incentives enable greenfield advanced manufacturing facilities. Maharashtra and Gujarat clusters attract component suppliers targeting export markets and local OEM programs.
Global Automotive Cross Car Beam Market Vendor Landscape
On the supply side, the industry is tiered between consolidated metal stamping incumbents and emerging composite specialists. Steel and aluminum fabricators leverage amortized die tooling across million-unit ICE programs. Composite entrants exploit shortened EV qualification cycles to bypass traditional distribution channels. Dominant competitive moves include capacity expansion in low-cost manufacturing zones and strategic partnerships for multi-material joining IP.
Among European-based structural component specialists, Benteler Automotive, Gestamp, and Elringklinger AG exemplify the tier-one metal forming archetype with extensive R&D footprints. These entities occupy positions where proprietary joining technologies and captive OEM relationships create defensive moats against material substitution pressures.
| Leading Market Players |
|---|
| Benteler Automotive |
| CIE Automotive |
| Dura-Shiloh |
| Elringklinger AG |
| Faurecia |
| Gestamp |
| KIRCHHOFF Automotive |
| Magna International |
| GF Casting Solutions |
| Others |
Supply Flow & Price Mechanics
The Ruhr region's dense concentration of tier-one metal formers serving Volkswagen Group volume programs creates asymmetric pricing power against downstream OEM buyers. Annual contract negotiations lock die-cast aluminum suppliers into fixed pricing while LME volatility erodes margins, forcing material substitution decisions upstream.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that span multi-year vehicle programs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under NHTSA and GB standards, with volume scale discounts compressing per-unit economics for mass-market ICE platforms. Cost compression in aluminum die-casting tiers is intensifying because Chinese smelter output decisions drive ingot price volatility. Tier-one suppliers with captive OEM relationships exhibit lowest price sensitivity; emerging EV specialists demonstrate highest sensitivity to per-kilogram premiums.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for cross car beam suppliers with trans-Pacific component flows. Manufacturing gravity centers on Germany, China, and Mexico, with primary aluminum drawing from Chinese smelters and hot-stamped steel resting on Ruhr basin capacity. Single-source vulnerability concentrates in high-pressure die-casting equipment where European and Japanese machinery makers control installation lead times. Distribution runs through vertically integrated tier-one assemblers maintaining captive relationships with BMW, Ford, and Volkswagen engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority consolidation among battery-electric vehicle specialists is shifting buyer power toward captive OEM engineering teams, fragmenting traditional tier-one distributor intermediation.
For Market Incumbents: Insulate margin position through backward integration into aluminum extrusion capacity and proprietary friction-stir welding IP for hybrid material configurations. Composite substitution threats from thermoplastic specialists require accelerated R&D in multi-material joining protocols. Certification investment under REACH and ECHA substance restrictions creates defensive moats against reformulation-capable entrants. For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI-enabled greenfield die-casting facilities serving Tata Motors and Mahindra domestic EV platforms. Shanghai-based NIO and XPeng engineering teams represent the most penetrable buyer segment given their disintermediation of legacy supplier channels. Direct material compounder relationships bypass tier-one markups and compress qualification cycles. For Investors and Strategic Acquirers: Long-term, this sits as a material-transition play because regulatory tailwinds under EPA fuel economy standards and Europe's F-Gas Regulation are structurally displacing stamped steel architectures. Acquisition targets should display proprietary joining patents and qualified composite matrices under shortened EV validation protocols. The signal to watch is OEM platform engineering headcount redistribution toward skateboard chassis integration teams.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Joining Patent Portfolio | Proprietary friction-stir welding IP creates differentiation in hybrid aluminum-steel configurations for BMW and Mercedes-Benz platforms. |
| India PLI Manufacturing Footprint | Greenfield aluminum die-casting capacity in Maharashtra and Gujarat captures domestic EV demand and export market access. |
| REACH-Compliant Composite Formulation | Thermoplastic matrix qualification under ECHA substance restrictions opens preferred supplier status with European OEMs. |
| Skateboard Chassis Interface Redesign | Attachment geometry reengineering for battery pack compatibility addresses NIO and XPeng specification requirements. |
| Circular Economy Material Recovery | Design-for-recycling protocols under Japan's METI guidelines position suppliers for closed-loop thermoplastic recovery with Toyota. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, and aftermarket distributors; and secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs/trade records. Bottom-up and top-down triangulation cross-referenced component-level bill-of-materials analysis with aggregate regional production forecasts.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions across the analysis window. CAGRs derive from modeled adoption curves for aluminum and composite substitution against stamped steel baselines, with battery-electric platform penetration and regulatory compliance timelines as primary demand drivers.
Macroeconomic conditions sit as an overlay; deviation in aluminum LME pricing, Chinese smelter output, or EPA enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on platform launch timing and material qualification success rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Global 3D Printing Automotive Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
Automotive Frame Machine Market