
 Robotic Welding for Automotive Manufacturing Market | 2026-2036
Robotic Welding for Automotive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Welding for Automotive Manufacturing Market Analytics
Modular welding cell packages is pivoting buyer choice away from standalone robot purchases toward integrated turnkey systems that bundle robotic arms, power sources, and control software. FANUC Corporation leverages its captive servo motor production to anchor pricing power across Asia-Pacific installations. Lincoln Electric sustains differentiation through deep wire-feed expertise that extends into automated torch management. KUKA AG competes by dominating European OEM body shop retrofits with heavy-payload articulated arms.
Robotic welding for automotive manufacturing deploys programmable multi-axis manipulators to execute fusion joints on stamped steel, aluminum, and alloy components with repeatability tolerances below 0.1 millimeter. The primary industrial purpose centers on achieving cycle-time compression and weld consistency across high-volume vehicle assembly lines. Arc welding technology leads installed base volumes due to its versatility across material thickness ranges, while laser welding commands premium positioning in aluminum-intensive electric vehicle architectures where heat-affected zone minimization protects battery tray integrity. Control systems represent the fastest-growing margin pool as software-defined path optimization and real-time seam tracking displace hardware-centric legacy architectures.
FDA oversight of factory safety systems intersects with OSHA lockout-tagout mandates and EPA air quality standards for welding fume capture in US automotive plants. The EU Machinery Directive and CE marking requirements enforce functional safety ratings on collaborative robot deployments in European assembly operations. Stakeholders must monitor how evolving ISO 10218 safety standards reshape robot-human collaboration protocols and determine capital allocation between greenfield installations and brownfield retrofits.
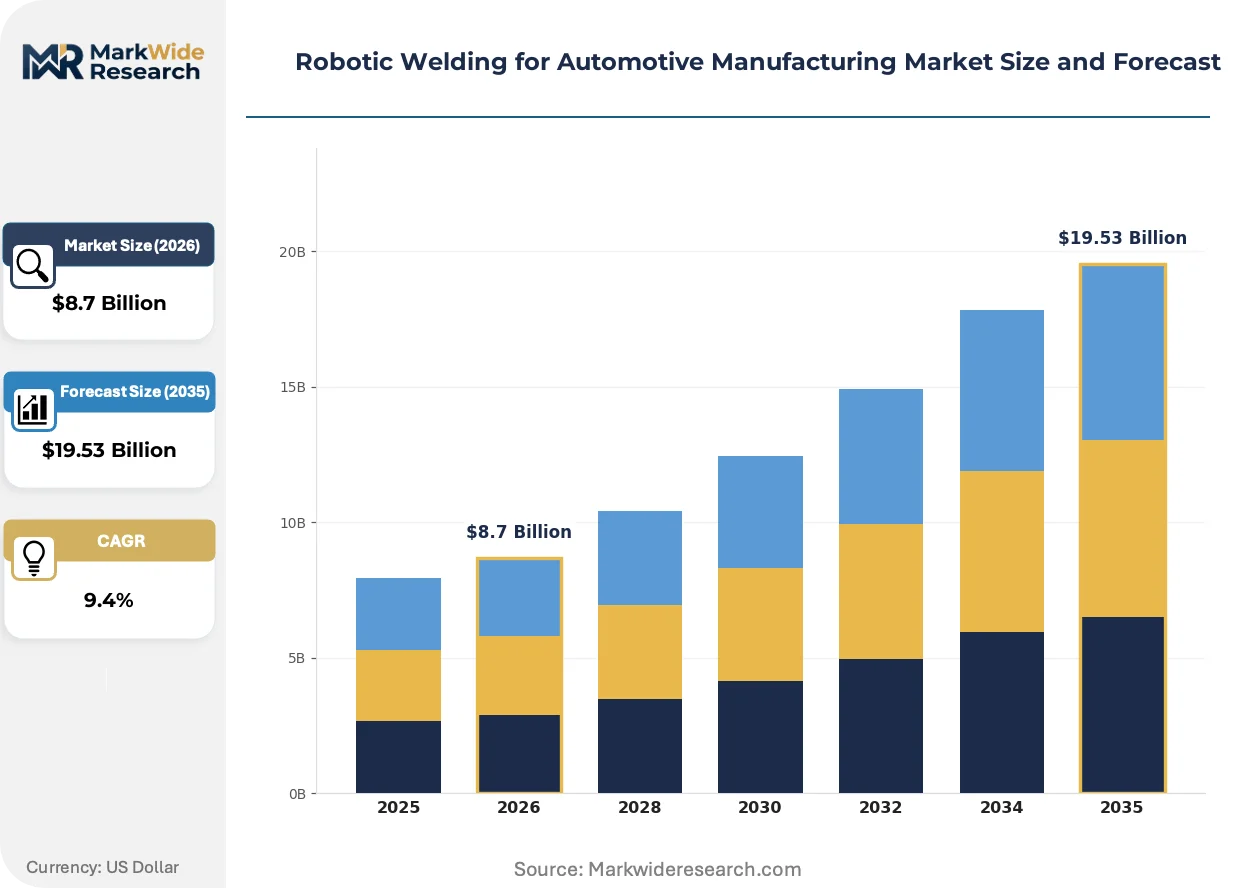
Market Dynamics
Electric vehicle platform architectures are forcing wholesale reconfiguration of body shop layouts, as aluminum-intensive battery tray assemblies demand laser welding precision that obsolete spot-welding infrastructures cannot deliver. Tier-1 suppliers face capital allocation decisions between retrofitting legacy lines and greenfield installations optimized for multi-material joining.
Growth Catalysts
- EU Green Deal emissions benchmarks:Manufacturers must replace energy-intensive resistance welding with arc and laser alternatives to meet carbon intensity targets for automotive production.
- Aluminum alloy adoption:Battery enclosure designs in electric vehicles require heat-affected zone minimization that only fiber laser systems can achieve at production scale.
- Stuttgart-Toyota-Detroit production clusters:Dense robot deployment in these three manufacturing hubs creates demonstration effects that accelerate adoption among neighboring Tier-2 suppliers.
Market Restraints
- Copper and rare-earth magnet cost volatility:Servo motor and power cable input costs fluctuate with commodity cycles, compressing margins for system integrators locked into fixed-price contracts.
- Japanese-German controller duopoly:Motion control hardware concentrates in two supplier geographies, creating single-source vulnerability for North American retrofit projects.
- ISO 10218-2 collaborative safety certification:Extended validation timelines for human-robot interaction protocols delay deployment in mixed-model assembly environments.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle production create first-mover advantage for turnkey welding cell providers establishing local integration capabilities.
- Wire-arc additive repair:Converging robotic deposition technology with end-of-line defect correction opens service revenue streams beyond original equipment installation.
- OSHA silica fume mandates:Stricter exposure limits in US plants force replacement of unenclosed manual stations, expanding addressable market for automated fume-capture cells.
Industry Challenges
- Multi-axis programming proficiency:Shortage of technicians capable of offline path simulation and seam tracking calibration extends commissioning timelines.
- Legacy PLC integration:Proprietary fieldbus protocols in 1990s-era body shops resist seamless handshaking with modern Ethernet-based robot controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Welding for Automotive Manufacturing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arms, Welding Machines, Control Systems, Accessories Technology: Arc Welding, Spot Welding, Laser Welding, Electron Beam Welding Application: Body Assembly, Chassis Manufacturing, Component Joining, Repair Services End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | ABB, Universal Robots, FANUC Corporation, ESAB Welding & Cutting Products, Lincoln Electric, YASKAWA Electric Corporation, Kawasaki Heavy Industries, Robert Bosch GmbH, KUKA AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Welding for Automotive Manufacturing Market Evolving Landscape
Software-defined control architectures are displacing hardware-centric legacy systems across welding automation, compressing reprogramming cycles and enabling real-time quality feedback loops that static mechanical fixtures cannot match.
Machine vision seam tracking is converging with adaptive torch positioning to eliminate manual teach-point programming. Battery tray manufacturers in Germany and China are adopting these systems at accelerated pace. The technology is converging with cloud-based weld parameter libraries that standardize quality signatures across distributed production networks.
REACH substance restrictions on hexavalent chromium plating are forcing conversion to alternative wire coatings for gas metal arc welding. Automotive OEMs in the EU must certify new consumable formulations by 2026. Suppliers are responding with copper-free and low-fume wire portfolios that maintain deposition rates under modified electrical waveforms.
Buyer consolidation among mega-Tier-1s is compressing vendor qualification cycles and unbundling after-sales service from equipment procurement. Powertrain suppliers in Japan now separate maintenance contracts from capital purchases, forcing robot OEMs to build standalone service revenue. This pattern is most visible where Yaskawa and FANUC maintain dense installed bases requiring predictive parts replacement.
Robotic Welding for Automotive Manufacturing Market Segmentation
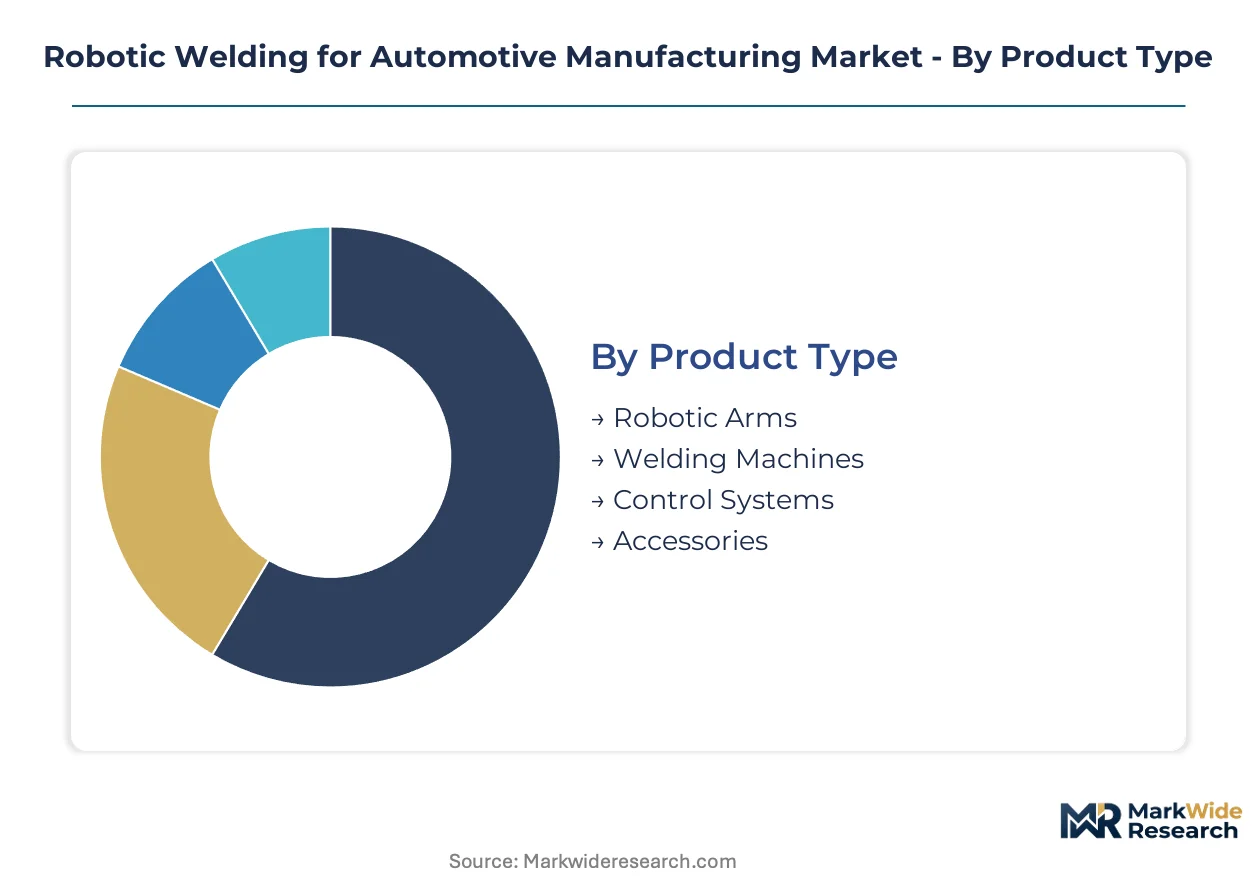
Segmentation in robotic welding reveals how capital allocation splits between hardware commoditization and software value capture. Buyers optimize procurement across product tiers, technology generations, and service integration levels depending on their position in automotive supply chains.
Product Type:
Standardization dominates at the component level while system integration demands bespoke configuration. The customization spectrum stretches from off-the-shelf servo motors to fully commissioned turnkey cells.
- Robotic Arms:Six-axis articulated manipulators with payload ratings from 6kg to 500kg constitute the physical foundation of automated welding. German and Japanese OEM body shops concentrate demand for heavy-payload units above 200kg as they retool for electric vehicle architectures. Payload capacity requirements are escalating as battery tray assemblies force handling of denser aluminum extrusions.
- Welding Machines:Power sources delivering controlled electrical energy to the weld joint span inverter-based arc units to solid-state laser generators. Tier-1 suppliers in the United States favor modular power source designs that permit rapid reconfiguration between steel and aluminum processes. Dual-process capability is becoming non-negotiable as multi-material vehicle platforms proliferate.
- Control Systems:Software-defined architectures for path planning, seam tracking, and quality feedback. Real-time adaptive control is gaining share fastest among premium installations.
- Accessories:Torches, wire feeders, fume extraction hoods, and fixture tooling. Consumable integration determines cell uptime in high-volume environments.
Leading the category by volume: Robotic Arms. Expanding most quickly: Control Systems.
Technology:
Process selection tracks material composition and joint access geometry. Cost tiers separate legacy resistance methods from precision energy beam alternatives commanding 3-5x capital intensity.
- Arc Welding:Gas metal arc and gas tungsten arc processes using consumable electrode wire or non-consumable tungsten. United States vehicle assemblers maintain the largest installed base of robotic arc cells for body-in-white production. Flexibility across material thickness ranges from 0.5mm sheet to 6mm structural members sustains its dominance.
- Spot Welding:Resistance welding through copper alloy electrodes clamping overlapping steel sheets. Component Joining applications in legacy internal combustion vehicle platforms still absorb significant spot welding capacity. Declining share in electric vehicle programs reflects aluminum incompatibility.
- Laser Welding:Fiber laser or disk laser energy delivery with minimal heat-affected zone. Battery tray manufacturers in Germany and China are the primary demand concentration for remote laser welding heads. Aluminum alloy battery enclosure integrity requirements are accelerating replacement of mechanical fastening.
- Electron Beam Welding:High-energy electron stream in vacuum environment for deep penetration joints. Specialized aerospace-derived applications in motorsport and premium chassis components.
Dominant by installed base: Arc Welding. Steepest expansion trajectory: Laser Welding.
Application:
Volume concentration follows vehicle assembly sequence with highest robot density in structural joining operations. Margin pools concentrate in repair and aftermarket services where utilization rates are less cyclical.
- Body Assembly:Joining of stamped sheet metal panels into complete vehicle body structure. OEM facilities in Germany, Japan, and the United States represent the densest robot deployment for unibody and spaceframe construction. Cycle time compression targets below 45 seconds per body are forcing adoption of synchronized multi-robot cells.
- Chassis Manufacturing:Fabrication of subframes, suspension cradles, and structural underbody components. Tier-1 suppliers in the United States specialize in automated chassis welding for pickup truck platforms. Payload and durability requirements sustain demand for heavy-payload articulated arms.
- Component Joining:Seat frames, exhaust systems, fuel tanks, and ancillary brackets. Smaller payload robots dominate this mid-volume tier.
- Repair Services:Automated deposition for defect correction and end-of-line rework. Wire-arc additive repair is emerging as a service revenue extension for integrators.
Highest volume concentration: Body Assembly. Gaining share fastest: Repair Services.
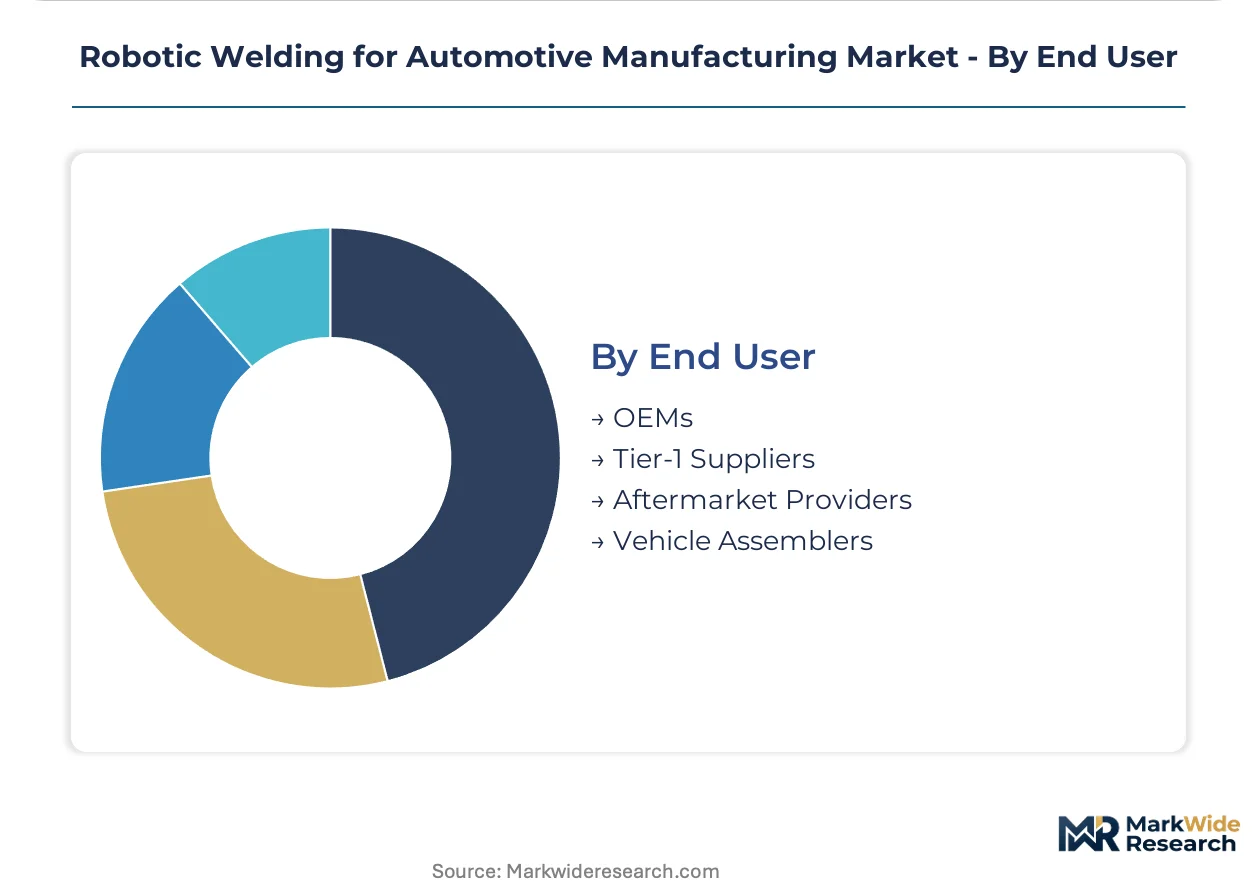
End User:
Procurement authority splits between capital-rich OEMs dictating specifications and Tier-1 suppliers absorbing tooling risk. Aftermarket providers operate on different financing timelines with equipment refresh cycles extending 50% longer.
- OEMs:Original equipment manufacturers with direct control over vehicle design and assembly strategy. German and Japanese OEMs specify welding cell architectures that Tier-1 suppliers must implement. Platform consolidation across electric vehicle programs is reducing the number of qualified system integrators.
- Tier-1 Suppliers:Component and subsystem manufacturers supplying directly to vehicle assembly plants. Tier-1 suppliers in the United States face capital allocation pressure between retrofitting legacy resistance welding lines and greenfield laser welding investments. Contract terms are shifting toward equipment-as-service models with performance guarantees.
- Aftermarket Providers:Collision repair, remanufacturing, and replacement part fabrication. Lower volume requirements favor collaborative robot deployments with simplified programming.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities. Localization mandates in India and Southeast Asia are creating first-mover opportunities for turnkey providers.
Largest procurement volume: OEMs. Fastest procurement growth: Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive manufacturing cluster concentrates demand for heavy-payload robotic welding systems as German OEMs retool for electric vehicle production. Tax incentives under the EU Green Deal accelerate capital deployment across European body shop retrofits.
United States
Pickup truck platforms and commercial vehicle assembly sustain demand for high-payload articulated arms in Michigan and Texas manufacturing corridors. OSHA lockout-tagout mandates and EPA air quality standards for welding fume capture compel automation upgrades in legacy plants. Detroit-Warren-Livonia metropolitan area hosts dense robot deployment for unibody construction.
Germany
Battery tray aluminum welding requirements drive fiber laser system adoption among Stuttgart and Munich OEM facilities. EU Machinery Directive and CE marking requirements enforce functional safety ratings on collaborative robot deployments. Baden-Württemberg production clusters demonstrate multi-robot synchronized cells achieving sub-45-second body cycle times.
China
Dual carbon goals and NEV platform standardization compel laser welding investments in battery enclosure manufacturing. MIIT industrial upgrading programs subsidize automation adoption in Yangtze River Delta automotive corridors. Shanghai and Suzhou manufacturing bases concentrate demand for remote laser welding heads in aluminum-intensive architectures.
Japan
Motion controller hardware concentration in Nagoya and Tokyo metropolitan areas creates supply chain anchoring for Asian system integrators. METI technology roadmaps prioritize seam tracking software development. Toyota City production clusters maintain the highest robot density per worker in automotive assembly globally.
India
PLI scheme incentives for electric vehicle production create first-mover opportunities for turnkey welding cell providers. BIS certification requirements for industrial equipment shape procurement specifications. Tamil Nadu and Gujarat automotive corridors attract greenfield investments in multi-material joining capabilities.
Robotic Welding for Automotive Manufacturing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integration tiers. The market structure concentrates in three layers: captive motor producers with pricing power, welding consumable specialists extending into automation, and pure-play robot OEMs dominating regional installed bases. Strategic moves center on bundling equipment with predictive maintenance contracts and backward integration into servo motor production.
Among diversified industrial conglomerates, ABB and Robert Bosch GmbH occupy positions spanning power electronics through system integration. FANUC Corporation and YASKAWA Electric Corporation exemplify the captive-component archetype with in-house servo motor production. KUKA AG represents European heavy-payload specialization in OEM body shop retrofits. These three archetypes—conglomerate systems integrators, captive-component robot OEMs, and regional payload specialists—define competitive positioning.
| Leading Market Players |
|---|
| ABB |
| Universal Robots |
| FANUC Corporation |
| ESAB Welding & Cutting Products |
| Lincoln Electric |
| YASKAWA Electric Corporation |
| Kawasaki Heavy Industries |
| Robert Bosch GmbH |
| KUKA AG |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between CE-marked European systems and uncertified alternatives creates a two-tier pricing architecture that simultaneously reflects supply chain qualification depth and buyer risk tolerance. Premium positioning demands ISO 10218-2 functional safety validation and captive servo motor production, while commodity tiers compete on spot availability of non-integrated components from distributed Asian suppliers.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to robotic welding cells delivering within twelve weeks versus standard twenty-six-week cycles. The dominant pricing structure runs through project-based turnkey contracts bundling hardware, software, and commissioning services. Price differentiation hinges on CE marking tier and after-sales service bundling, with German OEMs least price-sensitive due to platform consolidation mandates and Indian PLI beneficiaries most sensitive given capital constraints. Cost compression in mid-tier arc welding systems is intensifying because Japanese-German controller duopoly limits sourcing alternatives.
Supply Chain Analysis
CE marking and ISO 10218-2 certification gating restrict qualified supplier pools to established Japanese and German motion control specialists. Supply concentrates in Japan, Germany, and China, with servo motors and rare-earth magnets drawing from concentrated East Asian magnet processing and copper alloy electrode manufacturing. Single-source vulnerability pervades North American retrofit projects dependent on Nagoya-sourced controllers. Distribution runs through OEM-specified system integrators rather than direct robot OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU Machinery Directive safety ratings and CE marking requirements erect barrier-to-entry moats favoring incumbents with validated certification pipelines.
For Market Incumbents: Extend predictive maintenance contract penetration to offset equipment commoditization pressure from Chinese laser system entrants. Deepen backward integration into servo motor production to defend margin position against copper and rare-earth magnet cost volatility. Prioritize certification investment for ISO 10218-2 collaborative safety protocols ahead of mixed-model assembly demand inflection. For New Entrants and Emerging Players: Begin with wire-arc additive repair services as a low-capital entry point before competing in original equipment installation. Target India's PLI-subsidized electric vehicle manufacturing corridors where localization mandates favor turnkey providers establishing domestic integration capabilities. Lead with simplified collaborative robot deployments for aftermarket collision repair shops underserved by complex six-axis systems. For Investors and Strategic Acquirers: Re-rating potential sits with software-defined control architecture specialists given real-time seam tracking and cloud-based weld parameter libraries displacing hardware-centric legacy systems. Long-term viability favors vendors with recurring service revenue exceeding forty percent of total mix. Watch for inflection when Tier-1 suppliers separate maintenance contracts from capital purchases at scale in Japanese supply bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | FANUC and Yaskawa anchor pricing power through captive motor manufacturing in Asia-Pacific installations. |
| Software-Defined Control Architecture Investment | Real-time path optimization and seam tracking software displaces hardware-centric legacy architectures fastest. |
| Turnkey Welding Cell Localization | India's PLI scheme incentives create first-mover advantage for providers establishing Gujarat integration capabilities. |
| Predictive Maintenance Contract Unbundling | Japanese Tier-1s now separate service agreements from capital purchases, forcing standalone revenue model development. |
| CE Marking and ISO 10218-2 Certification Pipeline | EU Machinery Directive compliance creates defensible positioning for European OEM body shop retrofit specialists. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, system integrators, and aftermarket service heads combined with secondary validation from MIIT industrial upgrading disclosures, EU Machinery Directive implementation reports, and vehicle production databases. Bottom-up welding cell shipment tallies triangulated against top-down automotive capital expenditure patterns across Germany, Japan, United States, China, and India.
Data-stream reconciliation across the projection horizon applied segmentation dimensions of welding technology type, payload capacity tier, end-user procurement authority, and regional production cluster density. CAGRs derived from installed base turnover rates and electric vehicle platform reconfiguration timelines. Forecast inputs incorporated aluminum alloy adoption curves in battery tray architectures and OSHA silica fume mandate compliance deadlines.
Copper and rare-earth magnet commodity cycles, collaborative safety certification timeline extensions, and electric vehicle platform standardization delays are the dominant revision risks. Forecasts reflect documented assumptions regarding OEM capital allocation priorities and Tier-1 supplier retrofit-versus-greenfield decisions. A model refresh is warranted upon material change in EU Green Deal emissions benchmark enforcement or NEV subsidy program restructuring in China and India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Activated Carbon Canister Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Automotive Tie Rod Assembly Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Automotive Idler Arm Market