
 Automotive Torsion Bar Market | 2026-2036
Automotive Torsion Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Torsion Bar Market Insights
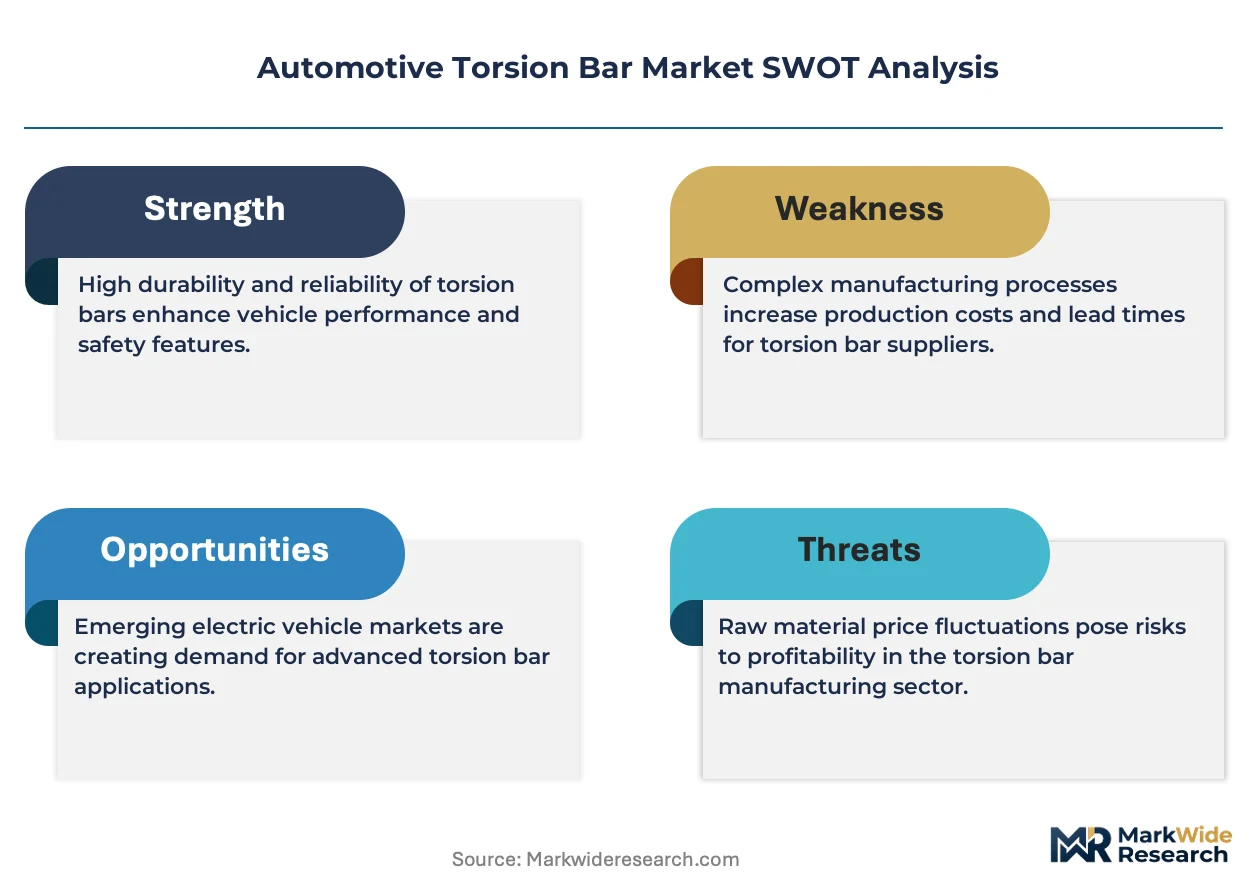
Maintenance-linked software calibration for active suspension systems is consolidating aftermarket revenue streams for torsion bar suppliers. Thyssenkrupp leverages captive steel processing to anchor European OEM contracts for hollow bar variants. Schaeffler competes through integrated torque-sensor modules that extend into chassis electrification architectures. DAEWON dominates Korean commercial vehicle platforms with forged solid bars that sustain load ratings for heavy-duty axles.
An automotive torsion bar is a spring-steel or alloy bar anchored at one end to a vehicle chassis and twisted at the opposite end by suspension arm deflection, storing elastic energy proportional to angular displacement and providing wheel-rate control without coil spring packaging height. Solid torsion bars retain dominance in commercial vehicle suspensions where ultimate fatigue strength and repair simplicity outweigh mass penalties, while hollow torsion bars capture share in passenger vehicles seeking unsprung weight reduction for compliance testing. Steel alloys occupy the material tier by volume, though composite-reinforced bars are emerging in performance vehicle segments where specific stiffness governs lap-time optimization.
NHTSA Federal Motor Vehicle Safety Standards govern torsion bar retention and fatigue life in US-market vehicles, while ECE R14 anchorage regulations shape European homologation requirements for suspension component attachment points. EPA corporate average fuel economy rules indirectly pressure hollow bar adoption by penalizing chassis mass, and China's MIIT passenger vehicle fuel consumption limits accelerate local sourcing of lightweight bar geometries. Stakeholders must monitor pending revisions to side-impact crash standards that could mandate revised torsion bar mounting locations and load-path redundancy.
Market Dynamics
Hollow bar geometries are displacing solid torsion bars across passenger vehicle platforms as EPA fuel-economy testing protocols penalize chassis mass accumulation. This material transition is redistributing forging capacity toward seamless tube production and reshaping supplier qualification criteria for North American and European OEMs.
Growth Catalysts
- EPA Corporate Average Fuel Economy:Stringent fleet-wide efficiency mandates compel automakers to specify hollow torsion bars that reduce unsprung weight without compromising wheel-rate performance.
- Chassis module assembly clusters:Concentrated manufacturing zones in Michigan, Lower Saxony, and Shanghai accelerate just-in-time procurement cycles and lower logistics overhead for suspension suppliers.
- Active suspension calibration:Software-defined damping systems require precision torsion bar torque characteristics, sustaining aftermarket demand for replacement hardware and diagnostic tooling.
Market Restraints
- Alloy steel price volatility:Manganese and chromium input cost swings compress margin stability for forged bar manufacturers locked into annual OEM supply agreements.
- Single-source hollow tube supply:European seamless steel tube production concentrates among integrated mills, exposing tier suppliers to allocation risk during capacity constraints.
- Composite spring substitution:Glass-fiber reinforced polymer leaf springs threaten torsion bar adoption in electric van platforms where packaging flexibility outweighs torsional stiffness requirements.
Strategic Opportunities
- India commercial vehicle expansion:Bharat Stage VI emission standards and domestic axle manufacturing growth create demand for forged solid bars in heavy-duty truck suspensions.
- Integrated torque sensing:Convergence of strain-gauge instrumentation with hollow bar architectures enables real-time load monitoring for predictive maintenance contracts.
- EU Green Deal material incentives:Carbon border adjustment mechanisms favor recycled-content steel alloys in torsion bar production, rewarding early circular-economy adopters with preferential OEM sourcing status.
Industry Challenges
- Heat-treatment certification timelines:NHTSA fatigue-life validation protocols require 18-24 month test cycles for new hollow bar geometries, delaying platform launch schedules.
- Seamless tube welding expertise:Hollow bar production demands specialized rotary friction welding talent scarce in traditional solid-bar forging regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Torsion Bar Market |
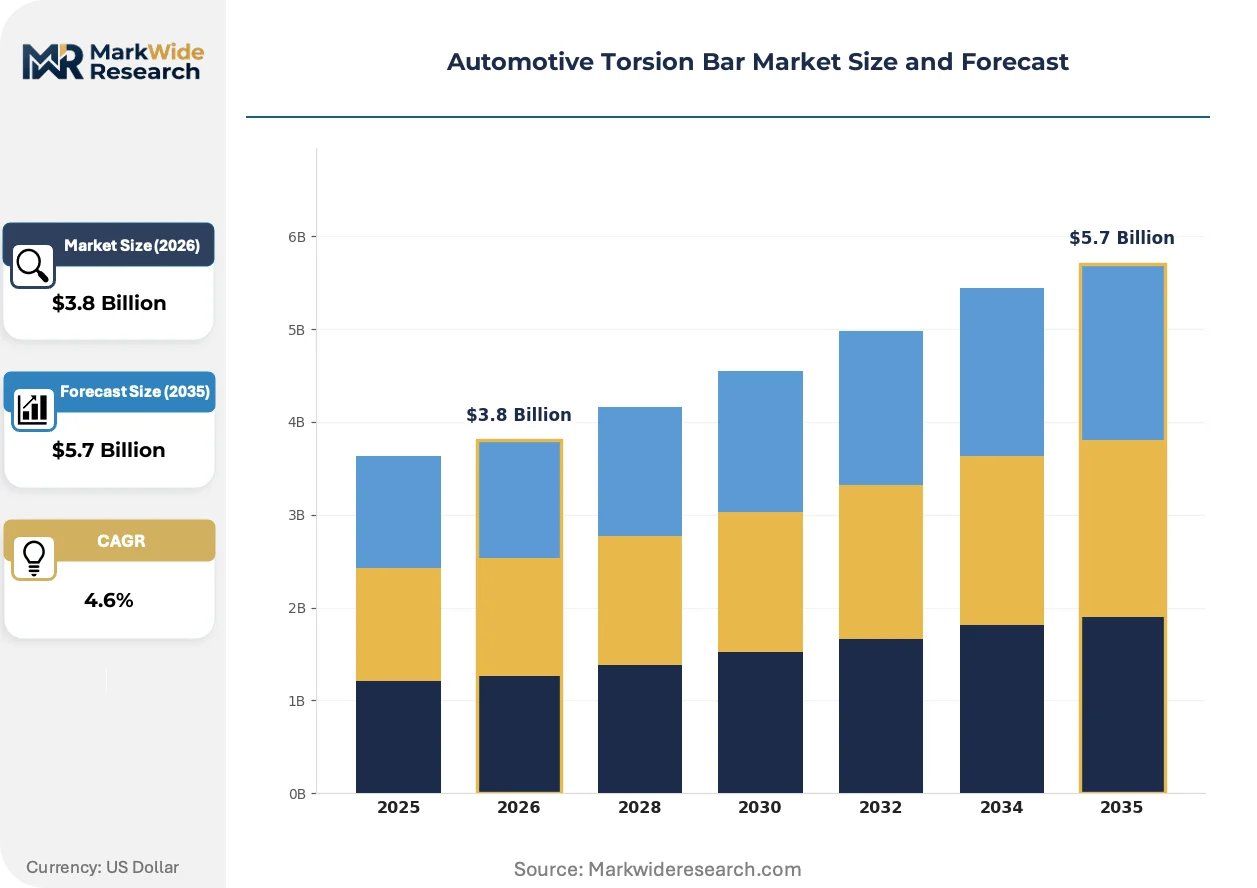
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Torsion Bars, Hollow Torsion Bars, Adjustable Torsion Bars, Non-Adjustable Torsion Bars Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Performance Vehicles Material: Steel, Aluminum, Composite, Others End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Facilities |
| Companies Covered | Lisi Automotive, Freudenberg, Thyssenkrupp, Tinsley Bridge, SOGEFI, ZF-TRW, Schaeffler, DAEWON, Magneti Marelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Torsion Bar Market Trends and Innovations
Material science advances and regulatory pressure on vehicle mass are converging to transform torsion bar design specifications and manufacturing footprints across automotive supply chains.
Induction-hardened hollow steel bars are decentralizing production location decisions by enabling smaller-scale forging operations to achieve fatigue ratings previously requiring massive solid-bar presses. Tier-2 suppliers in Poland and the Czech Republic are adopting this technology to serve regional OEM assembly plants. The shift is compressing historical economies of scale advantages held by integrated steel-forging conglomerates.
REACH substance restrictions on hexavalent chromium plating are forcing conversion to trivalent chromium or zinc-nickel corrosion protection for torsion bar anchorage hardware. European suppliers face 2025 compliance deadlines that accelerate surface-treatment capital investment. North American exporters to EU markets must simultaneously certify dual-process capability to maintain cross-Atlantic platform commonality.
Automakers are unbundling suspension component warranties from vehicle powertrain coverage, creating separate service-interval revenue streams for torsion bar replacement. Fleet operators in Germany and the United States now negotiate direct aftermarket supply agreements with bar manufacturers, bypassing traditional dealer-channel parts distribution. This disintermediation concentrates volume among suppliers offering predictive wear-monitoring telemetry.
Automotive Torsion Bar Market Segmentation
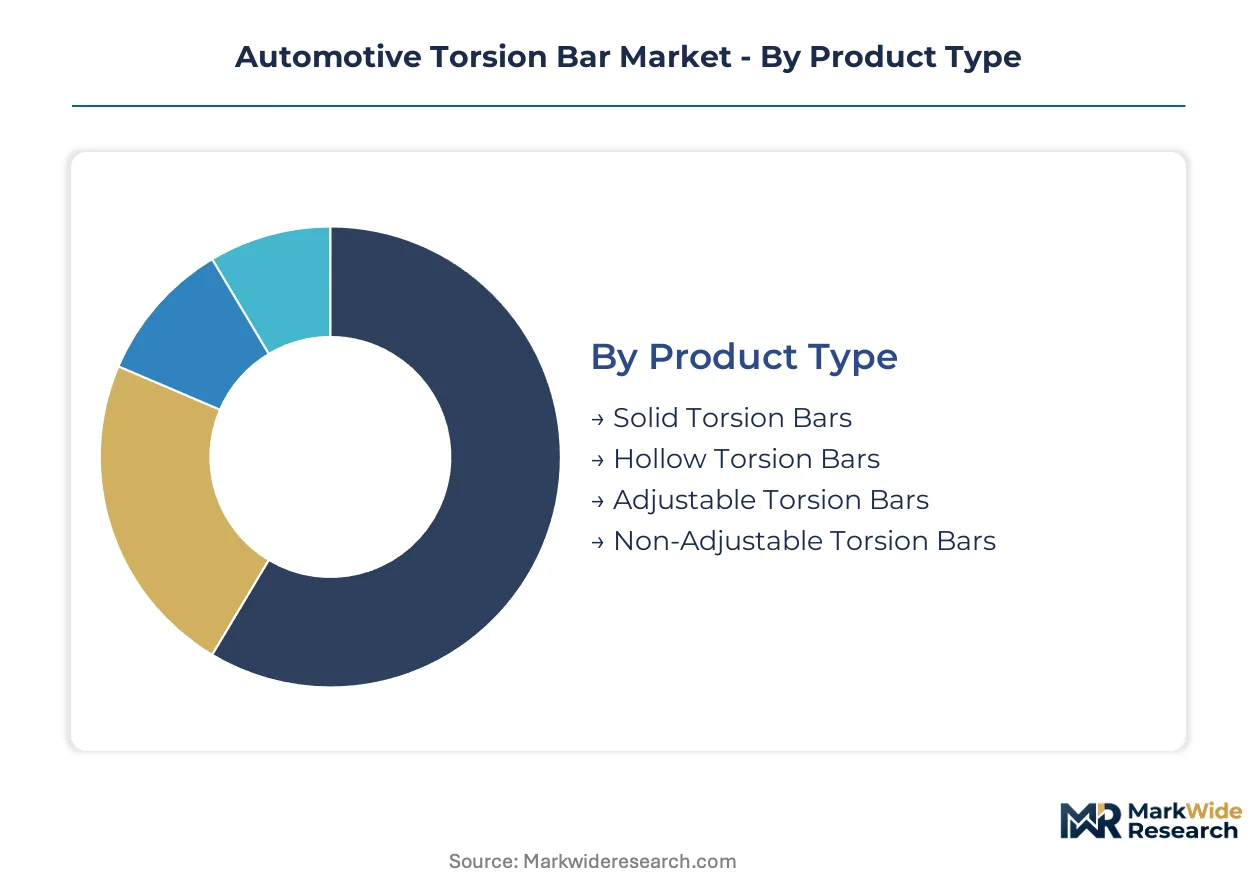
Torsion bar procurement patterns diverge sharply across vehicle architectures, with hollow geometries commanding premium forging investments while solid variants sustain volume in heavy-duty platforms. Material selection and end-user channel structure further partition supplier strategies between captive OEM supply and independent aftermarket distribution.
Product Type:
Capital intensity escalates from solid bar forging to precision hollow tube production, with seamless extrusion and rotary friction welding demanding specialized equipment footprints.
- Hollow Torsion Bars:Seamless steel tube construction with induction-hardened surfaces delivers unsprung weight reduction for EPA fuel-economy compliance. Procurement concentrates in Michigan and Lower Saxony chassis clusters where hollow bar adoption accelerates for light truck and SUV platforms.
- Solid Torsion Bars:Monolithic spring-steel forgings sustain ultimate fatigue ratings for commercial vehicle load requirements. Demand anchors in Korean and Indian heavy-duty axle manufacturing where repair simplicity outweighs mass penalties.
- Adjustable Torsion Bars:Threaded spline mechanisms enable ride-height modification for aftermarket customization. Specialty fabricators in the Czech Republic and Poland serve regional tuning markets.
- Non-Adjustable Torsion Bars:Fixed-rate geometries dominate economy passenger vehicle production where specification standardization reduces tooling complexity.
Most installed capacity flows through solid torsion bars. Expansion is steepest in hollow torsion bars.
Application:
Vehicle duty cycles determine torsional stiffness requirements, with off-road and performance segments prioritizing specific stiffness over mass optimization.
- Passenger Vehicles:Unibody architectures favor hollow bar geometries for packaging efficiency and crash-structure integration. OEM specification in the United States and Germany drives volume for crossover and sedan platforms.
- Commercial Vehicles:Solid bar dominance persists in ladder-frame trucks where axle load ratings exceed hollow bar fatigue limits. Bharat Stage VI emission standards in India accelerate domestic axle production.
- Off-Road Vehicles:Extreme angular deflection requirements favor high-yield alloy steels with enhanced corrosion protection for agricultural and construction equipment.
- Performance Vehicles:Composite-reinforced and hollow steel variants optimize lap-time through unsprung mass reduction and precise wheel-rate tuning.
Commercial vehicles absorb the largest production volume. Performance vehicles are climbing the fastest.
Material:
Raw material processing costs and recycling economics stratify supplier positioning across alloy and composite supply chains.
- Steel:Chrome-molybdenum and manganese alloy grades retain volume leadership through established forging infrastructure and NHTSA fatigue certification pathways. REACH-compliant surface treatment investments concentrate in European supplier networks.
- Aluminum:Extruded and forged aluminum bars penetrate electric vehicle platforms where absolute mass reduction governs range optimization.
- Composite:Carbon-fiber and glass-fiber reinforced polymer bars serve motorsport and limited-production hypercar applications where specific stiffness justifies unit cost premiums.
- Others:Titanium alloy variants occupy niche aerospace-derived performance applications with extreme strength-to-weight requirements.
Steel commands the dominant share of installed capacity. Composite materials are gaining share fastest.
End User:
Channel structure bifurcates between just-in-time OEM assembly supply and aftermarket inventory holding, with warranty unbundling reshaping service-interval economics.
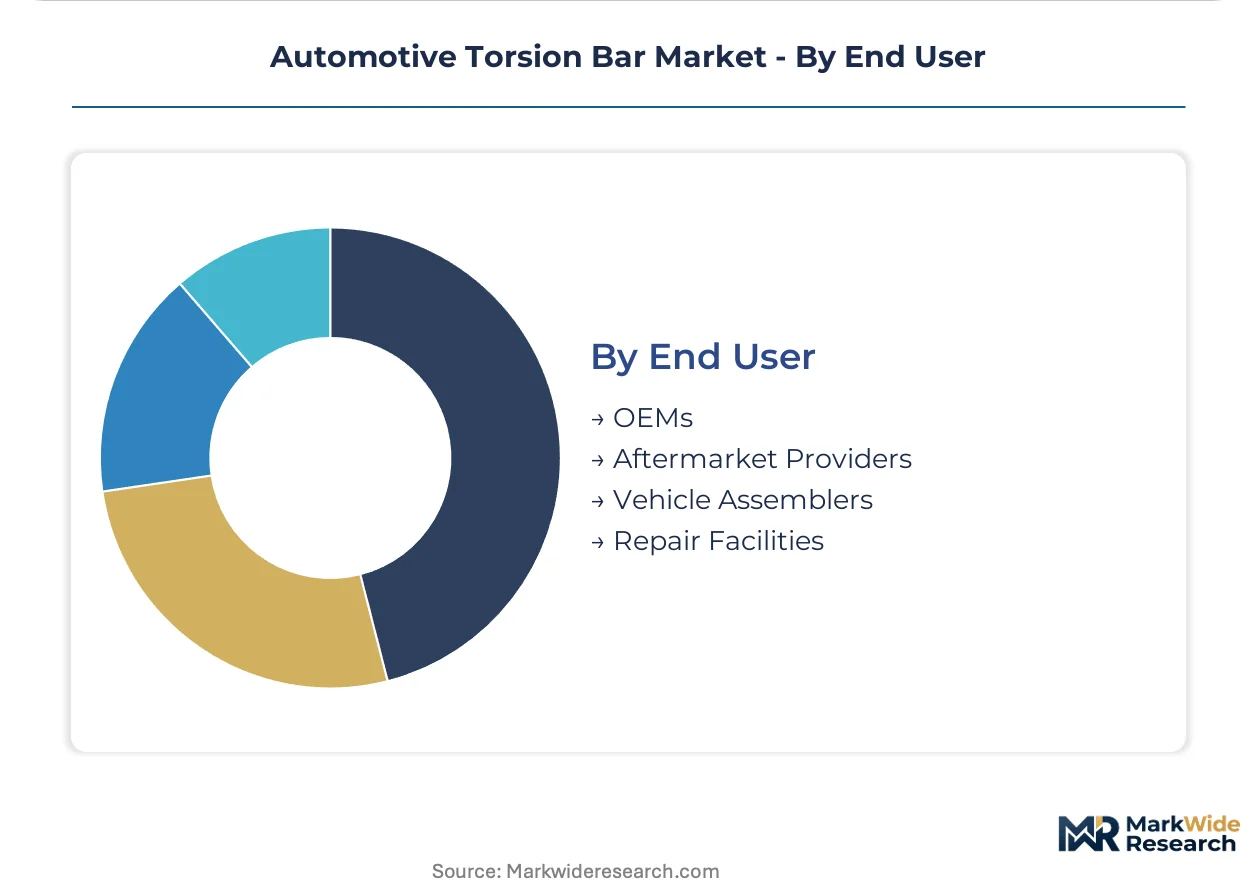
- OEMs:Direct platform engineering relationships require 18-24 month NHTSA validation cycles and hollow tube welding expertise. Procurement centralizes among integrated chassis module suppliers serving assembly plants in Shanghai and Detroit.
- Aftermarket Providers:Predictive wear-monitoring telemetry and direct fleet supply agreements are consolidating volume among bar manufacturers with diagnostic tooling capabilities.
- Vehicle Assemblers:Contract manufacturing arrangements in emerging markets source solid bars from regional forging operations with lower capital barriers.
- Repair Facilities:Independent service networks rely on distributor inventory for replacement hardware, with active suspension calibration requirements sustaining diagnostic equipment demand.
OEMs represent the primary volume channel. Aftermarket providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany hollow bar procurement outpaces United States volume growth, yet both markets concentrate chassis module assembly in Lower Saxony and Michigan corridors respectively. China domestic sourcing accelerates as MIIT fuel consumption limits tighten.
United States
Pickup truck and SUV platforms drive hollow torsion bar specification for EPA fuel-economy compliance. NHTSA Federal Motor Vehicle Safety Standards govern fatigue-life validation cycles spanning 18-24 months. Michigan chassis clusters anchor just-in-time procurement from integrated module suppliers serving Detroit assembly plants.
Germany
Passenger vehicle unibody architectures prioritize mass reduction through seamless tube geometries. ECE R14 anchorage regulations shape homologation requirements for suspension attachment points. Lower Saxony manufacturing zones concentrate forging capacity for European OEM platform engineering.
China
Domestic axle production expansion supports solid bar demand in commercial vehicle segments. MIIT passenger vehicle fuel consumption limits accelerate lightweight geometry adoption. Shanghai chassis module assembly clusters drive volume for regional just-in-time supply networks.
South Korea
Heavy-duty commercial vehicle platforms sustain forged solid bar procurement for load-rated axles. Domestic emission standards align with Bharat Stage VI benchmarks in adjacent export markets. Busan-Ulsan manufacturing corridors concentrate captive steel processing for Korean OEM contracts.
India
Bharat Stage VI standards and domestic axle manufacturing growth create demand for forged solid bars in heavy-duty truck suspensions. Central Pollution Control Board enforcement tightens commercial vehicle compliance timelines. Maharashtra and Gujarat industrial corridors attract regional forging investments for commercial vehicle supply chains.
Automotive Torsion Bar Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated steel processors commanding premium hollow bar contracts while regional forgers capture solid bar volume. The structure concentrates among three archetypes: captive steel conglomerates with seamless tube capability, precision forging specialists with NHTSA certification pathways, and chassis module integrators bundling torsion bars into suspension assemblies. Competitive moves center on rotary friction welding expertise acquisition and predictive maintenance telemetry integration.
Among European integrated suppliers, Thyssenkrupp and Schaeffler exemplify divergent positioning archetypes. Thyssenkrupp anchors hollow bar supply through captive steel processing and seamless tube production scale. Schaeffler occupies a position emphasizing sensor-integrated modules that extend into chassis electrification architectures. Lisi Automotive represents the precision forging specialist tier with established NHTSA fatigue validation credentials.
| Leading Market Players |
|---|
| Lisi Automotive |
| Freudenberg |
| Thyssenkrupp |
| Tinsley Bridge |
| SOGEFI |
| ZF-TRW |
| Schaeffler |
| DAEWON |
| Magneti Marelli |
| Others |
Pricing and Supply Chain Analysis
Rotary friction welding specialists in Lower Saxony and Michigan command wage premiums that widen spreads between premium hollow bar contracts and economy solid bar tiers. Labor-cost differentials between seamless tube production clusters and traditional forging regions directly translate into three-tier pricing stratification across OEM procurement categories.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for standard-grade hollow bars across European passenger vehicle platforms. Pricing stratifies across premium, standard, and economy tiers based on NHTSA fatigue certification status and volume commitment scale. Cost compression in the economy tier is intensifying as Indian forging operations capture commercial vehicle solid bar contracts. Fleet operators exhibit highest price sensitivity due to direct aftermarket procurement models, while OEM platform engineers prioritize certification reliability over unit cost.
Supply Chain Analysis
Scarcity of induction-hardening technicians in Germany, the United States, and China constrains seamless tube output expansion for hollow bar production. Raw material flows draw from chrome-molybdenum alloy suppliers in South Korea, manganese steel processors in India, and recycled-content steel mills in the European Union. Single-source vulnerability concentrates in European seamless tube production among integrated steel conglomerates. Distribution runs through chassis module integrators serving just-in-time assembly clusters in Detroit, Lower Saxony, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EPA fuel-economy testing protocols shift procurement toward hollow bar geometries with precision torque characteristics. OEM specification of sensor-integrated modules sustains premium pricing for suppliers with NHTSA validation credentials and predictive maintenance telemetry capabilities.
For Market Incumbents: Anchor market position through captive seamless tube capacity additions in Poland or the Czech Republic to deflect margin pressure from emerging regional forgers. Deepen backward integration into recycled-content steel alloy supply chains ahead of EU Green Deal carbon border adjustments. Secure rotary friction welding talent pools through technical training partnerships with regional vocational institutes.
For New Entrants and Emerging Players: Begin with adjustable torsion bar fabrication for aftermarket customization markets in Central Europe, where capital barriers remain lower than OEM certification pathways. Target fleet operator direct supply agreements in Germany and the United States where warranty unbundling creates service-interval revenue capture opportunities. Lead with predictive wear-monitoring telemetry bundled with replacement hardware to differentiate from distributor-channel competitors.
For Investors and Strategic Acquirers: Chassis module integrators are the most active acquirer in this space, seeking hollow bar welding expertise to complete suspension assembly bundling strategies. Five-to-ten year viability hinges on electrification architecture convergence and composite spring substitution risk in electric van segments. Monitor Bharat Stage VI enforcement intensity in India and MIIT fuel consumption limit revisions in China as demand inflection signals for solid versus hollow bar procurement mix.
| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Tube Capacity Expansion | Polish and Czech Republic investments capture EPA-driven hollow bar specification shifts in European OEM platforms. |
| Integrated Torque Sensor Development | Strain-gauge instrumentation convergence enables predictive maintenance contracts with German fleet operators. |
| Recycled-Content Steel Certification | EU Green Deal carbon border adjustment mechanisms reward circular-economy adopters with preferential sourcing status. |
| Rotary Friction Welding Talent Acquisition | Technical expertise scarcity in Lower Saxony and Michigan constrains hollow bar production scaling for NHTSA validation. |
| Direct Fleet Supply Agreement Negotiation | Warranty unbundling in Germany and the United States concentrates aftermarket volume among telemetry-capable manufacturers. |
Research Methodology
Multiple input streams — OEM platform engineering interviews, Tier 1 supplier procurement discussions, aftermarket distributor operational reviews, and regulatory affairs consultations — were reconciled against vehicle production databases, IHS Markit registration data, NHTSA FMVSS filing records, and EPA fuel-economy compliance reports. Primary fieldwork with chassis module integrators, suspension component procurement leads, and dealership service operations was validated through bottom-up and top-down triangulation against secondary trade flow and certification timeline data.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived through regression analysis of historical specification shifts and forward projection of regulatory compliance timelines. Industry-specific forecast inputs incorporated EPA fleet-wide efficiency mandate stringency trajectories and MIIT passenger vehicle fuel consumption limit enforcement patterns.
Several conditions sit outside the modeled scope, including pending NHTSA side-impact crash standard revisions affecting torsion bar mounting locations and REACH substance restriction enforcement variability on hexavalent chromium conversion timelines. Forecasts reflect documented assumptions regarding alloy steel price volatility ranges and seamless tube allocation risk during capacity constraints. Practitioners should monitor EPA CAFE rulemaking announcements and ECE R14 anchorage regulation amendment proposals for early signals of specification trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Idler Arm Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Trailer Drawbar Market