
 Global Two Wheeler Accessories Market | 2026-2036
Global Two Wheeler Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Global Two Wheeler Accessories Market Outlook
ECE 22.06 helmet certification is reorganizing supplier eligibility across the Global Two Wheeler Accessories Market, forcing retooling investments that filter out smaller molders. Hero MotoCorp leverages captive component plants to control cost position in Indian replacement channels. Yamaha Motor Corporation anchors premium accessory sales through dedicated dealership fitment centers. Studds Accessories dominates mass-market helmet distribution via dense rural dealer networks.
Two wheeler accessories comprise protective, functional, and aesthetic add-ons manufactured to vehicle-specific fitments, with helmet shells typically molded from polycarbonate or composite fiber blends to absorb impact energy across defined velocity thresholds. These products extend vehicle utility, rider safety, and personalization scope for motorcycles and scooters operating in varied traffic densities. Helmets command the largest value pool given mandatory-use laws and replacement cycles tied to impact exposure, while saddlebags gain traction among touring enthusiasts seeking integrated luggage solutions. Leather as a material segment sustains premium pricing in enthusiast channels despite synthetic alternatives gaining share in commercial fleet procurement. DIY installation routes expand through e-commerce tutorial ecosystems, though professional fitment retains preference for electronic and structural accessories.
India's BIS and the EU's ECE framework impose divergent impact-test protocols that fragment product development roadmaps for multinational suppliers. The US DOT and EPA regulate helmet labeling and exhaust-related accessory emissions respectively, creating layered compliance obligations for cross-border sellers. Stakeholders must monitor regulatory harmonization talks between ASEAN member states, as unified standards would reshape manufacturing location decisions and testing cost structures.
Market Dynamics
ECE 22.06 helmet certification is forcing molders to retool impact-testing lines, filtering out smaller suppliers while concentrating procurement power among certified tier-ones. This regulatory compression is reshaping supplier eligibility across protective gear segments.
Growth Catalysts
- India BIS mandate:Mandatory helmet certification is accelerating replacement demand and formalizing distribution channels previously served by uncertified imports.
- Southeast Asian delivery fleets:Standardized protective gear procurement by logistics platforms is creating volume anchors for accessory manufacturers.
- Composite fiber molding:Advanced shell materials are reducing weight-to-strength ratios, enabling premium positioning in enthusiast segments.
Market Restraints
- Polycarbonate resin volatility:Petrochemical input costs swing helmet margin structures unpredictably for molders without long-term supply contracts.
- Ho Chi Minh City supplier concentration:OEM park clustering creates single-point vulnerability for global brands dependent on Vietnamese manufacturing corridors.
- Divergent test protocols:India's BIS and EU ECE frameworks impose non-overlapping impact standards, fragmenting product development roadmaps.
Strategic Opportunities
- ASEAN harmonization talks:Unified safety standards would eliminate redundant testing costs and simplify cross-border supplier qualification.
- Integrated luggage systems:Saddlebag-to-chassis mounting solutions are capturing touring enthusiast spend previously directed to aftermarket fabricators.
- E-commerce tutorial ecosystems:DIY installation content is opening direct-to-rider channels, bypassing traditional dealer markup structures.
Industry Challenges
- ECE 22.06 certification timelines:Extended laboratory queue times are delaying product launches and freezing working capital in pre-approved inventory.
- Legacy dealer network integration:Electronic accessory fitment requires technician upskilling that rural distributors cannot absorb without manufacturer subsidy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Two Wheeler Accessories Market |
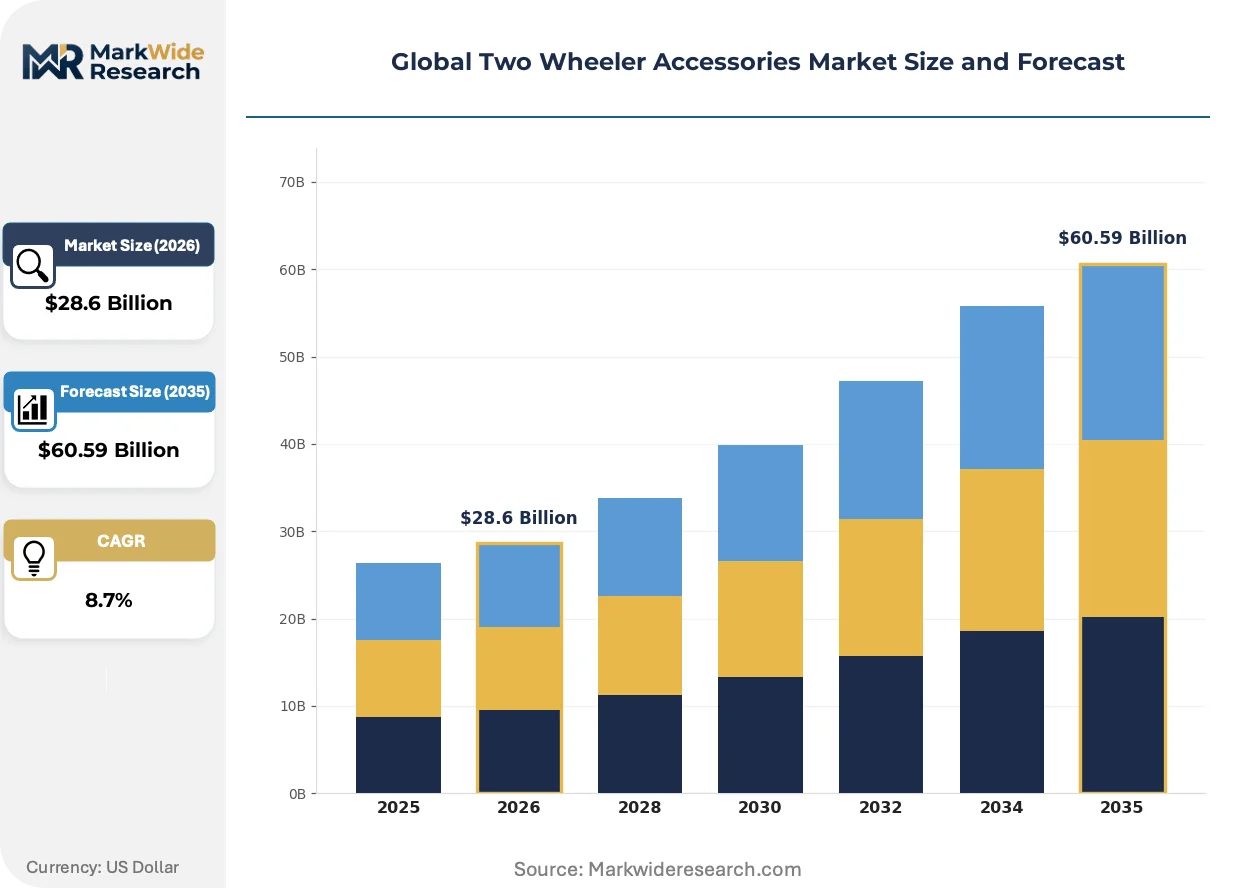
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Gloves, Saddlebags, Grips Material: Leather, Polyester, Plastic, Rubber Installation: DIY, Professional, Custom, Pre-installed End User: Motorcycle Riders, Delivery Services, Enthusiasts, Tourists |
| Companies Covered | Hero MotoCorp, Yamaha Motor Corporation, TVS Motor Company, Honda Motorcycle and Scooter India, Royal Enfield, Studds Accessories, Vega Auto Accessories, GIVI, Alpinestars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Two Wheeler Accessories Market Strategic Shifts
Accessory development is pivoting from passive protection toward connected functionality, with material science and regulatory harmonization acting as twin accelerants. Three shifts are compressing traditional competitive moats.
Smart helmet systems integrating heads-up displays and Bluetooth communication are displacing basic polycarbonate shells in premium segments. Adventure touring riders in Germany and Japan are adopting these units at pace, forcing traditional molders to partner with electronics suppliers or surrender price-positioning.
EU ECE 22.06 certification is mandating rotational-impact testing that previous DOT-approved designs cannot satisfy. European suppliers are absorbing retooling costs fastest, while US exporters face exclusion from continental procurement tenders unless they duplicate test protocols.
Fleet procurement by delivery platforms is consolidating buyer power and unbundling after-sales service from hardware purchase. Indonesian and Vietnamese logistics operators now negotiate direct with manufacturers, bypassing distributor layers that previously captured margin in replacement channels.
Global Two Wheeler Accessories Market Segmentation
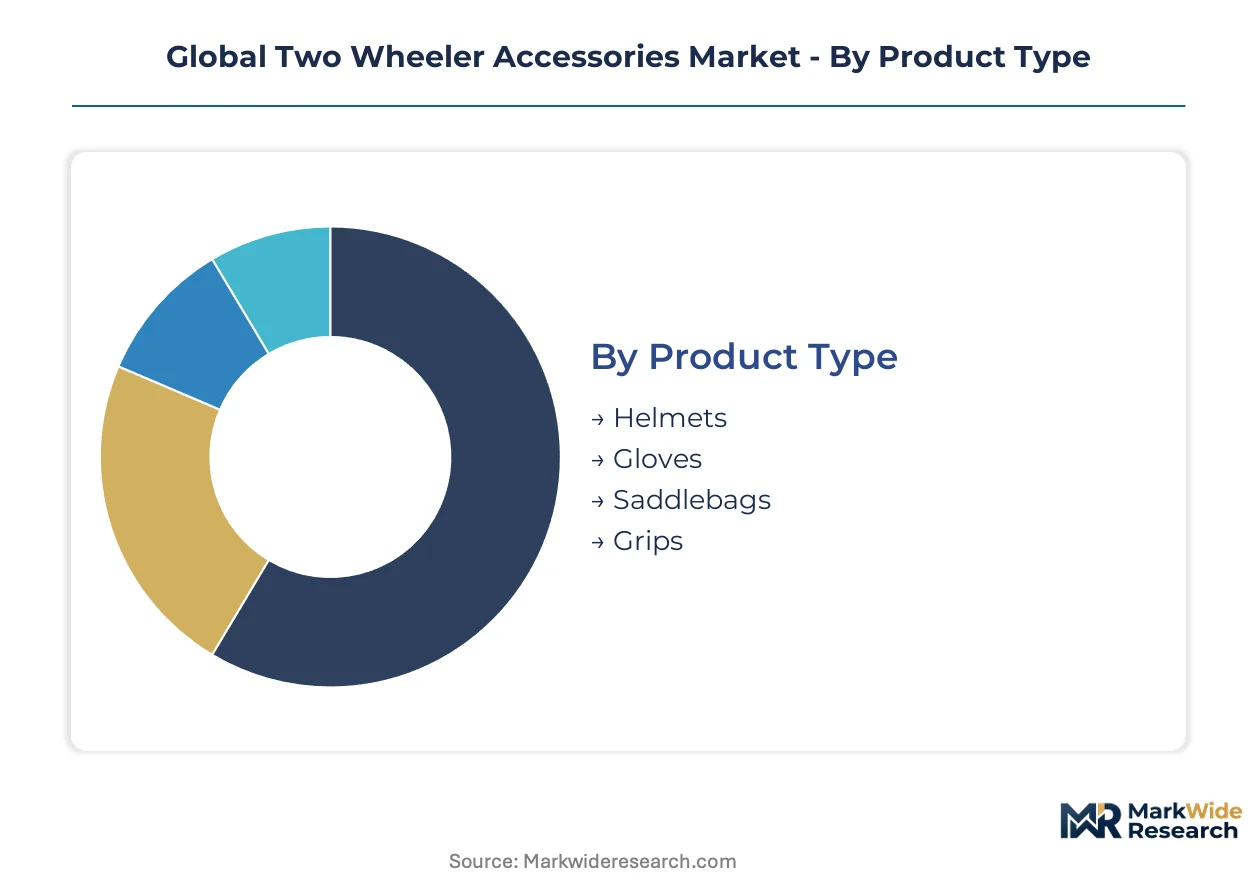
Segmentation in the two wheeler accessories market reveals how regulatory mandates, material substitution economics, and installation complexity fragment procurement patterns across rider categories. Understanding these fault lines exposes where supplier power concentrates and where margin compression threatens incumbent positioning.
Product Type:
Helmets face the strongest substitution pressure from integrated smart-rider systems that bundle communication, navigation, and impact sensing into single hardware investments, eroding standalone shell demand.
- Helmets:Polycarbonate and composite fiber shells absorb impact energy across velocity thresholds defined by ECE 22.06 and BIS protocols. India's certification mandate is accelerating replacement cycles in formal retail channels previously served by uncertified imports.
- Gloves:Abrasion-resistant leather and synthetic palm constructions protect against road surface contact during low-side incidents. Southeast Asian delivery fleets are standardizing procurement specifications that prioritize durability over tactile sensitivity for urban stop-and-go operations.
- Saddlebags:Rigid and soft-mount luggage solutions extend touring range for long-distance riders.
- Grips:Vibration-dampening rubber and gel compounds reduce rider fatigue during extended highway exposure.
Helmets anchors the volume base while saddlebags gains share at the steepest rate.
Material:
Cost tier stratification separates premium positioning from fleet procurement economics, with synthetic alternatives compressing leather's addressable market in commercial segments.
- Leather:Full-grain and corrected-grain hides sustain premium pricing in enthusiast channels through tactile quality and aging patina characteristics. German and Japanese touring riders maintain preference for natural material despite synthetic alternatives gaining share in Indonesian and Vietnamese logistics fleet procurement.
- Polyester:Woven and coated fabric constructions deliver weather resistance at unit costs compatible with high-volume replacement cycles. Delivery service procurement in Ho Chi Minh City corridors favors polyester for saddlebag and glove applications where abrasion resistance must balance against total cost of ownership.
- Plastic:Injection-molded ABS and polypropylene components serve structural accessory applications.
- Rubber:Natural and synthetic elastomer compounds provide grip and vibration isolation.
Polyester dominates shipment volumes while leather commands the highest unit margins.
Installation:
Customer capability dispersion creates channel conflict between professional fitment networks and direct-to-rider e-commerce tutorials that bypass dealer markup structures.
- DIY:Self-installation routes expand through video tutorial ecosystems that demonstrate helmet visor replacement, grip heating element wiring, and saddlebag mounting bracket attachment. Riders in India's tier-2 and tier-3 cities access these channels via smartphone connectivity, reducing dependence on urban dealer networks.
- Professional:Technician-dependent fitment retains preference for electronic accessories requiring CAN bus integration or structural modifications affecting vehicle handling. Yamaha Motor Corporation's dedicated dealership fitment centers capture this demand through certified technician labor.
- Custom:Bespoke fabrication and modification services serve enthusiast personalization requirements.
- Pre-installed:Factory-fit accessories bundled with new vehicle purchase reduce aftermarket decision friction.
Professional installation retains the highest revenue per transaction while DIY routes expand most quickly.
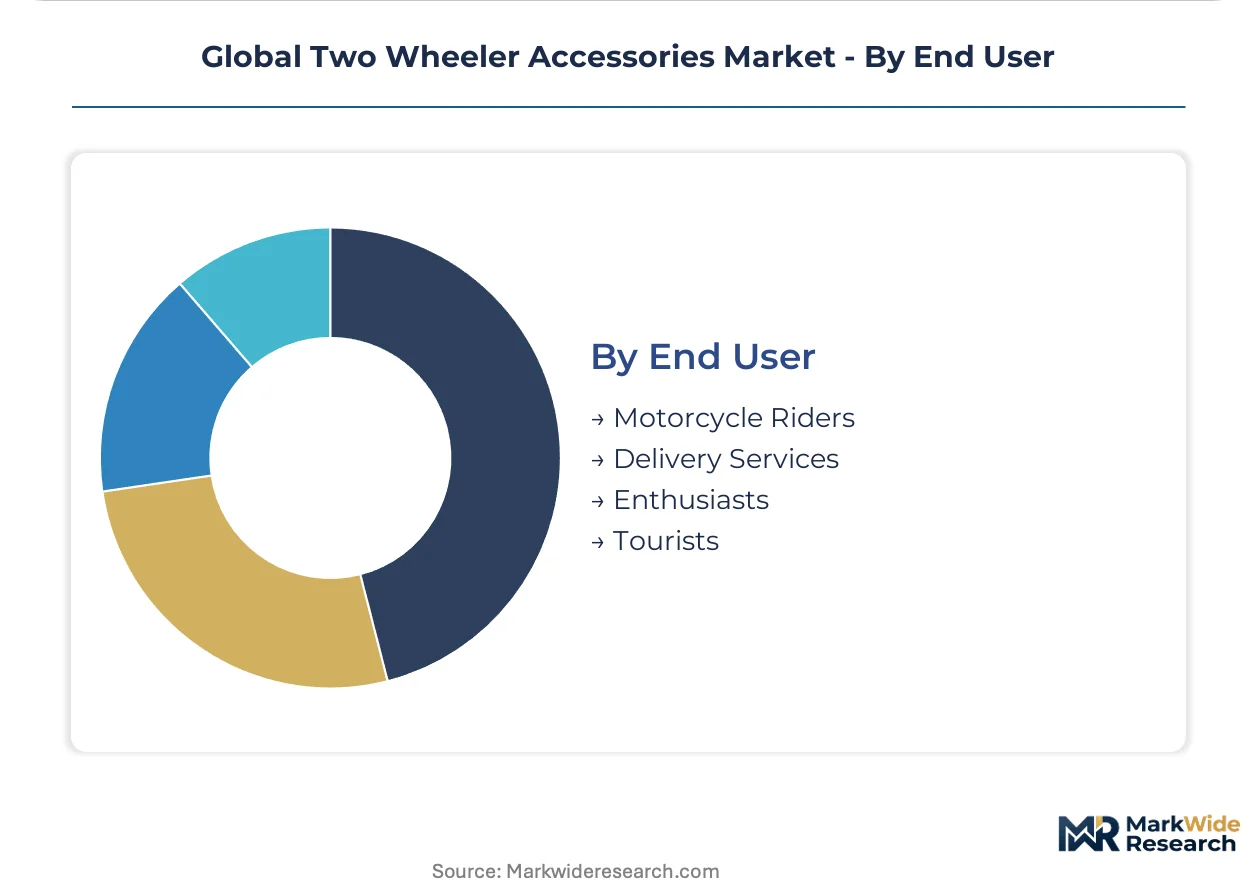
End User:
Application intensity varies dramatically between daily commercial operators and recreational riders, fragmenting product specification requirements across durability, weight, and aesthetic dimensions.
- Motorcycle Riders:General commuting and personal transportation users prioritize regulatory compliance and baseline protection at accessible price points. India's BIS helmet mandate has formalized demand in this segment, displacing uncertified imports from unorganized retail channels.
- Delivery Services:Logistics platform fleet operators negotiate direct manufacturer relationships for standardized protective gear procurement. Indonesian and Vietnamese delivery aggregators specify helmet and glove combinations optimized for 12-hour shift durability, bypassing traditional distributor markups.
- Enthusiasts:Performance-oriented and touring-focused riders invest in premium material specifications and integrated technology features.
- Tourists:Rental market and travel-specific accessory demand concentrates in seasonal patterns around motorcycle tourism corridors.
Delivery services concentrate procurement volume while enthusiasts drive premium segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS helmet certification mandate is formalizing distribution channels and accelerating replacement demand across South Asian markets. Vietnam's manufacturing corridors near Ho Chi Minh City concentrate OEM supplier parks serving export markets. Germany's ECE 22.06 adoption is filtering non-compliant imports from continental procurement tenders.
India
Delivery fleet standardization and BIS certification enforcement are displacing uncertified imports from unorganized retail channels. The Bureau of Indian Standards mandates impact-test protocols that fragment product development roadmaps for multinational suppliers. Manufacturing clusters in Maharashtra and Tamil Nadu host captive component plants controlling cost position in replacement channels.
Vietnam
Logistics platform procurement is consolidating buyer power for standardized protective gear across Southeast Asian delivery services. The country's national standards body participates in ASEAN harmonization talks that would reshape testing cost structures. OEM supplier parks cluster near Ho Chi Minh City, creating single-point vulnerability for global brands dependent on Vietnamese manufacturing corridors.
Germany
Adventure touring riders are adopting smart helmet systems with heads-up displays at pace, forcing traditional molders to partner with electronics suppliers. ECE 22.06 certification mandates rotational-impact testing that previous DOT-approved designs cannot satisfy. Industrial concentration in Bavaria and Baden-Württemberg absorbs retooling costs fastest among European suppliers.
Indonesia
Delivery aggregators negotiate direct manufacturer relationships for helmet and glove combinations optimized for 12-hour shift durability. The country's national standards regulator monitors ASEAN harmonization developments for unified safety standards. Procurement concentrates in Jakarta and Surabaya logistics corridors, bypassing distributor layers that previously captured margin in replacement channels.
United States
DOT labeling requirements and EPA exhaust-related accessory emissions regulations create layered compliance obligations for cross-border sellers. The National Highway Traffic Safety Administration maintains distinct impact-test protocols from ECE frameworks. Distribution channels concentrate in California and Texas metropolitan markets where e-commerce tutorial ecosystems expand DIY installation routes.
Global Two Wheeler Accessories Market Competitive Environment
Player mix skews toward integrated vehicle manufacturers with captive accessory operations and specialized protective gear fabricators serving aftermarket channels. Market structure exhibits tiered concentration with premium positioning held by dedicated fitment networks and mass-market volume captured through dense rural distribution. Two strategic archetypes dominate: OEM-captive suppliers leveraging vehicle-specific fitment relationships, and independent specialists competing on certification compliance and material specification. Competitive moves center on certification queue positioning for ECE 22.06 compliance and direct procurement relationships with delivery fleet operators.
Among India-based fabricators, Studds Accessories and Vega Auto Accessories exemplify mass-market helmet distribution archetypes, while Hero MotoCorp represents OEM-captive vertical control over replacement channels. Yamaha Motor Corporation anchors premium positioning through dedicated dealership fitment centers. These three companies occupy distinct tier positions shaped by regulatory compliance capabilities and channel access depth rather than interchangeable product substitution.
| Leading Market Players |
|---|
| Hero MotoCorp |
| Yamaha Motor Corporation |
| TVS Motor Company |
| Honda Motorcycle and Scooter India |
| Royal Enfield |
| Studds Accessories |
| Vega Auto Accessories |
| GIVI |
| Alpinestars |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Vietnamese polycarbonate molding facilities shapes both supply concentration and price floors across protective gear tiers. OEM supplier parks near Ho Chi Minh City generate scale economies that compress unit costs for certified helmet manufacturers while marginalizing smaller molders unable to absorb ECE 22.06 retooling investments.
Pricing Analysis
Certification level (ECE 22.06 versus BIS versus uncertified) creates the primary spread between premium and mass-market helmet tiers. Three-tier pricing structure across premium composite fiber, standard polycarbonate, and economy uncertified levels dominates transaction flows. Cost compression in the economy tier is intensifying because Indonesian and Vietnamese delivery fleets negotiate direct manufacturer contracts, stripping distributor markups from replacement channels. Delivery services exhibit the highest price sensitivity, while German and Japanese touring enthusiasts show minimal elasticity for smart helmet systems with integrated electronics.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for Southeast Asian manufacturing corridors serving global two wheeler accessory demand. Production concentrates in Vietnam, India, and China, with polycarbonate resin and composite fiber prepreg drawing from petrochemical feedstocks centered on Singapore and South Korea. Single-source vulnerability concentrates in Ho Chi Minh City OEM parks, where clustered molders face simultaneous disruption risk from regional logistics constraints. Distribution runs through dense rural dealer networks in India, dedicated dealership fitment centers in Germany and Japan, and direct-to-rider e-commerce channels expanding across tier-2 and tier-3 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable barriers. ECE 22.06 and BIS certification requirements impose fixed costs that filter out marginal competitors and protect compliant incumbents.
For Market Incumbents: Fortify certification queue positioning to secure ECE 22.06 approval timelines ahead of competitor launches. Deepen backward integration into polycarbonate resin sourcing through long-term offtake agreements with Singaporean petrochemical suppliers, neutralizing input cost volatility that threatens margin structures. Expand captive component plants in Maharashtra and Tamil Nadu to tighten cost control against Studds Accessories and Vega Auto Accessories in Indian replacement channels. For New Entrants and Emerging Players: E-commerce tutorial ecosystems where incumbents under-serve DIY installation guidance present accessible entry points. Target tier-2 and tier-3 Indian cities where smartphone-enabled riders bypass urban dealer networks for helmet visor replacement and grip heating element wiring instruction. Capture white-space in polyester saddlebag procurement for Vietnamese delivery fleets prioritizing durability over brand recognition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEM-captive suppliers with vehicle-specific fitment relationships and certified aftermarket service networks. Long-term viability favors targets with ECE 22.06 and BIS dual certification capabilities, integrated electronics partnerships for smart helmet migration, and direct procurement contracts with Indonesian or Vietnamese logistics platforms. Monitor ASEAN harmonization talks as the signal to watch for unified standards that would eliminate redundant testing costs and trigger manufacturing location consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ECE 22.06 Certification Investment | Retooling impact-testing lines filters smaller molders and concentrates procurement power among certified tier-ones. |
| Direct Fleet Procurement Relationships | Bypassing distributor layers captures margin previously lost to replacement channel intermediaries in Southeast Asia. |
| Smart Helmet Electronics Partnership | Bluetooth and heads-up display integration displaces basic shells in German and Japanese premium segments. |
| Backward Integration into Resin Sourcing | Long-term polycarbonate supply contracts neutralize petrochemical input cost swings affecting helmet margin structures. |
| DIY Installation Content Development | Video tutorial ecosystems open direct-to-rider channels in India's tier-2 and tier-3 cities beyond dealer networks. |
Study Parameters
Operator-level perspectives from helmet manufacturing plant managers, OEM procurement leads at Hero MotoCorp and Yamaha Motor Corporation, aftermarket distributor heads in Maharashtra and Tamil Nadu, and logistics platform fleet managers in Jakarta and Ho Chi Minh City anchored the qualitative base. These primary interviews combined with secondary validation from BIS certification registries, ECE 22.06 laboratory queue records, customs data on polycarbonate resin imports, and vehicle production databases. Bottom-up unit shipment estimates and top-down value triangulation cross-checked segment-level projections.
Sensitivity analysis tested forecast robustness across alternative regulatory harmonization scenarios and resin price volatility assumptions. The analytical framework modeled volume and value outputs across product type, material grade, installation complexity, and end-user application dimensions throughout the forecast period. CAGRs derived from historical replacement cycle patterns, fleet procurement growth trajectories, and certification mandate enforcement timelines. Industry-specific inputs included ECE 22.06 laboratory capacity constraints and ASEAN standards body negotiation progress.
Forecasts assume regulatory continuity in India's BIS enforcement and EU ECE framework adoption; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as ASEAN harmonization talks and composite fiber molding technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Conventional Motorcycles and Scooters Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Bicycle Crank Motor Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
Kids Bicycle Market
Bikes and Motorcycles
Motorcycle Hub Motor Market