
 Half-Shaft Assemblies Market | 2026-2036
Half-Shaft Assemblies Market Size, Share, and Industry Trends Forecast 2026-2036
Half-Shaft Assemblies Market Insights
A shift from single-source to multi-source procurement is restructuring supplier relationships across the half-shaft assemblies value chain. GKN Automotive leverages its global manufacturing footprint to serve multiple OEM platforms simultaneously. Dana Incorporated anchors North American supply through vertically integrated forging and machining operations. ZF Friedrichshafen AG competes by combining half-shaft production with its broader driveline systems portfolio.
Half-shaft assemblies are torque-transmitting driveline components that connect the differential to the drive wheels, typically manufactured from hollow or solid steel bars with induction-hardened splines and precision-machined joint interfaces to accommodate suspension travel and steering angles. Constant Velocity Half-Shaft configurations dominate passenger vehicle applications where articulation angles exceed 45 degrees, while Chromoly Steel retains the largest share among materials due to its fatigue resistance under torsional loading. Aluminum Alloy formulations represent the fastest-expanding material category as OEMs pursue mass reduction targets for battery-electric platforms.
The EPA Corporate Average Fuel Economy standards and NHTSA safety regulations in the United States, alongside ECHA REACH compliance requirements in Europe, shape material selection, surface treatment processes, and recyclability mandates for half-shaft manufacturers. ISO 9001 and IATF 16949 quality frameworks govern supplier qualification and production consistency across OEM supply bases. Stakeholders must monitor how evolving electric vehicle torque profiles and autonomous vehicle durability requirements redefine fatigue-life specifications and joint architecture standards.
Market Dynamics
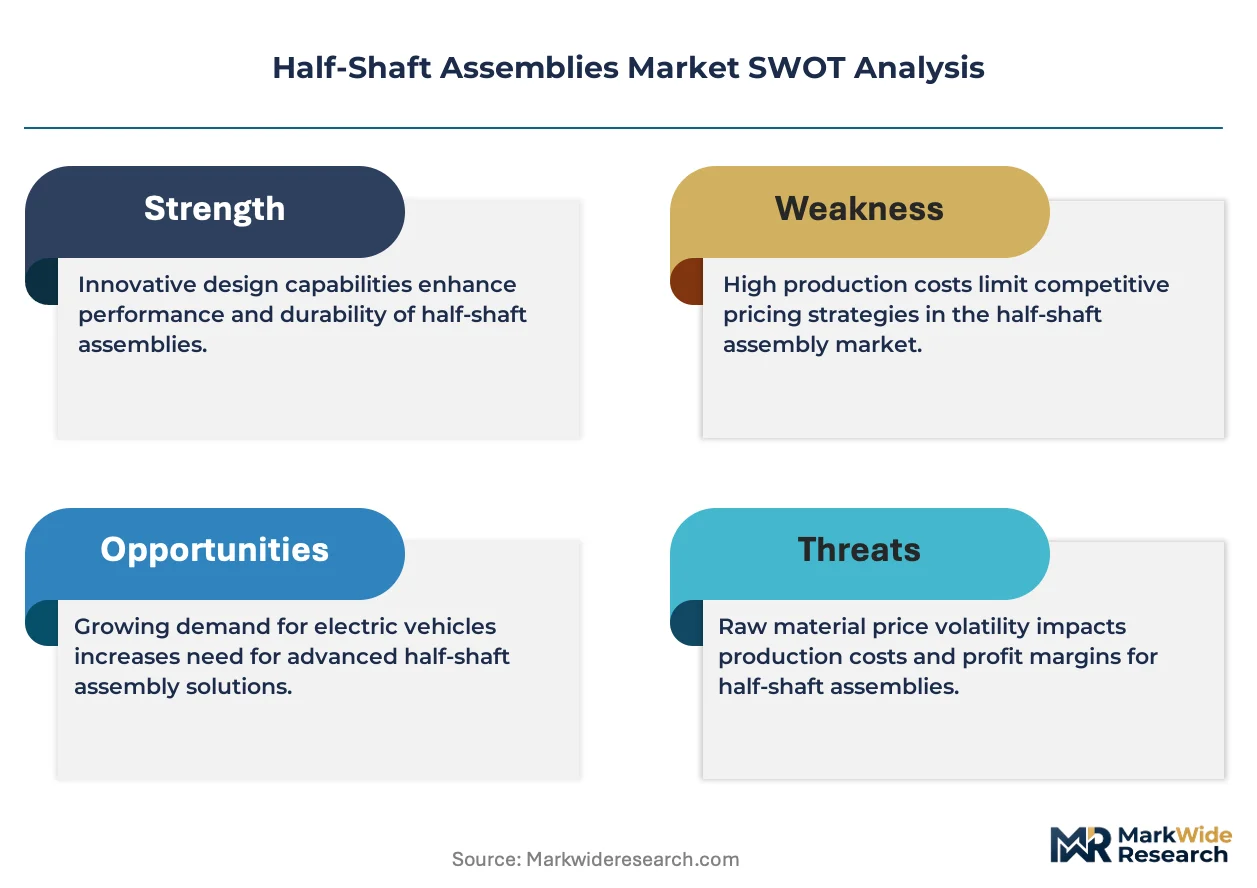
Electric vehicle powertrain architectures are compressing half-shaft design cycles and forcing material substitutions that prioritize mass reduction over legacy fatigue-life benchmarks established for internal combustion drivelines.
Growth Catalysts
- EU F-Gas Regulation:Carbon-emission mandates are accelerating aluminum alloy and composite adoption in European OEM supply chains.
- Battery-electric platforms:Higher instantaneous torque profiles from electric motors demand upgraded constant velocity joint specifications.
- Germany:Stuttgart and Munich manufacturing clusters concentrate premium OEM and Tier-1 engineering resources.
Market Restraints
- Chromoly steel price volatility:Alloy surcharges and scrap metal fluctuations compress margin predictability for forged component suppliers.
- Induction hardening capacity concentration:Specialized heat treatment infrastructure clusters in Germany and Japan, creating geographic supply risk.
- REACH compliance friction:ECHA substance restrictions on surface treatment chemicals extend qualification timelines.
Strategic Opportunities
- India:Domestic OEM localization mandates under PLI scheme create captive supply openings for forged driveline components.
- Autonomous vehicle durability standards:Extended service-life specifications for robotaxi fleets redefine fatigue testing protocols.
- Closed-loop aluminum recycling:EU Green Deal circular economy requirements favor suppliers with in-house remelt capabilities.
Industry Challenges
- Induction hardening technician scarcity:Specialized heat treatment expertise shortages constrain capacity expansion.
- IATF 16949 certification timelines:OEM qualification cycles for new joint architectures extend 18-24 months.
- Legacy spline interface integration:Electric axle packaging constraints force incompatible legacy joint redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Half-Shaft Assemblies Market |
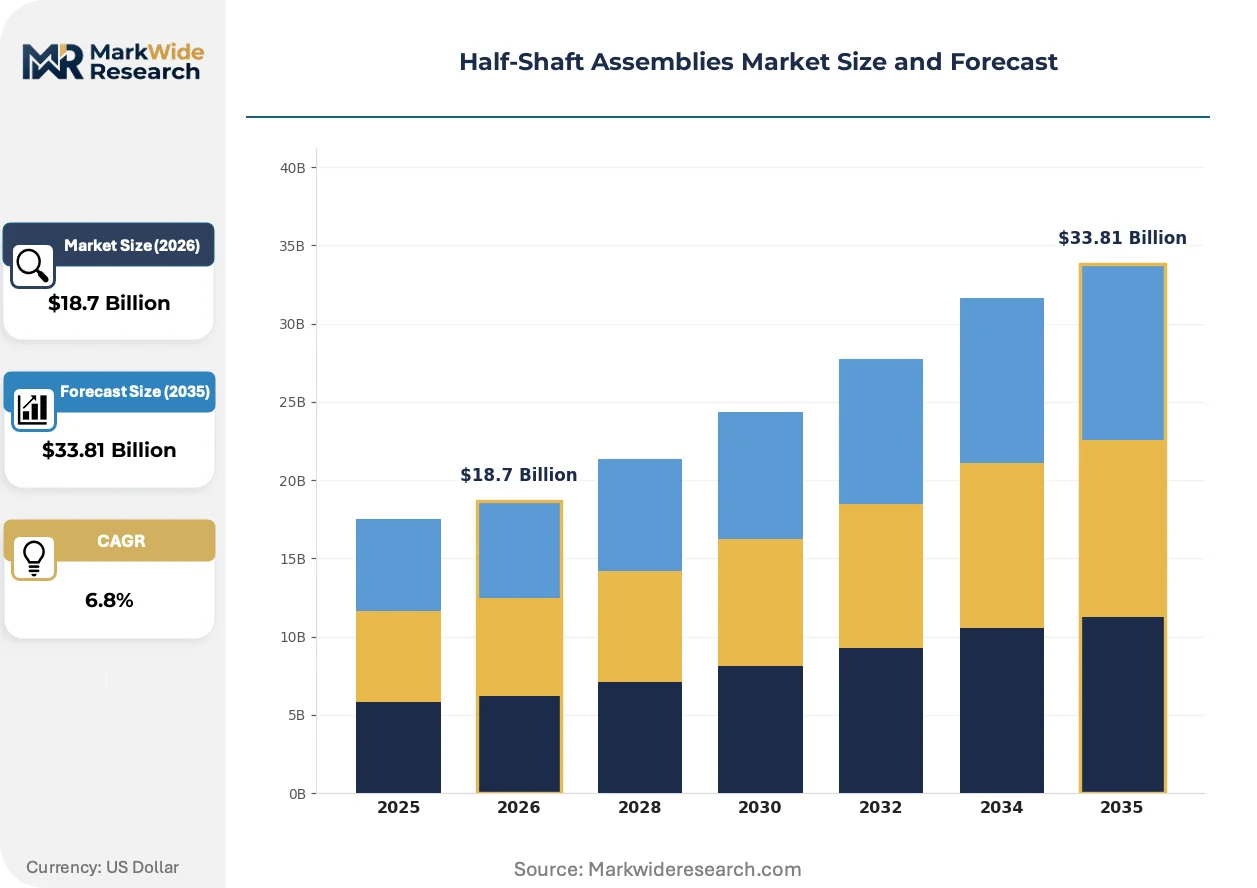
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Half-Shaft, Dead Half-Shaft, Constant Velocity Half-Shaft, Tripod Joint Half-Shaft Application: Passenger Vehicles, Commercial Vans, Utility Vehicles, Agricultural Machinery Material: Chromoly Steel, Carbon Steel, Aluminum Alloy, Composite Materials End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Component Manufacturers |
| Companies Covered | GKN Automotive, Dana Incorporated, JTEKT Corporation, ZF Friedrichshafen AG, Magna International, American Axle & Manufacturing, BorgWarner, Schaeffler Group, Hyundai WIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Half-Shaft Assemblies Market Trends and Innovations
Material science advances and regulatory pressure on vehicle mass are converging to redefine half-shaft engineering specifications across passenger and commercial vehicle platforms.
Carbon fiber-reinforced polymer hybrid shafts are integrating aluminum cores to achieve torsional stiffness targets at 40% mass reduction versus solid steel counterparts. Premium battery-electric OEMs in Germany and California are adopting these configurations for front axle applications. The technology is integrating multi-material joining processes that compress traditional forging-to-machining supply chains.
EPA Corporate Average Fuel Economy standards are tightening mass-reduction mandates that cascade into driveline component specifications. Tier-1 suppliers must document lifecycle carbon footprint per ISO 14040 frameworks to maintain OEM qualification. North American passenger vehicle programs face the steepest compliance ramps, accelerating aluminum alloy R&D spending.
Fleet operators are unbundling after-sales service contracts from initial equipment procurement, creating standalone remanufacturing revenue streams. Commercial vehicle leasing companies now specify half-shaft rebuildability clauses in supply agreements. This pattern is most visible in German long-haul trucking and North American last-mile delivery van segments.
Half-Shaft Assemblies Market Segmentation
Half-shaft assemblies require differentiated engineering specifications across torque ratings, articulation angles, and mass targets. Segmentation reveals where capital deployment concentrates and which material-product combinations command premium positioning in evolving powertrain architectures.
Product Type:
Capital intensity varies sharply across joint architectures, with constant velocity designs demanding the most sophisticated forging and precision machining infrastructure.
- Constant Velocity Half-Shaft:Incorporates ball-and-cage or Rzeppa joint geometries to transmit torque through articulation angles exceeding 45 degrees. Battery-electric platforms in Germany and California specify upgraded CV joint ratings to handle instantaneous motor torque, compressing traditional design cycles and forcing supplier retooling.
- Tripod Joint Half-Shaft:Employs three roller bearings within a tulip housing for plunging axial movement alongside angular displacement. Japanese and Korean OEMs favor tripod configurations for transverse front-drive layouts where packaging depth constraints limit ball joint diameters.
- Live Half-Shaft:Transmits torque continuously to wheels with integrated differential-side and wheel-side joint interfaces.
- Dead Half-Shaft:Serves non-driven axles primarily as structural members without torque transmission function.
Most installed capacity flows through Constant Velocity Half-Shaft. Expansion is steepest in Tripod Joint Half-Shaft.
Application:
Volume concentration tracks regional fleet composition, with passenger vehicle programs consuming the bulk of forging press hours.
- Passenger Vehicles:Encompasses sedans, crossovers, and SUVs requiring lightweight hollow shafts with induction-hardened splines. Stuttgart and Munich engineering clusters drive specification evolution for premium battery-electric architectures demanding 40% mass reduction targets.
- Commercial Vans:Covers last-mile delivery and urban freight applications where durability cycles exceed passenger duty by 3-4x. North American fleet operators now unbundle remanufacturing contracts from initial procurement, creating standalone revenue streams for forged component suppliers.
- Utility Vehicles:Includes off-road and recreational platforms articulating extreme suspension travel angles.
- Agricultural Machinery:Demands solid shaft configurations with enhanced corrosion resistance for field exposure.
Passenger Vehicles absorb the majority of production throughput. Commercial Vans are climbing the fastest as electrified urban logistics expand.
Material:
Raw material selection determines forging complexity, heat treatment protocols, and recyclability positioning under tightening environmental mandates.
- Chromoly Steel:Delivers superior fatigue resistance through chromium-molybdenum alloying with induction-hardened case depths. Legacy internal combustion drivelines in North American truck platforms retain chromoly dominance despite alloy surcharge volatility compressing margin predictability.
- Aluminum Alloy:Offers 50-60% mass reduction versus steel counterparts through hollow extrusion and friction-stir welding. EU F-Gas Regulation and carbon-emission mandates accelerate aluminum adoption as OEMs document lifecycle footprints per ISO 14040 frameworks.
- Carbon Steel:Provides cost-optimized performance for economy vehicle segments with lower torque density requirements.
- Composite Materials:Integrates carbon fiber-reinforced polymer over aluminum cores for premium mass-critical applications.
Chromoly Steel retains the largest share of forging tonnage. Aluminum Alloy is gaining share fastest under regulatory pressure.
End User:
Procurement authority concentrates with entities controlling platform architecture decisions and qualification timelines.
- OEMs:Direct half-shaft specification for proprietary axle designs with 18-24 month IATF 16949 qualification cycles. German premium OEMs cluster engineering resources around Stuttgart and Munich, compressing supplier development timelines for multi-source contracts.
- Tier-1 Component Manufacturers:Integrate half-shaft production into broader driveline system portfolios, capturing value through module-level supply. ZF Friedrichshafen AG and Dana Incorporated anchor regional supply through captive forging and machining operations.
- Aftermarket Suppliers:Serve replacement demand through remanufacturing and service part distribution.
- Vehicle Assemblers:Contract assembly operations for localized production under domestic content mandates.
OEMs command the greatest specification authority. Tier-1 Component Manufacturers are expanding most quickly through module integration strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Munich anchor engineering concentration for premium half-shaft specifications, while manufacturing disperses across cost-competitive forging centers in Asia and North America. Regulatory pressure on vehicle mass and carbon intensity is fragmenting supply chain geography. Material qualification timelines now span 18-24 months across all major production zones.
Germany
Premium battery-electric platforms from BMW and Mercedes-Benz demand 40% mass-reduced half-shaft configurations. The EU F-Gas Regulation accelerates aluminum alloy substitution in Stuttgart engineering clusters. Munich-based Tier-1 suppliers compress multi-source procurement cycles to 12 months for new joint architectures.
United States
EPA Corporate Average Fuel Economy standards tighten mass-reduction mandates for light-truck half-shaft programs. NHTSA safety regulations govern induction-hardened spline specifications for commercial van durability. Detroit-area forging operations anchor North American chromoly steel capacity despite alloy surcharge volatility.
China
Domestic EV manufacturers specify upgraded constant velocity joints for instantaneous torque transmission. MIIT dual carbon goals pressure material substitution toward aluminum and composite formulations. Yangtze River Delta forging clusters scale hollow shaft extrusion capacity for export programs.
Japan
Tripod joint architectures dominate transverse front-drive layouts from Toyota and Honda. METI carbon neutrality roadmaps align supplier R&D with friction-stir welding process development. Nagoya-area machining specialists concentrate precision spline grinding for hybrid powertrain integration.
India
Domestic OEM localization mandates under the PLI scheme create captive supply openings for forged driveline components. BIS quality frameworks govern IATF 16949 supplier qualification timelines. Tamil Nadu and Gujarat manufacturing corridors attract Tier-1 forging investments for compact SUV programs.
Half-Shaft Assemblies Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue composite material specialization and closed-loop recycling capabilities. The supplier base consolidates around three maturity tiers: global system integrators with captive forging networks, regional specialists with heat treatment expertise, and aluminum-focused challengers serving EV platforms. Strategic differentiation concentrates on multi-source contract capture, module-level integration, and geographic proximity to Stuttgart, Detroit, and Shanghai engineering clusters. Dominant competitive moves include backward integration into aluminum remelt operations and strategic partnerships for carbon fiber-reinforced polymer joint development.
Among Germany-based system integrators, ZF Friedrichshafen AG and Schaeffler Group exemplify module-level supply strategies that combine half-shaft production with broader driveline portfolios. GKN Automotive occupies a position within the global footprint archetype, leveraging multi-continental manufacturing to serve simultaneous OEM platform launches. Dana Incorporated anchors North American supply through in-house forging and machining control. These three represent distinct competitive postures: European module integration, global scale deployment, and regional vertical control.
| Leading Market Players |
|---|
| GKN Automotive |
| Dana Incorporated |
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| Magna International |
| American Axle & Manufacturing |
| BorgWarner |
| Schaeffler Group |
| Hyundai WIA |
| Others |
Pricing and Supply Chain Analysis
Friction-stir welding adoption in aluminum hollow shaft production is compressing forging-to-machining cycle times while concentrating supplier capability in Germany and China. This process transition simultaneously elevates capital barriers for new entrants and shifts pricing power toward Tier-1 suppliers with captive heat treatment infrastructure.
Pricing Analysis
Alloy surcharge pass-through from chromoly steel suppliers dominates contract negotiations, with forged component manufacturers absorbing margin compression when scrap metal volatility spikes. Three-tier pricing structure across premium, standard, and economy levels reflects IATF 16949 certification status and induction hardening capability depth. Pricing pressure stems from OEM multi-source procurement mandates that compress qualification premiums. Commercial van fleet operators exhibit highest price sensitivity due to unbundled remanufacturing contracts, while German premium OEMs prioritize mass reduction over unit cost.
Supply Chain Analysis
Induction hardening technician scarcity in Germany and Japan constrains capacity expansion despite Yangtze River Delta forging clusters scaling hollow shaft extrusion. Raw material feeds draw from chromoly steel mills in North America, aluminum smelters in China, and carbon fiber prepreg suppliers in Japan. Single-source vulnerability concentrates in specialized heat treatment infrastructure. Distribution runs through Tier-1 module suppliers to OEM axle assembly plants, with aftermarket remanufacturing channels expanding for commercial vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Half-shaft assemblies constitute a late-cycle quality story as battery-electric platforms redefine fatigue-life specifications and force material substitution toward aluminum and composite architectures. Premium OEM demand for 40% mass-reduced configurations is concentrating engineering resources and procurement authority with qualified suppliers.
For Market Incumbents: Lock in multi-source contract positions with Stuttgart and Munich engineering clusters before qualification timelines extend further. Secure captive aluminum remelt capabilities to meet EU Green Deal circular economy mandates. Defend against emerging composite specialists by accelerating Rzeppa joint R&D spending for instantaneous torque applications. For New Entrants and Emerging Players: The premium-economy price-point gap in commercial van remanufacturing services offers white-space capture potential. Target North American last-mile delivery fleet operators with rebuildability-focused value propositions. Enter through standalone aftermarket service contracts rather than direct OEM qualification to bypass 18-24 month IATF 16949 cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional heat treatment specialists with induction hardening expertise and pending certification renewals. Five-to-ten year viability hinges on aluminum alloy process development and friction-stir welding capability maturation. Monitor MIIT dual carbon goal implementation in China as inflection signal for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Remelt | EU F-Gas Regulation compliance positions suppliers for circular economy mandates from Stuttgart OEMs. |
| Multi-Material Joint Architecture Development | Carbon fiber-reinforced polymer hybrid shafts capture premium battery-electric platform specifications. |
| Induction Hardening Capacity Expansion | Specialized heat treatment infrastructure scarcity in Germany creates geographic supply risk mitigation value. |
| Remanufacturing Service Contract Unbundling | North American fleet operators now specify rebuildability clauses separate from initial equipment procurement. |
| Friction-Stir Welding Process Qualification | Aluminum hollow shaft joining technology compresses traditional forging-to-machining supply chains. |
Research Methodology
Coverage spans Germany, United States, China, Japan, and India, with primary inputs from each manufacturing cluster combining Tier-1 supplier procurement executives, OEM platform engineers, aftermarket distributors, and induction hardening specialists. Secondary validation draws from vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and ECHA REACH substance restriction updates. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers.
Rate-of-change decomposition separates volume growth from value mix shift across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from regression analysis of historical production data against regulatory mandate timelines and OEM platform launch schedules. Forecast inputs incorporate EPA Corporate Average Fuel Economy compliance ramps and MIIT dual carbon goal implementation trajectories.
Caveats apply where EU F-Gas Regulation enforcement intensity or chromoly steel alloy surcharge volatility could materially shift the outlook. Forecasts embed assumptions regarding IATF 16949 qualification timeline stability and induction hardening technician pipeline development. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market
Automotive Assemblies
Africa Automotive Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Automotive Grille Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Manifold Assembly Market