
 Automotive Idler Arm Market | 2026-2036
Automotive Idler Arm Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Idler Arm Market Intelligence
The adoption of heavy-duty idler arms for commercial truck and bus applications is unwinding the market's previous focus on standard passenger car components. This shift creates opportunities for specialized suppliers. ZF Friedrichshafen AG leverages its extensive OEM relationships to supply integrated steering systems for new vehicle platforms. Separately, Moog Inc. specializes in high-performance aftermarket components, targeting demanding repair and fleet upgrade channels.
An automotive idler arm is a pivoting support component within a vehicle’s parallelogram steering linkage system. It typically incorporates a bushing or bearing assembly to allow for smooth rotational movement. Its primary function is to support the center link at the correct height, ensuring precise steering geometry and vehicle control. While the aftermarket for passenger vehicles represents a high-volume base, the OEM channel for heavy-duty commercial vehicles offers higher margins and demands more robust material specifications.
Regulatory frameworks from the U.S. NHTSA and similar bodies in Europe under CE marking rules define stringent safety requirements. These standards, along with China's GB standards, mandate durability and failure testing for all safety-critical steering parts. Component manufacturers must now balance the cost of advanced materials against the performance demands of evolving vehicle architectures.
Market Dynamics
The market's central tension is the divergence between high-volume aftermarket needs and the specialized, high-margin demands of the commercial vehicle OEM channel. This split requires suppliers to manage distinct strategies for advanced, lightweight materials versus cost-effective standard components.
Growth Catalysts
- Commercial Vehicle Expansion:Growth in logistics and transportation sectors globally increases the production and service life of trucks and buses, directly boosting demand for durable idler arms.
- Stringent Safety Mandates:Regulations from bodies like the U.S. NHTSA and China's GB standards require rigorous failure testing, favoring manufacturers with certified, high-quality components.
- Manufacturing Hub Concentration:Production in automotive centers like Germany provides suppliers with direct access to large OEM customers and a robust export infrastructure for aftermarket parts.
Market Restraints
- Advanced Material Costs:The higher price of aluminum and composite materials compared to traditional steel creates a cost barrier for adoption, particularly in the price-sensitive passenger vehicle aftermarket.
- Substitution by Alternative Steering Systems:The prevalence of rack-and-pinion steering in modern passenger cars and light trucks structurally limits the market to vehicles using parallelogram linkage systems.
- Design Obsolescence:As vehicle platforms are retired, the specific idler arm designs for those models become obsolete, requiring constant retooling for new platforms.
Strategic Opportunities
- High-Performance Aftermarket:There is a clear opportunity to supply specialized, heavy-duty idler arms for fleet upgrades and repair channels focused on performance and longevity over lowest cost.
- Integrated System Supply:Suppliers can move up the value chain by offering complete steering linkage modules, including the idler arm, to OEMs for new vehicle platforms.
- Lightweighting for Electric Commercial Vehicles:The development of electric trucks and buses creates demand for lightweight components to offset battery weight, opening a niche for composite idler arms.
Industry Challenges
- Certification Delays:Navigating the complex and lengthy certification processes for safety-critical components under different international standards like CE marking can delay product launches.
- Manufacturing Process Adaptation:Shifting production from forged steel to cast aluminum or molded composites requires significant capital investment in new machinery and workforce retraining.
- Material Specification Complexity:Balancing the cost, weight, and durability requirements for different vehicle applications and regions complicates material sourcing and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Idler Arm Market |
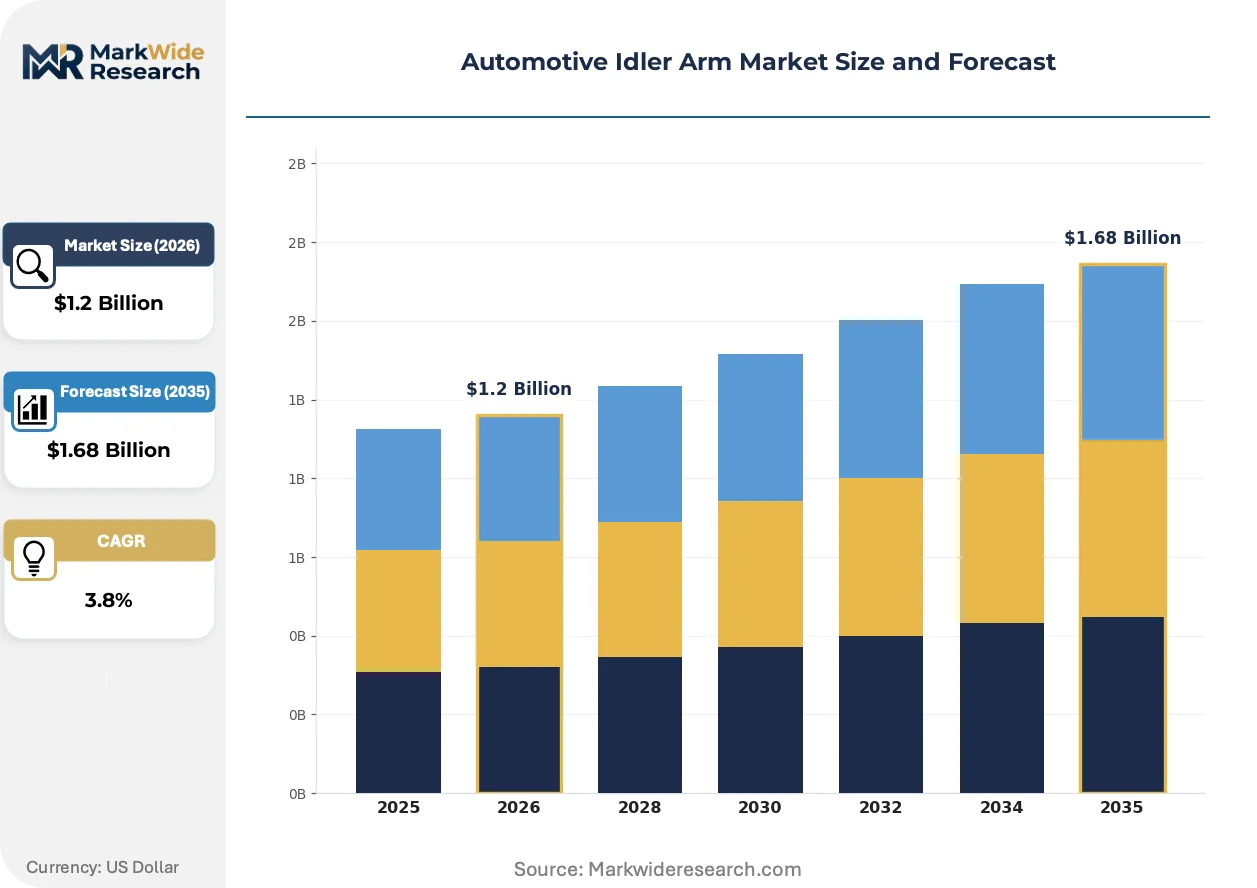
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.68 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Heavy-Duty, Light-Duty, Adjustable Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, Electric Vehicles Material: Steel, Aluminum, Carbon Fiber, Composite Installation Type: OEM, Aftermarket, Retrofit, Custom |
| Companies Covered | ZF Friedrichshafen AG, Moog Inc., ACDelco, Dorman Products, TRW Automotive, Denso Corporation, Continental AG, Mevotech, Sankei Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Idler Arm Market Strategic Shifts & Innovations
Material science advancements and divergent end-market requirements are bifurcating the idler arm market. A split is emerging between cost-driven aftermarket components and performance-engineered OEM parts for heavy-duty applications, reshaping supplier value propositions.
Composite materials, including glass-fiber reinforced polymers, offer a lightweight alternative to traditional forged steel idler arms. Commercial vehicle OEMs are adopting these solutions to improve fuel efficiency and increase payload capacity on new truck platforms. The proliferation of composite, aluminum, and steel options is fragmenting the material specification landscape, complicating procurement for multi-platform suppliers.
CE marking rules in Europe establish stringent safety and performance requirements for all critical automotive steering components. This compels manufacturers to provide extensive documentation on material traceability, durability testing, and failure mode analysis. The heavy-duty commercial vehicle segment is most impacted, pushing suppliers to invest in advanced quality control systems to maintain access to the European market.
A behavioral shift is occurring in the aftermarket, where large fleet maintenance operators increasingly prefer sourcing complete steering linkage kits. This model disrupts the traditional channel of selling individual components, favoring suppliers who can bundle idler arms with related parts like tie rods. This trend is most prominent in North America, driven by a focus on reducing vehicle downtime and simplifying repair logistics.
Automotive Idler Arm Market Segmentation
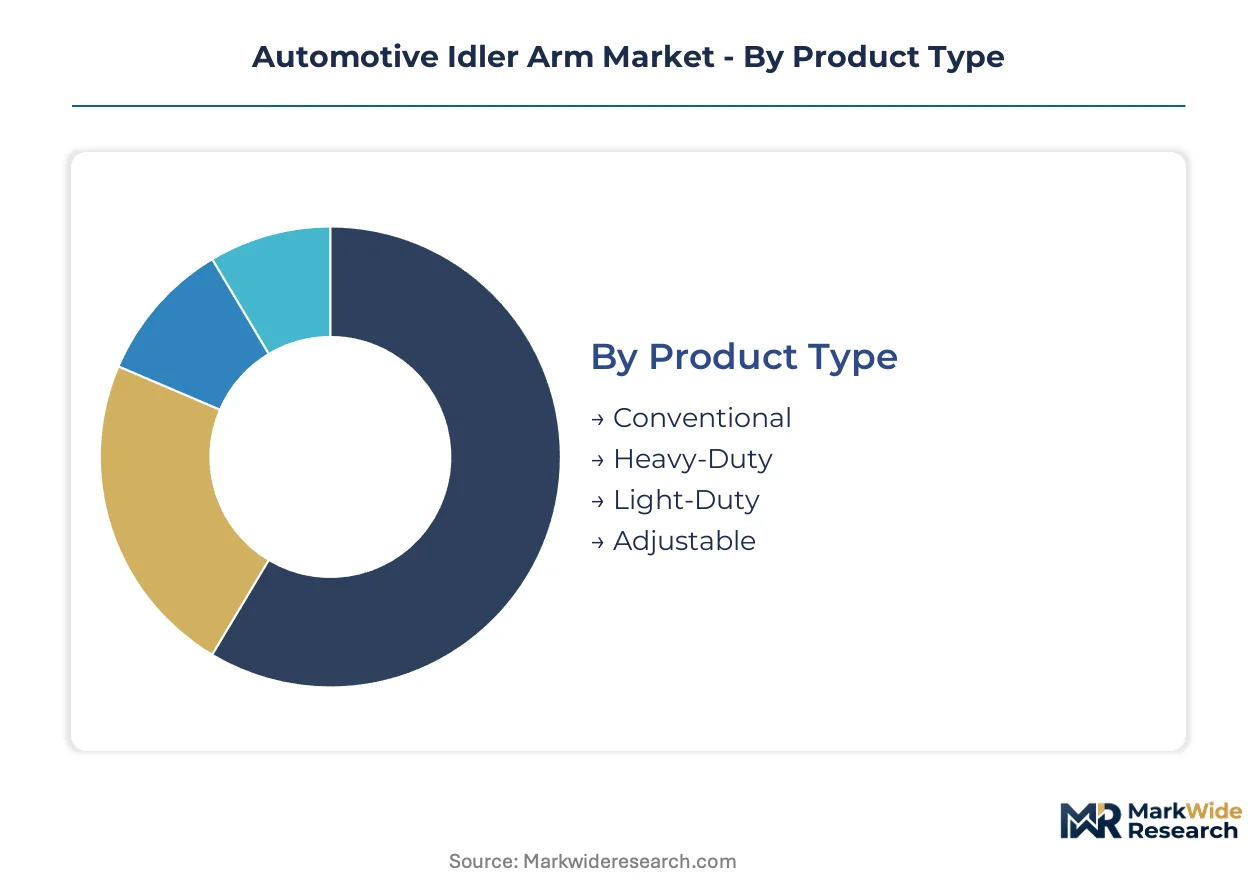
The Automotive Idler Arm Market segmentation reveals the diverse product specifications and end-user requirements driving component evolution. Understanding these distinct segments assists manufacturers in tailoring product development and market strategies. This granular analysis highlights where value creation and demand concentration are occurring across the industry.
Product Type:
The product type segmentation reflects how idler arms are engineered for specific vehicle classes and their intended distribution channels.
- Heavy-Duty:These idler arms feature reinforced construction and robust materials, often steel or high-strength composites, designed for sustained high-stress operation. Demand concentrates in the commercial vehicles sector, particularly for trucks and buses, where durability requirements are stringent.
- Conventional:Standard idler arms are typically forged steel components manufactured for broad compatibility with older passenger vehicle models. Their volume demand is sustained in the aftermarket, serving routine repair and replacement needs across various global regions.
- Light-Duty:These idler arms cater to smaller passenger cars, emphasizing cost-effectiveness and sufficient performance for lighter vehicle loads.
- Adjustable:Adjustable idler arms allow for fine-tuning of steering geometry, primarily used in specialized performance applications or custom vehicle builds.
By volume, Conventional idler arms lead due to their widespread use; Heavy-Duty components represent the fastest-growing trajectory, driven by commercial vehicle expansion.
Application:
Application segmentation differentiates idler arm usage based on specific vehicle customer types and their operational demands.
- Commercial Vehicles:These applications require idler arms engineered for continuous heavy loads and extensive mileage, often incorporating advanced materials for enhanced longevity. Demand is strong in logistics hubs like Germany and across growing transportation networks globally.
- Passenger Vehicles:Idler arms for passenger cars prioritize smooth operation and standard durability, fitting a wide range of everyday driving conditions. This segment maintains a significant aftermarket presence, particularly for older model replacements.
- Off-Road Vehicles:Idler arms in off-road vehicles require extreme durability and impact resistance to withstand harsh terrains and demanding operational environments.
- Electric Vehicles:This emerging application segment seeks lightweight idler arms to offset battery weight, potentially driving innovation in composite materials.
Supply for Commercial Vehicles concentrates among specialized OEM suppliers, while Passenger Vehicle idler arms are widely available across numerous aftermarket channels.
Material:
The material segmentation reflects varying cost structures and performance characteristics influencing idler arm design and manufacturing processes.
- Steel:Traditionally, idler arms are forged from high-strength steel, offering a cost-effective and robust solution for most vehicle applications. This material dominates the aftermarket due to its proven reliability and lower production cost.
- Composite:Composite materials, such as glass-fiber reinforced polymers, offer significant weight reduction benefits crucial for improving fuel efficiency and increasing payload capacity. This material is increasingly adopted by commercial vehicle OEMs for new platform development.
- Aluminum:Aluminum idler arms provide a balance of lightweighting and strength, finding use in specific passenger vehicle models and some heavy-duty applications.
- Carbon Fiber:Carbon fiber offers superior strength-to-weight ratios, though its high cost limits current adoption to niche, high-performance, or specialized vehicle segments.
Steel materials account for the largest volume of idler arm production, while composite materials command higher value due to their advanced properties and manufacturing complexity.
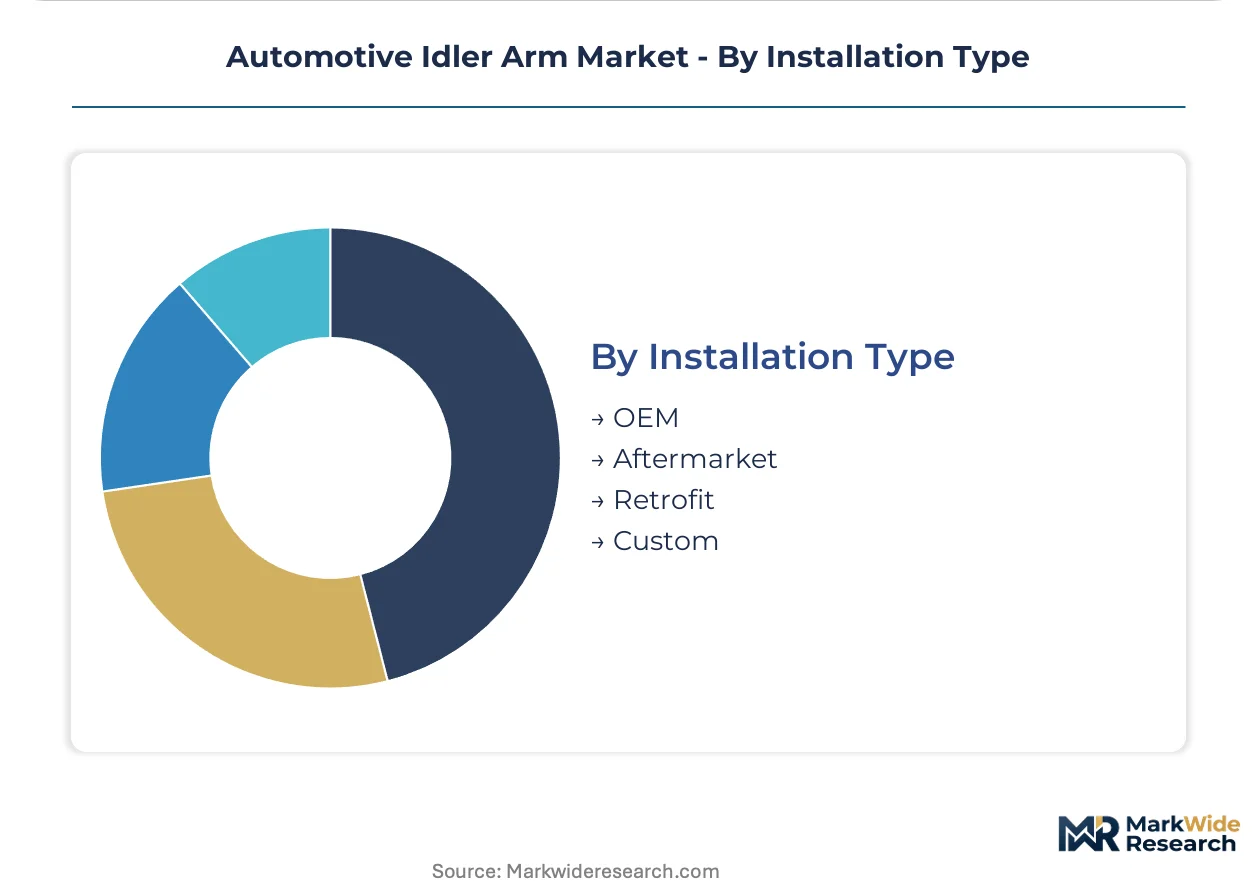
Installation Type:
Installation type segmentation highlights the distinct margin profiles and customer purchasing behaviors across different supply chains for idler arms.
- OEM:Original Equipment Manufacturer (OEM) idler arms are supplied directly to vehicle assembly lines, demanding stringent quality control and integrated system compatibility. This channel offers higher margins due to long-term contracts and design-in specifications for new vehicle platforms.
- Aftermarket:The aftermarket comprises replacement idler arms sold for vehicle repair and maintenance, catering to a vast installed base of passenger and commercial vehicles. This segment is highly price-sensitive but represents significant volume for standard components.
- Retrofit:Retrofit idler arms are designed to upgrade or modify existing vehicle systems, often targeting performance enhancements or specific operational improvements.
- Custom:Custom idler arms are bespoke solutions for unique vehicle builds or highly specialized applications, characterized by low volume and high unit cost.
OEM supply concentrates among a few large, integrated manufacturers, whereas the Aftermarket features a broader base of suppliers competing on price and availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Automotive Idler Arm Market demonstrates a clear demand-elasticity contrast, with aftermarket segments exhibiting higher price sensitivity compared to the premium OEM channel for heavy-duty commercial vehicles. This divergence drives regional specialization in manufacturing and distribution strategies. Demand for robust, high-performance components concentrates in established automotive manufacturing hubs, while cost-effective standard parts serve widespread repair needs.
Germany
Demand for advanced idler arms in Germany stems from its significant commercial vehicle production and export activities. CE marking rules mandate stringent safety and performance standards for all automotive components sold within the European Union. Automotive clusters in Bavaria and Baden-Württemberg drive innovation in integrated steering systems for new vehicle platforms.
China
China's expanding logistics and transportation sectors create substantial demand for durable heavy-duty idler arms. The country's GB standards enforce rigorous durability and failure testing for all safety-critical steering parts. Manufacturing hubs in the Yangtze River Delta and Pearl River Delta lead in both OEM supply and a vast aftermarket for commercial and passenger vehicles.
United States
The United States market sees strong demand for both high-volume aftermarket components and specialized heavy-duty idler arms for commercial fleets. The U.S. NHTSA sets comprehensive safety regulations, influencing design and material specifications for steering components. Major automotive manufacturing regions, including the Detroit metropolitan area, remain central for OEM procurement and supply chain coordination.
India
India's rapidly expanding commercial vehicle sector, fueled by infrastructure development, significantly boosts the demand for robust idler arms. Government initiatives like the Production-Linked Incentive (PLI) scheme encourage domestic manufacturing of automotive components. Industrial corridors around Chennai and Pune are emerging as key production centers for both OEM and aftermarket parts.
Japan
Japanese automotive manufacturers prioritize precision engineering and long-term reliability, driving demand for high-quality idler arms in new vehicle platforms. The country's stringent JIS standards ensure component quality and performance across the automotive supply chain. The Nagoya region, a prominent automotive manufacturing cluster, remains a core hub for steering component innovation and production.
Automotive Idler Arm Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the Automotive Idler Arm Market, reflecting the split between OEM and aftermarket requirements. The market exhibits a tiered structure, with integrated system suppliers dominating the OEM segment and a broader base of manufacturers competing in the aftermarket. Strategic archetypes include global Tier-1 suppliers, specialized aftermarket providers, and regional component manufacturers. Dominant competitive moves include strategic partnerships for new vehicle platforms and portfolio diversification across vehicle types.
Integrated system suppliers, like ZF Friedrichshafen AG, exemplify the OEM-focused approach, leveraging extensive relationships to supply complete steering solutions for new vehicle platforms. Separately, Moog Inc. occupies a position as a specialist in high-performance aftermarket components, targeting demanding repair and fleet upgrade channels. ACDelco represents a broad aftermarket presence, offering a wide range of standard replacement parts for passenger and commercial vehicles.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Moog Inc. |
| ACDelco |
| Dorman Products |
| TRW Automotive |
| Denso Corporation |
| Continental AG |
| Mevotech |
| Sankei Industries Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Economies of scale in steel forging for conventional idler arms drive supply concentration among large manufacturers, establishing competitive price floors across the aftermarket. This scale advantage influences both material sourcing and distribution efficiency.
Pricing Analysis
CE marking rules dictate the pricing tier structure for idler arms, particularly for high-performance commercial vehicle components in Europe. Pricing operates on a hybrid model, combining long-term OEM contracts with transactional sales in the aftermarket. Quality grade and certification level are primary price differentiation drivers. Cost compression in the conventional aftermarket is intensifying due to high volume production, making passenger vehicle owners highly price-sensitive compared to commercial fleet operators.
Supply Chain Analysis
Inventory management and lead-time optimization are critical due to the diverse material specifications and global distribution requirements for idler arms. Geographic supply concentration for steel components centers on China and India, while specialized composite production occurs in Germany. Raw material dependencies include high-grade steel alloys and advanced resins for composites. Single-source vulnerability for specific OEM-designed components represents a structural supply chain risk. Distribution runs through both direct OEM channels and a fragmented aftermarket network.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive idler arm market is at a platform-economics inflection point, driven by the shift towards integrated steering systems in new electric vehicle architectures. This evolving ecosystem demands greater interoperability between components.
For Market Incumbents: Consolidate market share through strategic acquisitions of specialized composite material manufacturers to counter lightweighting entrants. Invest in advanced quality control systems to meet stringent CE marking rules, securing OEM contracts for electric commercial vehicle platforms. Enhance R&D into predictive maintenance sensors for existing idler arm designs, extending product lifecycles.
For New Entrants and Emerging Players: Service-layer gaps exist in providing specialized, high-performance aftermarket idler arms for fleet upgrades in North America. Target the off-road vehicle segment and customized heavy-duty applications where standard components underperform. A go-to-market angle focusing on extended warranty and proven durability can differentiate offerings.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with long-term OEM contracts for heavy-duty commercial vehicle components. Long-term viability in this market favors companies with robust R&D capabilities in lightweight materials and integrated system design over the next decade. An ideal acquisition target archetype would be a mid-sized specialist in composite manufacturing with established OEM relationships. The signal to watch is the increasing share of composite idler arms in new commercial vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces manufacturing complexity and costs across diverse vehicle models, improving supply chain efficiency. |
| Composite Material R&D | Develops lightweight components crucial for electric vehicle efficiency and increased payload capacity. |
| Aftermarket Kit Bundling | Simplifies procurement for fleet operators, reducing downtime and streamlining repair logistics in North America. |
| Regulatory Compliance Investment | Ensures market access in Europe and the US by meeting stringent safety and durability standards. |
| Global Manufacturing Footprint | Mitigates geopolitical supply risks and optimizes production for regional market demands in China and India. |
Research Approach
Initial hypotheses were tested against primary input from OEM procurement managers, Tier 1 component engineers, aftermarket distributors, and fleet maintenance directors, and refined through iterative feedback. This qualitative data was triangulated with extensive secondary validation from public company filings, automotive production databases, and industry association reports. Bottom-up market sizing was cross-referenced with top-down macroeconomic indicators to ensure accuracy.
Variance decomposition identified key drivers impacting idler arm demand across the analysis window, including commercial vehicle production rates and material cost fluctuations. The analytical framework modeled market segments by product type, application, material, installation type, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, projected technological adoption, and anticipated shifts in vehicle parc composition. Forecast inputs included steel and composite material prices, and electric vehicle adoption curves.
Forecasts assume regulatory continuity in U.S. NHTSA and CE marking regimes; material policy shifts would require re-modeling. Geopolitical instability impacting raw material supply chains or significant shifts in vehicle electrification timelines represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Structural Sheet Market
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Automotive Roof Rails Market