
 Automotive Tube Bending and Assembly Parts Market | 2026-2036
Automotive Tube Bending and Assembly Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tube Bending and Assembly Parts Market Analysis
OEM-grade precision tolerances is reorganizing procurement patterns across the Automotive Tube Bending and Assembly Parts landscape. Continental AG leverages captive metallurgy labs to sustain tight bend-angle consistency for fuel injection lines. Magna International anchors North American supply through dedicated tube-forming cells serving light-truck hydraulic circuits. Bosch differentiates via in-house production of stainless-steel exhaust manifolds with robotic orbital welding.
Automotive tube bending and assembly parts encompass formed metallic conduits, joining hardware, and structural supports engineered to tight dimensional tolerances, typically fabricated through CNC rotary draw bending, mandrel forming, and laser welding for fluid conveyance and chassis integration. Aluminum tube benders occupy the fastest-expanding material tier as OEMs pursue mass reduction for battery thermal management circuits. Exhaust system applications retain the largest volume share but carry thinning margins as catalytic converter counts decline in electrified powertrains.
NHTSA crashworthiness standards and EPA emissions compliance shape wall-thickness and alloy specifications for fuel and exhaust tubing across the United States. ECHA REACH restrictions on hexavalent chromium plating force European suppliers to convert to trivalent alternatives or zinc-nickel coatings for corrosion protection. Stakeholders must monitor how Euro 7 particulate limits and evolving EPA greenhouse-gas rules redirect engineering resources from internal-combustion fluid lines toward battery cooling and hydrogen distribution architectures.
Market Dynamics
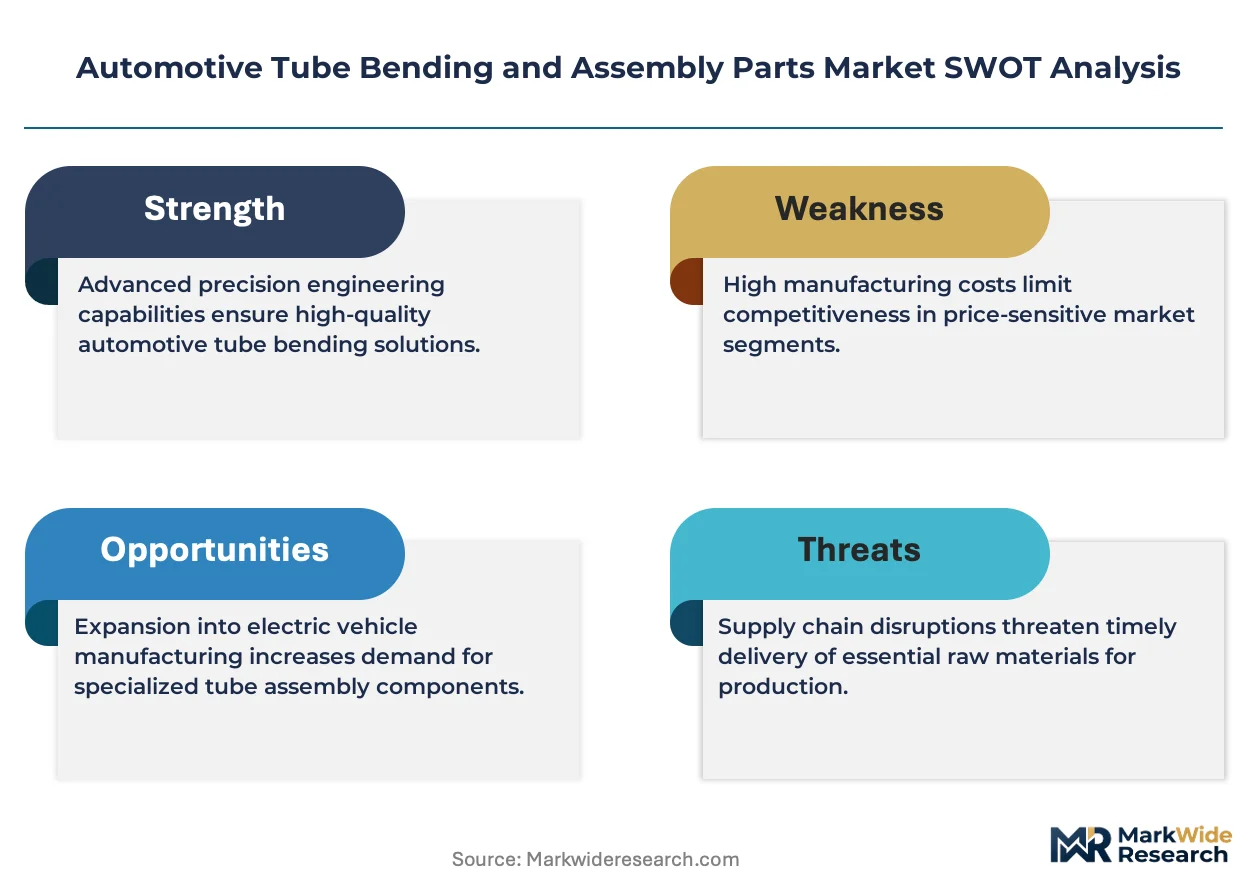
Powertrain electrification is collapsing demand for traditional fuel and exhaust tubing while simultaneously creating urgent need for precision thermal management circuits in battery packs. This structural pivot is forcing tube bending specialists to retool capabilities and renegotiate long-term supply agreements with OEMs.
Growth Catalysts
- Euro 7 particulate mandates:European OEMs require redesigned exhaust architectures with tighter bend tolerances and higher-grade alloys, sustaining premium tube demand despite electrification headwinds.
- Aluminum mandrel forming:Battery thermal management circuits favor lightweight aluminum tube benders for coolant distribution loops, opening material-tier expansion for established suppliers.
- German supplier ecosystem density:Volkswagen, BMW, and Mercedes-Benz maintain concentrated procurement relationships in Baden-Württemberg and Bavaria, anchoring precision forming capacity.
Market Restraints
- Nickel and molybdenum price volatility:Stainless-steel exhaust manifolds face margin compression when alloy markets spike, squeezing tier-two fabricators without long-term hedging.
- Supplier concentration in Baden-Württemberg:German automotive clusters create geographic vulnerability to regional energy disruptions or logistics bottlenecks.
- Hexavalent chromium plating bans:ECHA REACH restrictions force coating conversion costs onto European suppliers already managing thin margins on legacy exhaust programs.
Strategic Opportunities
- Hydrogen distribution architectures:High-pressure hydrogen fuel lines for commercial vehicles require new forming tolerances and sealing technologies, creating first-mover advantage for certified suppliers.
- India PLI scheme for EV components:Domestic manufacturing incentives attract tube bending investment for two-wheeler and three-wheeler battery cooling circuits.
- Robotic orbital welding integration:Convergence of automated welding with real-time bend-angle feedback enables lights-out production for OEM direct-supply contracts.
Industry Challenges
- CNC programming specialization:Rotary draw bending for complex battery pack geometries requires rare cross-training in metallurgy and parametric modeling, constraining workforce scalability.
- Dual certification timelines:Suppliers must simultaneously pursue NHTSA crashworthiness validation and EPA emissions compliance for North American programs, stretching engineering bandwidth.
- Legacy hydraulic circuit integration:Light-truck platforms retain mixed powertrain portfolios, forcing tube suppliers to maintain parallel production lines for fluid and thermal systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tube Bending and Assembly Parts Market |
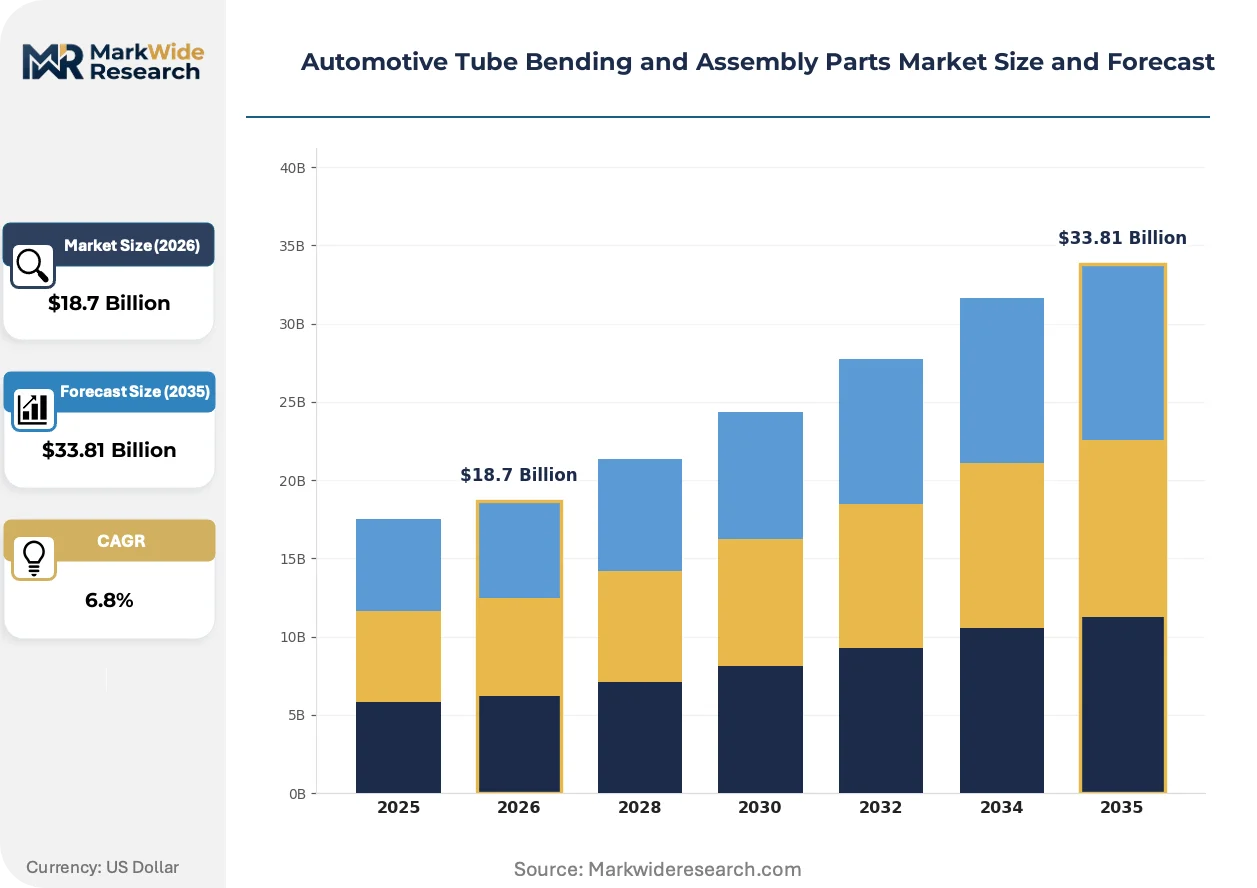
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tube Benders, Fasteners, Fittings, Brackets Material: Aluminum, Stainless Steel, Carbon Steel, Plastic End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Exhaust Systems, Fuel Lines, HVAC Systems, Hydraulic Systems |
| Companies Covered | Denso Corporation, Continental AG, Magna International, Bosch, Faurecia, Aisin Seiki, Thyssenkrupp AG, Tenneco, Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tube Bending and Assembly Parts Market Emerging Trajectories
Digital thread integration from CAD to shop-floor bending machines is compressing prototype-to-production cycles. Real-time quality telemetry and predictive maintenance algorithms are becoming baseline competitive requirements rather than differentiators.
Laser-assisted tube bending with in-process thermal profiling is displacing conventional mandrel forming for ultra-high-strength steel exhaust components. Tier-one suppliers in Germany and Japan are adopting this technology to meet Euro 7 wall-thickness specifications without springback degradation. The process is displacing older hydraulic press methods in premium vehicle programs where dimensional repeatability commands price premiums.
EPA greenhouse-gas rules for model year 2027 and beyond are tightening fleet-average emissions benchmarks. OEMs are responding by extending turbocharged downsized engine architectures that require more complex intercooler and EGR tubing geometries. North American suppliers are reconfiguring bend-cell layouts to accommodate shorter production runs across diversified engine variants.
Fleet procurement departments are consolidating tube assembly sourcing under systems-integration contracts rather than discrete component purchasing. Tier-one suppliers now bid on complete fluid-handling modules encompassing formed tubes, joining hardware, and sensor integration. This pattern is most pronounced in German and US Midwest automotive corridors where OEMs seek single-source accountability for thermal and fuel system performance.
Automotive Tube Bending and Assembly Parts Market Segmentation
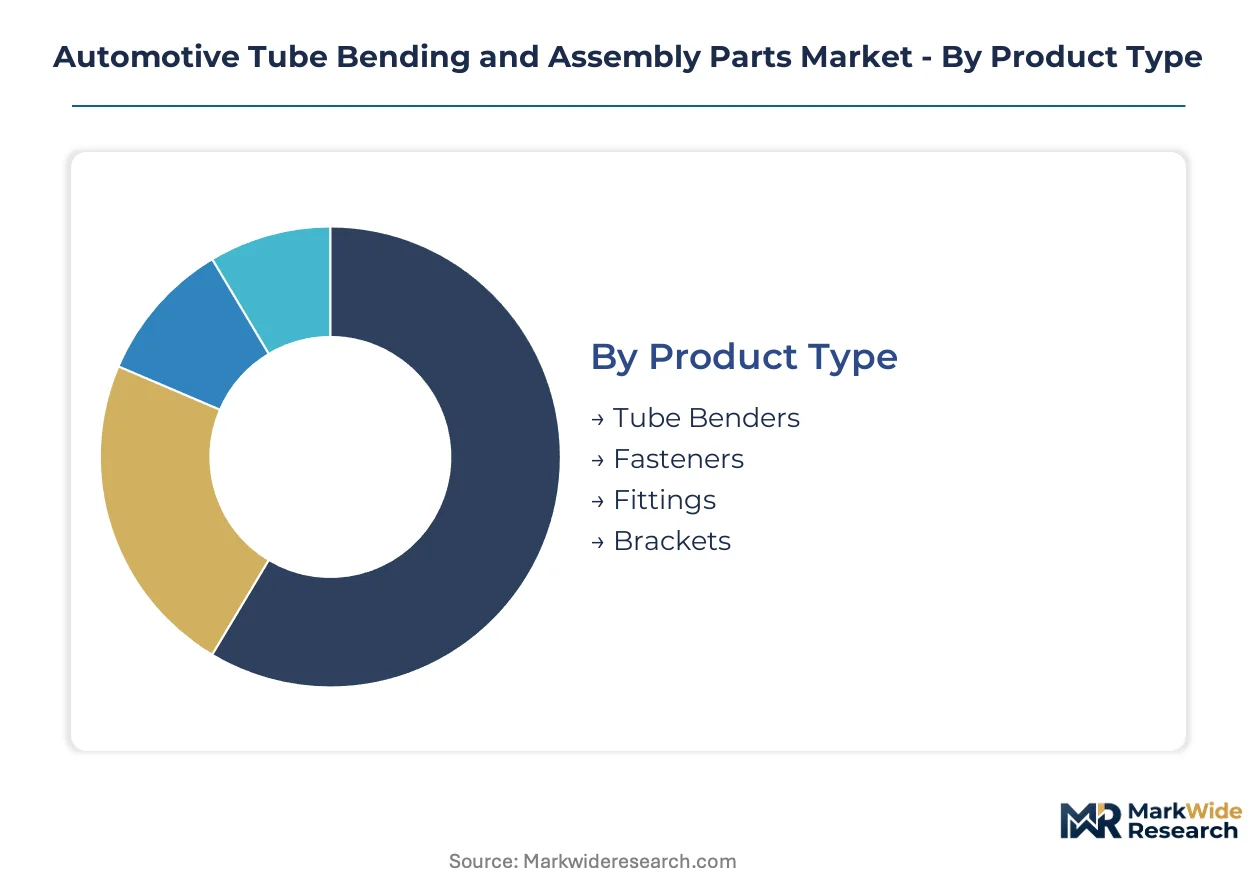
Tube bending and assembly parts flow through distinct procurement channels depending on precision requirements and volume scale. Each segmentation dimension reveals how supplier capabilities align with OEM thermal management strategies and emissions compliance architectures.
Product Type:
Tube benders dominate direct OEM supply channels where precision tolerances command premium positioning, while fasteners and fittings concentrate in tier-one module assembly contracts.
- Tube Benders:CNC rotary draw bending equipment produces formed conduits for fuel injection, exhaust, and battery cooling circuits. German OEMs in Stuttgart and Munich source these through captive supplier parks requiring real-time bend-angle telemetry. Demand concentrates in aluminum configurations for EV thermal management loops.
- Fasteners:Joining hardware for tube-to-tube and tube-to-chassis connections. North American light-truck manufacturers procure these through systems-integration contracts bundling formed tubes with attachment hardware. EPA emissions validation requirements drive specification tightening.
- Fittings:Sealed connection points for fluid and gas conveyance. European suppliers convert hexavalent chromium plating to trivalent alternatives under ECHA REACH mandates, adding conversion costs.
- Brackets:Structural mounting supports for chassis integration. Aftermarket channels absorb surplus capacity from OEM programs.
By volume, tube benders lead. By growth pace, aluminum-configured benders for battery cooling are expanding most quickly.
Material:
Cost tiers separate premium alloy grades from commodity carbon steel, with procurement patterns diverging across thermal performance requirements.
- Aluminum:Lightweight alloy for battery thermal management circuits. Mandrel forming achieves tight bend radii without wall thinning. German and Japanese OEMs specify this grade for coolant distribution loops in electrified platforms.
- Stainless Steel:Corrosion-resistant grade for exhaust manifolds and EGR tubing. Nickel and molybdenum price volatility squeezes tier-two fabricators without hedging programs. Euro 7 particulate mandates sustain demand despite powertrain electrification.
- Carbon Steel:Cost-optimized grade for structural brackets and non-corrosive environments. Volume production serves legacy internal-combustion programs.
- Plastic:Polymer alternatives for low-pressure HVAC ducts and cabin air routing. Limited thermal tolerance constrains underhood deployment.
Aluminum claims the steepest expansion trajectory as mass reduction targets intensify. Stainless steel retains the largest revenue base.
End User:
Customer type determines specification authority, with OEMs holding direct design control over safety-critical fluid systems.
- OEMs:Vehicle manufacturers specify precision tolerances for fuel, exhaust, and thermal management circuits. Volkswagen, BMW, and Mercedes-Benz maintain dense supplier ecosystems in Baden-Württemberg and Bavaria.
- Tier-1 Suppliers:Systems integrators bundle tube forming with joining hardware and sensor modules. Magna International and Continental AG anchor North American and European supply respectively.
- Aftermarket Providers:Replacement part distributors serve aging vehicle populations. Channels absorb excess capacity from OEM production runs.
- Vehicle Assemblers:Contract manufacturers for regional markets. Procurement concentrates on cost-optimized carbon steel configurations.
OEMs and tier-one suppliers command specification authority. Aftermarket channels show the fastest volume climb as vehicle parc ages.
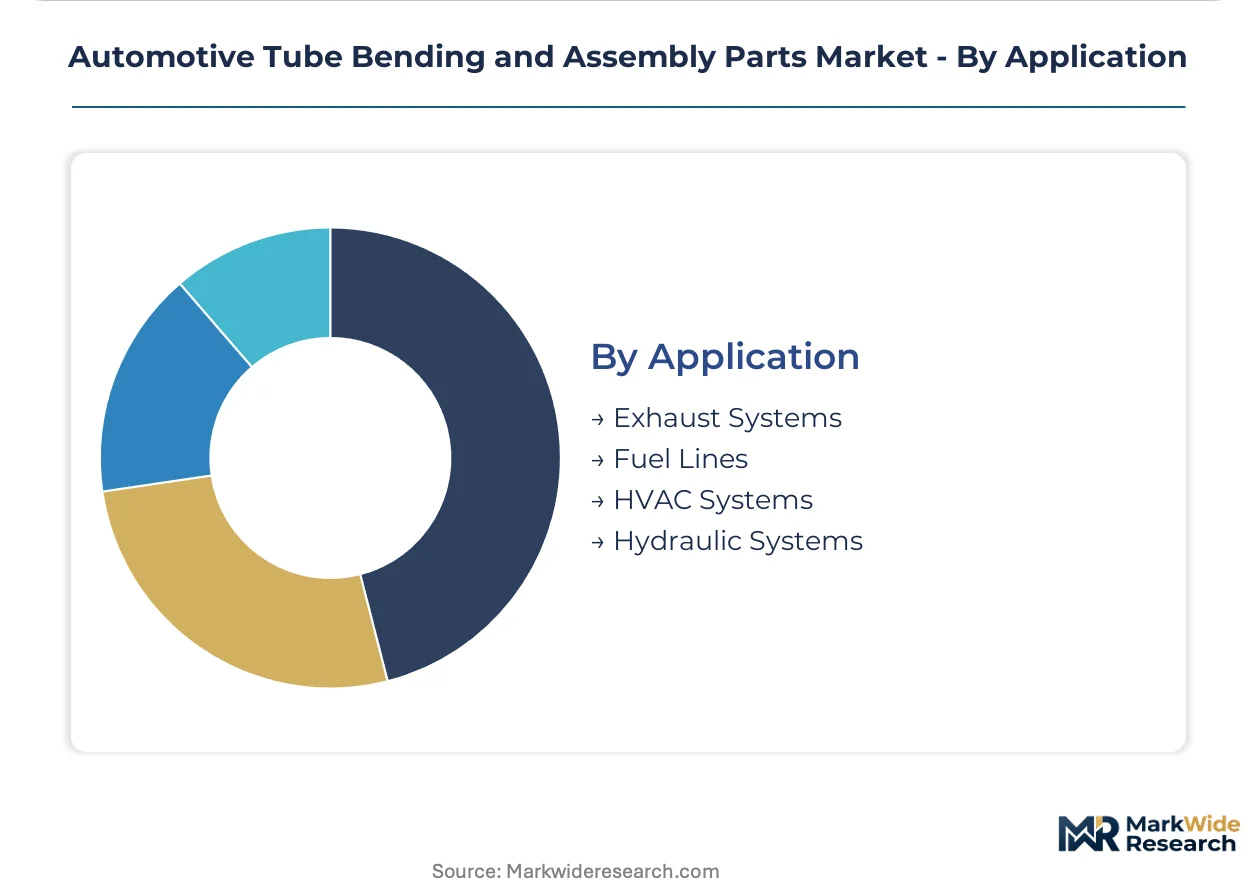
Application:
Maturity stages separate declining exhaust applications from emerging battery thermal systems, with margin profiles inversely correlated to technology vintage.
- Exhaust Systems:Formed tubing for catalytic converters, mufflers, and tailpipe architectures. Euro 7 particulate limits force wall-thickness reductions and higher-grade alloy specifications. Catalytic converter counts decline in electrified powertrains.
- Fuel Lines:High-pressure injection tubing and return circuits. NHTSA crashworthiness standards mandate specific wall thicknesses and routing protections. Demand contracts as battery-electric penetration rises.
- HVAC Systems:Climate control tubing for cabin thermal management. Plastic and aluminum configurations dominate this segment.
- Hydraulic Systems:Brake lines and power steering circuits for light-truck platforms. Mixed powertrain portfolios force parallel production lines.
Exhaust systems retain volume leadership. Battery cooling circuits—captured within HVAC and emerging thermal segments—gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural surplus in precision tube bending exports, while the United States and China balance import dependence against domestic capacity expansion for EV thermal systems.
Germany
Volkswagen, BMW, and Mercedes-Benz sustain dense supplier ecosystems for mandrel-formed aluminum cooling circuits. ECHA REACH restrictions on hexavalent chromium plating force coating conversion investments across Baden-Württemberg fabricators. Stuttgart and Munich anchor captive supplier parks requiring real-time bend-angle telemetry for fuel injection lines.
United States
EPA greenhouse-gas rules for model year 2027 tighten fleet-average benchmarks, extending demand for complex intercooler and EGR tubing geometries. NHTSA crashworthiness standards mandate specific wall thicknesses for fuel line routing protections. Michigan and Ohio reconfigure bend-cell layouts to accommodate shorter production runs across diversified engine variants.
China
Domestic EV manufacturers expand orders for lightweight fluid-handling assemblies as OEMs face dual carbon goals and MIIT efficiency mandates. GB standards for vehicle safety shape alloy specifications for battery thermal management circuits. The Yangtze River Delta concentrates CNC rotary draw bending capacity serving BYD and CATL supplier networks.
Japan
METI industrial policy prioritizes hydrogen distribution infrastructure for commercial vehicles, creating demand for high-pressure fuel line forming technologies. JIS standards govern dimensional tolerances for precision exhaust components. Toyota City and Nagoya maintain specialized orbital welding clusters for stainless-steel manifold production.
India
The PLI scheme for EV components attracts tube bending investment for two-wheeler and three-wheeler battery cooling circuits. BIS certification requirements shape material specifications for domestic thermal management systems. Tamil Nadu and Gujarat emerge as concentrated fabrication zones for export-oriented OEM supply contracts.
Automotive Tube Bending and Assembly Parts Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology access. The vendor base splits between diversified automotive suppliers with captive metallurgy labs and independent fabricators serving aftermarket channels. Three archetypes dominate: systems integrators bundling tube forming with sensor modules, precision specialists with dedicated bend-cell configurations, and diversified conglomerates leveraging backward integration into alloy production. Competitive moves concentrate on robotic welding integration and geographic expansion into Indian PLI zones.
Among diversified automotive suppliers, Continental AG, Magna International, and Bosch exemplify contrasting strategic positions. Continental AG represents the European systems-integrator archetype with captive metallurgy capabilities. Magna International anchors North American supply through dedicated production cells. Bosch occupies the diversified conglomerate tier with in-house stainless-steel fabrication. These three illustrate how scale, geographic focus, and vertical scope segment competitive positioning across OEM direct-supply channels.
| Leading Market Players |
|---|
| Denso Corporation |
| Continental AG |
| Magna International |
| Bosch |
| Faurecia |
| Aisin Seiki |
| Thyssenkrupp AG |
| Tenneco |
| Hyundai Mobis |
| Others |
Supply Flow & Price Mechanics
Euro 7 particulate mandates and EPA greenhouse-gas frameworks gate supplier qualification while simultaneously stratifying price tiers across precision tube bending contracts. OEMs award premium positioning only to fabricators with validated bend-angle telemetry and certified alloy traceability, compressing margins for tier-two suppliers lacking captive metallurgy labs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle tube forming with joining hardware and sensor integration. Price differentiation rests on ISO-certified quality grades and volume scale, with German automotive clusters commanding premiums for real-time telemetry capabilities. Cost compression in stainless-steel exhaust manifolds is intensifying because nickel and molybdenum price volatility squeezes unhedged fabricators. Aftermarket distributors exhibit highest price sensitivity, while captive supplier parks in Stuttgart and Munich absorb specification premiums without volume elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate German and Japanese automotive corridors, where OEMs mandate real-time bend-angle feedback to eliminate buffer stock. Strategic stockpiling of nickel and molybdenum alloys persists among tier-one suppliers hedging against commodity volatility. Geographic supply concentration centers on Germany, China, and Japan, with raw material dependencies drawing from Indonesian nickel, Chilean copper, and Australian bauxite. Single-source vulnerability in Baden-Württemberg supplier parks creates exposure to regional energy disruptions. Distribution runs through systems-integration contracts bundling formed tubes with module assembly rather than discrete component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in predictive maintenance algorithms and real-time quality telemetry are expanding faster than hardware sales as OEMs mandate digital thread integration from CAD to shop-floor bending machines.
For Market Incumbents: Secure NHTSA and EPA dual certification timelines ahead of model year 2027 fleet-average benchmarks to defend against emerging Chinese suppliers entering through India PLI zones. Deepen backward integration into captive alloy production to offset nickel and molybdenum price volatility squeezing tier-two competitors. Prioritize robotic orbital welding integration for lights-out production contracts with Volkswagen and BMW procurement teams. For New Entrants and Emerging Players: Differentiate on hydrogen distribution architecture certification for commercial vehicle high-pressure fuel lines, where first-mover advantage remains unclaimed. Target Tamil Nadu and Gujarat fabrication zones under India PLI scheme incentives for two-wheeler and three-wheeler battery cooling circuits. Pursue go-to-market partnerships with CATL and BYD supplier networks in Yangtze River Delta clusters rather than direct OEM confrontation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aluminum mandrel forming configurations as battery thermal management circuits displace legacy exhaust programs. Long-term viability favors diversified automotive suppliers with captive metallurgy labs and validated Euro 7 compliance pathways. Acquisition target archetypes include precision specialists with dedicated bend-cell configurations and established German supplier park relationships. Watch for inflection when hydrogen fuel line certification standards crystallize under METI industrial policy frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Orbital Welding Integration | Enables lights-out production for Volkswagen and BMW direct-supply contracts with real-time quality telemetry. |
| Backward Integration into Alloy Production | Insulates Continental AG and Magna International from nickel and molybdenum price volatility squeezing unhedged competitors. |
| Hydrogen Distribution Architecture Certification | Creates first-mover advantage for commercial vehicle high-pressure fuel lines under METI industrial policy frameworks. |
| India PLI Zone Manufacturing Footprint | Captures domestic content incentives for two-wheeler and three-wheeler battery cooling circuit demand. |
| Digital Thread Integration from CAD to Shop-Floor | Compresses prototype-to-production cycles for OEMs mandating predictive maintenance algorithm bundling. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution heads, and CNC programming specialists and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings from diversified automotive suppliers, and EPA emissions compliance disclosures. Bottom-up segmentation modeling across tube bender configurations, material grades, and end-user channels was triangulated with top-down market sizing from automotive production forecasts and content-per-vehicle assumptions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation dimensions spanning propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from trend extrapolation of aluminum mandrel forming penetration rates and stainless-steel exhaust manifold decline curves, cross-referenced with Euro 7 implementation timelines and EPA model year 2027 fleet-average benchmarks.
Forecasts assume regulatory continuity in EPA greenhouse-gas frameworks and ECHA REACH coating restrictions; material policy shifts would require re-modeling. Revision becomes warranted when battery-electric penetration rates or hydrogen infrastructure deployment cross threshold inflection points altering thermal management circuit demand composition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Die-Stamping Equipment Market
Automotive Assemblies
Automotive Roof Rails Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Electric Off Highway Equipment Machinery Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Automotive Activated Carbon Canister Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Automotive Throttle Body Assembly Market
Automotive Assemblies
Global Automotive Rear Mounted Tray Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Automotive Roof Bar and Roof Racks Market