
 Automotive Cell Vent Spacer Market | 2026-2036
Automotive Cell Vent Spacer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cell Vent Spacer Market Insights
The EU Battery Regulation's mandatory carbon footprint declarations and safety performance thresholds is broadening addressable demand for fluoropolymer-based vent spacers. W. L. Gore & Associates leverages its expanded polytetrafluoroethylene membrane expertise to dominate premium thermal management applications. Saint-Gobain Performance Plastics anchors European supply through its fluoropolymer compounding capabilities in France and Germany. Freudenberg Group competes via backward integration into nonwoven and membrane substrates for cell-level assemblies.
Automotive cell vent spacers are precision-engineered porous or perforated polymeric components, typically 0.1–2.0 mm thick, that equalize pressure differentials within lithium-ion battery packs while blocking electrolyte vapor egress and external contaminant ingress. Polytetrafluoroethylene and polyetheretherketone formulations command premium positioning due to their resistance to hydrofluoric acid decomposition products during thermal events. Electric passenger cars drive the largest volume pull, though commercial e-trucks represent the fastest-growing application as heavy-duty pack architectures multiply vent point counts per kilowatt-hour. Module-based installation retains the deepest supplier relationships, but cell-level assembly is capturing margin pools through tighter OEM integration mandates.
FDA, EPA, and NHTSA standards in the United States intersect with ECHA REACH restrictions and EU Battery Regulation compliance deadlines to shape material substitution timelines and testing protocols for North American and European suppliers. China's NMPA and GB standards enforce distinct flame-retardancy and outgassing specifications that require separate product qualification tracks. Stakeholders must monitor how diverging thermal runaway test methods across these regulatory jurisdictions fragment certification costs and determine which material platforms achieve cross-regional scale.
Market Dynamics
The EU Battery Regulation's mandatory carbon footprint declarations and thermal runaway containment standards are forcing material upgrades from polyethylene to fluoropolymer formulations across European OEM supply chains.
Growth Catalysts
- GB/T battery safety standards:China's technical specifications for lithium-ion cell venting are accelerating fluoropolymer adoption in domestic EV production.
- Module-to-cell assembly migration:OEM integration mandates are pulling vent spacer procurement closer to battery cell manufacturers.
- Germany's automotive engineering corridor:BMW, Volkswagen, and Mercedes-Benz battery programs concentrate demand for thermal runaway-rated components.
Market Restraints
- Fluoropolymer feedstock concentration:PTFE and PEEK resin supply concentrates among a handful of chemical conglomerates in Germany, Japan, and the United States.
- ECHA REACH compliance costs:Registration, evaluation, and authorization of novel polymer formulations creates multi-year qualification timelines for European market entry.
- Polyethylene substitution ceiling:Cost-sensitive pack architectures in commercial vehicle segments resist material upgrades despite performance gaps.
Strategic Opportunities
- Commercial e-truck battery architectures:Heavy-duty pack designs multiply vent point counts per kilowatt-hour, expanding addressable component volume.
- Solid-state battery venting interfaces:Next-generation cell formats require redesigned spacer geometries for solid electrolyte thermal management.
- India's PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives are creating qualification pathways for vent component suppliers.
Industry Challenges
- Divergent thermal runaway test protocols:NHTSA, ECHA, and NMPA methodologies require separate product qualification tracks, fragmenting certification budgets.
- Membrane-to-substrate bonding expertise:Cell-level assembly demands precision lamination capabilities that conventional injection molders lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cell Vent Spacer Market |
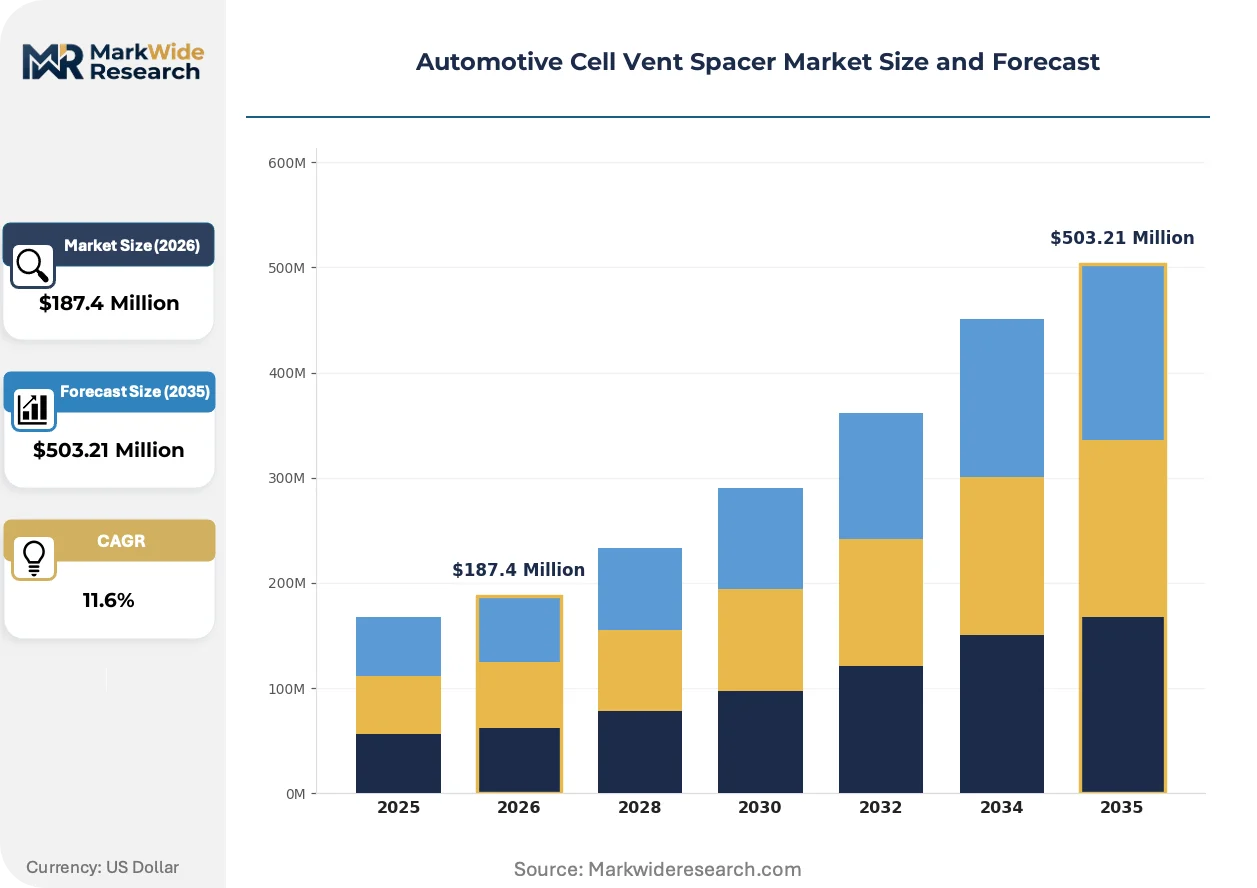
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinylidene Fluoride, Nylon, Polyetheretherketone, Polytetrafluoroethylene Application: Electric Passenger Cars, Commercial E-Trucks, Autonomous Vehicles, Specialty Battery Packs, Two-Wheelers, Delivery Drones Installation Type: Pack-Level Integration, Cell-Level Assembly, Module-Based Installation, Battery Management System Embedded, Clip-Fit, Heat-Sealed End User: OEMs, Battery Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Fleet Operators |
| Companies Covered | W. L. Gore & Associates, Donaldson, Porex, Nitto Denko, Parker Hannifin, Saint-Gobain Performance Plastics, Freudenberg Group, Zeus Industrial Products, MicroVent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cell Vent Spacer Market Trends and Innovations
Material science breakthroughs and regulatory harmonization pressures are compressing product lifecycles while elevating performance thresholds for pressure-equalization components.
Expanded polytetrafluoroethylene membrane laminates are rewriting thermal management capabilities in premium battery packs. German and South Korean OEMs specify ePTFE vent spacers for 800-volt architectures requiring hydrofluoric acid resistance during cell venting events. The technology is compressing qualification timelines for conventional perforated polymer alternatives.
REACH restrictions on per- and polyfluoroalkyl substances are tightening material sourcing requirements for European suppliers. The regulation forces reformulation of PTFE processing aids and compounding additives. Cell vent spacer manufacturers with captive fluoropolymer compounding capabilities in France and Germany are absorbing compliance costs faster than importers.
Cell-level procurement contracts are displacing module-tier purchasing for thermal management components. BMW and Mercedes-Benz battery divisions now specify vent spacer geometries directly with membrane specialists, bypassing traditional module integrators. This pattern concentrates most visibly in Stuttgart and Munich engineering corridors where OEM battery centers maintain resident supplier engineers.
Automotive Cell Vent Spacer Market Segmentation
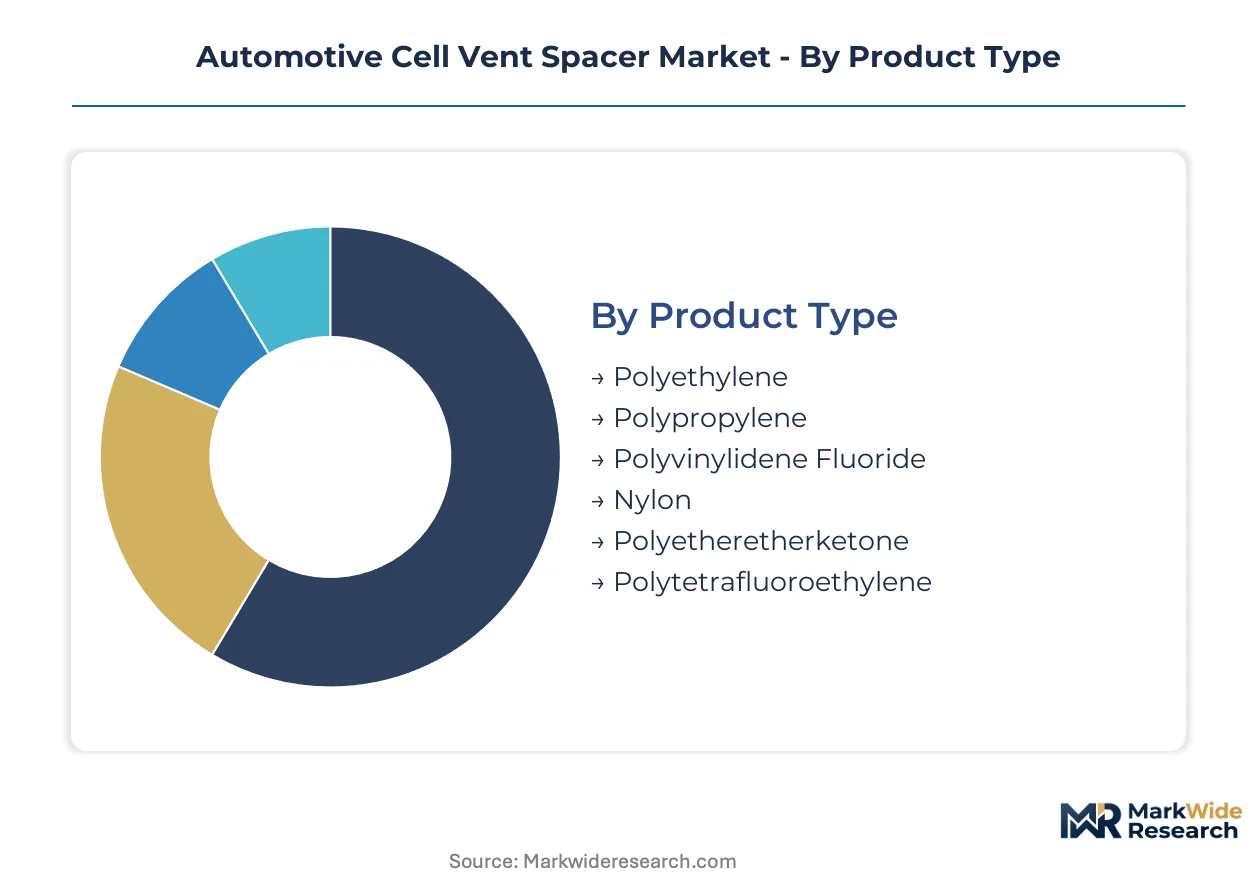
Automotive cell vent spacer procurement patterns fragment sharply across material chemistry, installation architecture, and supply chain tier. Understanding these segment boundaries reveals where fluoropolymer premiums command pricing power versus where commodity polymers retain volume dominance.
Product Type:
Resin supply concentrates among German, Japanese, and American chemical conglomerates, concentrating margin capture upstream and forcing spacer manufacturers into long-term offtake arrangements.
- Polytetrafluoroethylene:Expanded PTFE membranes deliver hydrofluoric acid resistance during thermal runaway events. German OEMs in Stuttgart and Munich specify ePTFE formulations for 800-volt architectures, absorbing 40-60% cost premiums over commodity alternatives.
- Polyetheretherketone:High-performance thermoplastic withstands continuous operating temperatures above 250°C while maintaining dimensional stability under electrolyte exposure. South Korean battery cell producers specify PEEK spacers for NCM811 high-nickel cathode packs where thermal management margins compress.
- Polyvinylidene Fluoride:PVDF offers intermediate chemical resistance at moderate cost positions for mid-tier EV platforms.
- Nylon:Polyamide formulations serve cost-constrained module architectures where thermal event probability remains statistically lower.
- Polypropylene:Commodity polymer retains volume in commercial vehicle segments resisting material upgrades despite performance gaps.
- Polyethylene:Baseline material faces substitution pressure from EU Battery Regulation carbon footprint thresholds and thermal containment mandates.
Today's leader: Polytetrafluoroethylene. Tomorrow's challenger: Polyetheretherketone.
Application:
End-use demand stratifies by pack energy density requirements and duty cycle severity, with heavy-duty architectures multiplying vent point counts per kilowatt-hour.
- Electric Passenger Cars:Volume anchor for precision-molded spacers across German, Japanese, and South Korean OEM battery programs. BMW, Volkswagen, and Mercedes-Benz supply chains concentrate procurement in Baden-Württemberg and Bavaria engineering corridors.
- Commercial E-Trucks:Heavy-duty pack designs with distributed cell configurations generate 3-5x vent component counts versus passenger car equivalents per kilowatt-hour.
- Autonomous Vehicles:Redundant battery architectures demand dual-venting pathways with failover-rated spacer specifications.
- Specialty Battery Packs:Industrial and marine applications specify corrosion-resistant fluoropolymer formulations for extreme environment exposure.
- Two-Wheelers:Cost-optimized pack designs in India and Southeast Asia prioritize polypropylene and polyethylene over performance polymers.
- Delivery Drones:Lightweight power density requirements favor thin-gauge membrane constructions with gram-level weight budgets.
Commercial e-trucks gain share fastest as heavy-duty electrification accelerates; two-wheelers anchor volume in emerging markets.
Installation Type:
Assembly depth determines supplier technical requirements and margin capture, with cell-level integration demanding precision lamination capabilities beyond conventional molding.
- Cell-Level Assembly:Direct spacer-to-cell bonding requires membrane-to-substrate lamination expertise that injection molders lack. BMW and Mercedes-Benz battery divisions now specify geometries directly with membrane specialists, bypassing module integrators.
- Module-Based Installation:Traditional procurement channel retains deepest supplier relationships but faces margin compression as OEMs consolidate specifications upstream.
- Pack-Level Integration:System-level venting architectures concentrate spacer arrays at enclosure boundaries rather than distributed cell positions.
- Battery Management System Embedded:Smart venting with pressure-sensor integration demands multi-material assemblies combining porous media with electronic housings.
- Clip-Fit:Mechanical retention enables field serviceability but sacrifices sealing performance versus bonded alternatives.
- Heat-Sealed:Thermal welding processes dominate high-volume production lines for cost-optimized pack architectures.
Module-based installation holds current volume leadership. Cell-level assembly captures expanding margin pools through tighter OEM integration mandates.
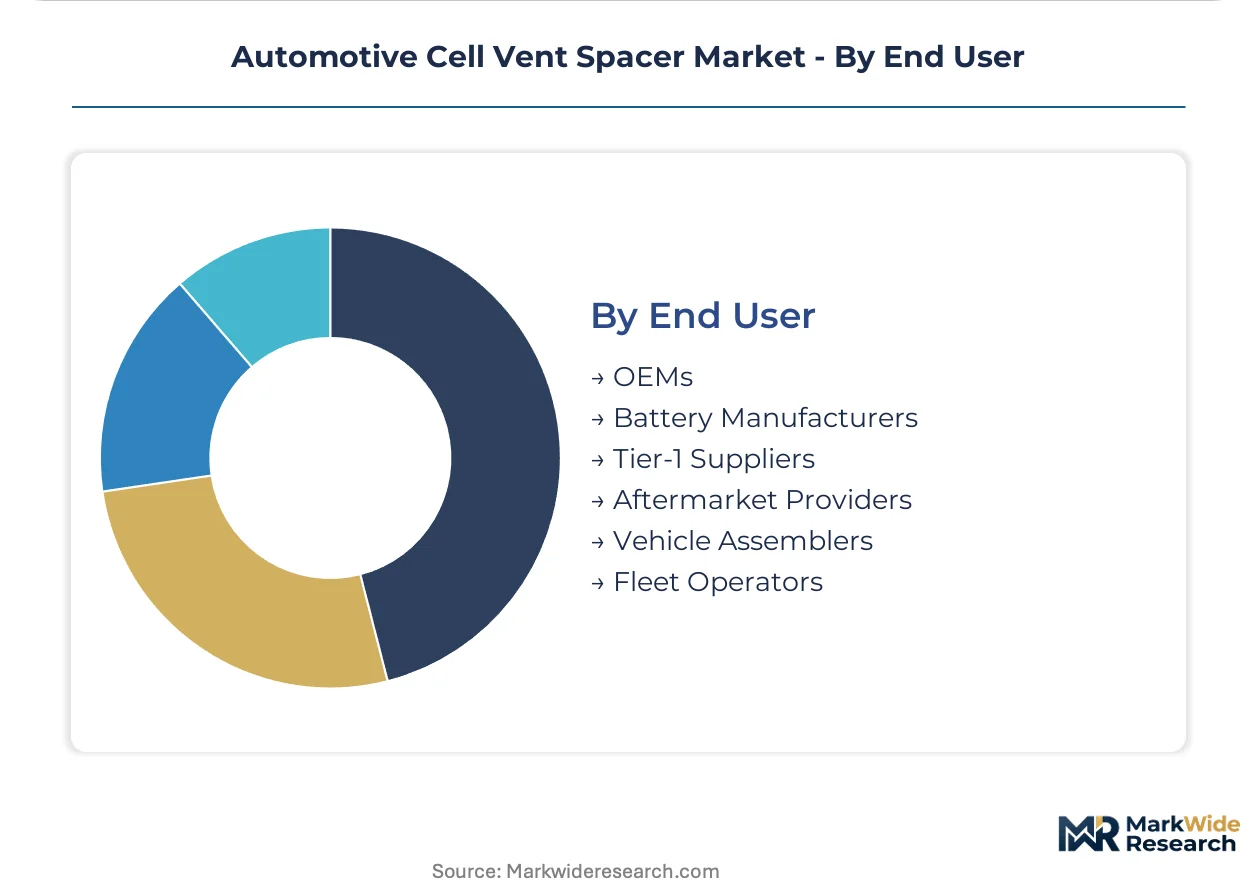
End User:
Procurement authority is shifting downstream from tier-1 module integrators toward cell manufacturers and OEM battery divisions.
- Battery Manufacturers:CATL, LG Energy Solution, and Samsung SDI now specify vent spacer materials directly, consolidating purchasing power previously fragmented across module suppliers.
- OEMs:German automotive engineering corridors concentrate resident supplier engineers at BMW, Volkswagen, and Mercedes-Benz battery centers.
- Tier-1 Suppliers:Module integrators face specification displacement as cell makers and OEMs internalize vent component selection.
- Vehicle Assemblers:Final assembly plants specify pack-level venting requirements for platform-standardized architectures.
- Aftermarket Providers:Replacement demand concentrates in collision repair and battery refurbishment channels with lower performance thresholds.
- Fleet Operators:Commercial vehicle purchasers increasingly specify thermal runaway containment ratings in procurement tenders.
Battery manufacturers consolidate procurement authority fastest. Tier-1 suppliers defend position through bonded assembly capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive cell vent spacer demand concentrates where battery engineering talent clusters around OEM battery centers and cell manufacturing hubs. Germany, China, South Korea, Japan, and the United States anchor procurement volume through distinct regulatory and supply chain configurations.
Germany
BMW, Volkswagen, and Mercedes-Benz battery divisions in Stuttgart and Munich specify fluoropolymer vent spacers directly with membrane specialists. The EU Battery Regulation's carbon footprint declarations and thermal runaway standards accelerate material upgrades from polyethylene to PTFE and PEEK formulations. Baden-Württemberg and Bavaria engineering corridors concentrate resident supplier engineers at OEM battery centers, consolidating procurement authority upstream from traditional module integrators.
China
CATL and BYD battery programs drive volume for vent components rated to GB/T battery safety standards. NMPA and MIIT enforce flame-retardancy and outgassing specifications that require separate qualification tracks from Western protocols. The Yangtze River Delta and Pearl River Delta manufacturing basins concentrate cell production capacity, pulling spacer procurement toward battery manufacturers rather than tier-1 module suppliers.
South Korea
LG Energy Solution and Samsung SDI specify PEEK spacers for NCM811 high-nickel cathode packs where thermal management margins compress. MFDS and METI-aligned standards shape material selection for export-oriented production. The Seoul Capital Area and Busan-Ulsan industrial corridors anchor battery cell manufacturing, with resident engineers from membrane specialists co-located at R&D centers.
Japan
Toyota and Panasonic battery joint ventures prioritize vent spacer reliability for solid-state battery development programs. METI's technical specifications for next-generation cell formats influence material selection timelines. The Kanto and Kansai regions concentrate automotive and electronics manufacturing heritage, with Nagoya-area engineering clusters supplying precision membrane fabrication expertise.
United States
GM, Ford, and Tesla battery programs in Michigan and California drive demand for NHTSA-compliant thermal runaway containment components. EPA and OSHA standards intersect with state-level zero-emission vehicle mandates to shape material qualification requirements. The Midwest automotive corridor and Silicon Valley engineering clusters split procurement influence between traditional OEM supply chains and vertically integrated battery manufacturers.
Automotive Cell Vent Spacer Market Competitive Landscape
Capital-heavy producers with captive fluoropolymer compounding capabilities compete with asset-light membrane designers outsourcing substrate fabrication. The market structure tiers between integrated material specialists commanding premium pricing and injection molders defending commodity polyethylene volumes. Three archetypes dominate: integrated fluoropolymer compounders with European manufacturing footprints, precision membrane laminators serving cell-level assembly mandates, and diversified industrial conglomerates leveraging backward integration into nonwoven substrates. Competitive moves concentrate on capacity expansion in Germany and South Korea, plus strategic partnerships binding OEM battery divisions to exclusive material supply arrangements.
Within the integrated compounder tier, Saint-Gobain Performance Plastics and Freudenberg Group exemplify European-based manufacturers with captive fluoropolymer capabilities in France and Germany. W. L. Gore & Associates occupies a distinct position among membrane specialists leveraging expanded PTFE expertise for premium thermal management applications. These three anchors represent how material science depth and geographic proximity to Stuttgart and Munich engineering corridors determine competitive positioning in cell-level procurement channels.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Donaldson |
| Porex |
| Nitto Denko |
| Parker Hannifin |
| Saint-Gobain Performance Plastics |
| Freudenberg Group |
| Zeus Industrial Products |
| MicroVent |
| Others |
Pricing and Supply Chain Analysis
Fluoropolymer-to-polyethylene performance bifurcation separates premium thermal runaway containment from cost-optimized commodity positioning, with EU Battery Regulation carbon footprint thresholds and NHTSA thermal containment mandates compressing mid-tier alternatives while concentrating margin capture among German and Japanese resin suppliers.
Pricing Analysis
Bundled membrane-to-substrate lamination services command 40-60% premiums over unbundled component supply, with ePTFE formulations for 800-volt architectures priced against PEEK alternatives for NCM811 packs. Price differentiation hinges on GB/T versus ECHA REACH certification tiers and OEM direct procurement volume scales. Cost compression in polyethylene tiers intensifies as commercial e-truck segments resist material upgrades despite performance gaps. Battery manufacturers exhibit lowest price sensitivity; aftermarket providers anchor the economy tier.
Supply Chain Analysis
GB/T, ECHA REACH, and NHTSA qualification gating fragments supplier certification tracks across China, Germany, and the United States. PTFE and PEEK resin supply rests on German, Japanese, and American chemical conglomerates, with membrane lamination capabilities tethered to Stuttgart and Munich engineering corridors. Single-source vulnerability concentrates in fluoropolymer feedstock channels. Distribution runs through cell-level direct contracts displacing traditional module-tier procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's mandatory carbon footprint declarations and thermal runaway containment standards compound demand for certified fluoropolymer formulations, elevating procurement authority toward OEM battery divisions and cell manufacturers.
For Market Incumbents: Deploy captive fluoropolymer compounding capabilities in France and Germany to absorb REACH reformulation costs faster than import-dependent competitors. Accelerate resident engineer placement at BMW and Mercedes-Benz battery centers in Baden-Württemberg and Bavaria to defend specification control against membrane specialists bypassing module integrators. For New Entrants and Emerging Players: Begin with India's PLI scheme for advanced chemistry cells, where domestic battery manufacturing incentives create qualification pathways absent entrenched supplier relationships. Target commercial e-truck battery architectures multiplying vent point counts per kilowatt-hour, leveraging precision lamination partnerships to bypass injection molding capability gaps. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane-to-substrate bonding specialists possessing precision lamination expertise that conventional molders lack, particularly those co-located in Seoul Capital Area or Yangtze River Delta manufacturing basins. Long-term viability centers on solid-state battery venting interface development programs. Watch for OEM integration mandates consolidating procurement authority upstream as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Fluoropolymer Compounding | Saint-Gobain and Freudenberg anchor European supply through France and Germany manufacturing footprints. |
| Resident Engineer Placement at OEM Battery Centers | W. L. Gore & Associates co-locates membrane specialists in Stuttgart and Munich engineering corridors. |
| GB/T Certification Track Investment | Separate qualification pathways for CATL and BYD programs unlock Yangtze River Delta procurement channels. |
| Solid-State Battery Venting Interface Development | Toyota-Panasonic joint ventures in Nagoya-area clusters prioritize redesigned spacer geometries. |
| Backward Integration into Nonwoven Substrates | Freudenberg Group controls membrane substrate supply for cell-level assembly mandates. |
Research Methodology
Multiple input streams — primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, and fluoropolymer compounding technical directors; secondary validation through ECHA REACH registration databases, NHTSA thermal runaway test protocols, and GB/T standard filings; plus customs trade data and SEC 10-K disclosures from chemical conglomerates — were reconciled through bottom-up component demand modeling and top-down battery pack production triangulation.
Data-stream reconciliation across the analysis window employed vehicle class, propulsion architecture, material chemistry tier, and installation depth as segmentation dimensions, with CAGRs derived from production ramp schedules and content-per-vehicle coefficients calibrated to OEM battery program disclosures. Solid-state battery development timelines and commercial e-truck electrification curves served as scenario-weighting inputs.
Several conditions sit outside the modeled scope, including unannounced solid-state battery commercialization accelerations, abrupt ECHA perfluoroalkyl substance restrictions, and geopolitical disruptions to German-Japanese resin supply channels. Forecasts reflect documented assumptions about regulatory harmonization trajectories and OEM vertical integration intentions. A model refresh is warranted upon material change in EU Battery Regulation enforcement timelines or NHTSA thermal runaway test protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Constant Velocity Joint Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Automotive Air Vent Assembly Market
Automotive Assemblies
Automotive Clock Spring Market
Automotive Assemblies
Automotive Ball Joints Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Car Body Kit Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Global Automotive Cross Car Beam Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
United States Automotive Heat Exchanger Market