
 South Africa Automotive Actuators Market | 2026-2036
South Africa Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Actuators Market Analytics
Steel-to-aluminum substitution in actuator housings is shifting cost structures across the supply base. Robert Bosch GmbH leverages its in-house forging capabilities to control aluminum billet flows into precision actuator castings. Continental AG sustains engineering partnerships with domestic OEM programs, anchoring its position in electromechanical brake actuator development. Denso Corporation specializes in compact linear actuator designs for engine management systems, occupying a niche where thermal tolerance requirements exclude lower-tier competitors.
Automotive actuators are electromechanical or fluid-power devices that convert control signals into precise mechanical motion, typically achieving positional accuracy within micrometer tolerances through ball-screw, solenoid, or servo-hydraulic mechanisms. Their primary purpose is to execute real-time adjustments in vehicle subsystems—throttle position, brake pressure, climate damper orientation—under command from electronic control units. Rotary actuators dominate power steering applications where angular displacement cycles exceed ten million over a vehicle lifespan, while linear actuators capture expanding share in HVAC flap control as cabin-zone complexity rises. Electromechanical technology leads across both product categories, displacing purely pneumatic alternatives as OEMs prioritize energy recuperation and programmable motion profiles.
The National Regulator for Compulsory Specifications mandates SABS-approved testing for safety-critical actuator assemblies, creating compliance barriers for uncertified imports. South Africa's alignment with United Nations Economic Commission for Europe braking standards further shapes product specifications for export-bound vehicle programs. The Department of Trade, Industry and Competition administers local content thresholds through the Automotive Production and Development Programme, influencing Tier-1 sourcing decisions for actuator subcomponents. Stakeholders must monitor regulatory convergence between domestic specifications and EU-type approval frameworks as assemblers pursue dual-market certification strategies.
Market Dynamics
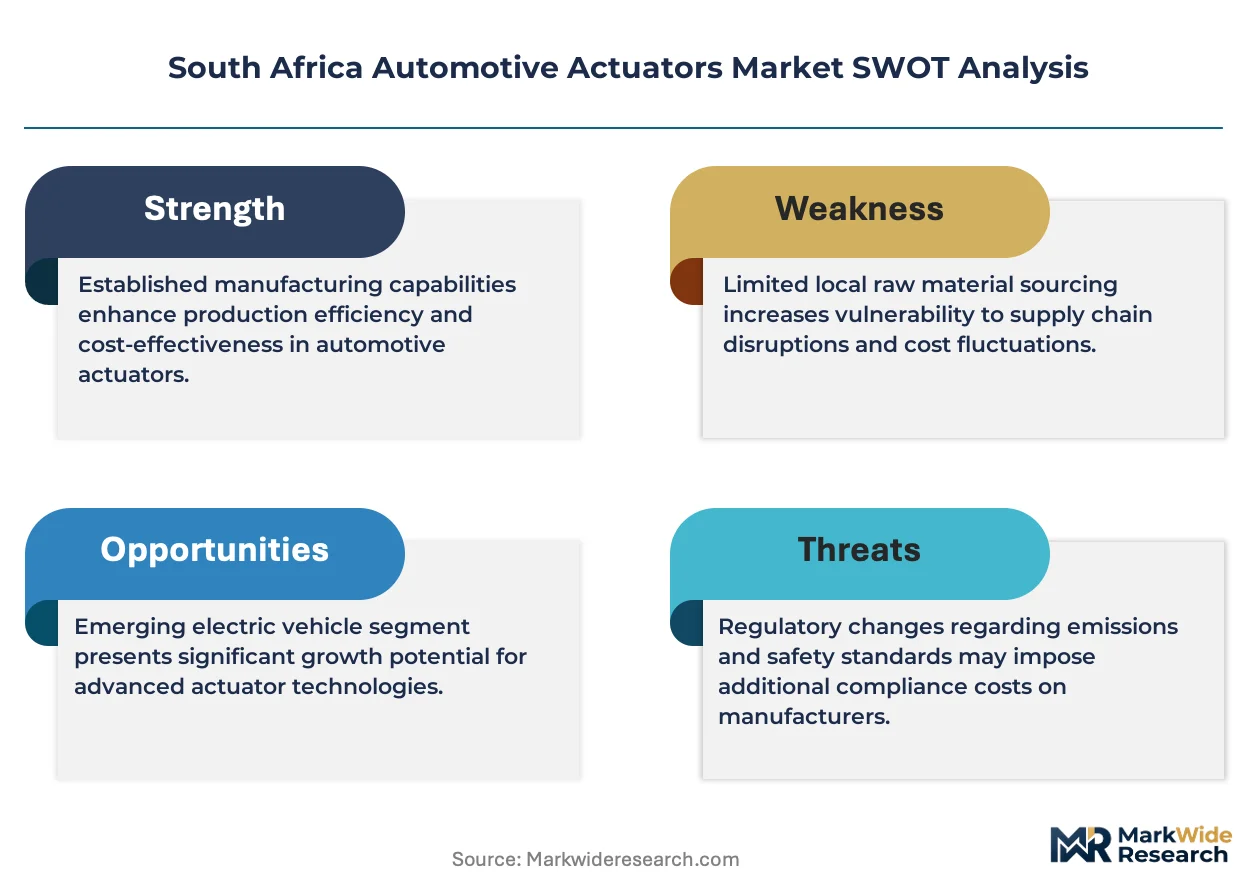
Localization mandates under the Automotive Production and Development Programme are forcing Tier-1 suppliers to restructure actuator sourcing networks around Gauteng-based forging and machining clusters.
Growth Catalysts
- Electromechanical brake actuators:UN Economic Commission for Europe braking standards alignment is accelerating OEM adoption of electrohydraulic designs for export-bound vehicle programs.
- Aluminum billet forging:Steel-to-aluminum substitution in actuator housings is reducing component weight for power steering assemblies.
- Rosslyn-Pretoria cluster concentration:Gauteng province vehicle assembly density is creating procurement scale effects for linear actuator suppliers serving engine management systems.
Market Restraints
- SABS certification barriers:National Regulator for Compulsory Specifications testing mandates for safety-critical assemblies are extending import qualification timelines.
- Aluminum price volatility:Raw material cost swings are compressing margin structures for precision casting suppliers without captive billet supply.
- Pneumatic actuator displacement:Electromechanical alternatives are rendering legacy compressed-air systems obsolete in climate control applications.
Strategic Opportunities
- HVAC flap control expansion:Cabin-zone complexity is creating demand for compact linear actuators with programmable motion profiles.
- Dual-market certification:Convergence between South African specifications and EU-type approval frameworks is enabling single-platform designs for regional export.
- Thermal tolerance specialization:Engine bay heat management requirements are excluding lower-tier competitors from high-specification actuator segments.
Industry Challenges
- Ball-screw machining expertise:Micrometer-tolerance component production requires skilled tool-and-die capacity that concentrates in established Tier-1 facilities.
- Legacy ECU integration:New electromechanical actuator designs must maintain backward compatibility with existing vehicle electronic architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Actuators Market |
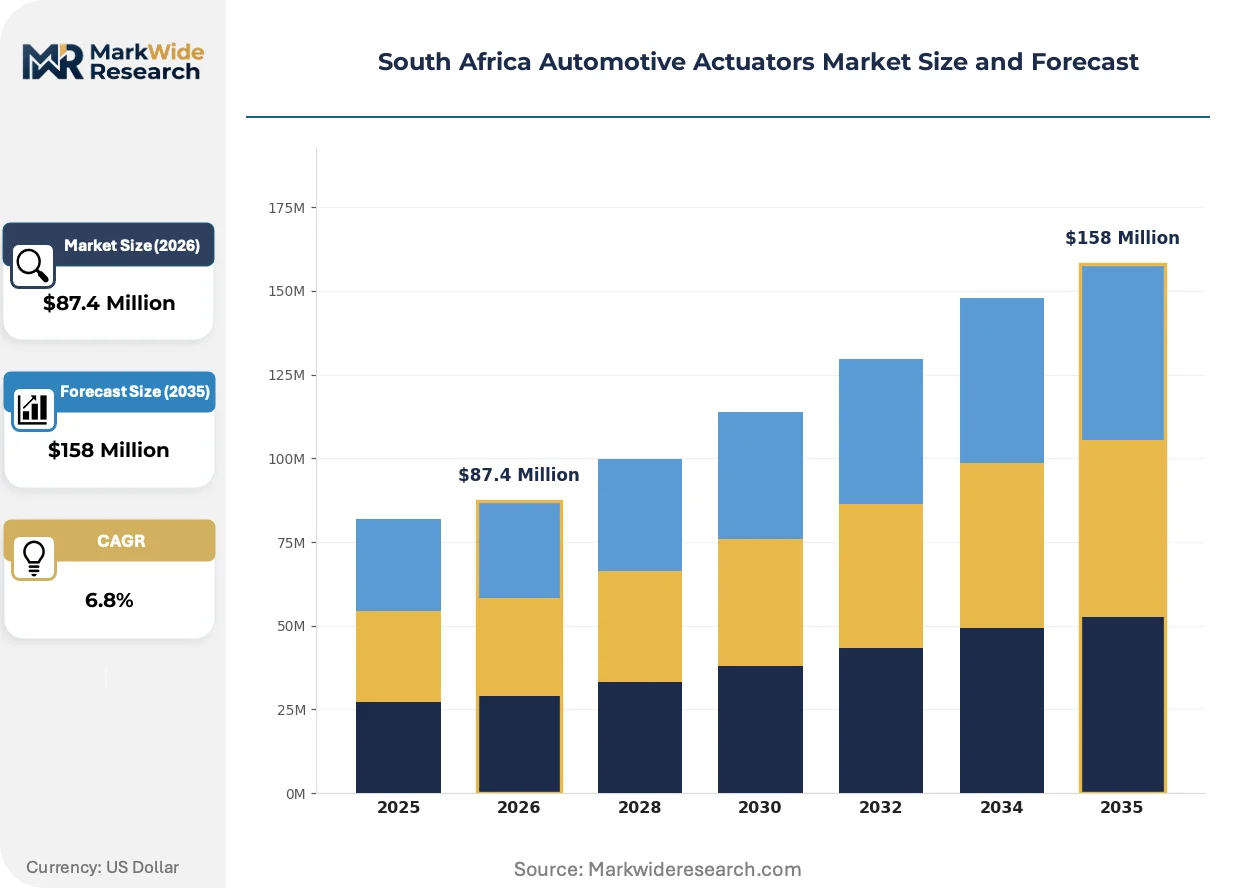
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Hydraulic Actuators, Pneumatic Actuators Application: Power Steering, Brake Systems, Engine Control, HVAC Systems End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Electromechanical, Electrohydraulic, Pneumatic, Mechanical |
| Companies Covered | Denso Corporation, Mitsubishi Electric Corporation, Nidec Corporation, Hitachi Ltd, Continental AG, Robert Bosch GmbH, BorgWarner Inc, Aptiv Plc, HELLA GmbH & Co. KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Actuators Market Evolving Landscape
Actuator technology trajectories in South Africa are being pulled by material substitution, regulatory harmonization pressures, and OEM sourcing consolidation around provincial industrial clusters.
Brushless DC motor technology is converging with integrated position sensing for throttle control applications. Domestic OEM programs are adopting these designs to meet energy recuperation targets. The convergence is compressing supplier development cycles as assemblers demand programmable motion profiles from single-source electromechanical platforms.
SABS approval pathways for safety-critical actuator assemblies are tightening documentation requirements for electromagnetic compatibility testing. Tier-1 suppliers must now submit extended validation data for brake and steering applications. Export-oriented vehicle programs are responding by front-loading certification work to secure dual-market approval under EU-type frameworks.
Consolidated procurement through Gauteng-based OEM technical centers is displacing distributed supplier relationships. Tier-1 actuator vendors now negotiate directly with assembler engineering teams rather than through regional purchasing offices. This pattern concentrates most visibly in Rosslyn assembly operations where power steering actuator specifications are locked eighteen months before production launch.
South Africa Automotive Actuators Market Segmentation
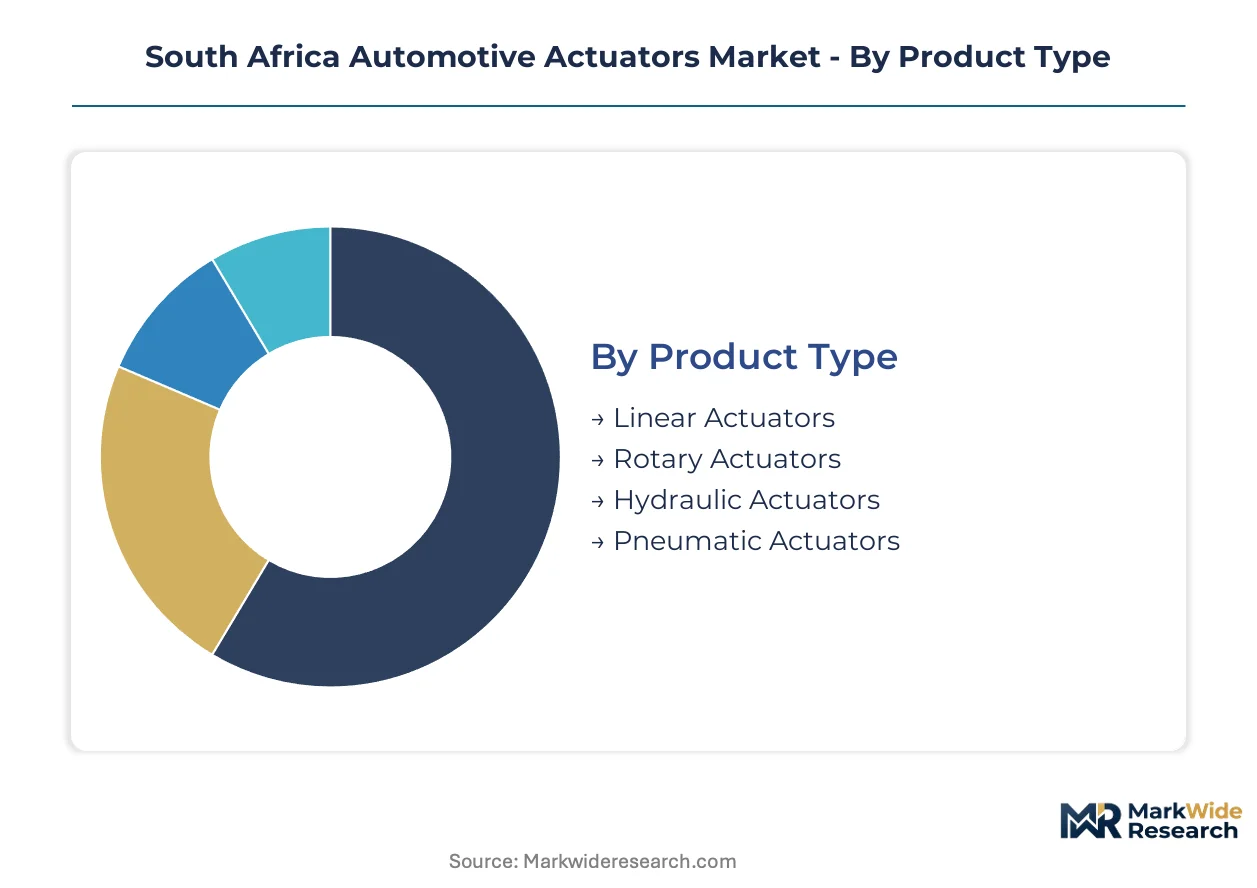
Actuator procurement patterns in South Africa diverge sharply across product architectures and customer tiers. Gauteng-based OEM technical centers source predominantly through consolidated Tier-1 channels, while aftermarket demand fragments across distributed service networks.
Product Type:
Linear and rotary actuator variants demand the heaviest upfront capital investment due to precision ball-screw machining and integrated position sensing requirements.
- Linear Actuators:Compact designs with ball-screw or lead-screw mechanisms achieve positional accuracy within micrometer tolerances. Demand concentrates in HVAC flap control applications across Rosslyn assembly operations as cabin-zone complexity rises.
- Rotary Actuators:Angular displacement systems with brushless DC motor integration dominate power steering applications requiring ten-million-cycle durability. Gauteng vehicle assemblers specify these for export-bound programs aligned with UN Economic Commission for Europe braking standards.
- Hydraulic Actuators:High-pressure fluid-power systems retain niche presence in heavy commercial vehicle brake applications.
- Pneumatic Actuators:Compressed-air mechanisms face displacement pressure from electromechanical alternatives in climate control segments.
Rotary actuators absorb the bulk of installed capacity; linear actuators are expanding most quickly.
Application:
Brake and steering applications command premium pricing tiers due to SABS certification mandates and safety-critical validation requirements.
- Power Steering:Electromechanical rack-drive systems with torque sensor integration enable energy recuperation for fuel efficiency targets. Rosslyn-based OEM programs specify these eighteen months ahead of production launch.
- Brake Systems:Electrohydraulic actuator designs with electromagnetic compatibility testing documentation satisfy National Regulator for Compulsory Specifications pathways. Export-oriented assemblers front-load certification work for dual-market EU-type approval.
- Engine Control:Throttle position actuators with thermal tolerance specifications exclude lower-tier competitors from under-hood placement.
- HVAC Systems:Multi-zone climate control damper actuators with programmable motion profiles capture expanding share.
Brake systems command the highest specification intensity; HVAC systems show the steepest expansion trajectory.
End User:
OEM direct procurement carries steeper technical qualification barriers than aftermarket channels, concentrating margin in assembler-facing relationships.
- OEMs:Original equipment manufacturers in Pretoria and Rosslyn technical centers negotiate actuator specifications directly with Tier-1 engineering teams rather than through regional purchasing offices.
- Aftermarket Providers:Distributed service networks source replacement actuators through independent parts distributors with shorter validation cycles.
- Vehicle Assemblers:Final assembly operations in Gauteng province anchor procurement volumes for localized component sourcing under Automotive Production and Development Programme thresholds.
- Tier-1 Suppliers:Integrated system houses consolidate actuator sourcing with in-house forging capabilities for aluminum billet flow control.
Vehicle assemblers absorb the bulk of installed capacity; Tier-1 suppliers are expanding most quickly.
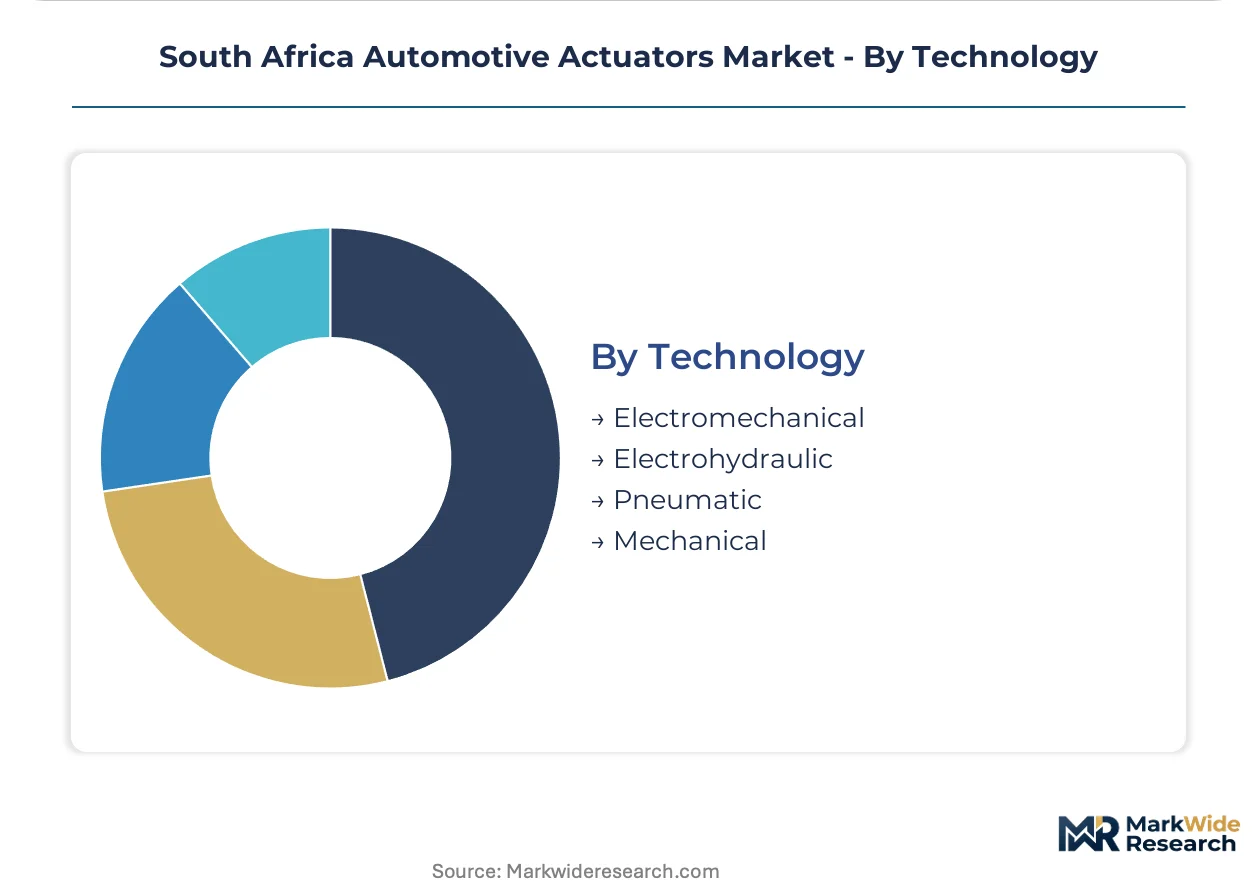
Technology:
Electromechanical platforms require the deepest R&D investment due to embedded control electronics and software integration demands.
- Electromechanical:Brushless DC motor technology with integrated position sensing displaces purely pneumatic alternatives as OEMs prioritize programmable motion profiles and energy recuperation. Domestic programs adopt these designs for throttle control applications.
- Electrohydraulic:Combined electric-hydraulic architectures satisfy stricter automotive quality benchmarks from the National Regulator for Compulsory Specifications for safety-critical brake and steering assemblies.
- Pneumatic:Legacy compressed-air systems face obsolescence in climate control applications where electromechanical alternatives offer superior precision.
- Mechanical:Purely mechanical linkages retain minimal presence in non-automated auxiliary systems.
Electromechanical technology absorbs the bulk of installed capacity; electrohydraulic designs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vehicle assembly clusters concentrate procurement volumes in specific sub-regions where OEM technical centers negotiate directly with Tier-1 engineering teams. The National Regulator for Compulsory Specifications shapes sourcing decisions through SABS certification mandates that extend qualification timelines for safety-critical components.
Gauteng Province
Rosslyn and Pretoria anchor South Africa's densest vehicle assembly corridor, with OEM technical centers locking power steering actuator specifications eighteen months before production launch. The Automotive Production and Development Programme enforces local content thresholds that force Tier-1 suppliers to restructure sourcing networks around Gauteng-based forging clusters. Precision machining capacity for ball-screw components concentrates in established industrial zones where skilled tool-and-die expertise remains scarce.
Western Cape
Export-oriented vehicle programs in this coastal region front-load certification work to secure dual-market approval under EU-type frameworks alongside domestic SABS pathways. The Department of Trade, Industry and Competition administers incentive structures that influence Tier-1 sourcing decisions for actuator subcomponents destined for European markets. Cape Town metro industrial corridors host specialized testing facilities for electromagnetic compatibility validation required by the National Regulator for Compulsory Specifications.
KwaZulu-Natal
Durban's port infrastructure supports import-dependent supply chains for aluminum billet and precision casting feedstock used in actuator housing production. Stricter automotive quality benchmarks from the National Regulator for Compulsory Specifications push suppliers toward certified electrohydraulic designs that satisfy both domestic and export requirements. Automotive component distributors in the Durban-Pinetown corridor service aftermarket demand through independent parts networks with shorter validation cycles than OEM channels.
Eastern Cape
Vehicle assembly operations in the Port Elizabeth-Gqeberha corridor generate concentrated demand for brake system actuators aligned with United Nations Economic Commission for Europe standards. The National Regulator for Compulsory Specifications mandates SABS-approved testing for safety-critical assemblies, creating compliance barriers for uncertified imports entering through this coastal manufacturing zone. Regional industrial development zones attract Tier-2 machining suppliers seeking proximity to OEM technical centers.
South Africa Automotive Actuators Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system houses commanding premium positions in safety-critical brake and steering applications while independent fabricators serve aftermarket channels. The vendor base concentrates around three strategic archetypes: Japanese diversified industrials with captive electronics capabilities, German automotive-tier conglomerates with in-house forging operations, and North American powertrain specialists leveraging modular platform strategies. Competitive moves center on backward integration into aluminum billet supply and strategic partnerships with Gauteng-based OEM engineering teams.
Among Japanese diversified industrials, Denso Corporation and Mitsubishi Electric Corporation exemplify the integrated-system archetype, occupying positions where thermal tolerance requirements and embedded control electronics create qualification barriers for lower-tier competitors. Continental AG and Robert Bosch GmbH anchor the German automotive-tier grouping, representing manufacturers with captive forging capabilities that control material flows into precision actuator castings. These five entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning within South Africa's SABS-regulated procurement environment.
| Leading Market Players |
|---|
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Nidec Corporation |
| Hitachi Ltd |
| Continental AG |
| Robert Bosch GmbH |
| BorgWarner Inc |
| Aptiv Plc |
| HELLA GmbH & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Aluminum billet costs flow from Durban port entry through Gauteng-based forging clusters into three distinct pricing tiers for actuator housings. Raw material volatility compresses margins for precision casting suppliers lacking captive supply, while SABS certification investments create premium separation for electrohydraulic brake actuator assemblies.
Pricing Analysis
Volume concentration in Rosslyn-Pretoria assembly operations splits the market between high-specification OEM contracts and price-sensitive aftermarket channels. Three-tier pricing structure across premium, standard, and economy levels reflects SABS certification grade and thermal tolerance performance rather than brand identity alone. Pricing pressure stems from aluminum spot market swings that erode casting margins without long-term offtake agreements. Aftermarket distributors exhibit highest price sensitivity due to shorter validation cycles and import substitution options, while export-bound OEM programs absorb premium tiers for dual-market EU-type approval.
Supply Chain Analysis
Specialty steel and aluminum billet supply rests on South African domestic smelters, Chinese semi-finished exports, and Australian primary aluminum flows through Durban container terminals. Critical dependencies include precision ball-screw machining capacity concentrated in established Tier-1 facilities, brushless DC motor electronics from East Asian component houses, and electromagnetic compatibility testing equipment anchored in Western Cape validation centers. Single-source vulnerability concentrates in Gauteng-based forging clusters where skilled tool-and-die expertise remains scarce. Distribution runs through consolidated OEM technical center negotiations rather than regional purchasing offices, compressing supplier development cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ball-screw machining capacity scarcity props pricing for high-specification actuator segments, constraining supply expansion regardless of demand pull from Rosslyn assembly operations.
For Market Incumbents: Cement backward integration into aluminum billet supply to insulate margin structures from raw material volatility. Lock eighteen-month specification cycles with Gauteng OEM engineering teams before competitor qualification. Prioritize SABS certification pathway investments to defend against uncertified import erosion in safety-critical brake and steering segments. For New Entrants and Emerging Players: The premium-to-economy price gap in HVAC flap control actuators offers white-space entry below established Tier-1 thermal tolerance positioning. Target aftermarket distributor networks with shorter validation cycles as the most penetrable channel. Pursue programmable motion profile specialization as the go-to-market angle for cabin-zone complexity expansion. For Investors and Strategic Acquirers: Tier-1 supplier consolidation announcements are the leading indicator that Gauteng assembly cluster procurement is shifting toward integrated system houses with captive forging capabilities. Five-to-ten year viability favors vertically integrated mid-cap specialists with existing SABS approval pathways and Rosslyn OEM relationships. Watch aluminum price corridor stability as the inflection signal for precision casting acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Billet Supply | Captive material flow insulates margin compression from Durban port price volatility. |
| SABS Certification Pathway Acceleration | Front-loaded validation secures dual-market EU-type approval for export-bound Rosslyn programs. |
| Gauteng Forging Cluster Capacity Expansion | Proximity to Pretoria technical centers compresses supplier development cycle timelines. |
| HVAC Flap Control Actuator Specialization | Programmable motion profile capability captures cabin-zone complexity expansion demand. |
| Aftermarket Distributor Network Partnership | Independent parts channel access bypasses eighteen-month OEM specification lock cycles. |
Research Methodology
Document review covered vehicle production databases, IHS Markit registration data, and National Regulator for Compulsory Specifications filings, complemented by interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and Gauteng-based forging cluster operations managers. Secondary validation drew from customs trade records, SABS certification registries, and Automotive Production and Development Programme administrative documents. Bottom-up actuator procurement volume estimates triangulated against top-down vehicle assembly forecasts across the analysis window.
Cross-referencing historical production patterns with expert panel input shaped the analytical framework across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from segmented growth rate reconciliation against macroeconomic automotive demand indicators. Industry-specific forecast inputs incorporated UN Economic Commission for Europe braking standards alignment timelines and aluminum price corridor assumptions.
Underlying measurement precision varies by segment; electromechanical brake and steering actuators carry tighter precision than pneumatic climate control alternatives due to SABS certification documentation density. Forecasts reflect documented assumptions about regulatory convergence pace and raw material price stability. Aluminum spot volatility, skilled machining labor availability, and EU-type approval pathway acceleration warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Automotive Trailer Drawbar Market
Automotive Assemblies
Automotive Armrest Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
Automotive Roof Rack Market
Automotive Assemblies
Engine Fixture Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Automotive Torsion Bar Market
Automotive Assemblies
Manifold Assembly Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Automotive Ball Joints Market