
 Automotive Trailer Drawbar Market | 2026-2036
Automotive Trailer Drawbar Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Trailer Drawbar Market Outlook
SAE Class IV/V rating upgrades is bifurcating the competitive landscape into premium certified suppliers and commodity producers. AL-KO leverages its integrated axle-drawbar systems to dominate European OEM supply chains for high-GVWR applications. Böckmann Fahrzeugwerke GmbH sustains brand strength in specialized agricultural trailers where corrosion-resistant specifications command sustained premiums. Bosch competes through sensor-integrated drawbar modules that enable trailer stability monitoring for commercial fleets.
An automotive trailer drawbar is a structural coupling member, typically fabricated from high-tensile steel or extruded aluminum alloy, that transmits牵引 loads between a towing vehicle and a towed trailer while maintaining defined hitch height and articulation geometry; its primary function is to ensure safe load transfer and directional stability across rated gross vehicle weight conditions. Fixed drawbar configurations occupy the mature volume tier in agricultural and construction trailer applications where standardized hitch heights predominate, while adjustable drawbar variants capture expanding demand from rental fleets and multi-vehicle operators requiring rapid coupling adaptation. Aluminum material segments are gaining structural share as fleet operators prioritize payload recovery against tightening axle weight regulations, though steel retains margin concentration in heavy-duty mining and military trailer specifications.
The National Highway Traffic Safety Administration enforces FMVSS No. 223 rear impact guard standards that indirectly shape drawbar load-path engineering for commercial trailers operating in the United States. The European Union's Machinery Directive and CE marking requirements impose dynamic load testing protocols that filter non-compliant suppliers from aftermarket distribution channels serving European commercial fleets. Stakeholders must monitor evolving brake-by-wire integration standards and e-trailer electrification architectures that will redefine mechanical drawbar specifications within the next product development cycle.
Market Dynamics
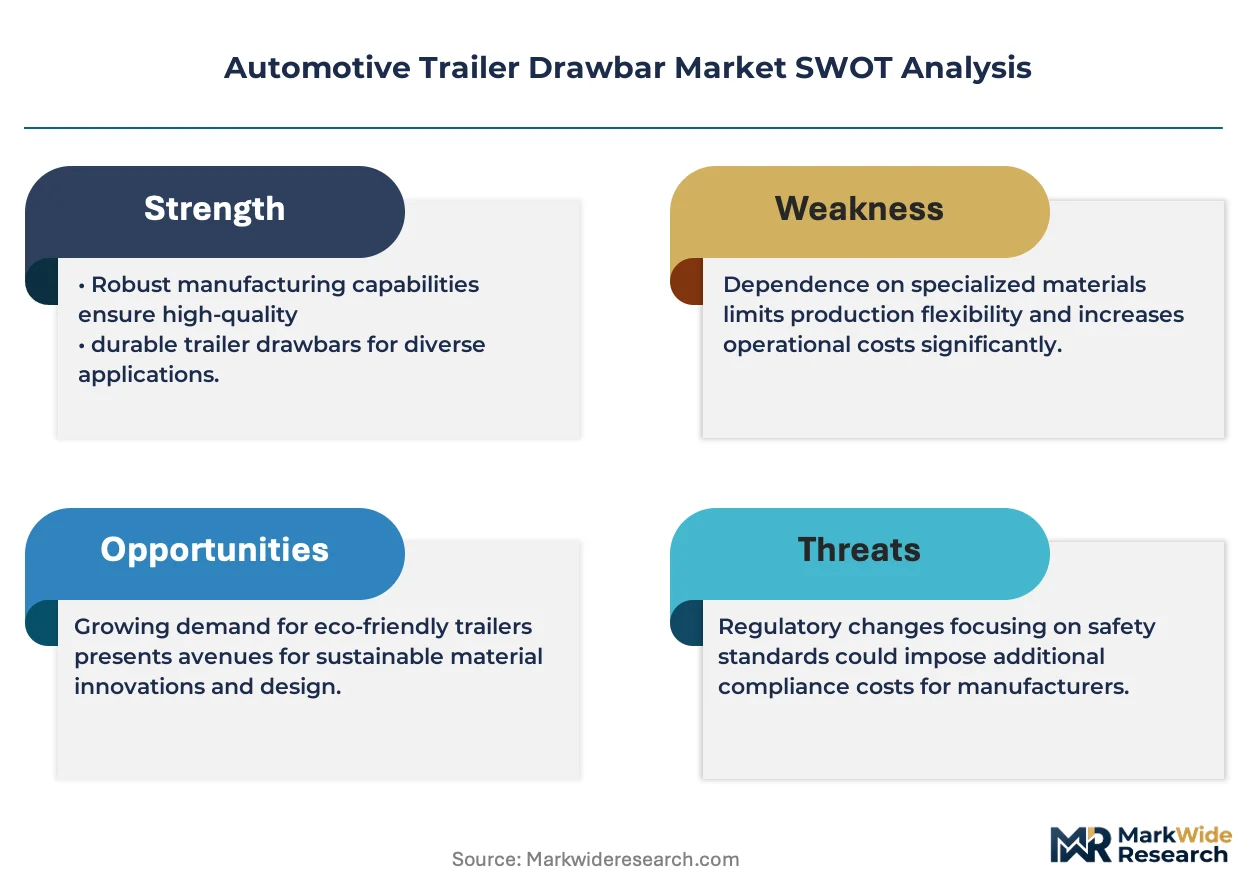
SAE Class IV/V certification requirements are compressing supplier margins while fragmenting procurement channels between certified premium suppliers and uncertified commodity producers serving price-sensitive agricultural segments.
Growth Catalysts
- E-commerce logistics expansion:Commercial fleet operators across Germany and the United States are upgrading to heavier-rated drawbar assemblies to accommodate expanded trailer configurations for last-mile delivery density.
- EU Green Deal material mandates:Regulatory pressure from Brussels is accelerating aluminum and composite material adoption as fleet operators prioritize payload recovery against tightening axle weight regulations.
- Sensor integration protocols:Trailer stability monitoring systems are creating specification pull-through for drawbar modules with integrated load-path sensing and real-time telemetry capabilities.
Market Restraints
- High-tensile steel input volatility:Alloy steel price swings and scrap availability constraints are compressing margin predictability for heavy-duty mining and military trailer specifications.
- Supplier concentration in Baden-Württemberg:German axle-drawbar system integration creates geographic supply risk for European OEMs dependent on single-source certification pathways.
- Dynamic load testing compliance costs:EU Machinery Directive CE marking protocols impose capital-intensive validation requirements that filter smaller aftermarket suppliers from commercial fleet channels.
Strategic Opportunities
- Brake-by-wire e-trailer architectures:Electrification of trailer braking systems is opening specification windows for smart drawbar modules with integrated power and data transmission pathways.
- Rental fleet adjustable configurations:Multi-vehicle operators requiring rapid hitch height adaptation represent an underserved segment beyond fixed agricultural applications.
- US FMVSS No. 223 alignment services:Rear impact guard load-path engineering expertise creates consulting and retrofit revenue streams for engineering houses serving commercial trailer manufacturers.
Industry Challenges
- Welding certification scarcity:Qualified aluminum TIG welders for high-tensile alloy drawbar fabrication command premium wages and extended recruitment timelines across manufacturing hubs.
- Legacy mechanical-electronic integration:Brake-by-wire standardization delays are forcing parallel development tracks for mechanical and sensor-integrated drawbar specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Trailer Drawbar Market |
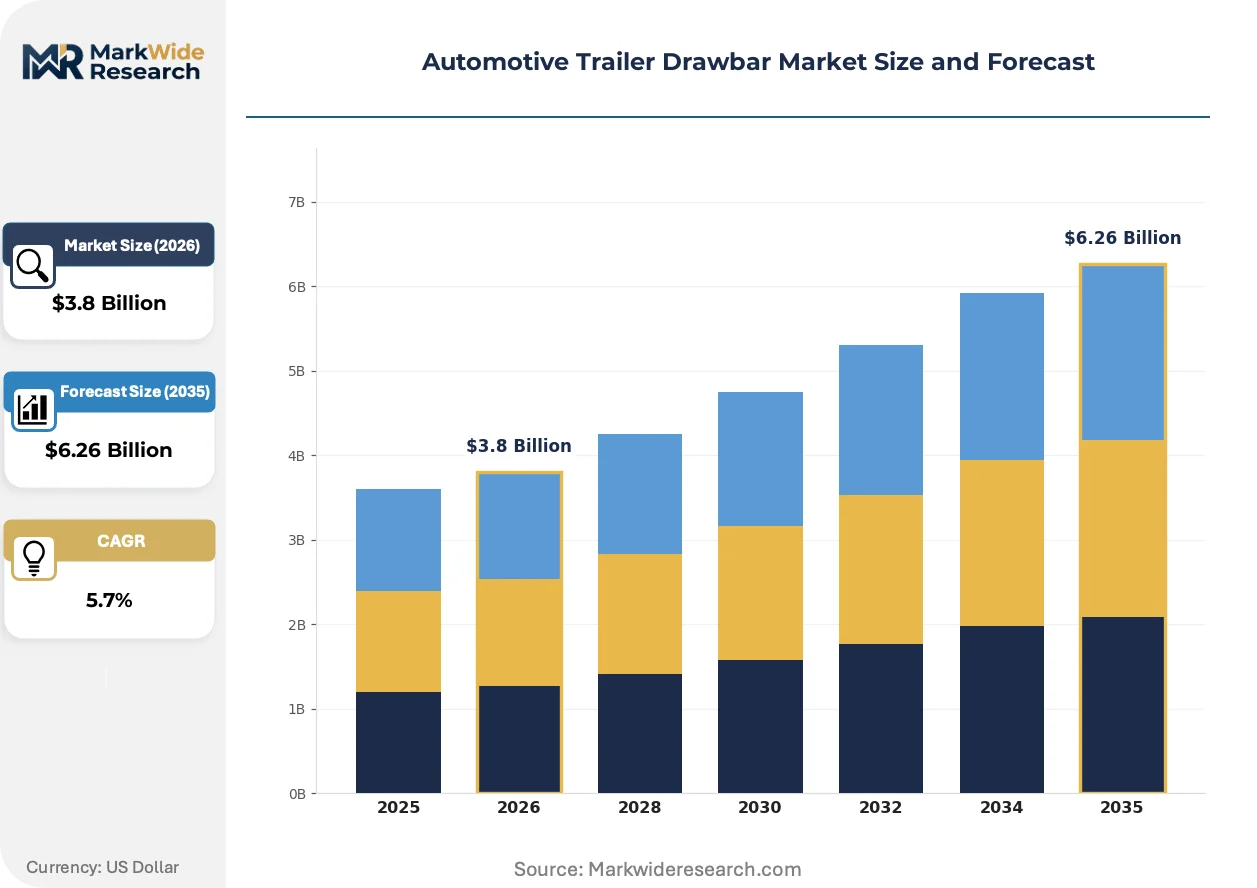
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Drawbar, Adjustable Drawbar, Heavy-Duty Drawbar, Lightweight Drawbar Material: Steel, Aluminum, Composite, Plastic End User: OEMs, Aftermarket Providers, Commercial Fleets, Individual Consumers Installation Type: Welded, Bolt-On, Quick-Release, Integrated |
| Companies Covered | Bosch, Hyundai Motor Group, Dennison Trailers Ltd., Great Dane, Böckmann Fahrzeugwerke GmbH, China International Marine Containers (Group) Co., Ltd., Humbaur GmbH, AL-KO, BPW Bergische Achsen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Trailer Drawbar Market Strategic Shifts
Material science advances and regulatory digitization are compressing traditional steel-dominated specifications while opening modular, sensor-ready architectures for next-generation trailer electrification.
Extruded aluminum alloy drawbar fabrication is fragmenting the heavy-duty segment as fleet operators recover payload capacity against axle weight limits. German agricultural OEMs are adopting hybrid steel-aluminum configurations fastest, with corrosion-resistant specifications commanding sustained specification premiums over commodity steel alternatives. This material rotation is fragmenting supplier tiering between integrated aluminum processors and legacy steel fabricators.
EPA emissions standards for commercial vehicle efficiency are indirectly shaping drawbar lightweighting specifications through fleet fuel economy optimization mandates. The regulatory pressure cascades into trailer GVWR management, where aluminum material substitution directly supports tractor-trailer combination efficiency targets. California Air Resources Board precedents are extending influence into Midwest fleet procurement specifications.
After-sales service unbundling is disrupting traditional OEM-captive distribution for drawbar replacement components. Independent commercial fleet maintenance providers in Texas and Ohio are sourcing direct from certified suppliers, compressing distributor margin pools. This channel fragmentation is most visible in multi-site rental fleet operations with centralized procurement functions and technical specification authority.
Automotive Trailer Drawbar Market Segmentation
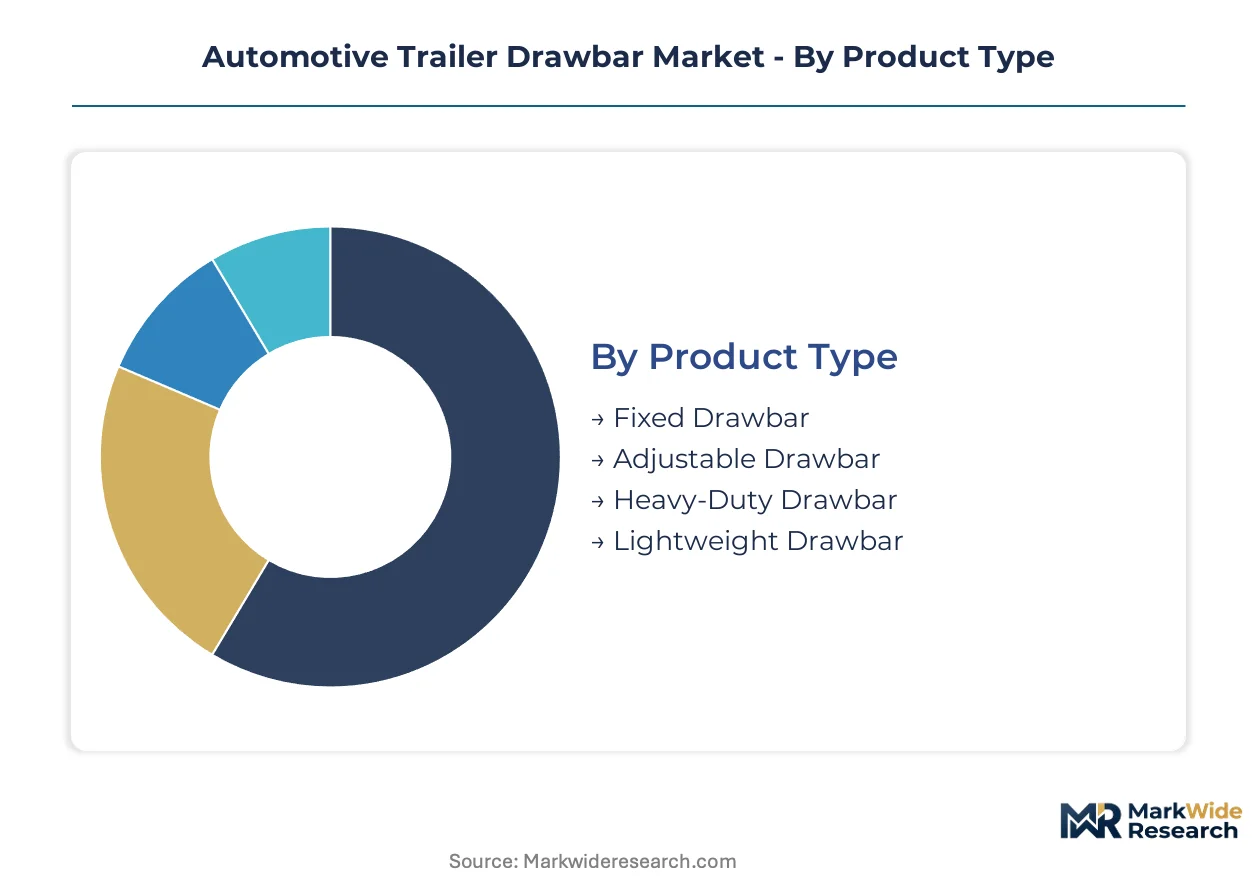
Drawbar specification tiers map directly to certification pathways and axle weight regulations across commercial fleet procurement. Material and installation choices cascade through total cost of ownership calculations for agricultural, construction, and logistics operators.
Product Type:
EU Machinery Directive CE marking and SAE Class IV/V certification requirements create divergent engineering validation costs across configuration categories.
- Fixed Drawbar:Standardized hitch geometry dominates agricultural and construction trailer specifications where single-vehicle coupling predominates. German OEMs in Baden-Württemberg specify fixed configurations for corrosion-resistant premium agricultural trailers commanding sustained specification premiums.
- Adjustable Drawbar:Rapid hitch height adaptation enables multi-vehicle fleet operators to standardize inventory across tractor-trailer combinations. Rental fleets in Texas and Ohio are sourcing adjustable variants direct from certified suppliers, bypassing traditional distributor channels.
- Heavy-Duty Drawbar:Mining and military trailers specify high-tensile steel load-path engineering for extreme GVWR conditions.
- Lightweight Drawbar:Extruded aluminum fabrication supports payload recovery against tightening axle weight regulations.
Fixed configurations handle the majority of throughput; adjustable variants are gaining share fastest among rental fleet procurement.
Material:
Cost tier differentiation separates premium alloy specifications from commodity steel alternatives in fleet procurement evaluations.
- Steel:High-tensile alloy grades retain margin concentration in heavy-duty mining and military specifications where dynamic load testing protocols demand proven fatigue resistance. Scrap availability constraints and alloy price volatility compress margin predictability for fabricators serving these segments.
- Aluminum:Extruded alloy fabrication fragments supplier tiering between integrated aluminum processors and legacy steel fabricators. EPA emissions standards indirectly accelerate aluminum adoption through fleet fuel economy optimization mandates cascading into trailer GVWR management.
- Composite:Emerging specifications target sensor-integrated modules with embedded load-path telemetry.
- Plastic:Limited to light-duty consumer applications below commercial certification thresholds.
Steel retains volume leadership; aluminum is climbing the fastest on specification share.
End User:
Customer type determines channel structure and technical specification authority in procurement workflows.
- OEMs:Integrated axle-drawbar system sourcing dominates European supply chains with single-source certification dependencies.
- Aftermarket Providers:CE marking validation requirements filter smaller suppliers from commercial fleet channels serving European markets.
- Commercial Fleets:Centralized procurement functions with in-house technical specification authority are unbundling after-sales service from OEM-captive distribution.
- Individual Consumers:Price-sensitive agricultural segments drive commodity specification demand outside certified premium tiers.
Commercial fleets concentrate specification pull-through; aftermarket providers face the steepest compliance barriers.
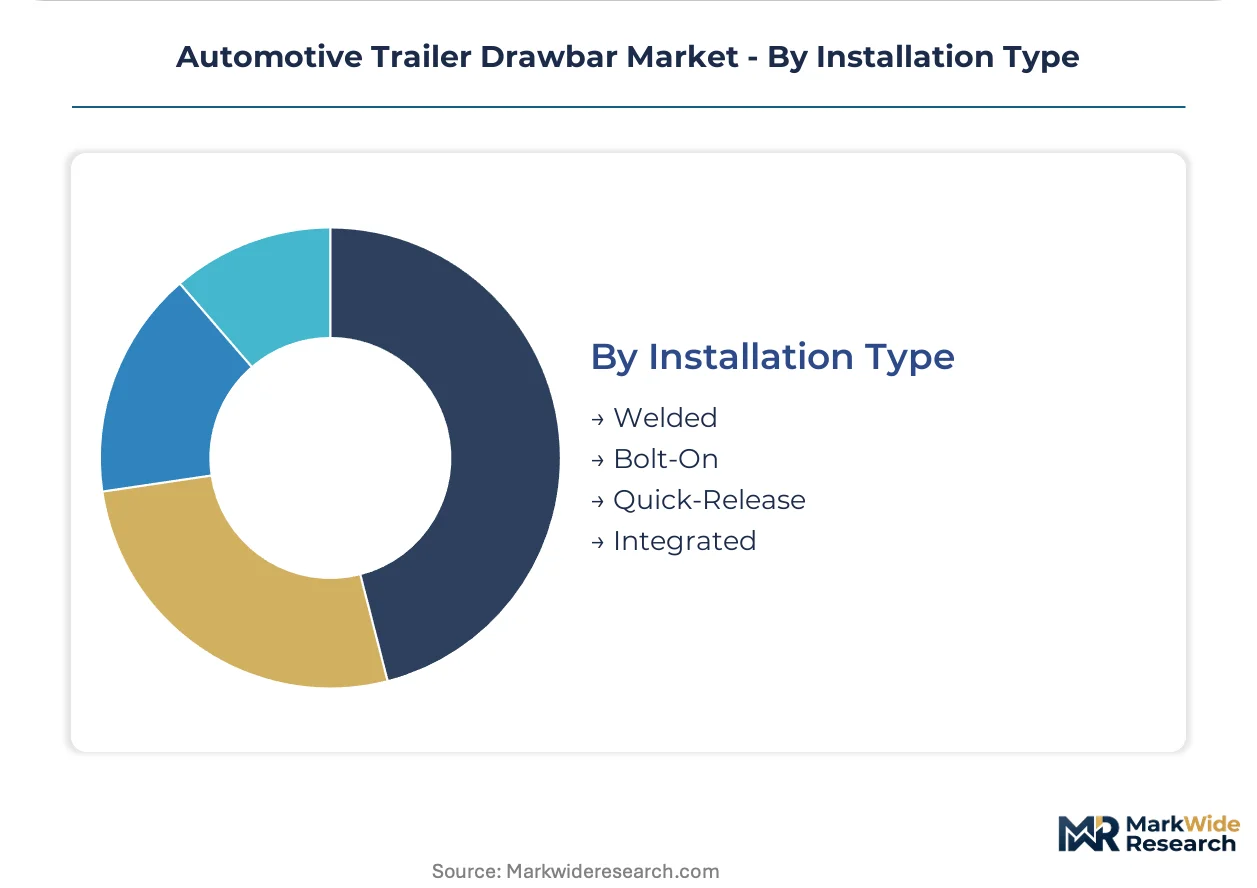
Installation Type:
Installation method correlates with field service capability requirements and warranty liability structures.
- Welded:Permanent fabrication demands qualified aluminum TIG welders commanding premium wages and extended recruitment timelines across manufacturing hubs.
- Bolt-On:Field-replaceable configurations align with independent maintenance provider capabilities in decentralized fleet operations.
- Quick-Release:Rapid coupling adaptation supports rental fleet operational flexibility.
- Integrated:Axle-drawbar system consolidation reduces supplier count for OEM assembly operations.
Bolt-on installations dominate aftermarket volume; quick-release specifications show the steepest expansion trajectory in rental applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in trailer drawbar assemblies favor manufacturing clusters with integrated axle-system capabilities. Germany and the United States maintain trade surpluses in premium certified components, while China supplies volume-tier fabrications to price-sensitive agricultural markets.
United States
Commercial fleet operators in Texas and Ohio are upgrading to heavier-rated drawbar assemblies for e-commerce logistics trailers. NHTSA enforces FMVSS No. 223 rear impact guard standards that indirectly shape drawbar load-path engineering for commercial trailers. Independent maintenance providers in the Midwest are unbundling after-sales service from OEM-captive distribution channels.
Germany
Agricultural OEMs in Baden-Württemberg specify corrosion-resistant premium drawbar configurations commanding sustained specification premiums. The EU Green Deal accelerates aluminum and composite material adoption as fleet operators prioritize payload recovery. Böckmann Fahrzeugwerke and AL-KO anchor a dense supplier cluster serving premium trailer manufacturers.
China
Volume-tier fabricators supply standardized steel drawbar configurations to emerging market agricultural segments. GB standards and MIIT regulations shape domestic certification requirements for trailer coupling systems. Manufacturing concentrates in coastal provinces with integrated steel processing and export logistics infrastructure.
Japan
Precision-engineered drawbar modules support domestic light commercial vehicle and specialty trailer production. METI efficiency mandates cascade into trailer lightweighting specifications through fleet fuel economy optimization. Industrial clusters in the Chubu region maintain specialized fabrication capabilities for high-tensile alloy processing.
India
Domestic trailer OEMs source bolt-on drawbar configurations for agricultural and construction applications. BIS certification requirements and axle weight regulations filter supplier tiers in commercial fleet procurement. Manufacturing activity concentrates in Maharashtra and Gujarat with expanding fabrication capacity for regional aftermarket distribution.
Automotive Trailer Drawbar Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and material processing capabilities. The vendor base fragments between premium certified suppliers serving European OEM supply chains and commodity producers targeting price-sensitive agricultural segments. Three archetypes dominate: integrated axle-drawbar system providers, corrosion-resistant agricultural specialists, and sensor-integrated module developers. Competitive moves concentrate on strategic partnerships for brake-by-wire integration and geographic expansion into rental fleet channels.
Among Germany-based fabricators, Böckmann Fahrzeugwerke GmbH and AL-KO occupy positions within the premium-tier certification pathway, while Bosch exemplifies the sensor-integrated module archetype through its stability monitoring capabilities.
| Leading Market Players |
|---|
| Bosch |
| Hyundai Motor Group |
| Dennison Trailers Ltd. |
| Great Dane |
| Böckmann Fahrzeugwerke GmbH |
| China International Marine Containers (Group) Co., Ltd. |
| Humbaur GmbH |
| AL-KO |
| BPW Bergische Achsen |
| Others |
Value Chain & Pricing Dynamics
SAE Class IV/V certification gates both supplier qualification and price differentiation simultaneously, compressing uncertified commodity producers into thin-margin agricultural tiers while reserving premium pricing corridors for integrated axle-drawbar system providers serving European OEMs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade and after-sales service bundling as the primary differentiation drivers. Price erosion runs through the commodity steel tier as Chinese volume fabricators compete on landed cost for emerging market agricultural demand. Fleet operators with centralized procurement functions exhibit the lowest price sensitivity, while individual agricultural purchasers drive aggressive negotiation in uncertified aftermarket channels.
Supply Chain Analysis
Inventory cycles for high-tensile alloy inputs extend lead times during scrap availability constraints, forcing European fabricators to pre-position aluminum extrusion stock. Manufacturing gravity centers on Germany, China, and the United States, with raw material feeds drawing from Swedish specialty steel mills, Chinese primary aluminum smelters, and domestic scrap recovery networks. Single-source vulnerability concentrates in Baden-Württemberg for integrated axle-drawbar certification pathways. Distribution runs through OEM-captive channels for premium tiers and independent maintenance providers for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where CE marking and SAE certification create entrenched switching costs that protect incumbent positioning against commodity encroachment.
For Market Incumbents: Fortify certification depth by pursuing brake-by-wire integration partnerships ahead of e-trailer standardization, while adding captive aluminum extrusion capacity in Central Europe to offset scrap volatility. AL-KO's integrated system architecture demonstrates how axle-drawbar consolidation defends against modular disruptors. For New Entrants and Emerging Players: Differentiate on sensor-integrated smart drawbar modules for commercial fleet telemetry, targeting the underserved rental fleet adjustable configuration segment in Texas and Ohio. A direct-sourcing go-to-market model bypasses traditional distributor markups and aligns with centralized fleet procurement workflows. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive component specialists holding dormant drawbar fabrication capabilities. Long-term viability hinges on electrification-readiness rather than mechanical legacy. Watch for NHTSA brake-by-wire standardization announcements as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Integration Partnership | Positions suppliers for e-trailer electrification architectures ahead of SAE standardization. |
| Aluminum Extrusion Capacity Expansion | Captures payload recovery demand from EU Green Deal mandates and EPA fleet efficiency rules. |
| Sensor Module Development | Enables trailer stability telemetry for commercial fleets requiring real-time load monitoring. |
| Direct Fleet Channel Development | Bypasses distributor compression in Texas and Ohio rental fleet procurement. |
| CE Marking Acceleration Program | Filters smaller competitors from European commercial aftermarket channels. |
Study Parameters
A standing panel of OEM procurement directors, aftermarket service managers, fleet maintenance supervisors, and aluminum fabrication engineers provided ongoing calibration across primary fieldwork and secondary validation. Bottom-up demand modeling triangulated against customs trade records, SAE certification registries, EPA fleet efficiency disclosures, and European axle-system production data.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon, with segmentation modeled by material grade, drawbar configuration type, end-user category, and regional regulatory cluster. CAGRs derived from shipment volume trajectories and average selling price movements, incorporating fleet upgrade cycles and e-commerce logistics expansion as industry-specific demand inputs.
Material uncertainties — alloy price volatility, brake-by-wire standardization delays, and CE marking enforcement intensity — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
South Africa Automotive Actuators Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Half-Shaft Assemblies Market
Automotive Assemblies
Rocker Arm Assembly Market
Automotive Assemblies
Automotive Die Casting Market
Automotive Assemblies
United States Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Side Impact Assembly Market
Automotive Assemblies
Automotive Cross Member Market
Automotive Assemblies
Body in White (BIW) Market
Automotive Assemblies
Global Automotive Center Stacks Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Automotive Tensioner Market
Automotive Assemblies
China and Saudi Arabia Automotive Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Global Automotive Terminal Market
Automotive Assemblies
Global Automotive Air Spring Market