
 Automotive OEM Brake Friction Material Market | 2026-2036
Automotive OEM Brake Friction Material Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive OEM Brake Friction Material Market Analysis
Copper-free formulations is consolidating market positioning as original equipment manufacturers phase out heavy metal content under tightening environmental mandates. Robert Bosch leverages its integrated braking systems portfolio to anchor European OEM supply relationships. Akebono Brake Industry specializes in low-copper and copper-free pad architectures for Japanese and North American automakers. Continental dominates module-level integration where friction material selection ties directly to electronic braking control calibration.
Automotive OEM brake friction materials encompass engineered composites bonded to structural backplates, formulated from resins, fibers, and fillers cured under 150-250 bar pressure to achieve coefficient of friction targets between 0.35 and 0.45 across operating temperature ranges. These components convert kinetic energy to thermal energy during deceleration events, with material stability determining pedal feel, noise characteristics, and dust generation profiles. Semi-metallic formulations occupy the volume core of passenger vehicle programs where thermal load tolerance meets cost constraints. Ceramic segments command premium positioning in performance rating tiers where fade resistance and rotor compatibility justify elevated pricing structures.
The EPA's copper-free brake initiative and California's SB 346 phase-out timeline shape North American material roadmaps, while ECHA's REACH restrictions on heavy metal content enforce reformulation across European supply bases. OEM quality rating tiers face escalating test protocol requirements as FMVSS 135 and ECE R90 harmonization pressures drive certification investment. Stakeholders must monitor regulatory divergence between regional copper phase-out schedules and emerging per- and polyfluoroalkyl substance restrictions that threaten existing binder chemistries.
Market Dynamics
Copper-free friction formulations are forcing material suppliers to rebuild binder chemistries and fiber architectures from the ground up as automakers redesign brake systems around regenerative energy recovery. This technological pivot compresses development cycles while elevating certification requirements across every major supply base.
Growth Catalysts
- EU REACH heavy metal restrictions:European automakers must eliminate copper content from brake pads by mandated deadlines, creating immediate demand for reformulated semi-metallic and ceramic alternatives.
- Electric vehicle platform proliferation:Battery-electric architectures reduce mechanical braking frequency, extending pad life but requiring materials optimized for intermittent high-load events and corrosion resistance.
- California SB 346 phase-out timeline:The state's copper-free mandate accelerates North American OEM roadmaps and pulls suppliers into compliance ahead of federal benchmarks.
Market Restraints
- Phenolic resin supply concentration:Binder chemistry inputs face pricing volatility as petroleum-derived feedstocks fluctuate and specialty resin producers consolidate in Northeast Asia.
- Aramid fiber import dependency:High-performance fiber supply chains concentrate among limited global producers, exposing friction material compounders to allocation risk during demand surges.
- Copper-free friction coefficient stability:Replacement formulations struggle to match the thermal conductivity and wear characteristics of legacy copper-bearing materials across full temperature operating ranges.
Strategic Opportunities
- India domestic OEM supply localization:Maruti Suzuki and Tata Motors are expanding local sourcing requirements for brake system components under national manufacturing incentive frameworks.
- Per- and polyfluoroalkyl substance replacement chemistry:Emerging restrictions on PFAS binders create first-mover advantage for suppliers developing fluorine-free friction stabilization technologies.
- Regenerative braking system integration:Friction material suppliers can deepen module-level partnerships with electronic braking control specialists to co-develop pad-calibration packages.
Industry Challenges
- Dual certification timeline compression:Suppliers must simultaneously achieve FMVSS 135 and ECE R90 harmonized testing while managing divergent regional copper phase-out schedules.
- Tribology simulation capability gaps:Finite element modeling of friction interfaces requires scarce computational materials science talent that suppliers compete to recruit from academic and motorsport channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive OEM Brake Friction Material Market |
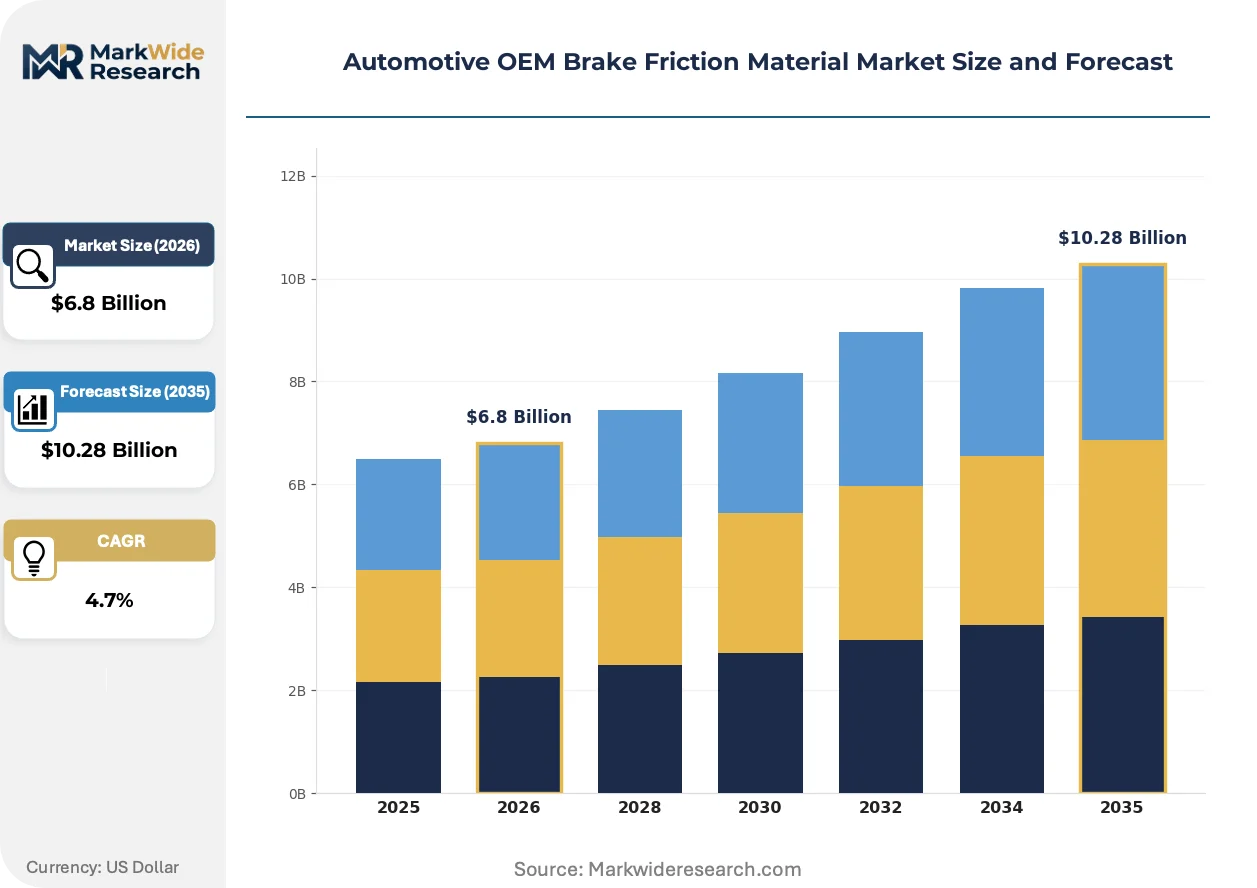
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Organic, Semi-Metallic, Metallic, Ceramic Product Form: Pads, Shoes, Discs, Linings End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, All-Terrain Vehicles Performance Rating: High Performance, Standard, OEM Quality, Heavy Duty |
| Companies Covered | Brembo, Robert Bosch, Akebono Brake Industry, TMD Friction, Nisshinbo Holdings, Federal-Mogul, ZF Friedrichshafen, Continental, Miba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive OEM Brake Friction Material Market Emerging Trajectories
Material science advances are collapsing traditional trade-offs between thermal performance, environmental compliance, and rotor compatibility. Suppliers now compete on simulation-driven formulation speed rather than incremental recipe refinement.
Non-asbestos organic matrix technologies are modularizing brake system design. These formulations incorporate bio-sourced fibers and ceramic reinforcements to deliver stable friction coefficients across regenerative braking duty cycles. Tier 1 suppliers adopt them for electric vehicle platforms where reduced brake usage extends service intervals. The technology is modularizing supplier-OEM relationships around co-development contracts rather than commodity supply agreements.
ECHA's expanding REACH restrictions on heavy metal content are forcing European compounders to eliminate copper and antimony trisulfide from friction materials ahead of 2025 enforcement milestones. Manufacturers must retest entire product portfolios under ECE R90 protocols while maintaining supply continuity to assembly plants. Premium passenger vehicle programs absorb the highest compliance costs as they prioritize fade resistance and noise suppression targets.
Fleet operators and leasing companies now specify brake dust generation limits in procurement contracts, displacing traditional price-per-axle-set metrics. OEMs respond with low-dust ceramic formulations that command position in corporate fleet supply agreements. Germany's commercial vehicle channels exhibit the strongest specification pressure as municipal transit authorities mandate particulate emission reductions from braking systems.
Automotive OEM Brake Friction Material Market Segmentation
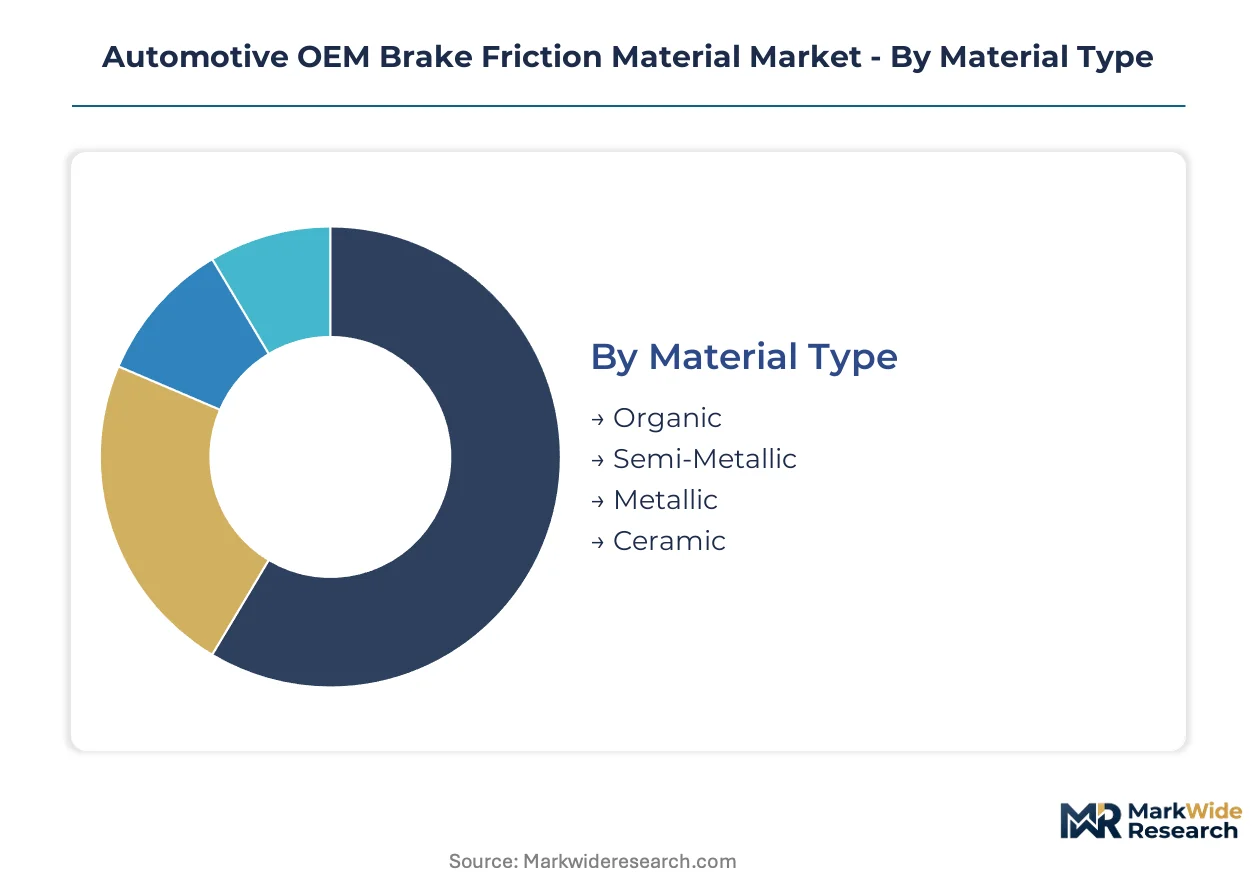
Brake friction material segmentation reflects divergent thermal load requirements across vehicle architectures. Material composition and product form selections cascade into certification tiers that determine OEM supply eligibility and pricing bandwidth.
Material Type:
Cost tier dictates material selection for platform engineers balancing thermal performance against per-vehicle budget constraints.
- Semi-Metallic:Iron and steel fiber composites bonded with phenolic resins deliver thermal conductivity above 40 W/mK for sustained high-load braking. Passenger vehicle volume programs in Germany specify these formulations for their fade resistance under autobahn-speed deceleration cycles.
- Ceramic:Silicate and copper-free ceramic matrices engineered for coefficient stability above 300°C operating temperatures. Premium OEM sourcing clusters around Stuttgart prioritize these for rotor compatibility and extended service intervals in corporate fleet contracts.
- Organic:Glass, rubber, and Kevlar fiber blends with minimal metallic content for reduced rotor wear and noise suppression.
- Metallic:Sintered metal powders compressed under extreme pressure for maximum thermal mass in heavy-load commercial applications.
Semi-Metallic leads on scale; Ceramic leads on momentum.
Product Form:
Application architecture determines whether friction material integrates as replaceable wear components or permanent rotor surfaces.
- Pads:Composite blocks bonded to steel backplates through hot-press curing at 150-250 bar pressure, designed for caliper-actuated disc brake systems. Electric vehicle platforms specify corrosion-resistant formulations for intermittent high-load events where regenerative braking dominates.
- Shoes:Curved friction linings riveted or bonded to steel platforms for drum brake configurations in cost-optimized rear axle applications.
- Discs:Integral friction surfaces cast or machined as single-piece rotors, predominantly carbon-ceramic for supercar OEM programs.
- Linings:Bulk friction material supplied in rolls or sheets for aftermarket cutting and bonding to commercial vehicle brake bands.
Pads dominate procurement volume; Discs command the steepest expansion trajectory as performance tier OEMs upgrade brake system specifications.
End User:
Customer type shapes duty cycle profiles that determine fiber architecture and binder chemistry requirements.
- Passenger Vehicles:Low-copper and copper-free formulations engineered for reduced dust generation under urban stop-and-go conditions. California's SB 346 compliance deadlines accelerate reformulation roadmaps for North American OEM supply bases.
- Commercial Vehicles:Heavy-duty semi-metallic and sintered metal compositions rated for sustained thermal loads above 500°C during mountain descent braking.
- Motorcycles:Compact pad geometries with high specific friction coefficients for wet-weather performance in two-wheeler OEM programs.
- All-Terrain Vehicles:Contamination-resistant formulations for off-road duty cycles with elevated mud and debris exposure.
Passenger Vehicles anchor procurement scale; Commercial Vehicles gain share fastest as fleet electrification extends brake service intervals and elevates per-event thermal loads.
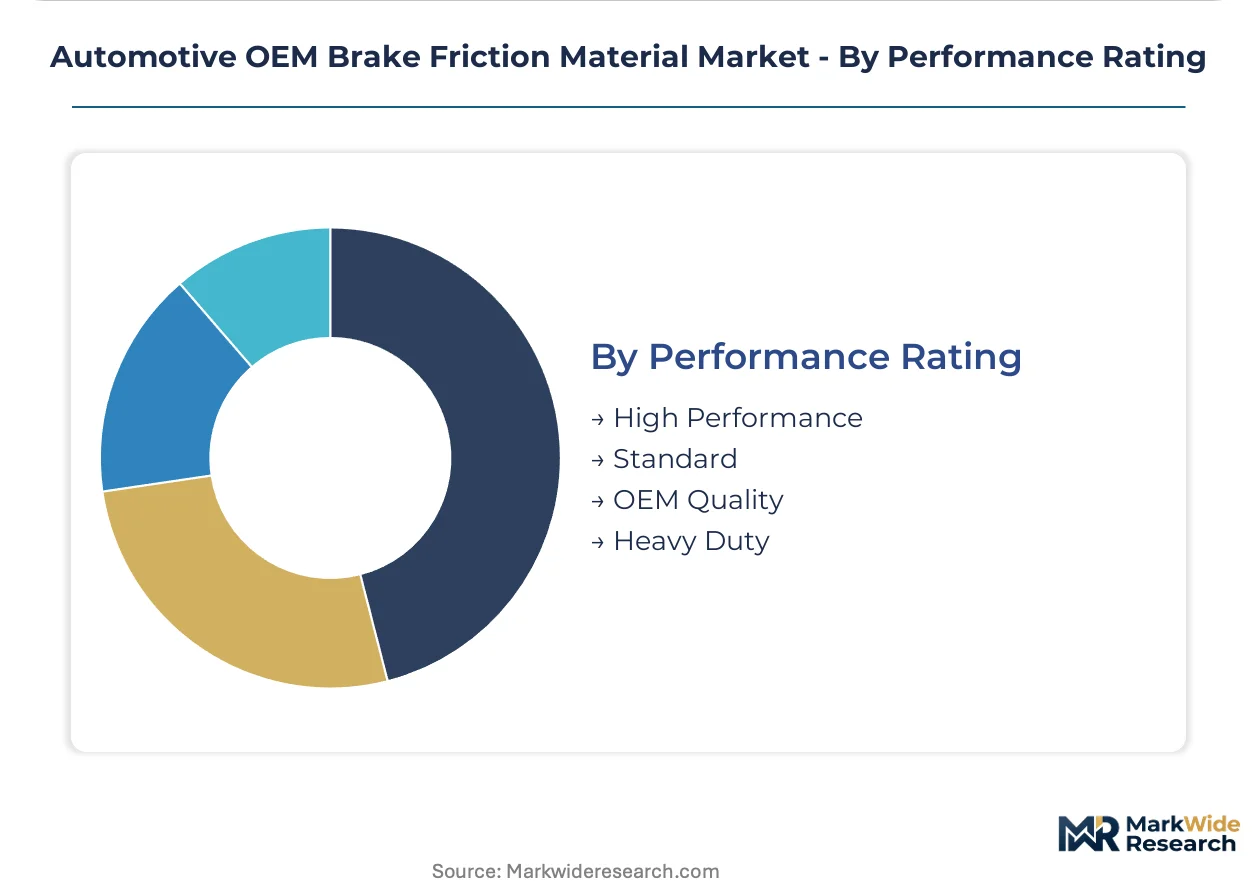
Performance Rating:
Margin stratification separates commodity supply agreements from co-development partnerships with module-level integration requirements.
- OEM Quality:Baseline formulations meeting FMVSS 135 and ECE R90 harmonized test protocols for mass-market vehicle programs. European compounders face retesting burdens under ECHA REACH heavy metal restrictions while maintaining supply continuity to assembly plants.
- High Performance:Fade-resistant ceramic and advanced semi-metallic matrices calibrated for track-day thermal cycling and premium pedal feel.
- Standard:Cost-optimized organic and low-metallic formulations for emerging market vehicle platforms with reduced thermal load requirements.
- Heavy Duty:Reinforced fiber architectures for commercial vehicle and specialty equipment applications with sustained high-temperature operation.
OEM Quality leads on volume concentration; High Performance expands most quickly as premium passenger vehicle programs absorb compliance costs for copper-free certification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors procurement concentration for premium brake friction materials, with German OEM sourcing clusters driving continental formulation standards and certification requirements across European supply chains.
United States
California's SB 346 copper phase-out deadlines accelerate reformulation roadmaps for Detroit Three automakers. The EPA's copper-free brake initiative shapes federal compliance benchmarks. Michigan-based Tier 1 suppliers concentrate R&D investment around low-dust ceramic architectures for corporate fleet contracts.
Germany
Premium passenger vehicle programs absorb the highest copper-free compliance costs as automakers prioritize fade resistance targets. ECHA's REACH heavy metal restrictions enforce 2025 elimination deadlines for copper and antimony trisulfide. Stuttgart and Munich sourcing clusters anchor continental procurement patterns for ceramic and advanced semi-metallic formulations.
China
Domestic OEMs expand local sourcing requirements under national manufacturing incentive frameworks for brake system components. MIIT emissions standards and dual carbon goals pressure material suppliers toward copper-free architectures. Yangtze River Delta manufacturing bases concentrate volume production for both domestic brands and joint-venture programs.
Japan
Automakers specify low-copper and copper-free pad architectures for export-market compliance across multiple regulatory jurisdictions. METI industrial standards harmonize with ECE R90 protocols to streamline dual certification burdens. Aichi Prefecture supplier clusters coordinate formulation development with North American and European OEM technical centers.
India
Maruti Suzuki and Tata Motors expand domestic sourcing mandates for friction materials under PLI scheme incentives. BIS quality standards elevate certification requirements for component suppliers entering OEM supply bases. Tamil Nadu and Gujarat automotive corridors attract compounder investments to serve expanding passenger vehicle and commercial vehicle production.
Automotive OEM Brake Friction Material Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers retool manufacturing lines for copper-free formulation output. The market structure concentrates around integrated braking system specialists, independent friction material compounders, and diversified automotive component conglomerates. Three archetypes define competitive positioning: module-level integrators controlling electronic calibration interfaces, formulation specialists commanding material science IP, and scale-driven manufacturers serving emerging market volume programs. M&A activity and strategic partnerships represent the dominant competitive moves as firms acquire simulation capabilities and binder chemistry expertise.
Within the module-level integrator tier, Robert Bosch and Continental exemplify suppliers leveraging electronic braking control calibration to deepen OEM relationships. Brembo occupies a position among performance-tier specialists where fade resistance and rotor compatibility justify premium positioning. Akebono Brake Industry represents the formulation specialist archetype, with its company structure indicating concentrated expertise in low-copper and copper-free architectures for Japanese and North American automakers.
| Leading Market Players |
|---|
| Brembo |
| Robert Bosch |
| Akebono Brake Industry |
| TMD Friction |
| Nisshinbo Holdings |
| Federal-Mogul |
| ZF Friedrichshafen |
| Continental |
| Miba |
| Others |
Supply Flow & Price Mechanics
EU REACH copper phase-out mandates gate qualified supply access for European compounders while stratifying pricing tiers between certified and non-compliant formulations. Premium OEM programs absorb elevated certification costs for fade-resistant ceramic matrices, whereas volume-tier suppliers face margin compression from dual-protocol retesting burdens.
Pricing Analysis
Input-cost pass-through from aramid fiber and phenolic resin volatility shapes contract negotiations between compounders and Tier 1 braking system integrators. Three-tier pricing structure across premium, standard, and economy levels separates ECE R90-certified ceramic formulations from baseline semi-metallic and cost-optimized organic alternatives. Cost compression in the standard tier intensifies because petroleum-derived binder feedstocks fluctuate with energy markets. Fleet procurement managers exhibit highest price sensitivity, while premium passenger vehicle OEMs prioritize fade resistance over per-unit cost.
Supply Chain Analysis
Workforce availability constraints in Germany, China, and Japan shape manufacturing location decisions for copper-free formulation lines. Raw material sourcing draws from Northeast Asian phenolic resin producers, Belgian aramid fiber specialists, and Brazilian mineral ore processors. Single-source vulnerability concentrates in high-performance fiber supply where limited global producers control allocation. Distribution runs through Tier 1 braking system integrators who bundle friction materials with electronic control modules for final OEM assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where fleet electrification shifts demand toward premium ceramic formulations with extended service intervals and reduced dust generation profiles.
For Market Incumbents: Anticipate regulatory divergence between regional copper phase-out schedules by maintaining parallel certification tracks for ECE R90 and FMVSS 135 protocols. Backward integration into phenolic resin production mitigates feedstock volatility exposure. Capacity addition in Tamil Nadu and Gujarat automotive corridors captures Maruti Suzuki and Tata Motors localization mandates before competitor entry. For New Entrants and Emerging Players: PFAS-free binder chemistry represents a technology-first wedge into European supply chains ahead of ECHA restrictions on fluorinated compounds. White-space targets include India domestic OEM supply under PLI scheme incentives and aftermarket low-dust ceramic segments for German municipal transit authorities. Co-development partnerships with electronic braking control specialists offer the most penetrable go-to-market angle against integrated module suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional friction material compounders because copper-free retesting burdens favor scale players with dedicated certification infrastructure. Five-to-ten-year viability hinges on simulation-driven formulation capabilities that compress development cycles. Acquisition target archetype: mid-tier European compounders with ECE R90 test protocols and stranded capacity awaiting copper-free conversion. Watch PFAS regulatory announcements as inflection indicator for binder chemistry replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Free Formulation Scale-Up | ECHA REACH deadlines force portfolio-wide retesting for European compounders by 2025. |
| Backward Integration into Resin Production | Captive phenolic supply insulates margins from petroleum feedstock volatility in Northeast Asia. |
| Regenerative Braking Co-Development | Module-level partnerships with Continental and Robert Bosch deepen OEM relationship lock-in. |
| India Manufacturing Localization | PLI scheme incentives from Maruti Suzuki and Tata Motors attract compounder facility investments. |
| PFAS-Free Binder R&D Investment | First-mover advantage in fluorine-free stabilization chemistry ahead of emerging ECHA restrictions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and friction material R&D directors with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive component suppliers, and ECHA regulatory enforcement notices. Bottom-up segment sizing triangulated against top-down OEM production forecasts.
Segment-weighting across material type, product form, vehicle class, and regional production cluster determined value allocation throughout the forecast period. CAGRs derived from regression analysis of historical formulation adoption curves and OEM platform rollout schedules. Industry-specific inputs included copper-free compliance timeline assumptions and regenerative braking duty cycle profiles by propulsion architecture.
The model holds under steady regulatory enforcement timelines and OEM platform rollout schedules; deviation in ECHA restriction acceleration or battery-electric vehicle adoption rates would shift volume projections. Material deviation in PFAS regulatory triggers or phenolic resin supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Small Engine Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Mexico Automotive Air Filters Market
Automotive Parts
Commercial Vehicle Brake Chambers Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Global Automotive Gasket and Seal Market