
 Automotive Brake System and Components Market | 2026-2036
Automotive Brake System and Components Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake System and Components Market Analysis
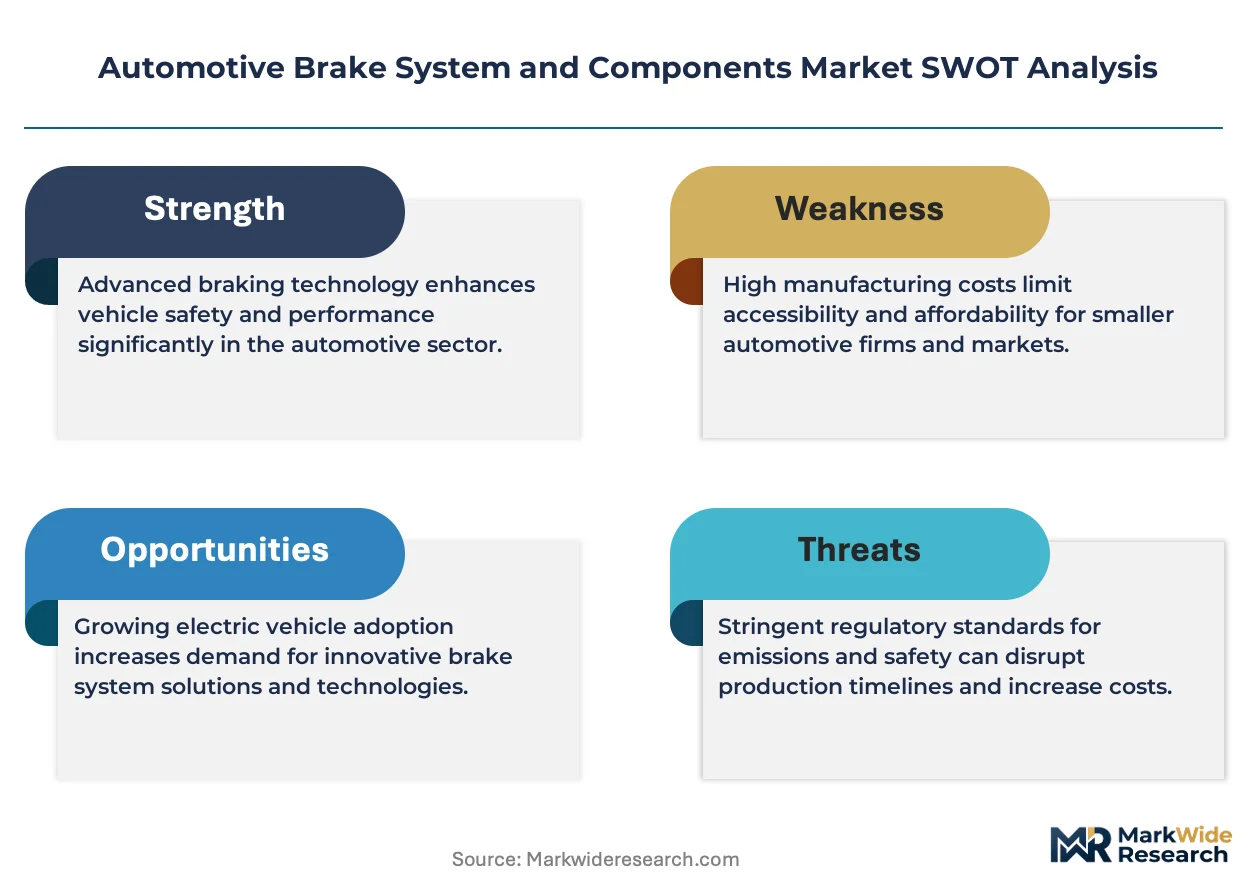
NHTSA Federal Motor Vehicle Safety Standard 135 is hardening the cost-of-entry calculus for brake system suppliers serving North American OEM programs. Robert Bosch GmbH leverages its integrated mechatronics portfolio to dominate electro-hydraulic brake control modules. Continental AG anchors European supply relationships through its continental-scale manufacturing footprint for disc brake calipers. ZF Friedrichshafen AG competes on modular brake platform architectures that span passenger and commercial vehicle applications.
An automotive brake system converts kinetic energy into thermal energy through friction interfaces to decelerate or immobilize a vehicle, with disc brake assemblies typically comprising cast iron or carbon-carbon rotors, caliper housings, and organic or metallic friction pads engineered to withstand peak temperatures exceeding 600°C during high-speed braking events. Disc brake configurations occupy the largest share of value across passenger vehicle applications where thermal management and fade resistance determine specification. Electromechanical brake systems represent the fastest-expanding product category as automakers eliminate hydraulic fluid circuits from electric vehicle platforms. Aftermarket Providers capture significant margin pools in regions with high vehicle parc density and extended fleet utilization cycles.
NHTSA, ECE R90 under United Nations Economic Commission for Europe framework, and China's GB 7258 national standard collectively define friction material coefficient requirements, brake system response latency thresholds, and electromagnetic compatibility protocols for electronic braking controls. These frameworks compel suppliers to maintain parallel certification laboratories and region-specific homologation documentation. Stakeholders must monitor regulatory divergence between brake-by-wire permissiveness in European type approval and NHTSA's incrementalist approach to fully decoupled braking architectures.
Market Dynamics
Electromechanical brake architectures are displacing hydraulic circuits across electric vehicle platforms, forcing suppliers to reengineer manufacturing footprints and recalibrate engineering talent pools for software-integrated hardware systems.
Growth Catalysts
- China's GB 7258 brake performance mandates:National standard revisions are compelling domestic OEMs to upgrade friction material specifications, creating specification pull for advanced brake system suppliers.
- Electromechanical brake-by-wire adoption:Electric vehicle platforms are eliminating hydraulic fluid circuits entirely, opening architecture redesign windows for integrated system providers.
- German OEM sourcing concentration:Premium passenger vehicle manufacturers in Stuttgart and Munich are consolidating supplier relationships around mechatronics-capable brake system integrators.
Market Restraints
- Neodymium and copper price volatility:Electromechanical brake motors depend on rare earth magnet supply chains concentrated in Chinese processing facilities.
- Dual homologation cost burden:NHTSA FMVSS 135 and ECE R90 parallel certification requirements force suppliers to maintain redundant testing laboratories.
- Thermal management limitations in carbon-ceramic rotors:High-performance friction materials face production yield constraints that limit volume scalability for mass-market electric vehicles.
Strategic Opportunities
- India's commercial vehicle brake upgrade cycle:Bharat Stage VI emission compliance is accelerating fleet replacement, expanding addressable market for air disc brake retrofits.
- Regenerative braking integration with friction systems:Blended brake control algorithms that coordinate motor regeneration with mechanical braking represent unclaimed IP territory.
- Direct-to-fleet aftermarket channels:Logistics operators with centralized procurement functions are bypassing traditional distribution tiers for brake pad and rotor replacement contracts.
Industry Challenges
- Embedded software safety certification:ISO 26262 functional safety compliance for brake control firmware extends development timelines by 18-24 months.
- Legacy hydraulic system integration:Hybrid vehicle architectures require suppliers to maintain dual competency in fluid dynamics and electromechanical actuation.
- Electromagnetic compatibility testing backlog:ECE R10 compliance verification for electronic braking controls faces laboratory capacity constraints across European certification bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake System and Components Market |
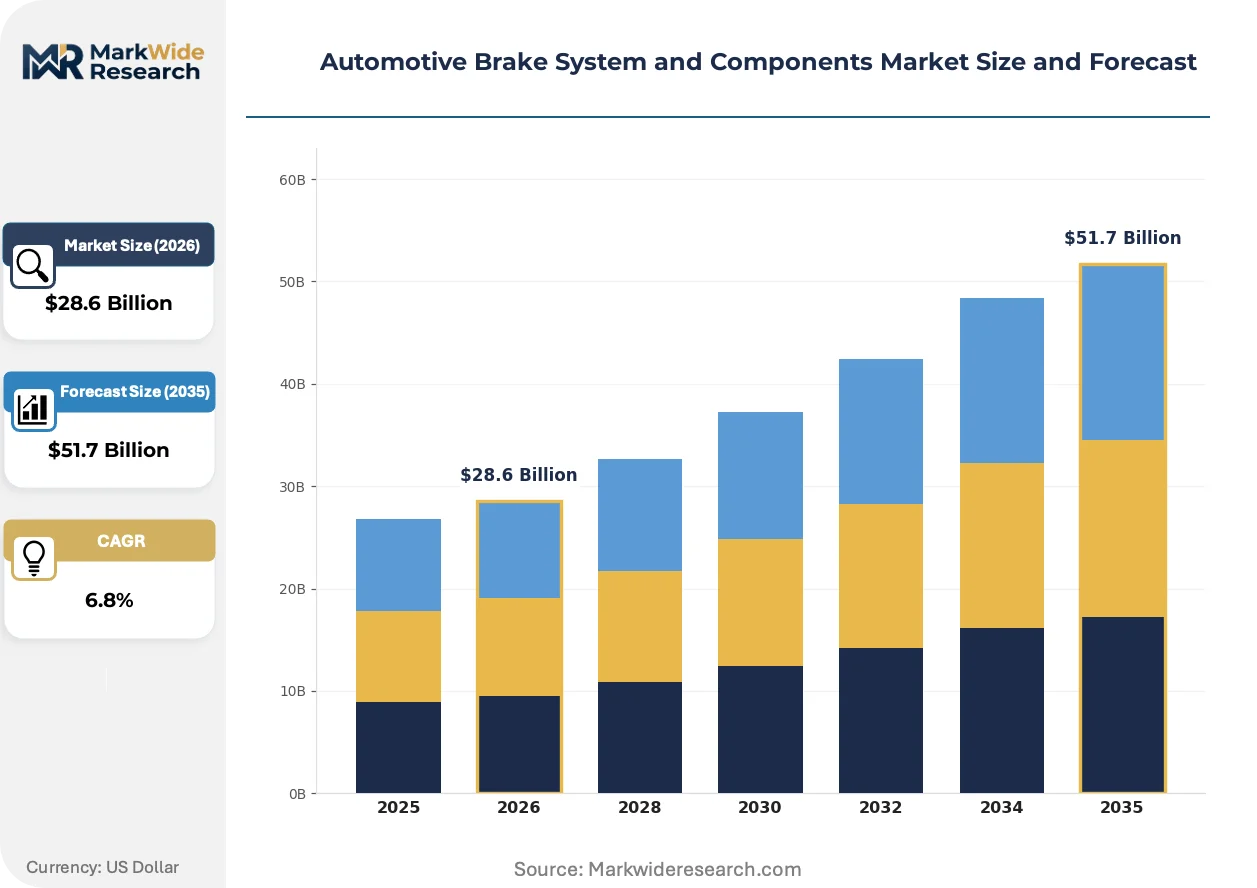
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brake, Drum Brake, Anti-lock Braking System, Electromechanical Brake End User: Original Equipment Manufacturers, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Cast Iron, Stainless Steel, Composite, Carbon-Carbon Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Brembo S.p.A., AISIN Seiki Co., Ltd., Akebono Brake Industry Co., Ltd., Knorr-Bremse AG, Hitachi Astemo, Ltd., Mando Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake System and Components Market Emerging Trajectories
Brake system architecture is converging with powertrain electrification, creating specification windows for integrated electromechanical solutions while compressing margins for hydraulic component specialists.
Electromechanical parking brake actuators are absorbing caliper integration functions previously handled by separate mechanical systems. Premium electric vehicle platforms from German and Chinese OEMs are specifying combined service-and-parking brake units as standard equipment. This consolidation is absorbing standalone parking brake cable suppliers into tiered brake module procurement structures.
ECE R90 homologation amendments under UN Economic Commission for Europe review are tightening friction material coefficient consistency requirements across temperature ranges. Brake pad suppliers must reformulate organic matrix compounds to maintain performance thresholds from cold start through repeated high-speed deceleration cycles. Aftermarket providers serving European vehicle parc face restocking cost pressures as legacy formulations lose type approval.
Logistics fleet operators are unbundling brake maintenance from full-service lease agreements, creating direct procurement relationships with component suppliers. Large commercial vehicle fleets in the United States are negotiating volume contracts for brake pad and rotor replacement cycles based on telematics-derived wear predictions. This disintermediation compresses distributor margins while rewarding suppliers with predictive maintenance data integration capabilities.
Automotive Brake System and Components Market Segmentation
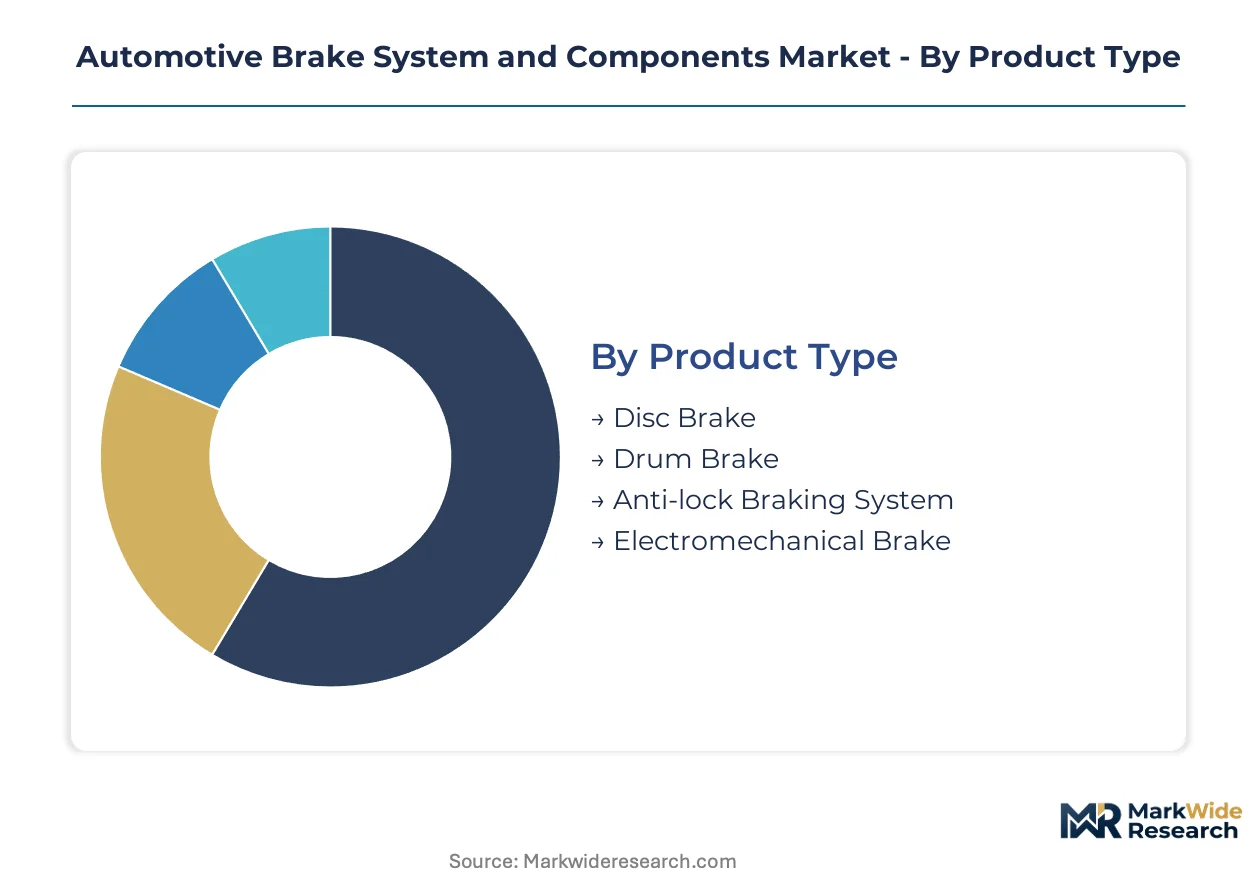
Brake system specification varies sharply by thermal load, duty cycle, and platform electrification level. Procurement patterns diverge between OEMs seeking integrated mechatronics and aftermarket channels optimizing for friction material replacement economics.
Product Type:
Supply concentration for advanced brake architectures tilts toward electromechanical specialists with embedded software capabilities, while hydraulic component manufacturers face margin compression from commoditization.
- Disc Brake:Cast iron or carbon-ceramic rotors paired with caliper-actuated friction pads dominate passenger vehicle specifications above 150 km/h top speeds. German and Chinese OEMs specify floating-caliper designs for mass-market electric vehicles, while fixed-caliper configurations persist in performance segments. Thermal fade resistance above 600°C determines supplier selection for autobahn-rated applications.
- Electromechanical Brake:Motor-driven caliper actuation eliminates hydraulic fluid circuits entirely, integrating parking and service brake functions into single modules. Chinese GB 7258 compliance deadlines are accelerating domestic OEM adoption timelines for brake-by-wire architectures. This segment is climbing the fastest as electric vehicle platforms scale.
- Drum Brake:Leading configuration for rear-axle applications in cost-optimized passenger vehicles and commercial vehicle parking brake systems. Simpler manufacturing tooling sustains supplier margins in emerging market vehicle programs.
- Anti-lock Braking System:Wheel-speed sensor networks with solenoid valve modulation remain mandatory for NHTSA FMVSS 135 compliance across all US-market vehicles.
Current procurement leader: Disc Brake. Electrification challenger: Electromechanical Brake.
End User:
Customer type determines contract structure, with OEMs demanding system-level integration liability and aftermarket channels optimizing for inventory velocity.
- Original Equipment Manufacturers:Volkswagen Group and BYD specify integrated brake modules with embedded control firmware, transferring hardware-software integration risk to tiered suppliers. Contract terms extend across vehicle platform lifecycles exceeding seven years.
- Aftermarket Providers:European distributors face ECE R90 reformulation costs as legacy friction materials lose type approval. High-parc-density regions in Germany and the United States concentrate margin pools for disc pad and rotor replacement.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG capture brake control module procurement through mechatronics integration capabilities.
- Vehicle Assemblers:Contract manufacturers in lower-volume markets source complete brake corner modules to minimize assembly complexity.
Volume concentrates with OEMs. Margin expansion sits with aftermarket specialists.
Material:
Raw material selection trades thermal performance against supply chain concentration, with carbon-carbon sources limited to specialized aerospace-grade suppliers.
- Cast Iron:Gray iron rotors with lamellar graphite microstructure absorb 90% of passenger vehicle brake thermal loads. Chinese foundry capacity dominates global supply for economy-segment vehicles.
- Carbon-Carbon:C/C composites withstand sustained temperatures above 1000°C without thermal degradation. Motorsport and hypercar applications in Stuttgart and Modena drive specification, with production yields below 30% constraining mass-market adoption.
- Stainless Steel:Corrosion-resistant caliper housings and hardware components for coastal and winter-road environments.
- Composite:Aluminum-matrix and polymer-composite caliper bodies reduce unsprung mass in electric vehicle platforms seeking range optimization.
Cast Iron anchors volume. Carbon-Carbon commands premium positioning.
Application:
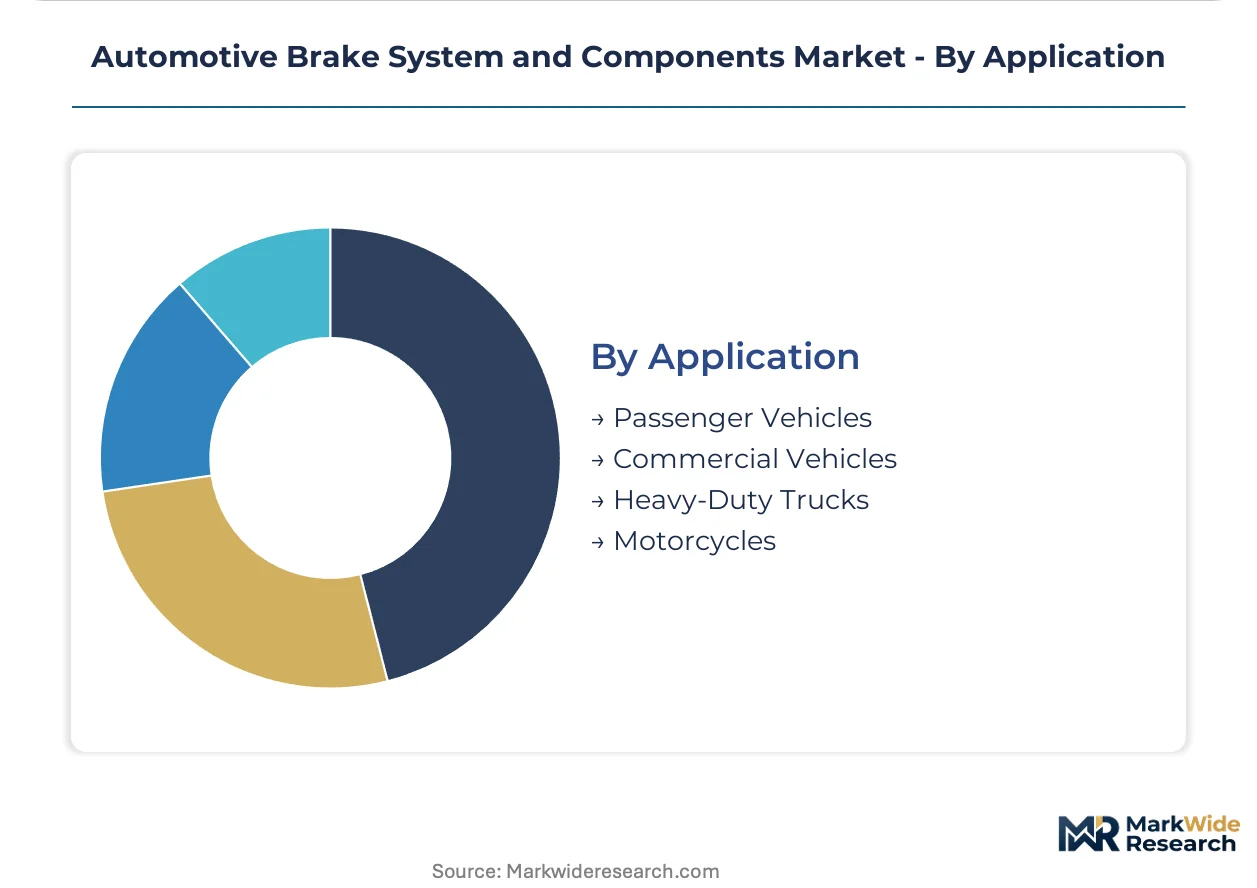
Duty cycle severity determines brake system specification, with commercial vehicle applications demanding air-actuated disc configurations absent from passenger car portfolios.
- Passenger Vehicles:Electromechanical parking brake integration is standard equipment for German and Chinese premium electric platforms. Regenerative braking coordination with friction systems creates specification windows for blended control algorithms.
- Heavy-Duty Trucks:Bharat Stage VI compliance in India is accelerating air disc brake retrofit demand across commercial fleets. Telematics-enabled wear prediction is disintermediating traditional distributor channels for pad and rotor procurement.
- Commercial Vehicles:Light-duty van and truck applications in the United States specify hydraulic disc configurations with integrated ABS modules.
- Motorcycles:Single- and twin-piston caliper configurations dominate two-wheeler braking, with combined braking systems mandatory under Indian CMVR regulations.
Passenger Vehicles drive technology transition. Heavy-Duty Trucks offer aftermarket expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Detroit, and Shanghai anchor brake system innovation clusters. These concentrations attract tier-1 suppliers seeking mechatronics capabilities. Workforce density determines regional competitive positioning in electromechanical brake development.
United States
Domestic OEMs source integrated brake-by-wire modules for electric truck platforms. NHTSA FMVSS 135 compliance mandates shape supplier qualification timelines. Detroit-area engineering centers concentrate firmware development for blended regenerative-friction control systems.
Germany
Premium passenger vehicle manufacturers specify combined service-and-parking brake units as standard equipment. KBA type approval processes govern ECE R90 friction material certification. Stuttgart and Munich clusters dominate mechatronics-integrated brake module procurement relationships.
China
Domestic electric vehicle platforms are eliminating hydraulic circuits entirely. GB 7258 national standard revisions compel friction material upgrades across OEM portfolios. Yangtze River Delta manufacturing bases scale electromechanical brake actuator production for BYD and NIO supply chains.
India
Bharat Stage VI emission compliance accelerates commercial fleet replacement cycles. The country's national automotive regulator enforces upgraded brake performance for heavy-duty applications. Tamil Nadu and Maharashtra industrial corridors expand air disc brake retrofit capacity for logistics operators.
Japan
Hybrid vehicle architectures sustain demand for dual hydraulic-electromechanical competency. METI industrial policy supports brake control software safety certification under ISO 26262 frameworks. Aichi Prefecture supplier networks coordinate motor regeneration blending algorithms with friction system suppliers.
Automotive Brake System and Components Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across brake system tiers. Market structure consolidates around mechatronics-integrated module providers while fragmenting across hydraulic component fabricators. Three archetypes dominate: full-system integrators owning hardware-software stacks, friction material specialists commanding aftermarket margin pools, and electromechanical actuator pure-plays. Competitive moves center on strategic partnerships for brake-by-wire development and backward integration into rare earth magnet supply chains.
Within the full-system integrator tier, Robert Bosch GmbH and Continental AG exemplify conglomerate-scale diversification across automotive electronics and brake hardware. ZF Friedrichshafen AG occupies a position bridging passenger and commercial vehicle applications through modular platform architectures. Brembo S.p.A. represents the performance-specialist archetype, anchoring premium friction material positioning in motorsport-derived supply relationships. These three company structures illustrate how geographic origin and corporate form shape competitive positioning: German GmbH and AG entities dominate integrated system supply, while Italian S.p.A. structures concentrate thermal performance specialization.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Brembo S.p.A. |
| AISIN Seiki Co., Ltd. |
| Akebono Brake Industry Co., Ltd. |
| Knorr-Bremse AG |
| Hitachi Astemo, Ltd. |
| Mando Corporation |
| Others |
Supply Flow & Price Mechanics
Chinese GB 7258 friction material upgrades are compelling domestic OEMs to source certified brake pads from tier-1 suppliers with parallel NHTSA and ECE R90 laboratories, forcing supply base consolidation and compressing margins for uncertified aftermarket providers. This specification tightening cascades through procurement structures, concentrating pricing power with integrated mechatronics suppliers while fragmenting commodity hydraulic component markets.
Pricing Analysis
Bundled brake-by-wire modules with embedded control firmware command premium positioning against unbundled hydraulic component sourcing. Three-tier pricing structure across premium, standard, and economy levels separates certified electromechanical systems from conventional disc brake assemblies and commodity drum brake configurations. Cost compression in economy-tier hydraulic components is intensifying because Chinese foundry overcapacity sustains gray iron rotor oversupply. Fleet procurement managers demonstrate highest price sensitivity, while German premium OEMs prioritize thermal performance over unit cost.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese rare earth processing facilities that feed electromechanical brake motor production in Germany and the Yangtze River Delta. Raw material dependencies span lamellar graphite cast iron from Chinese foundries, carbon-carbon preforms from aerospace-grade suppliers in France and the United States, and copper windings for caliper actuation motors. Single-source vulnerability concentrates in rare earth magnet separation capacity. Distribution runs through tier-1 module integrators to OEM assembly plants, with aftermarket channels bypassing traditional tiers for direct fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where successive NHTSA FMVSS 135 and ECE R90 amendment cycles force recurring certification investments that deepen incumbent moats and raise capital barriers for challengers.
For Market Incumbents: Anticipate brake-by-wire architecture consolidation by securing embedded software safety certification under ISO 26262 before development timeline extensions lock out late entrants. Backward integration into rare earth magnet supply chains mitigates Chinese processing concentration risk. Capacity addition in Tamil Nadu and Maharashtra industrial corridors captures Bharat Stage VI commercial vehicle retrofit demand.
For New Entrants and Emerging Players: Logistics fleet operators with telematics-enabled procurement functions represent the most penetrable buyer archetype for direct brake pad and rotor contracts bypassing distributor markups. White-space targets include predictive maintenance data integration for wear-cycle optimization and air disc brake retrofit capacity for Indian commercial fleets. A software-defined brake control algorithm development angle opens procurement relationships with electric vehicle platform engineers seeking regenerative-friction blending IP.
For Investors and Strategic Acquirers: Asymmetric upside sits with electromechanical actuator pure-plays possessing embedded firmware capabilities and active ECE R90 certification pipelines. Long-term viability over the projection horizon favors suppliers with demonstrated mechatronics integration track records across multiple OEM platform awards. Watch for GB 7258 compliance deadline acceleration as the inflection indicator for Chinese domestic supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Standardization | Robert Bosch GmbH and Continental AG consolidate procurement relationships through unified electromechanical architectures. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processing facilities secure neodymium availability for motor-driven caliper production. |
| Software-Defined Brake Control Investment | Embedded firmware development for regenerative-friction blending algorithms creates differentiated IP for electric vehicle platforms. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu and Maharashtra capacity buildout captures Bharat Stage VI commercial fleet brake upgrade cycles. |
| Aftermarket Direct-to-Fleet Channel Development | Telematics-integrated wear prediction capabilities disintermediate traditional distributors for logistics operator contracts. |
Methodological Framework
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each market informing cross-regional pattern identification. The analysis combines structured interviews with OEM platform engineers, tier-1 supplier procurement directors, aftermarket distributors, and fleet maintenance managers with secondary validation against vehicle production databases, IHS Markit registration data, NHTSA FMVSS 135 filing records, and ECE R90 type approval registries. Bottom-up segment sizing and top-down macro constraint checks ensure triangulation integrity across estimation approaches.
Granularity-level modeling distinguishes propulsion architecture, vehicle class, content per vehicle, OEM tier positioning, and regional production cluster dynamics throughout the forecast period. CAGRs derive from segment-level unit demand projections married to average selling price trajectories reflecting specification mix shifts. Industry-specific forecast inputs include electric vehicle platform rollout schedules, GB 7258 compliance deadline phasing, and Bharat Stage VI fleet replacement velocity assumptions.
Underlying measurement precision varies by segment; electromechanical brake system forecasts carry tighter precision than commodity hydraulic component estimates due to concentrated supplier disclosure and visible OEM platform sourcing. Forecasts reflect documented assumptions regarding regulatory amendment timing, rare earth supply continuity, and OEM vertical integration propensity. A small set of triggers—GB 7258 acceleration, NHTSA brake-by-wire permissiveness shifts, and neodymium price volatility spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Automotive Carbon Fiber Components Market
Automotive Components
Automotive Retarders Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Japan Automotive Sunroof Market
Automotive Components
France Automotive Market
Automotive Components
Automotive Fender Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automotive Active Seat Headrests Market
Automotive Components
Automotive Headliners Market