
 Clutch Friction Plate Market | 2026-2036
Clutch Friction Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Clutch Friction Plate Market Outlook
Fleet operators and aftermarket providers is unwinding the historical dominance of OEM procurement in clutch friction plate demand. Schaeffler leverages its integrated transmission systems portfolio to anchor supply relationships with European commercial vehicle builders. EXEDY competes through specialized racing and high-performance friction formulations that sustain premium positioning in motorsport channels.
A clutch friction plate is a rotating disc lined with friction material—typically organic resin-bonded compounds, sintered metallic powders, or ceramic composites pressed onto a steel core—that engages and disengages power transmission between engine and drivetrain by clamping against a flywheel and pressure plate under calibrated spring or hydraulic load. The component must withstand operating temperatures exceeding 300°C while maintaining consistent coefficient of friction across millions of engagement cycles. Multi-plate configurations command the highest torque density applications in heavy commercial vehicles and performance drivetrains, where the segment captures concentrated margin pools despite lower unit volumes than single-plate alternatives. Ceramic material formulations are displacing organic linings in high-stress environments, driven by thermal durability requirements that composite blends increasingly satisfy at intermediate cost positions.
EPA emissions enforcement and NHTSA fuel economy standards in the United States, alongside REACH chemical restrictions and EU Green Deal decarbonization pathways in Europe, are elevating compliance costs for friction material composition and manufacturing processes. China's MIIT dual carbon goals and GB standards for vehicle component durability are reshaping supplier qualification requirements for access to the world's largest automotive production base. Stakeholders must monitor regulatory divergence between jurisdictions, as material certification regimes that diverge across EPA, ECHA, and MIIT frameworks will force parallel product development tracks and regional manufacturing footprints rather than unified global platforms.
Market Dynamics
Fleet operators extending vehicle lifecycles are dismantling the traditional OEM-centric procurement model for clutch friction plates. Aftermarket channels now capture incremental share as commercial vehicle owners prioritize component-level replacement over full transmission system overhauls.
Growth Catalysts
- Extended Fleet Utilization:Commercial operators in North America and Europe are running heavy-duty trucks beyond 800,000 kilometers, multiplying clutch plate replacement cycles and redirecting demand toward independent distributors.
- MIIT Dual Carbon Goals:China's Ministry of Industry and Information Technology durability standards for vehicle components are forcing domestic OEMs to upgrade friction material specifications, opening qualification opportunities for certified suppliers.
- Ceramic Composite Maturation:Sintered metallic and ceramic hybrid formulations are penetrating high-torque applications previously reserved for organic linings, expanding addressable market scope in performance and commercial segments.
Market Restraints
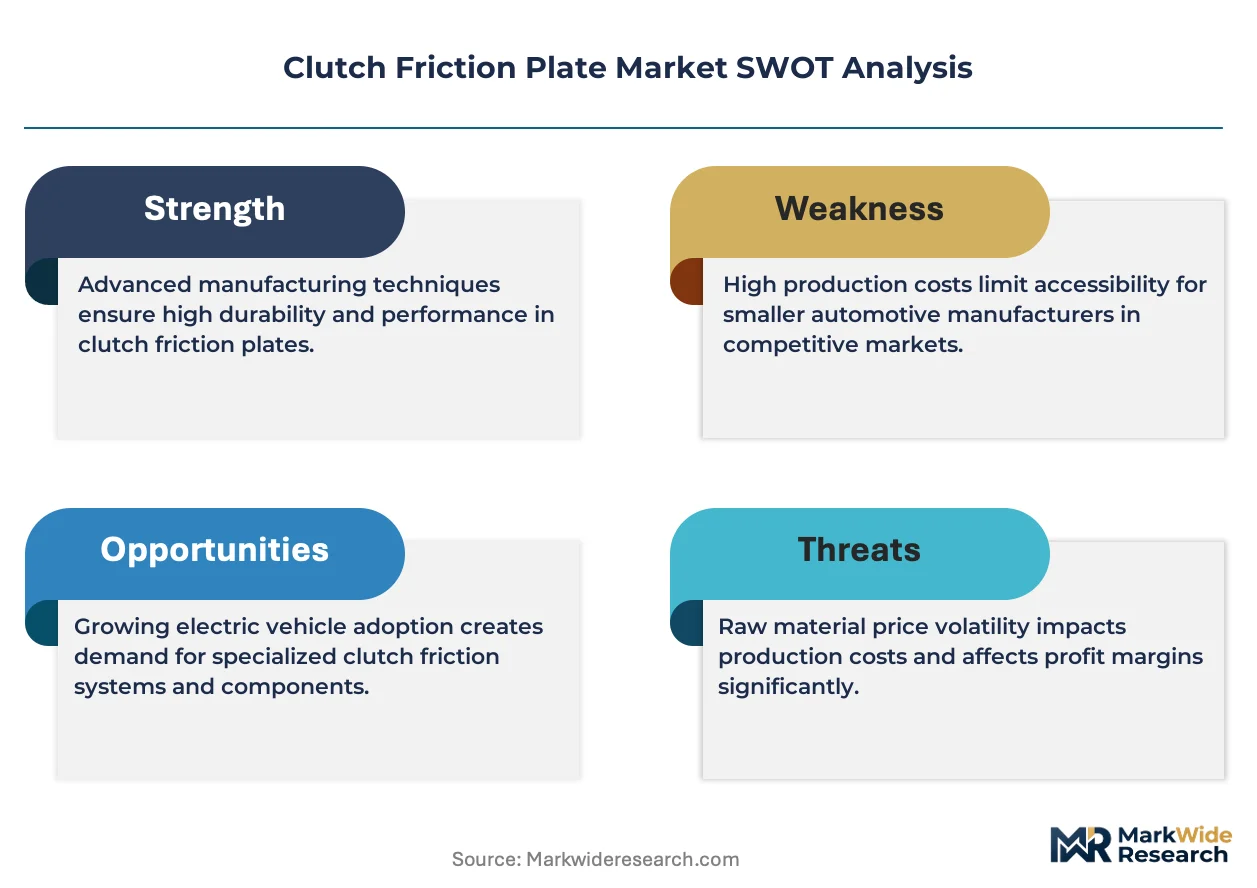
- Raw Material Concentration:Specialty ceramic fiber and copper powder supplies concentrate among limited Chinese and Russian producers, exposing friction material compounders to input volatility and qualification disruption.
- REACH Chemical Complexity:ECHA restrictions on phenolic resin precursors and heavy metal binders are forcing European manufacturers into parallel formulation tracks, elevating R&D overhead without guaranteed pass-through pricing.
- Electrification Substitution:Battery-electric commercial vehicle platforms eliminate multi-plate clutch systems entirely, compressing long-term demand visibility in heavy-duty segments where torque transfer once guaranteed volume.
Strategic Opportunities
- Hybrid Powertrain Positioning:Dual-clutch and automated manual transmissions in 48V mild-hybrid architectures require specialized friction plates with rapid heat dissipation, creating premium tier openings for material innovators.
- India Commercial Vehicle Aftermarket:BS-VI emission compliance deadlines have compressed replacement cycles for heavy trucks, concentrating demand in Mumbai-Pune and Chennai manufacturing corridors where distributor networks remain underdeveloped.
- Remanufacturing Channel Expansion:EPA-endorsed remanufacturing protocols for automotive components are enabling certified rebuilders to capture warranty-adjacent revenue streams previously monopolized by OEM captive channels.
Industry Challenges
- Friction Material Formulation Expertise Gap:Compound chemistry and thermal modeling capabilities concentrate among aging technical workforces in Germany and Japan, constraining supplier scaling in emerging production regions.
- Multi-Jurisdiction Certification Overlap:Parallel SAE, JIS, and GB testing protocols for clutch plate durability create 18-24 month qualification timelines that freeze supplier switching decisions and lock in incumbent relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clutch Friction Plate Market |
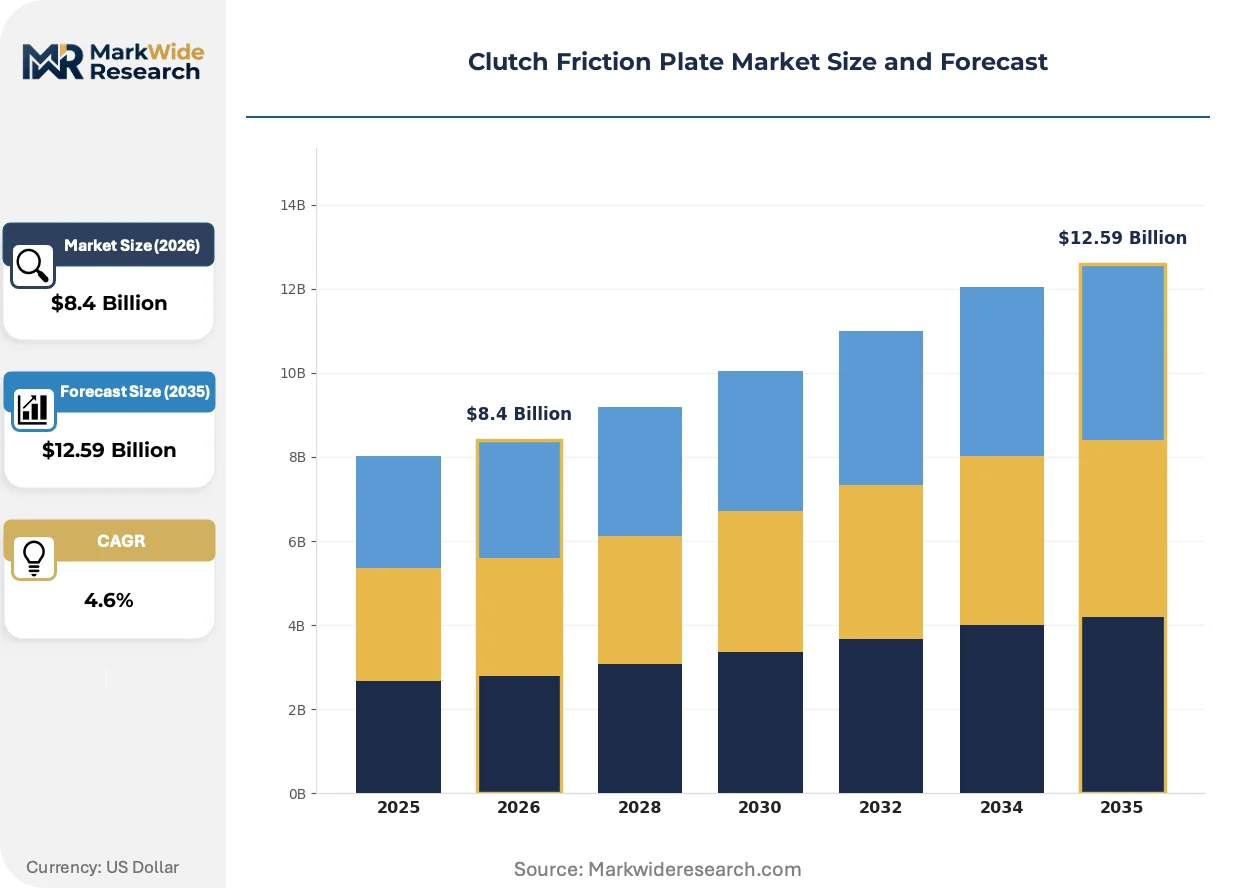
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Plate, Dual Plate, Multi Plate, Friction Disc Technology: Hydraulic, Mechanical, Pneumatic, Electromagnetic End User: OEMs, Aftermarket Providers, Automotive Manufacturers, Industrial Machinery Material: Organic, Ceramic, Metallic, Composite |
| Companies Covered | ZF Friedrichshafen AG, EXEDY, BorgWarner Inc., Nisshinbo Holdings Inc., F.C.C. Co., Ltd., Schaeffler, Aisin, Eaton, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clutch Friction Plate Market Strategic Shifts
Material science breakthroughs and regulatory chemistry restrictions are converging to rewrite friction plate specifications. Suppliers must now engineer thermal performance without legacy resin systems while serving divergent electrification timelines across commercial and passenger vehicle segments.
Ceramic-copper composite friction materials are supplanting traditional organic linings in high-stress commercial applications. Heavy-duty fleet operators in Germany and the United States are specifying these formulations for their 40% superior heat tolerance during mountain-grade descents. The shift is compressing margin pools for conventional compounders while elevating specialized sintering houses into tier-one supply positions.
REACH Annex XVII restrictions on hexavalent chromium and specific phenolic derivatives are forcing European friction material producers into accelerated reformulation cycles. Manufacturers serving the KBA-regulated German commercial vehicle market face 2026 deadlines for alternative binder systems. The regulatory pressure is most acute among mid-volume suppliers lacking captive chemical synthesis capabilities, driving consolidation toward integrated material science groups.
Aftermarket distributors are unbundling clutch plate sales from bundled transmission service packages. Independent parts specialists in China's Yangtze River Delta region now stock ceramic-composite SKUs for direct fleet procurement, bypassing traditional OEM dealer networks. The behavioral shift concentrates price transparency pressure on incumbent suppliers while rewarding logistics-efficient distributors with regional density.
Clutch Friction Plate Market Segmentation
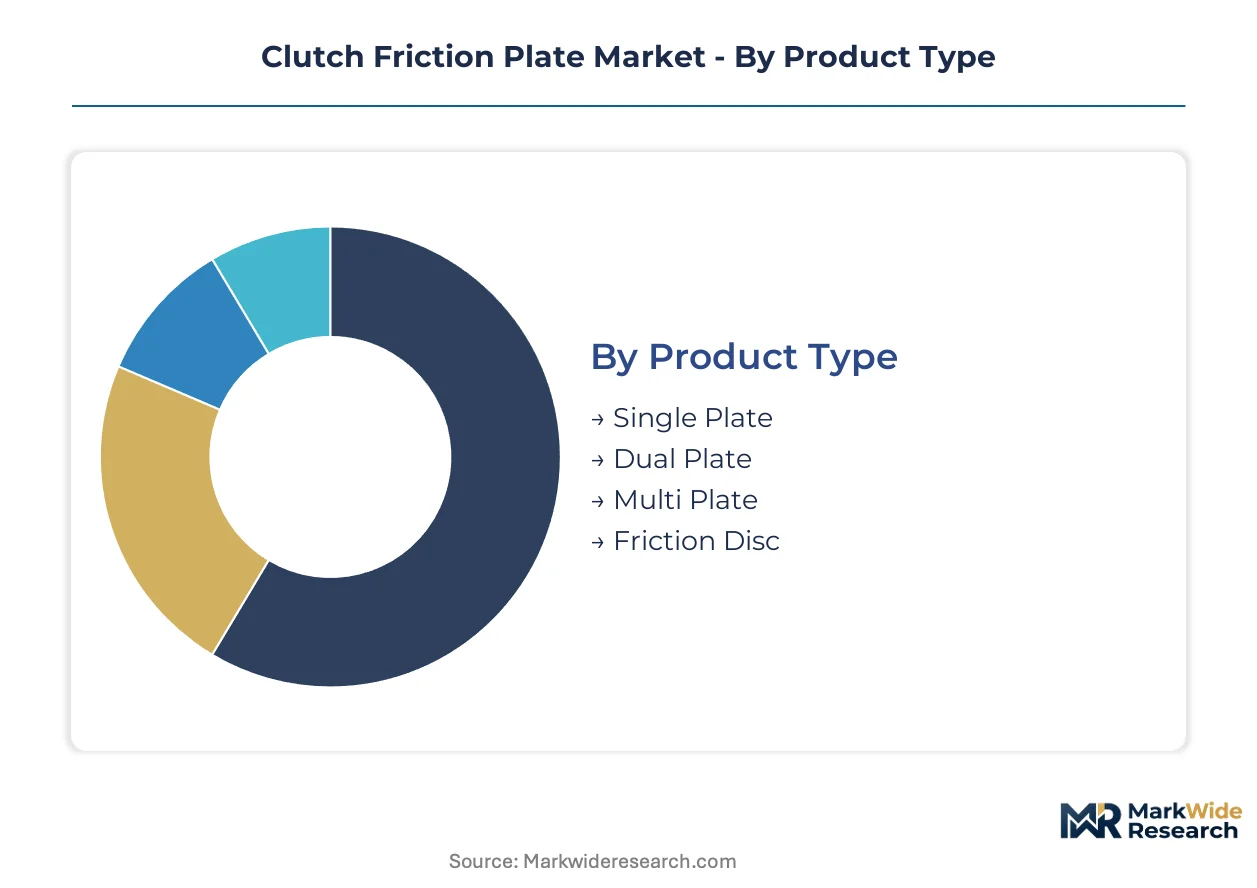
Clutch friction plate segmentation reveals how torque density requirements, thermal durability standards, and procurement channel shifts fragment supplier positioning across commercial and passenger vehicle applications. Material chemistry and plate configuration choices directly determine qualification pathways into OEM, fleet, and industrial machinery channels.
Product Type:
Margin pools concentrate in multi-plate configurations where thermal management complexity and lower unit volumes sustain premium pricing power against commoditized single-plate alternatives.
- Multi Plate:Stacked disc arrangements deliver superior torque density for heavy commercial vehicles and performance drivetrains. German heavy-duty truck builders specify these configurations for sustained mountain-grade operations where heat dissipation failures trigger warranty exposure.
- Dual Plate:Twin-disc systems balance engagement smoothness with thermal capacity in high-torque passenger applications. Demand from China's domestic OEMs is climbing fastest as 48V mild-hybrid architectures proliferate through Yangtze River Delta manufacturing clusters.
- Single Plate:Dominates volume production for light-duty passenger vehicles across cost-sensitive segments.
- Friction Disc:Replacement-focused component format capturing aftermarket share as fleet operators unbundle from full clutch assembly procurement.
Multi-plate configurations hold installed capacity in heavy commercial segments. Dual-plate systems are rotating up the share rankings through hybrid powertrain penetration.
Technology:
Actuation method selection tracks vehicle electrification timelines and hydraulic system elimination roadmaps across passenger and commercial platforms.
- Hydraulic:Dominates current heavy-duty commercial vehicle installations where pedal effort reduction and consistent clamping force justify system complexity. EPA fuel economy standards are accelerating hydraulic-to-electromechanical transitions in US Class 8 trucks.
- Electromagnetic:Coil-based engagement eliminates mechanical wear components and enables software-controlled torque modulation. Japanese transmission suppliers are qualifying electromagnetic actuation for next-generation automated manual transmissions targeting 2030 platform launches.
- Mechanical:Cable and linkage systems persist in cost-optimized emerging market vehicles.
- Pneumatic:Compressed air actuation retains niche presence in industrial machinery and off-highway equipment.
Hydraulic systems anchor current revenue. Electromagnetic architectures are climbing the fastest as electrification timelines compress.
End User:
Procurement channel fragmentation is redistributing margin capture from OEM captive networks toward independent distributors and certified remanufacturers.
- Aftermarket Providers:Independent distributors and fleet-direct procurement channels are capturing incremental share as vehicle lifecycle extension multiplies replacement cycles. Mumbai-Pune corridor heavy truck operators now source ceramic-composite plates directly from regional distributors, bypassing OEM dealer markups.
- OEMs:Original equipment procurement retains specification authority and volume concentration, though pricing pressure intensifies from platform standardization mandates. China's MIIT durability standards are forcing domestic OEMs into material upgrades that favor qualified tier-one suppliers.
- Automotive Manufacturers:Captive transmission divisions and integrated powertrain builders.
- Industrial Machinery:Construction, agricultural, and material handling equipment OEMs with distinct duty cycle requirements.
OEM channels hold installed capacity. Aftermarket providers are rotating up the share rankings through fleet procurement behavioral shifts.
Material:
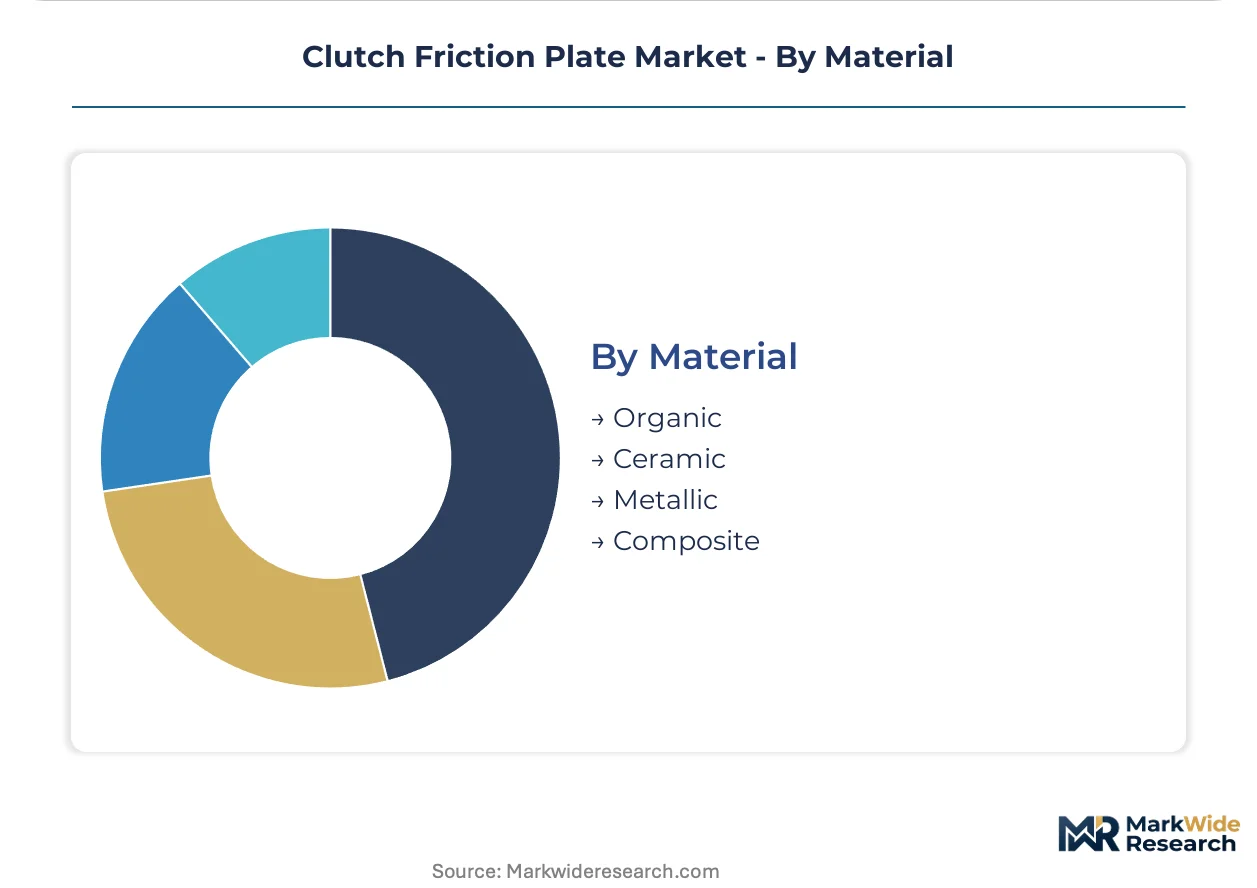
Formulation chemistry determines thermal ceiling, particulate emissions compliance, and qualification access into regulated commercial vehicle markets.
- Ceramic:Sintered metallic and oxide-based composites deliver 40% superior heat tolerance versus organic alternatives. KBA-regulated German commercial vehicle specifications are mandating ceramic formulations for heavy-duty applications by mid-decade deadlines.
- Composite:Hybrid ceramic-organic blends occupy intermediate cost-performance positions for high-stress passenger and light commercial segments. Japanese transmission suppliers are qualifying copper-ceramic hybrids for 48V mild-hybrid clutch applications requiring rapid thermal cycling durability.
- Organic:Resin-bonded compounds face REACH Annex XVII pressure on phenolic precursors.
- Metallic:Sintered bronze and copper formulations retain industrial machinery presence.
Ceramic formulations hold installed capacity in premium commercial segments. Composite blends are rotating up the share rankings through hybrid powertrain qualification wins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German friction plate manufacturers export ceramic-composite formulations to heavy-duty fleet operators across North America and China, while Japanese suppliers ship specialized racing materials to European motorsport channels. This trade-flow pattern concentrates high-value production in established automotive belts while aftermarket distributors in emerging markets capture replacement-cycle volume.
United States
EPA emissions enforcement and NHTSA fuel economy standards are forcing domestic heavy-duty truck builders into material upgrades for mountain-grade thermal durability. Fleet operators running vehicles beyond 800,000 kilometers now source ceramic-composite plates directly from independent distributors in the Midwest manufacturing corridor. Detroit-area transmission rebuilders are expanding remanufacturing capacity to capture warranty-adjacent revenue from extended lifecycle programs.
Germany
KBA-regulated commercial vehicle specifications mandate ceramic formulations for heavy-duty applications by mid-decade deadlines. REACH Annex XVII restrictions on phenolic resin precursors are forcing friction material compounders into accelerated reformulation cycles. Stuttgart and Munich industrial clusters concentrate sintering expertise for copper-ceramic hybrids serving premium commercial vehicle builders.
China
MIIT dual carbon goals and GB standards for component durability are reshaping supplier qualification requirements for access to the world's largest automotive production base. Domestic OEMs in the Yangtze River Delta are expanding clutch plate sourcing for both conventional and hybrid powertrains. Shanghai-area distributors now stock ceramic-composite SKUs for direct fleet procurement, bypassing traditional dealer networks.
Japan
METI-backed R&D programs support next-generation friction formulations for 48V mild-hybrid architectures requiring rapid thermal cycling durability. JIS testing protocols for clutch plate qualification create 18-24 month certification timelines that favor incumbent supplier relationships. Nagoya-area transmission specialists are qualifying copper-ceramic hybrids for automated manual transmission platforms targeting 2030 launches.
India
BS-VI emission compliance deadlines have compressed replacement cycles for heavy trucks, concentrating demand in Mumbai-Pune and Chennai manufacturing corridors. Fleet operators in these clusters now source ceramic-composite plates directly from regional distributors, bypassing OEM dealer markups. BIS durability standards for commercial vehicle components are forcing material upgrades that open qualification opportunities for certified tier-one suppliers.
Clutch Friction Plate Market Competitive Environment
Player mix skews toward integrated automotive suppliers with captive transmission divisions and specialized friction material compounders serving aftermarket channels. The market structure concentrates specification authority among German and Japanese tier-one suppliers while fragmenting volume production across regional fabricators. Two dominant archetypes emerge: integrated powertrain builders leveraging transmission system portfolios to anchor OEM relationships, and specialized compounders competing through material science differentiation in high-stress applications. Competitive moves center on ceramic formulation licensing partnerships and backward integration into specialty ceramic fiber supply.
Among German-based integrated suppliers, ZF Friedrichshafen AG and Schaeffler occupy positions exemplifying the powertrain-anchored archetype, while Japanese specialists EXEDY and F.C.C. Co., Ltd. represent the material-science-focused tier competing through thermal durability expertise in motorsport and commercial channels.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| EXEDY |
| BorgWarner Inc. |
| Nisshinbo Holdings Inc. |
| F.C.C. Co., Ltd. |
| Schaeffler |
| Aisin |
| Eaton |
| Valeo SA |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII restrictions on phenolic resin precursors and hexavalent chromium binders gate both supplier qualification into European commercial vehicle markets and the price premiums commanded by certified ceramic-composite formulations. KBA-mandated material upgrades for German heavy-duty applications compress margin pools for conventional compounders while elevating sintering specialists into tier-one pricing tiers.
Pricing Analysis
Technology-generation pricing gaps separate legacy organic linings from ceramic-copper hybrids and next-generation electromagnetic actuation platforms. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and thermal durability specifications, with KBA-compliant ceramic formulations capturing 40% premiums over conventional alternatives. Cost compression in organic resin segments intensifies as REACH deadlines force reformulation investments without guaranteed pass-through pricing. Fleet operators in aftermarket channels exhibit highest price sensitivity, while OEM platform engineers prioritize qualification security over unit cost.
Supply Chain Analysis
China and Russia anchor specialty ceramic fiber and copper powder production for friction material compounders. German and Japanese sintering houses draw from these concentrated raw material streams, exposing formulation specialists to input volatility and qualification disruption from geopolitical friction. Single-source vulnerability concentrates in Chinese ceramic fiber suppliers serving European and North American compounders. Distribution runs through OEM captive channels for original equipment, while independent distributors in China's Yangtze River Delta and India's Mumbai-Pune corridor capture fleet-direct procurement volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement channel fragmentation across fleet-direct, remanufacturing, and traditional OEM networks creates white-space opportunities for specialists unbundling component sales from bundled transmission services.
For Market Incumbents: Consolidate backward integration into specialty ceramic fiber supply to defend formulation margins against raw material volatility. Lock in KBA and MIIT certification timelines ahead of mid-decade deadlines to freeze supplier switching decisions by platform engineers. Capture remanufacturing channel expansion through EPA-endorsed rebuild protocols that warranty-adjacent revenue streams previously monopolized by OEM captive networks. For New Entrants and Emerging Players: Aftermarket logistics gaps in India's Mumbai-Pune and Chennai corridors offer immediate penetration points where distributor networks remain underdeveloped. Target ceramic-composite SKU stocking for direct fleet procurement, bypassing traditional OEM dealer markups. Pursue qualification partnerships with Yangtze River Delta transmission specialists seeking alternative friction material sources for 48V mild-hybrid architectures. For Investors and Strategic Acquirers: REACH Annex XVII implementation deadlines reshape the acquisition landscape toward compounders with captive chemical synthesis capabilities and established ECHA compliance track records. Five-to-ten year viability favors integrated material science groups over mid-volume suppliers lacking vertical integration. Monitor MIIT dual carbon goal enforcement intensity as the signal indicating qualification timeline compression for access to China's production base.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Formulation Licensing Partnership | Enables mid-tier compounders to access KBA-compliant thermal durability specifications without captive R&D investment. |
| Backward Integration into Ceramic Fiber Supply | Reduces exposure to Chinese and Russian raw material concentration while securing qualification continuity. |
| Remanufacturing Channel Certification | Captures warranty-adjacent revenue streams from EPA-endorsed rebuild protocols in Midwest manufacturing corridors. |
| Hybrid Powertrain Qualification Program | Positions copper-ceramic hybrids for 48V mild-hybrid clutch applications through JIS and GB testing protocols. |
| Regional Distribution Density Expansion | Concentrates logistics efficiency in India's underdeveloped Mumbai-Pune and Chennai aftermarket corridors. |
Study Parameters
A standing panel of OEM platform engineers, aftermarket distributor procurement heads, Tier 1 supplier technical directors, and fleet maintenance managers provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA enforcement disclosures, ECHA REACH restriction updates, MIIT GB standard publications, and vehicle production databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic anchors.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Analytical framework modeled segmentation by plate configuration, material formulation, actuation technology, end-user channel, and regional regulatory cluster. CAGRs derived from installed base turnover rates, replacement cycle compression, and technology substitution curves. Industry-specific inputs included thermal durability testing data and qualification timeline distributions across SAE, JIS, and GB protocols.
Forecasts assume regulatory continuity in EPA emissions enforcement, REACH Annex XVII implementation, and MIIT dual carbon goal trajectories; material policy shifts would require re-modeling. Specific risks include accelerated electrification substitution in heavy commercial segments and raw material supply disruption from geopolitical friction. Recalibration cycles align with material shifts in fleet lifecycle extension patterns and ceramic composite formulation maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Pumps Market
Powertrain
Natural Gas Engines Market
Powertrain
Global Automotive Drive Shaft Market
Powertrain
Automotive Transmission System Market
Powertrain
Automotive Power Modules Market
Powertrain
Small Gas Engine Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Automotive Conversion Kit Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Engines Market
Powertrain
Global Automotive Clutch Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
Tuning Box Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Europe Automatic Transmission for Passenger Car Market