
 Automotive Brake Pads Market | 2026-2036
Automotive Brake Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Pads Market Analysis
Chinese brake pad manufacturing capacity is decoupling from traditional Western supply chains as domestic producers scale ceramic and semi-metallic output. Brembo sustains technology leadership through advanced carbon-ceramic systems for performance applications. Tenneco anchors the North American aftermarket through extensive distribution networks and private-label coverage. Nisshinbo Holdings differentiates via copper-free formulations that preempt tightening environmental standards.
Automotive brake pads are friction components comprising bonded fiber matrices, metallic fillers, and ceramic modifiers that convert kinetic energy into thermal dissipation through caliper-actuated contact with rotors or drums. Manufacturing employs sequential hot pressing, thermal curing, and surface grinding to achieve specified coefficients of friction and wear rates. Ceramic brake pads command premium positioning due to low dust generation and extended service intervals in passenger car applications. Semi-metallic formulations dominate commercial vehicle and heavy-duty truck installations where thermal load tolerance outweighs noise considerations. The aftermarket channel generates recurring revenue streams as replacement cycles compress under severe-duty operating conditions.
The US EPA and California Air Resources Board enforce copper reduction mandates that reshape friction material composition requirements. Europe's REACH regulation and ECHA substance restrictions drive reformulation investments across metallic and semi-metallic product lines. China's GB standards and SAMR certification protocols govern domestic brake pad quality thresholds and market access procedures. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging material compliance timelines.
Market Dynamics
Copper elimination mandates from California's EPA and Europe's ECHA are forcing simultaneous reformulation across semi-metallic and ceramic product lines, compressing development timelines while opening premium positioning for compliant suppliers.
Growth Catalysts
- Commercial fleet replacement acceleration:Logistics operators in Germany and the United States are compressing brake pad change intervals to maximize vehicle uptime and avoid liability exposure from degraded stopping performance.
- REACH copper restrictions:Europe's phased copper content limits are pulling forward R&D investment in ceramic matrix alternatives and accelerating supplier qualification cycles with domestic OEMs.
- China's industrial corridor concentration:Manufacturing clusters in Jiangsu and Guangdong provinces are generating concentrated demand from domestic commercial vehicle production and state-mandated local sourcing requirements.
Market Restraints
- Raw material cost volatility:Fluctuations in copper, steel fiber, and rare earth ceramic additives are compressing margin stability for semi-metallic formulation producers.
- Supply concentration in bonded fiber substrates:Three specialized Japanese and German suppliers control critical aramid fiber supply for high-performance ceramic pads.
- Technical limitation in cold-temperature friction consistency:Early-generation copper-free ceramics exhibit reduced initial bite in sub-zero conditions, limiting adoption in Nordic passenger applications.
Strategic Opportunities
- India's commercial vehicle aftermarket:Underpenetrated organized service networks in Maharashtra and Tamil Nadu present white-space for branded ceramic pad distribution.
- Regulatory tailwind from US EPA copper mandates:California's SB 346 implementation timeline creates guaranteed demand displacement for compliant formulations through 2025-2028.
- Technology convergence of sensor-integrated pads:Embedding wear-indicator telemetry into ceramic substrates enables predictive maintenance contracts with fleet management platforms.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in friction material tribology and thermal modeling is concentrated among retiring specialists in Germany and Japan.
- Dual certification timeline compression:Simultaneous GB standard compliance for China and ECE R90 certification for Europe is straining testing laboratory capacity.
- Legacy drum brake integration complexity:Copper-free formulations for heavy-duty drum applications require redesigned anchor pin geometries and expanded shoe platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Pads Market |
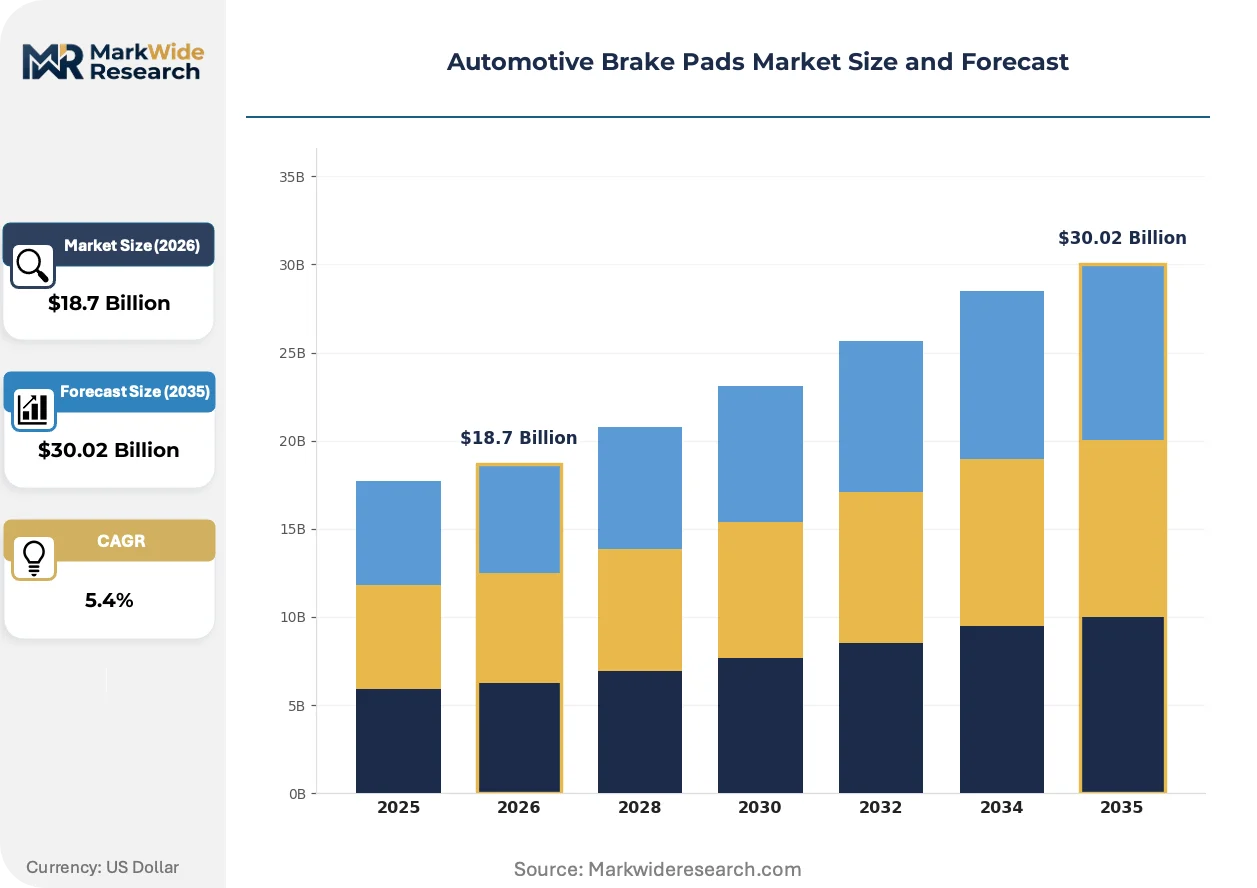
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Metallic, Semi-Metallic, Ceramic Application: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Distribution Channel: Online Retail, Authorized Dealers, Independent Stores, Wholesale Distributors |
| Companies Covered | TMD Friction, Nisshinbo Holdings, Brembo, Tenneco, EBC Brakes, Akebono Brake Industry, ZF TRW, ADVICS, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Pads Market Emerging Trajectories
Friction material science is bifurcating between low-emission ceramic systems for passenger compliance and reinforced semi-metallic architectures for thermal endurance in commercial duty cycles.
Non-asbestos organic (NAO) ceramic composites with potassium titanate whisker reinforcement are electrifying the aftermarket upgrade segment. Premium passenger vehicle owners in California and Germany are adopting these formulations to eliminate wheel dust staining and extend service intervals. The technology is electrifying competitive positioning by enabling direct-to-consumer premium pricing that decouples from commodity semi-metallic benchmarks.
Europe's REACH Annex XVII copper restriction timeline is eliminating legacy semi-metallic compositions from EU type-approval eligibility. Brake pad manufacturers are reallocating formulation capacity toward titanate and glass-ceramic fiber alternatives ahead of 2025 enforcement milestones. Aftermarket distributors in France and Italy are accelerating inventory rotation to avoid stranded stock of non-compliant metallic formulations.
Fleet procurement departments are consolidating brake pad sourcing through integrated vehicle maintenance contracts that bundle friction material supply with installation labor and disposal compliance. Independent repair shops in Texas and Ohio are losing share to authorized commercial vehicle service centers that capture recurring replacement revenue through multi-year uptime guarantees. This concentration is most visible in long-haul trucking corridors where operator bankruptcy risk makes vendor financial stability a selection criterion.
Automotive Brake Pads Market Segmentation
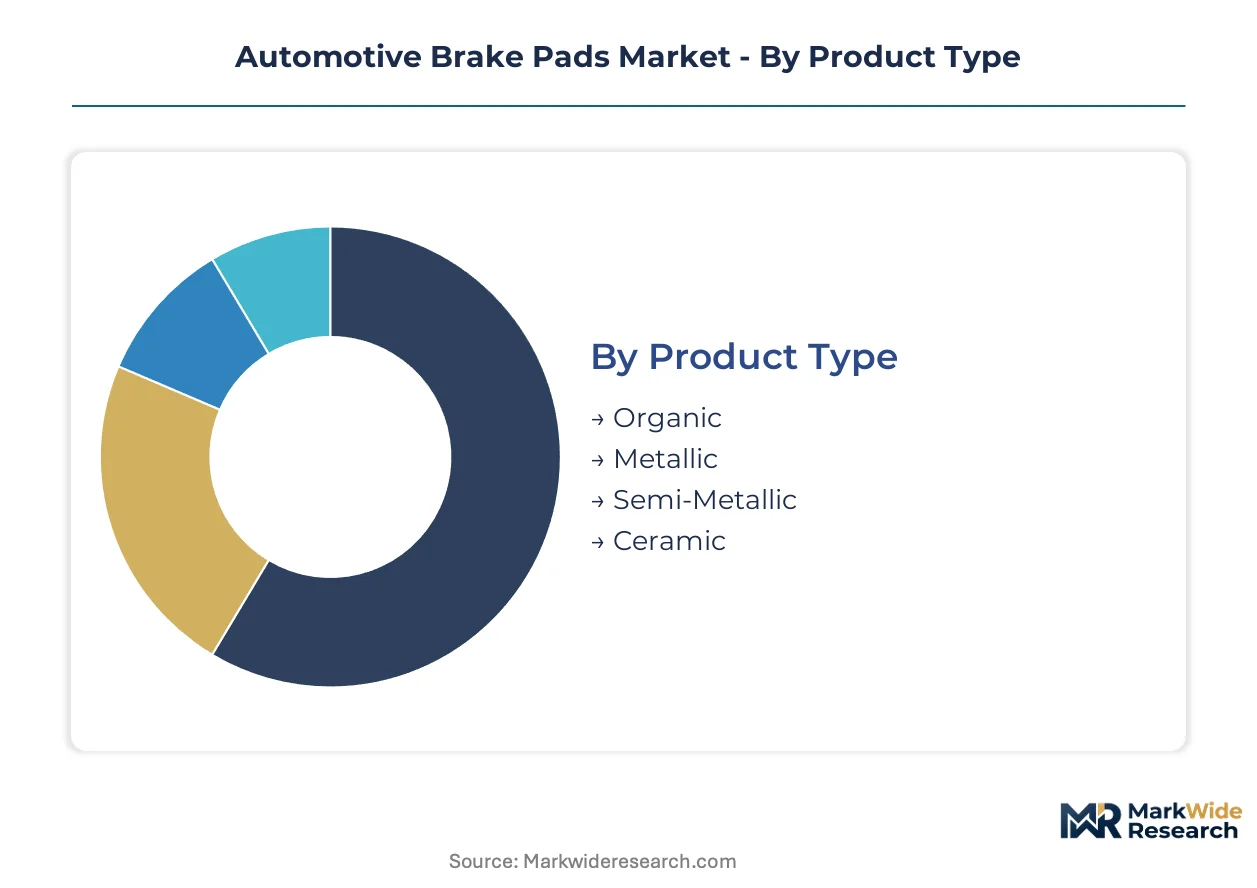
Brake pad segmentation reveals how formulation chemistry, vehicle duty cycles, and procurement channel economics create distinct competitive arenas. Each dimension carries unique margin structures and regulatory exposure that reshape supplier positioning.
Product Type:
Supply concentration in bonded fiber substrates and ceramic modifiers determines which formulations command premium positioning versus commodity exposure.
- Ceramic:Non-asbestos organic matrices reinforced with potassium titanate whiskers deliver low dust generation and extended service intervals. Demand concentrates in California and Germany where REACH and EPA copper mandates eliminate competing metallic alternatives. The technology captures direct-to-consumer premium pricing that decouples from semi-metallic benchmarks.
- Semi-Metallic:Steel fiber and copper-bronze composites tolerate extreme thermal loads in heavy-duty cycles. Fleet operators in Germany and the United States specify these formulations for commercial vehicles despite noise trade-offs, prioritizing stopping reliability over passenger comfort.
- Metallic:Sintered copper and steel formulations persist in performance and racing applications where thermal saturation thresholds exceed ceramic limits.
- Organic:Low-metallic NAO compounds serve cost-sensitive passenger applications with moderate thermal demands.
Today's leader: Semi-Metallic. Tomorrow's challenger: Ceramic.
Application:
Vehicle duty cycles create divergent friction material specifications that segment suppliers by thermal engineering capability rather than scale alone.
- Passenger Cars:Ceramic and low-metallic NAO formulations dominate as owners prioritize dust reduction and wheel aesthetics. California's SB 346 copper mandate accelerates displacement of legacy semi-metallic fitments in this segment.
- Heavy-Duty Trucks:Reinforced semi-metallic architectures withstand sustained braking energy on mountain descents and urban delivery routes. Fleets in Texas and Ohio consolidate procurement through authorized service centers that bundle material supply with uptime guarantees.
- Commercial Vehicles:Intermediate thermal loads favor hybrid formulations balancing durability with regulatory compliance across European and North American corridors.
- Motorcycles:Sintered metallic pads address high heat-to-mass ratios in performance riding segments.
Heavy-Duty Trucks anchor current volume. Passenger Cars expand most quickly as copper-free mandates propagate.
End User:
Procurement authority patterns separate specification-driven OEM relationships from price-sensitive aftermarket replenishment cycles.
- Aftermarket Providers:Independent repair shops and distributors in France and Italy rotate inventory aggressively to avoid stranded stock of non-compliant metallic formulations ahead of REACH enforcement milestones.
- OEMs:Vehicle manufacturers in Jiangsu and Guangdong provinces enforce state-mandated local sourcing requirements that favor domestic brake pad suppliers over traditional Western supply chains.
- Tier-1 Suppliers:Braking system integrators qualify multiple friction material sources to mitigate supply concentration in Japanese and German aramid fiber substrates.
- Vehicle Assemblers:Commercial vehicle manufacturers specify pad formulations within integrated maintenance contracts that bundle replacement intervals with warranty coverage.
Aftermarket Providers dominate transaction volume. OEMs capture specification authority that shapes long-term formulation trajectories.
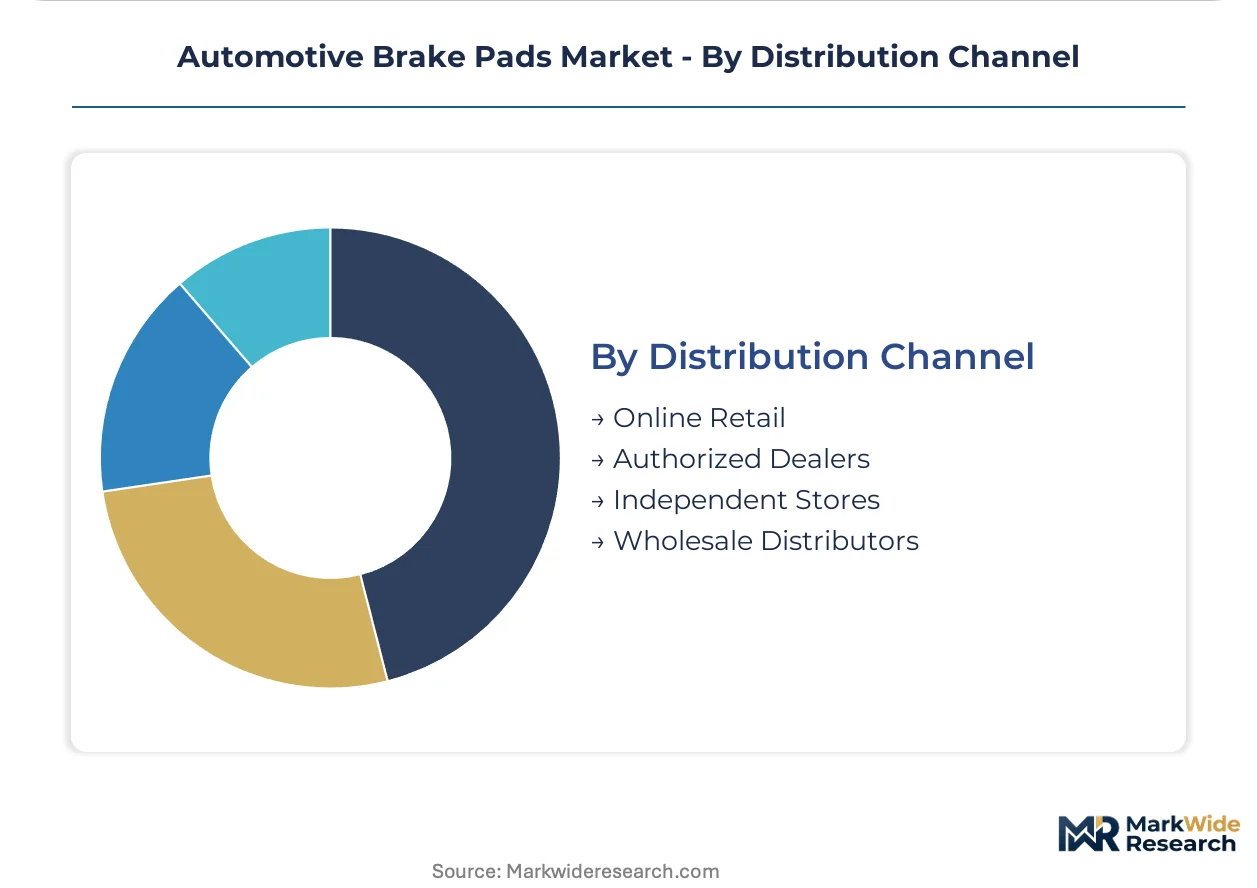
Distribution Channel:
Channel economics separate immediate-availability service models from inventory-light digital procurement platforms with divergent margin structures.
- Authorized Dealers:OEM-aligned service networks in Texas and Ohio capture fleet replacement revenue through multi-year uptime guarantees that independent shops cannot match. Financial stability of the vendor becomes a selection criterion in long-haul trucking corridors.
- Online Retail:Direct-to-consumer platforms enable premium ceramic pad positioning that bypasses traditional wholesale markups. California and German vehicle owners adopt these channels for dust-free upgrade formulations.
- Wholesale Distributors:Regional inventory hubs buffer against raw material volatility in copper, steel fiber, and rare earth ceramic additives.
- Independent Stores:Neighborhood repair shops lose share to consolidated fleet service centers but persist in emergency replacement scenarios.
Authorized Dealers defend the core. Online Retail climbs the fastest as consumer specification literacy improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redistributing brake pad manufacturing capacity as producers seek cost-of-compliance arbitrage. The United States, Germany, China, Japan, and India each present distinct formulation mandates and sourcing incentives that reshape supplier location decisions.
United States
Commercial fleet operators in Texas and Ohio compress replacement intervals to maximize vehicle uptime. The EPA and California Air Resources Board enforce copper reduction mandates that reshape friction material specifications. Manufacturing clusters in the Midwest supply domestic OEMs and aftermarket distributors with semi-metallic and ceramic formulations.
Germany
Logistics operators accelerate brake pad change schedules to avoid liability exposure from degraded stopping performance. ECHA substance restrictions and REACH Annex XVII copper limits drive reformulation investments across metallic product lines. Industrial corridors in Bavaria and North Rhine-Westphalia concentrate R&D facilities for copper-free ceramic alternatives.
China
Domestic OEM sourcing mandates favor local brake pad suppliers over traditional Western supply chains. GB standards and SAMR certification protocols govern quality thresholds and market access procedures. Manufacturing clusters in Jiangsu and Guangdong provinces scale ceramic and semi-metallic output for commercial vehicle production.
Japan
Specialized expertise in friction material tribology concentrates among formulation chemists in METI-supported industrial zones. JIS standards and domestic certification requirements maintain technical barriers for imported friction materials. Production facilities in Aichi and Kanagawa prefectures supply aramid fiber substrates for high-performance ceramic pads.
India
Underpenetrated organized service networks in Maharashtra and Tamil Nadu present white-space for branded ceramic pad distribution. The PLI scheme and BIS quality protocols incentivize domestic manufacturing capacity expansion. Fleet procurement departments in industrial corridors consolidate sourcing through integrated vehicle maintenance contracts.
Automotive Brake Pads Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue copper-free formulation specialization and sensor-integrated pad architectures. The market structures around three maturity tiers: integrated braking system suppliers with captive friction material capacity, independent pad specialists with formulation expertise, and regional fabricators serving price-sensitive aftermarket channels. Dominant competitive moves include backward integration into bonded fiber substrate production and strategic partnerships with fleet management platforms for predictive maintenance contracts.
Among European-based suppliers, TMD Friction and Continental AG exemplify the integrated tier with braking system breadth, while Brembo occupies a position on the premium-performance vector. Japanese specialists including Nisshinbo Holdings and Akebono Brake Industry represent formulation-driven archetypes with copper-free development capabilities. Tenneco anchors the North American aftermarket through extensive distribution networks. These named entities serve as reference points for market structure analysis rather than exhaustive enumeration.
| Leading Market Players |
|---|
| TMD Friction |
| Nisshinbo Holdings |
| Brembo |
| Tenneco |
| EBC Brakes |
| Akebono Brake Industry |
| ZF TRW |
| ADVICS |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
California's SB 346 copper mandate and Europe's REACH Annex XVII restrictions gate qualified supply by disqualifying legacy semi-metallic formulations from premium-tier pricing access, forcing suppliers to absorb reformulation costs or forfeit specification authority with compliant OEMs and fleet operators.
Pricing Analysis
Distributor margin layers compress as authorized dealers bundle installation labor with material supply, while direct-to-consumer online channels capture premium ceramic pricing that bypasses wholesale markups. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant ceramic pads from transitional low-copper semi-metallics and stranded legacy inventory. Pricing pressure stems from raw material volatility in rare earth ceramic additives and aramid fiber substrates. Fleet procurement departments show lowest price sensitivity due to uptime guarantees, while independent repair shops face acute margin compression.
Supply Chain Analysis
China's GB standards and SAMR certification protocols reshape sourcing by mandating local brake pad production for domestic OEM fitments, severing traditional Western supply chain dependencies. Manufacturing concentrates in Germany, China, and Japan, with critical aramid fiber substrates drawing from specialized Japanese and German suppliers. Supply chain risk centers on single-source vulnerability in bonded fiber substrates for high-performance ceramic pads. Distribution runs through authorized dealer networks for fleet contracts and online retail for direct-to-consumer premium formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive brake pads rests on copper-free formulation premiums and captive fiber substrate production that insulates suppliers from raw material volatility.
For Market Incumbents: Extend copper-free ceramic capacity ahead of REACH enforcement milestones to capture specification authority with European OEMs. Backward integration into aramid fiber substrate production neutralizes supply concentration risk among Japanese and German specialists. Defensive patent positioning in potassium titanate whisker reinforcement blocks emerging entrant access to premium-tier formulations. For New Entrants and Emerging Players: The price-point gap between premium ceramic and economy organic pads creates entry space for mid-tier hybrid formulations targeting India's underpenetrated commercial vehicle aftermarket in Maharashtra and Tamil Nadu. White-space exists in sensor-integrated brake pads for predictive maintenance contracts with fleet management platforms. Go-to-market through digital channels bypasses entrenched wholesale distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional ceramic specialists because formulation chemist expertise concentrates among retiring specialists in Germany and Japan, creating scarcity value for qualified technical teams. Long-term viability favors suppliers with dual ECE R90 and GB standard certification capability. Watch copper-free cold-temperature friction consistency breakthroughs as the inflection signal for Nordic passenger market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Copper-Free Formulation Scale-Up | REACH and EPA compliance secures OEM specification authority with German and California vehicle manufacturers. |
| Backward Integration into Fiber Substrates | Captive aramid supply neutralizes concentration risk among three specialized Japanese and German suppliers. |
| Sensor-Integrated Pad Development | Wear-indicator telemetry enables predictive maintenance contracts with Texas and Ohio fleet operators. |
| Dual Certification Investment | Simultaneous ECE R90 and GB standard qualification opens access to European and Chinese OEM sourcing. |
| Direct-to-Consumer Channel Buildout | Online retail bypasses wholesale markups and captures premium pricing from California and German vehicle owners. |
Methodological Framework
Direct dialogue with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet maintenance directors grounded the qualitative assessment, cross-referenced with vehicle production databases, customs trade records, EPA regulatory filings, and REACH substance restriction announcements. Bottom-up and top-down triangulation validated volume estimates across ceramic, semi-metallic, metallic, and organic formulation segments.
Bottom-up modeling projected replacement cycle compression and copper-free adoption curves across passenger car, heavy-duty truck, and commercial vehicle applications, while top-down analysis calibrated aggregate market expansion against automotive production forecasts and regulatory compliance timelines. CAGRs derived from segment-level growth rate reconciliation with macro vehicle fleet expansion. Key inputs included thermal load tolerance specifications, friction material tribology performance data, and channel inventory rotation patterns.
The model assumes a particular technology adoption path; alternative pathways for copper-free ceramic cold-temperature friction consistency would alter the outlook for Nordic market penetration. Forecasts reflect assumptions regarding REACH enforcement adherence, raw material supply continuity, and fleet operator uptime prioritization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive V-Belts Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Global Automotive Water Separation Systems Market
Automotive Components
Automotive Metal Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automotive Bearing Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Automotive Bushing Market
Automotive Components
Drive System Market