
 Small Engine Market | 2026-2036
Small Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Small Engine Market Analytics
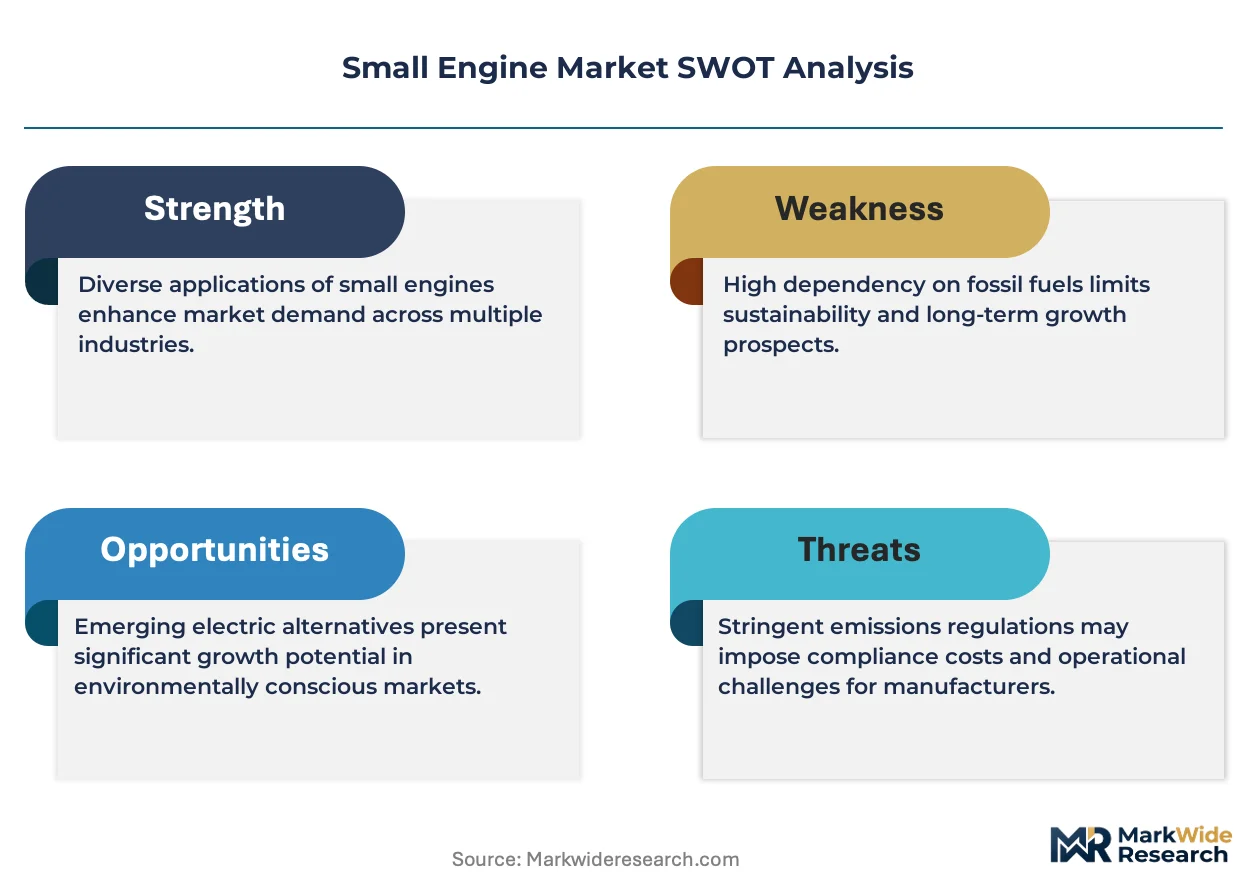
EPA Phase 3 and CARB small off-road engine (SORE) certification is bifurcating the competitive landscape into compliant and non-compliant supplier tiers. Honda Motor Co. leverages its four-stroke emissions leadership to sustain premium positioning in residential and commercial channels. Briggs & Stratton anchors the North American replacement parts ecosystem through dense dealer network coverage. Yamaha Motor Corp. competes in the portable generator segment with inverter technology specialization.
Small engines are compact internal combustion or electric power units typically displacing less than 50cc to 200cc, producing mechanical output for handheld, walk-behind, or stationary equipment through piston-driven crankshaft rotation. Gasoline configurations dominate current installed bases, though electric and hybrid architectures are gaining share in noise-restricted municipal and residential zones. Lawn mowers and generators represent the largest product volume pools, with generators capturing higher margin profiles due to emergency preparedness premiums. The 50-100cc engine size bracket leads unit shipments for handheld equipment, while sub-50cc electric alternatives are displacing two-stroke gasoline units in European and North American consumer markets.
EPA Phase 3 emission rules, CARB SORE amendments, and EU Stage V non-road engine directives are compressing development cycles and raising compliance costs for gasoline-centric portfolios. EPA certification gates market access for engines above specific horsepower thresholds sold in the United States, while EU Stage V pushes particulate and NOx limits that favor electronic fuel injection over carbureted designs. Stakeholders must monitor battery energy density improvements and charging infrastructure buildouts that could accelerate electric substitution in sub-100cc applications.
Market Dynamics
EPA Phase 3 emission standards and CARB SORE amendments are compressing product development cycles while simultaneously accelerating electric powertrain substitution in sub-100cc handheld equipment categories.
Growth Catalysts
- Commercial landscaping outsourcing:Property management firms and municipal parks departments are contracting groundskeeping services, driving fleet refresh demand for professional-grade walk-behind and ride-on equipment.
- Electronic fuel injection penetration:EFI systems enable gasoline engines to meet EU Stage V particulate limits without aftertreatment, preserving engine architecture against battery substitution in mid-displacement categories.
- India BIS certification expansion:Domestic manufacturing incentives and import substitution policies are localizing supply chains for portable generator and agricultural pump applications.
Market Restraints
- Steel and aluminum input volatility:Crankcase and cylinder head castings depend on primary metal prices that fluctuate with energy costs and trade policy uncertainty.
- Carburetor supplier concentration:Two Japanese and one Chinese manufacturer control diaphragm carburetor supply for two-stroke handheld equipment, creating single-source vulnerability.
- Lithium-ion energy density ceiling:Current cell chemistry limits runtime in commercial landscaping applications where gasoline refueling intervals define productivity benchmarks.
Strategic Opportunities
- Brazil ANVISA-equivalent agricultural mechanization:Smallholder farm equipment upgrading from animal traction to motorized tillers and pumps represents underpenetrated volume.
- Hybrid architecture convergence:Series-hybrid generators combining small gasoline engines with battery buffers capture emergency preparedness and noise-restricted construction site demand simultaneously.
- Direct-to-fleet digital procurement:Landscaping service chains are consolidating vendor relationships through integrated maintenance platforms that bypass traditional dealer networks.
Industry Challenges
- Emissions calibration engineering scarcity:EFI mapping and catalyst specification expertise concentrates at tier-one automotive suppliers, raising recruitment costs for small engine OEMs.
- EPA certification timeline compression:Phase 3 test protocol complexity extends homologation cycles, delaying product launches and freezing development capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Engine Market |
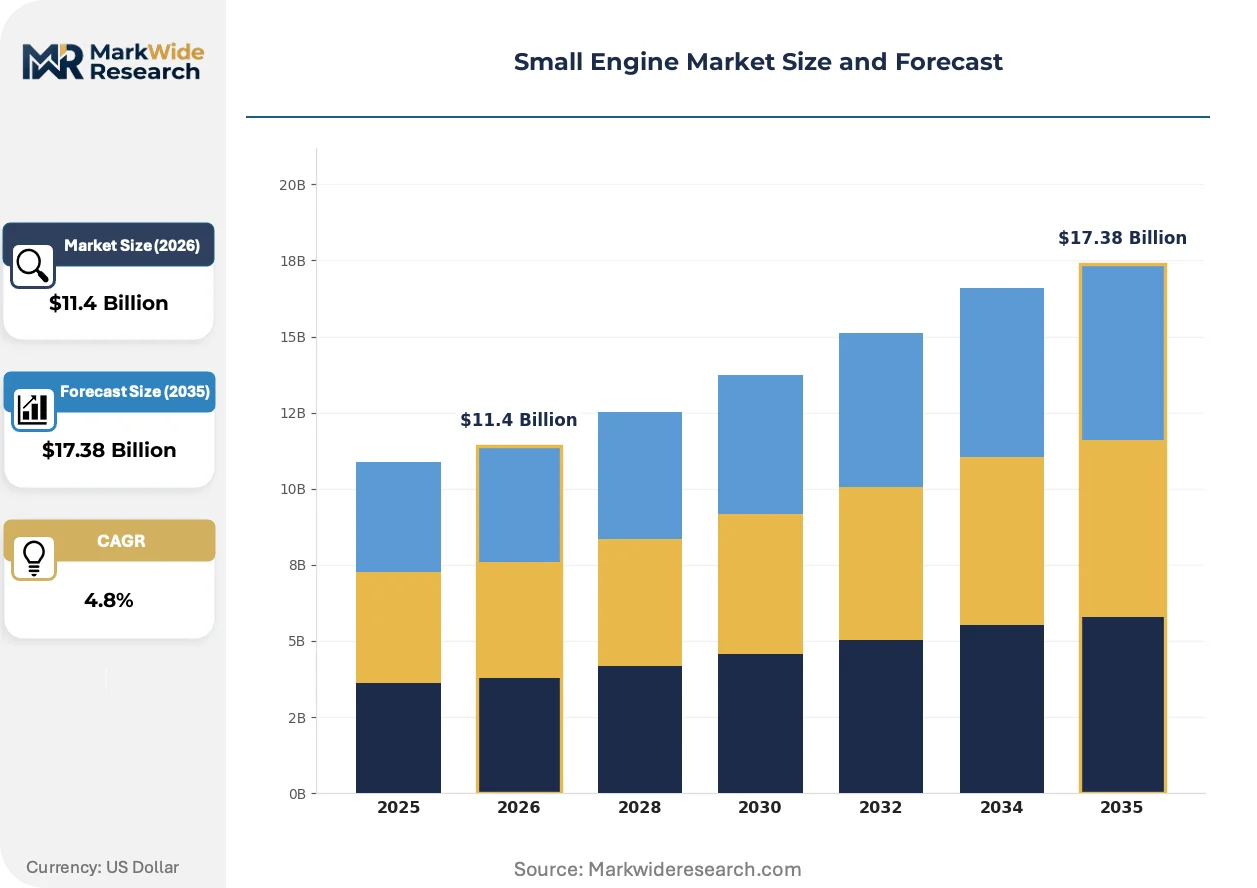
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lawn Mowers, Generators, Chain Saws, Trimmers Fuel Type: Gasoline, Diesel, Electric, Hybrid End User: Residential, Commercial, Agricultural, Industrial Engine Size: Less than 50cc, 50-100cc, 100-200cc, More than 200cc |
| Companies Covered | Yamaha Motor Corp., Kubota Corp., Honda Motor Co., Generac Holdings, Yanmar Co., Briggs & Stratton, Kawasaki Heavy Industries, Changchai, Kohler Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Engine Market Evolving Landscape
Powertrain architecture decisions are splitting the competitive landscape into emissions-compliant gasoline specialists, electric entrants, and hybrid integrators pursuing divergent technical and commercial strategies.
Brushless DC motor and lithium-ion battery packs are bifurcating the sub-50cc handheld segment. Municipal noise ordinances in Germany, California, and Japan are accelerating adoption by groundskeeping contractors. Battery-electric architecture is bifurcating supplier tiers into integrated motor-battery-pack providers and traditional engine manufacturers lacking electrical system competency.
EPA Phase 3 and CARB SORE amendments mandate evaporative emission controls and cold-start hydrocarbon limits that carbureted designs cannot achieve. Engineering teams are redirecting development resources toward EFI platforms and catalyzed exhaust systems. The 100-200cc walk-behind equipment segment faces the steepest compliance cost escalation, compressing margins for volume producers.
Equipment-as-service contracting is replacing unit sales in commercial landscaping channels. Fleet operators are outsourcing maintenance and refresh decisions to integrated service providers who specify equipment. This concentration is visible in United States metropolitan markets where national landscaping chains negotiate direct procurement relationships with manufacturers, disintermediating independent dealers.
Small Engine Market Segmentation
Small engine procurement decisions split across equipment duty cycles, fuel infrastructure availability, and emissions compliance thresholds. Segment boundaries are hardening as EPA Phase 3 and EU Stage V regulations disqualify legacy architectures from specific horsepower and displacement brackets.
Product Type:
EPA Phase 3 evaporative emission controls and cold-start hydrocarbon limits favor sealed fuel systems and catalyzed exhaust configurations, advantaging designs with larger displacement envelopes and integrated aftertreatment packaging.
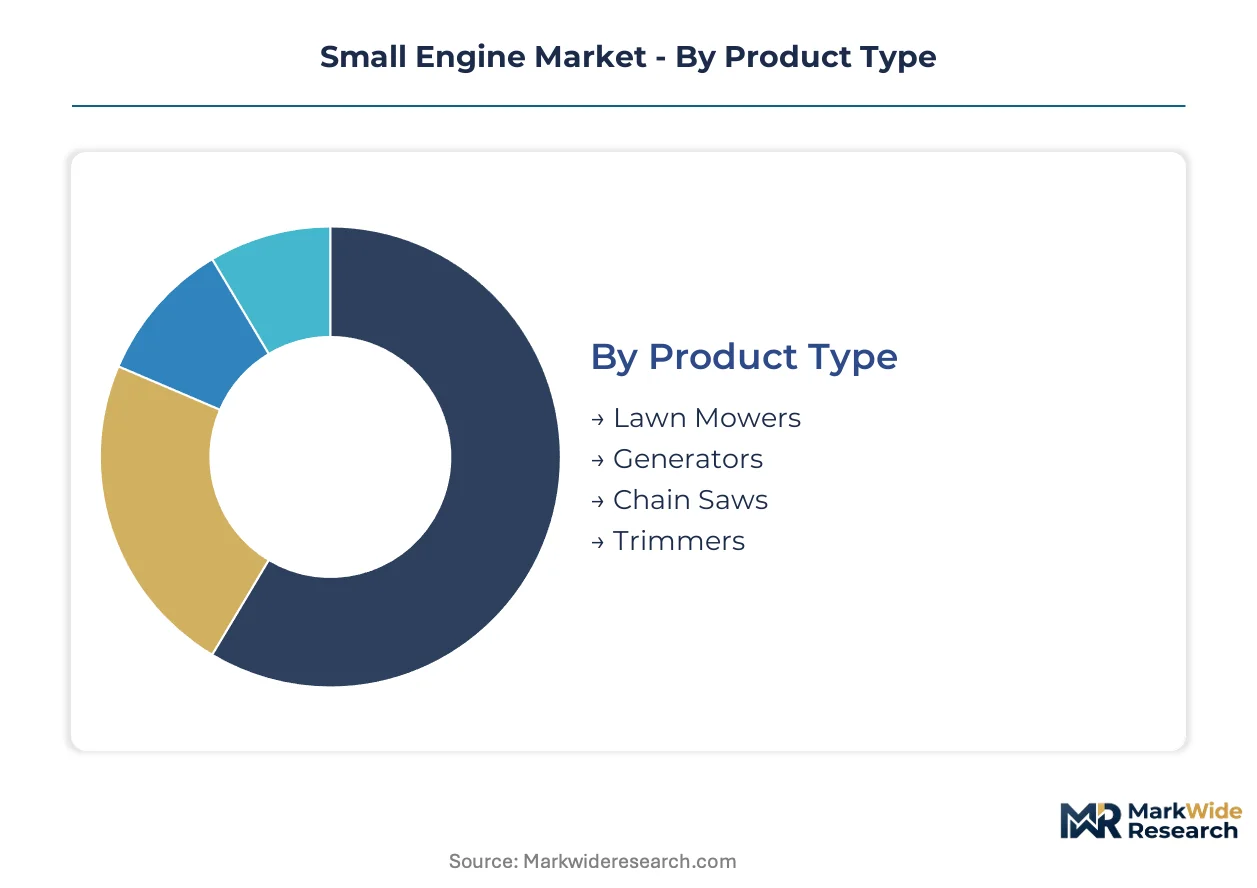
- Lawn Mowers:Walk-behind and ride-on configurations dominate unit volumes for residential and commercial groundskeeping fleets. Demand concentrates in the United States where professional landscaping services operate compressed equipment replacement cycles to maintain fleet reliability.
- Generators:Portable and stationary power units command premium pricing through emergency preparedness positioning and construction site reliability requirements. Demand is climbing fastest in noise-restricted municipal zones where inverter technology and hybrid architectures displace conventional open-frame gasoline units.
- Chain Saws:Handheld forestry equipment requires sub-50cc to 100cc displacement ranges optimized for power-to-weight ratios.
- Trimmers:String and brush-cutting handheld units face acute battery substitution pressure in European and North American consumer channels.
Lawn mowers handle the majority of throughput; generators are gaining share fastest through emergency preparedness premiums and hybrid technology adoption.
Fuel Type:
Cost tier stratification separates carbureted gasoline volume producers from EFI-compliant specialists and electric entrants bearing battery pack cost premiums.
- Gasoline:Four-stroke and two-stroke internal combustion configurations retain installed base dominance in commercial landscaping and portable power applications. EFI penetration is accelerating in the 100-200cc walk-behind segment where EU Stage V particulate limits would otherwise require costly aftertreatment or electric substitution.
- Electric:Brushless DC motor and lithium-ion battery architectures are displacing sub-50cc two-stroke units in handheld equipment categories. Municipal noise ordinances in Germany, California, and Japan are compressing payback periods for battery-electric groundskeeping fleets.
- Diesel:Compression-ignition designs concentrate in stationary generator and agricultural pump applications above 200cc displacement.
- Hybrid:Series-hybrid configurations combining small gasoline prime movers with battery buffers capture simultaneous demand from emergency preparedness and noise-restricted construction site specifications.
Gasoline retains the dominant throughput position; electric is expanding most quickly in sub-100cc handheld categories subject to noise regulation.
End User:
Customer type determines equipment durability specifications, procurement channel preferences, and maintenance outsourcing arrangements.
- Commercial:Landscaping service chains and municipal parks departments specify professional-grade walk-behind and ride-on equipment with compressed replacement cycles. Fleet operators are consolidating vendor relationships through integrated maintenance platforms that disintermediate traditional dealer networks.
- Residential:Consumer purchasers prioritize acquisition cost over lifecycle operating expense, sustaining demand for carbureted gasoline designs in price-sensitive brackets. Retail channel concentration through home improvement chains limits brand switching flexibility.
- Agricultural:Smallholder farm equipment upgrading from animal traction to motorized tillers and pumps represents underpenetrated volume in Brazil and India.
- Industrial:Construction and rental fleet operators demand portable generator reliability and rapid field service response.
Commercial channels handle the majority of throughput; agricultural applications show the steepest expansion trajectory through mechanization programs.
Engine Size:
Displacement brackets align with equipment portability requirements and regulatory horsepower thresholds that gate market access under EPA certification protocols.
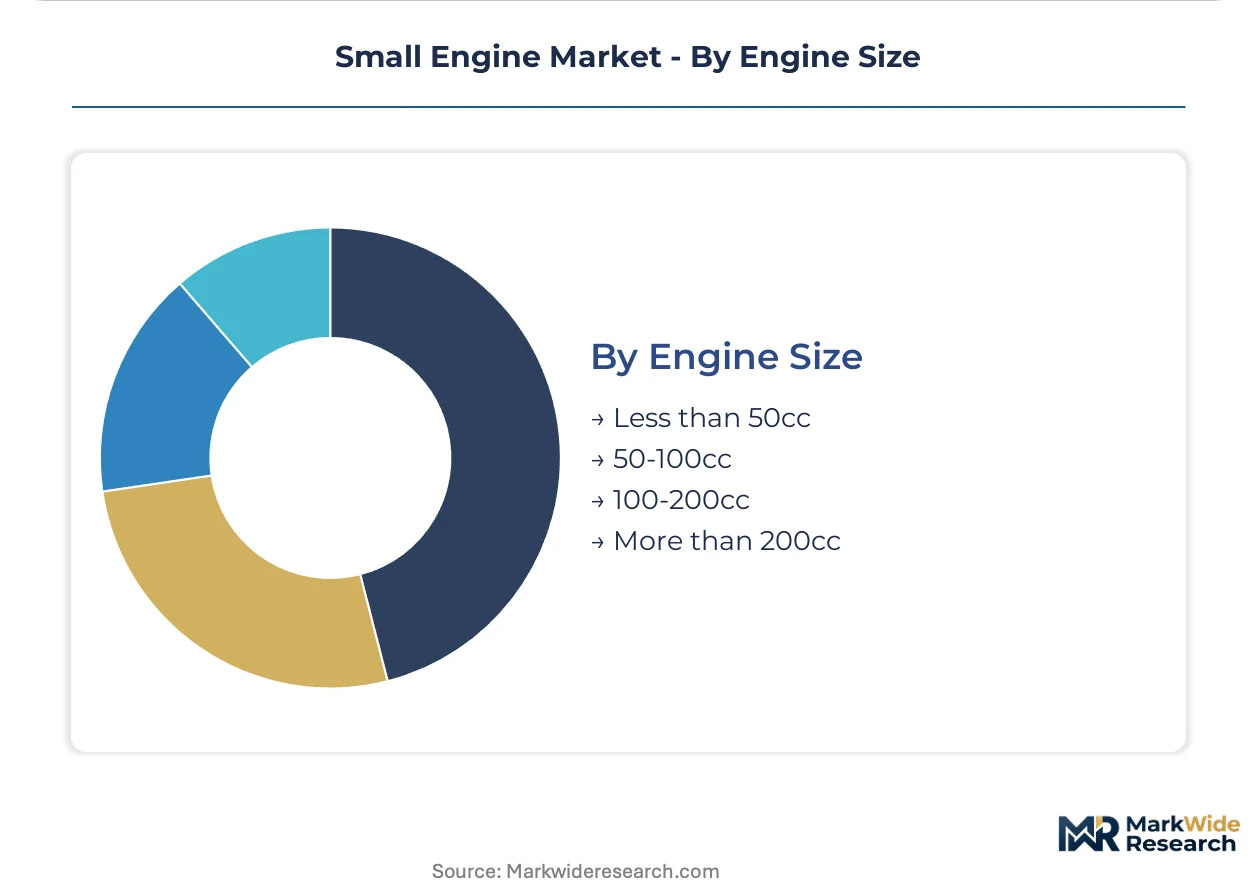
- 50-100cc:Mid-displacement handheld and walk-behind equipment faces acute compliance cost escalation under EPA Phase 3 and CARB SORE amendments. EFI adoption is concentrating here as carbureted designs fail cold-start hydrocarbon limits.
- Less than 50cc:Sub-50cc handheld equipment including string trimmers and chain saws is experiencing the fastest battery substitution as lithium-ion energy density improves and municipal noise restrictions tighten.
- 100-200cc:Larger walk-behind and small ride-on equipment brackets bear the steepest margin compression from catalyzed exhaust and evaporative emission control requirements.
- More than 200cc:High-displacement stationary and large ride-on applications retain gasoline and diesel dominance where battery weight and charging infrastructure constraints prevent electrification.
The 50-100cc bracket handles the majority of unit shipments; sub-50cc electric alternatives are climbing the fastest on share through noise regulation alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing incentives and import substitution policies are reshaping procurement patterns across major small engine consumption centers. Emissions certification regimes in the United States, European Union, and India are compressing development timelines while accelerating electric powertrain localization.
United States
Professional landscaping service chains drive fleet refresh demand through compressed replacement cycles. EPA Phase 3 emission standards gate market access for engines above specific horsepower thresholds. Wisconsin and Georgia host dense manufacturing clusters where OEMs coordinate dealer network coverage for replacement parts ecosystems.
Germany
Municipal noise ordinances in Bavaria and North Rhine-Westphalia accelerate battery-electric groundskeeping fleet conversions. EU Stage V non-road engine directives push particulate and NOx limits favoring electronic fuel injection over carbureted designs. Stuttgart industrial corridor concentrates EFI calibration engineering talent for compliance-focused suppliers.
China
Agricultural mechanization programs in Shandong and Jiangsu provinces sustain demand for motorized tillers and irrigation pumps. GB standards alignment with EU Stage V particulate thresholds raises compliance costs for export-oriented manufacturers. Chongqing municipality anchors small diesel engine production for domestic farm equipment upgrading.
India
Domestic manufacturing incentives under the PLI scheme localize supply chains for portable generator and agricultural pump applications. BIS certification expansion tightens quality gates for imported engine components. Pune and Chennai industrial belts concentrate assembly operations for sub-200cc equipment serving South Asian markets.
Brazil
Smallholder farm equipment upgrading from animal traction to motorized implements represents underpenetrated volume in Minas Gerais and São Paulo states. ANVISA-equivalent agricultural mechanization standards remain less stringent than EPA or EU regimes. Sorocaba manufacturing cluster hosts assembly operations for regional Latin American distribution.
Small Engine Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with engine divisions alongside specialized powertrain manufacturers. Market structure concentrates around Japanese and North American incumbents with established emissions certification track records. Three strategic archetypes dominate: four-stroke gasoline specialists, electric powertrain integrators, and hybrid architecture developers. Competitive moves center on EFI platform development partnerships and direct-to-fleet digital procurement channel establishment.
Within the diversified industrial tier, Honda Motor Co. and Yamaha Motor Corp. occupy positions reflecting multi-decade emissions compliance leadership. Briggs & Stratton anchors the North American replacement parts ecosystem archetype through dense dealer network coverage. Kubota Corp. represents the agricultural equipment integration specialist segment with compact engine-to-implement vertical coordination. These three exemplify how geographic origin and corporate structure shape competitive positioning under tightening certification regimes.
| Leading Market Players |
|---|
| Yamaha Motor Corp. |
| Kubota Corp. |
| Honda Motor Co. |
| Generac Holdings |
| Yanmar Co. |
| Briggs & Stratton |
| Kawasaki Heavy Industries |
| Changchai |
| Kohler Co. |
| Others |
Value Network & Pricing Analysis
Lithium-ion battery pack substitution for gasoline powertrains is redrawing procurement geography toward East Asian cell manufacturers while compressing margin structures for traditional engine castings and carburetion suppliers. This input shift simultaneously elevates pricing power for integrated motor-battery providers and erodes historic premiums for EFI-compliant gasoline architectures in sub-100cc handheld categories.
Pricing Analysis
Certification level under EPA Phase 3 and CARB SORE amendments creates the primary spread between premium EFI-equipped engines and economy carbureted units facing market exclusion. Three-tier pricing structure across EPA-certified premium, transitional standard, and non-compliant economy levels reflects evaporative emission control complexity and cold-start hydrocarbon calibration investment. Cost compression in the 100-200cc walk-behind segment is intensifying because catalyzed exhaust and sealed fuel system requirements add component cost without proportional performance differentiation. Residential consumer channels exhibit highest price sensitivity, while commercial landscaping fleets prioritize reliability and fleet management integration over acquisition cost.
Supply Chain Analysis
China and Japan anchor global production of small displacement gasoline engines, lithium-ion battery cells, and precision carburetor components for handheld equipment categories. Crankcase castings draw from aluminum smelters in Shandong and Jiangsu provinces, while diaphragm carburetor supply concentrates with two Japanese and one Chinese manufacturer creating single-source vulnerability for two-stroke handheld production. Tariff exposure on steel and aluminum primary metals amplifies input cost volatility for cylinder head and crankcase foundries. Distribution runs through dense dealer networks in North America and direct-to-fleet digital procurement platforms consolidating vendor relationships for commercial landscaping service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFI calibration engineering scarcity and catalyzed exhaust system specification expertise are concentrating at tier-one automotive suppliers, leaving small engine OEMs competing for finite talent pools while compliance timelines compress. This capability gap threatens product launch schedules and homologation success for gasoline-centric portfolios.
For Market Incumbents: Shield core replacement parts revenue through backward integration into dealer network software platforms that lock in maintenance outsourcing relationships. Prioritize captive EFI calibration capability through acquisition of automotive emissions engineering specialists before Phase 3 timeline compression freezes development capital. Battery-electric entrants and hybrid integrators represent the primary substitution threat requiring defensive patent positioning in series-hybrid generator architectures. For New Entrants and Emerging Players: Anchor in Brazilian smallholder agricultural mechanization where ANVISA-equivalent standards remain less stringent than EPA or EU regimes, creating regulatory arbitrage for carbureted designs excluded from North American and European channels. Target portable generator hybridization as the most penetrable white space, combining small gasoline prime movers with battery buffers to capture simultaneous emergency preparedness and noise-restricted construction site demand. Pursue direct-to-fleet digital procurement relationships with consolidating landscaping service chains as the primary go-to-market angle bypassing established dealer networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outdoor power equipment manufacturers carrying legacy carbureted portfolios facing Phase 3 obsolescence. Long-term viability over the next decade hinges on successful EFI platform transition or electric powertrain pivot completion. Acquisition candidates include tier-two carburetor-dependent suppliers with undervalued dealer network real estate and Brazilian or Indian assembly operations serving mechanization growth markets. Watch battery energy density improvement curves and municipal noise ordinance adoption rates as the critical inflection signal for electric substitution acceleration in sub-100cc categories.| Strategic Initiative | Industry Significance |
|---|---|
| EFI Platform Development Partnership | Bridges emissions compliance capability gaps through automotive supplier technology licensing. |
| Direct-to-Fleet Digital Procurement Launch | Captures consolidating commercial landscaping vendor relationships disintermediating dealer networks. |
| Hybrid Generator Architecture Investment | Addresses simultaneous emergency preparedness and noise-restricted construction site specifications. |
| Brazilian Agricultural Mechanization Expansion | Exploits regulatory arbitrage for carbureted designs in smallholder farm equipment upgrading. |
| Dealer Network Software Integration | Locks in aftermarket parts revenue through maintenance outsourcing platform control. |
Research Methodology
The analysis maps gasoline, electric, hybrid, and diesel powertrain sub-sectors, each validated through OEM product planning directors, commercial landscaping fleet operators, agricultural equipment distributors, and EFI calibration engineering specialists. Primary interview intelligence combined with secondary validation against EPA certification databases, CARB SORE amendment filings, EU Stage V directive documentation, and customs trade flow records enables bottom-up unit shipment estimation and top-down market value triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated equipment type, fuel architecture, end-user channel, engine displacement bracket, and regional regulatory cluster dimensions. CAGRs were derived from regression analysis of historical replacement cycle patterns and regulatory phase-in schedules. Industry-specific forecast inputs included commercial landscaping fleet refresh rates, lithium-ion cell cost curves, and municipal noise ordinance adoption timelines.
Decision-makers should treat outputs as directional under stable regulatory phase-in assumptions and continuing metal price volatility; material deviation in battery energy density improvement or accelerated EPA enforcement would warrant model refresh. Recalibration cycles align with material shifts in Phase 3 certification timelines, CARB SORE amendment finalization, and lithium-ion cost parity achievement in sub-100cc handheld categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Tire Mold Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Heavy Duty Engines Market
Automotive Parts
Global Automotive Engine Valves Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Indonesia Commercial Vehicles Lubricants Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
France Commercial Vehicles Lubricants Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Automotive Belts and Hoses Market