
 Windshield Washer Fluid Market | 2026-2036
Windshield Washer Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Windshield Washer Fluid Market Outlook
Aftermarket service revenue is fragmenting across multiple channel tiers as retailers, fleet maintenance networks, and direct-to-consumer platforms compete for recurring fluid purchases. Prestone Products Corporation leverages its heritage in automotive chemicals to sustain shelf presence at major automotive stores and discount retailers. Guangzhou Botny Chemical Co., Ltd. anchors supply across Asia-Pacific through manufacturing scale and regional distribution density. 3M Company differentiates via technology leadership in additive chemistry for streak-free performance and cold-climate reliability.
Windshield washer fluid comprises a formulated aqueous solution containing surfactants, solvents, and functional additives designed to remove road grime, insect residue, and ice from vehicle windshields without damaging wiper blades or painted surfaces. The solution typically operates across temperature ranges from minus forty degrees Celsius to plus fifty degrees Celsius depending on seasonal formulation. Ready-to-use formulations command the largest volume share due to consumer convenience and reduced mixing errors, while concentrated products attract cost-sensitive fleet operators and environmentally conscious buyers seeking reduced packaging waste. Winter blend formulations carry premium positioning in northern climates where methanol or ethylene glycol content prevents freezing, and bulk container packaging dominates fleet and service station procurement channels.
The EPA regulates volatile organic compound content under Clean Air Act provisions, directly limiting methanol concentrations in consumer-grade formulations and pushing manufacturers toward lower-VOC alternatives. State-level regulations in California and New York impose additional formulation constraints that exceed federal baselines, creating a patchwork compliance environment for national distributors. The National Highway Traffic Safety Administration references windshield clarity standards within Federal Motor Vehicle Safety Standards, indirectly influencing OEM specification requirements for factory-fill products. Stakeholders must monitor evolving chemical restriction timelines and assess backward integration into additive sourcing to protect margin pools from formulation cost volatility.
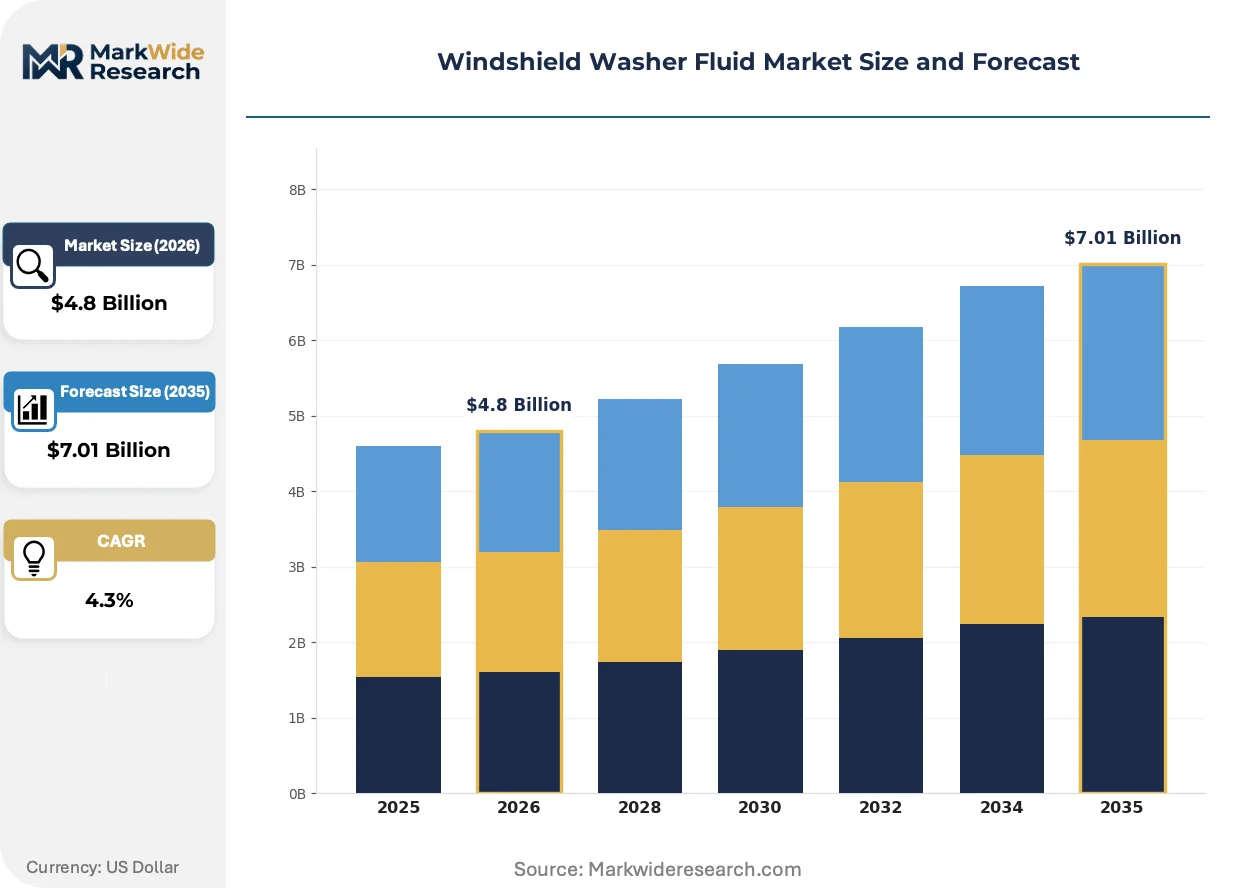
Market Dynamics
Fleet uptime mandates and EPA VOC restrictions are compressing formulation flexibility while fragmenting procurement channels across retail, direct-to-consumer, and service network tiers.
Growth Catalysts
- Commercial Vehicle Parc Expansion:Fleet operators in China and India are extending maintenance intervals, driving bulk concentrate purchases through dedicated supply contracts.
- REACH Chemical Restrictions:The European Chemicals Agency is accelerating methanol substitution research, opening formulation partnerships between additive suppliers and regional blenders.
- Aftermarket Channel Densification:E-commerce platforms in Southeast Asia are capturing recurring fluid purchases previously routed through traditional auto parts distributors.
Market Restraints
- Methanol Price Volatility:Feedstock cost swings tied to natural gas markets compress margin pools for winter blend manufacturers in North America.
- Supply Concentration Risk:Surfactant additive production clusters in Germany and China expose formulators to single-source dependency during logistics disruptions.
- Technical Performance Ceiling:Current biodegradable surfactant chemistries fail to match petroleum-derived alternatives for sub-zero ice removal speed.
Strategic Opportunities
- Underpenetrated Fleet Segments:Latin American mining and agriculture vehicle operators represent untapped demand for concentrated bulk formulations with corrosion inhibitors.
- EU Green Deal Alignment:The European Commission's sustainable chemistry incentives reward manufacturers developing bio-based solvent alternatives to ethylene glycol.
- Connected Vehicle Integration:Telematics-enabled fluid level monitoring is hybridizing with predictive maintenance platforms to automate replenishment scheduling.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in low-VOC surfactant blending remains concentrated among legacy chemical engineering programs in Germany and Japan.
- Multi-Jurisdiction Compliance:California Air Resources Board standards diverge from EPA baselines, forcing dual-SKU production runs for national distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Windshield Washer Fluid Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.01 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, Ready-to-Use, Winter Blend, Summer Blend End User: Retail Customers, Automotive Manufacturers, Fleet Operators, Service Stations Packaging Type: Bottles, Cans, Bulk Containers, Pouches Distribution Channel: Online, Supermarkets, Automotive Stores, Discount Retailers |
| Companies Covered | Guangzhou Botny Chemical Co., Ltd., Soft99 Corporation, 3M Company, Rain-X, Turtle Wax, Prestone Products Corporation, SONAX GmbH, Total, ITW Global Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Windshield Washer Fluid Market Strategic Shifts
Formulation chemistry and distribution architecture are undergoing simultaneous pressure from environmental compliance mandates and fleet digitization requirements.
Biodegradable surfactant technology is hybridizing petroleum-derived and plant-based chemistries to maintain freeze-point depression while satisfying ECHA registration thresholds. European fleet operators are piloting these formulations in municipal vehicle contracts. The structural consequence is compressing R&D timelines as blenders race to validate performance equivalence before 2025 restriction deadlines.
The EPA's Safer Choice program is expanding voluntary certification criteria to include aquatic toxicity benchmarks beyond baseline VOC limits. Manufacturers pursuing this designation must reformulate with alternative solvents and submit third-party efficacy data. Consumer-grade ready-to-use products face the steepest compliance cost increases, accelerating private-label concentration at discount retailers.
Subscription-based replenishment models are displacing spot purchasing among commercial fleet managers seeking to consolidate indirect spend categories. Third-party logistics providers in the United States are capturing this demand through vendor-managed inventory programs tied to telematics data feeds. The shift is most visible in long-haul trucking segments where fluid consumption correlates directly with route mileage and weather exposure.
Windshield Washer Fluid Market Segmentation
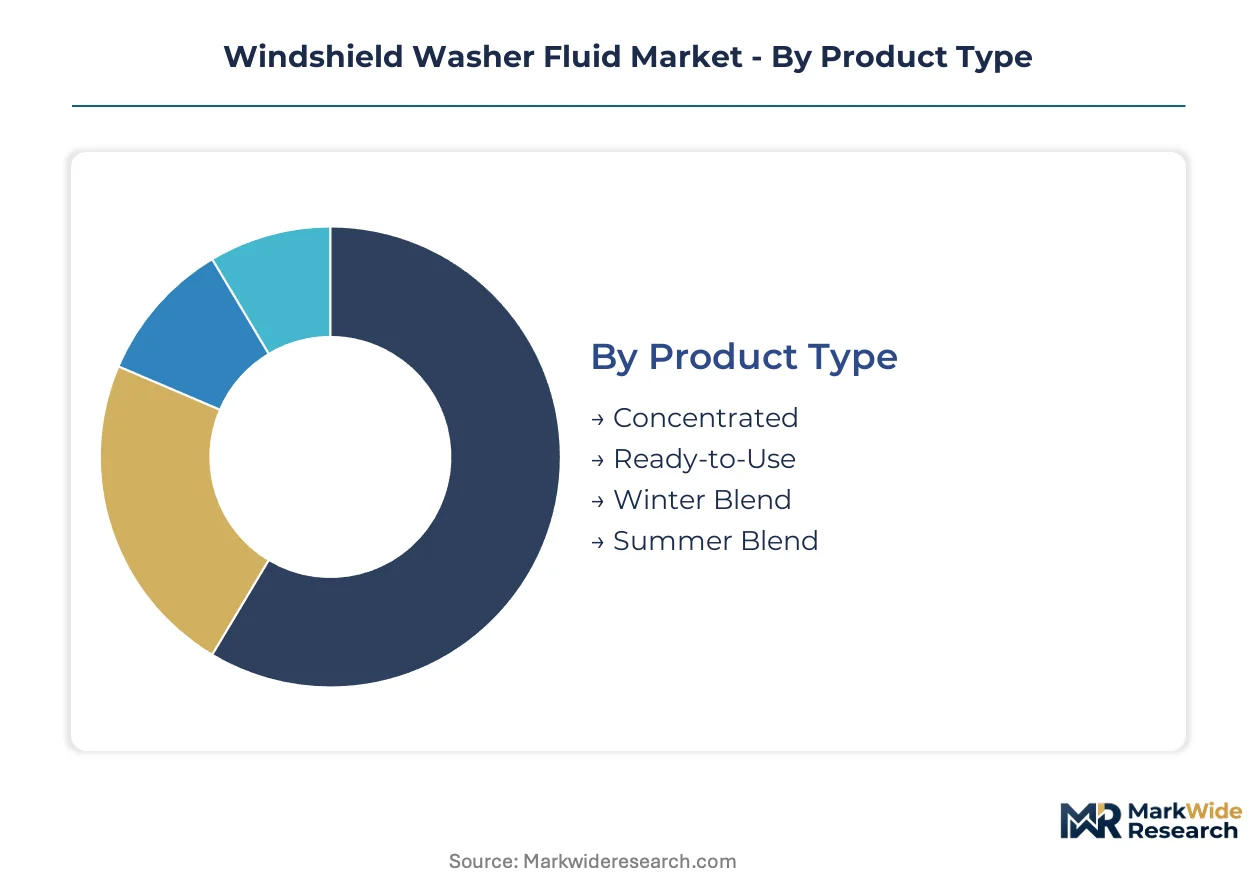
Windshield washer fluid segmentation reflects divergent service intensity across vehicle ownership models. Fleet operators demand bulk logistics and predictive replenishment, while retail consumers prioritize shelf-ready convenience and seasonal adaptability.
Product Type:
After-sales service intensity varies sharply by formulation complexity, with winter blends requiring technical support for freeze-point verification and dilution guidance.
- Ready-to-Use:Pre-diluted aqueous solutions eliminate consumer mixing errors and command shelf space at automotive retailers and convenience stores. Demand concentrates in suburban North American markets where DIY vehicle maintenance persists and temperature fluctuations necessitate seasonal formula swaps.
- Winter Blend:Methanol or ethylene glycol formulations engineered for freeze-point depression below minus forty degrees Celsius. Fleet procurement in Minnesota, Michigan, and Canadian provinces drives volume, with bulk tanker deliveries synchronized to municipal snow-removal contracts.
- Concentrated:High-strength base fluids requiring dilution prior to application, appealing to cost-conscious commercial operators seeking reduced packaging waste.
- Summer Blend:Surfactant-heavy formulations optimized for insect residue removal without freeze-protection additives, prevalent in Sun Belt states and Mediterranean climates.
By volume, Ready-to-Use leads. By growth pace, Winter Blend is ahead as climate volatility extends severe cold periods into traditional shoulder seasons.
End User:
Cost tier stratification separates specification-grade OEM contracts from price-sensitive spot purchases at retail.
- Fleet Operators:Commercial vehicle managers procuring through multi-year supply agreements with corrosion-inhibitor specifications. Mining and agriculture fleets in Brazil and Australia represent expanding demand for concentrated bulk formulations.
- Retail Customers:Individual vehicle owners selecting single-unit purchases based on seasonal temperature ratings and brand recognition at point-of-sale.
- Automotive Manufacturers:OEMs specifying factory-fill formulations meeting Federal Motor Vehicle Safety Standards for windshield clarity.
- Service Stations:Quick-lube networks bundling fluid top-offs with oil change services, capturing recurring revenue from time-constrained drivers.
Fleet Operators generate the highest per-account revenue. Retail Customers deliver the steepest expansion trajectory as e-commerce platforms capture recurring subscription purchases.
Packaging Type:
Volume economics favor bulk configurations for commercial accounts while convenience drives single-serve formats.
- Bulk Containers:Intermediate bulk containers and drum formats dominate fleet maintenance depots and municipal vehicle yards.
- Bottles:One-gallon and half-gallon polyethylene containers standard at automotive stores and supermarkets.
- Cans:Aerosol formats for de-icer sprays complementary to reservoir fluids.
- Pouches:Flexible packaging emerging in concentrated products for reduced shipping cube and shelf footprint.
Bulk Containers anchor commercial procurement. Pouches are climbing the fastest as sustainability mandates pressure plastic reduction.
Distribution Channel:
Customer type determines channel selection, with fleet managers bypassing retail entirely through direct vendor relationships.
- Automotive Stores:Specialized retailers stocking seasonal SKUs with technical staff guidance on freeze-point ratings.
- Online:E-commerce platforms capturing subscription replenishment from fleet managers and bulk-conscious consumers.
- Supermarkets:Mass merchants offering promotional pricing on ready-to-use formats during seasonal transition periods.
- Discount Retailers:Private-label concentration at price-focused chains compressing branded margins.
Automotive Stores retain the largest transaction volume. Online is gaining share fastest as telematics-integrated replenishment platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes windshield washer fluid through fleet bulk procurement and retail ready-to-use channels simultaneously, while the United States splits demand between seasonal DIY purchases and commercial service contracts, creating divergent supply chain configurations.
United States
Fleet operators in Michigan and Minnesota drive concentrated winter blend demand through municipal snow-removal contracts. The EPA's Safer Choice program imposes voluntary aquatic toxicity benchmarks beyond baseline VOC limits. Manufacturing clusters in Ohio and Illinois supply private-label formulations to discount retailers across the Midwest.
Germany
Commercial vehicle parc expansion in Bavaria and North Rhine-Westphalia accelerates bulk concentrate procurement. ECHA registration thresholds under REACH accelerate methanol substitution research among regional blenders. Stuttgart's automotive chemical corridor hosts formulation partnerships between additive suppliers and winter blend specialists.
China
Domestic vehicle parc growth in Guangdong and Jiangsu provinces fuels aftermarket channel development for ready-to-use products. The Ministry of Ecology and Environment enforces dual carbon goals that pressure manufacturers toward bio-based solvent alternatives. Shanghai's chemical processing clusters anchor supply for Asia-Pacific distribution networks.
Brazil
Mining and agriculture fleets in Minas Gerais and São Paulo generate untapped demand for concentrated bulk formulations with corrosion inhibitors. ANVISA regulates chemical content in consumer-grade automotive products through national sanitary surveillance standards. São Paulo's industrial belt concentrates blending capacity for Latin American export markets.
Japan
Metropolitan fleet managers in Tokyo and Osaka adopt subscription-based replenishment models tied to telematics data. METI promotes sustainable chemistry incentives that reward bio-based surfactant development. Nagoya's automotive supplier corridor integrates windshield washer fluid specifications into OEM factory-fill contracts.
Windshield Washer Fluid Market Competitive Environment
Capability concentration sits with specialty additive developers; scale advantage sits with regional chemical conglomerates. The market structures around three tiers: multinational diversified chemical producers, regional blending specialists with distribution density, and private-label manufacturers serving price-focused retail chains. Dominant competitive moves include backward integration into surfactant sourcing and geographic expansion through distributor acquisition.
Within the diversified chemical tier, 3M Company and Total occupy positions anchored by technology leadership in additive chemistry. Guangzhou Botny Chemical Co., Ltd. exemplifies the regional specialist archetype through Asia-Pacific manufacturing scale. Prestone Products Corporation represents heritage automotive chemical positioning at North American retail channels.
| Leading Market Players |
|---|
| Guangzhou Botny Chemical Co., Ltd. |
| Soft99 Corporation |
| 3M Company |
| Rain-X |
| Turtle Wax |
| Prestone Products Corporation |
| SONAX GmbH |
| Total |
| ITW Global Brands |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's methanol production clusters is compressing supplier margins and forcing blenders toward longer-term contract structures that lock in feedstock costs while sacrificing pricing flexibility.
Pricing Analysis
Long-term offtake agreements dominate fleet procurement, insulating large buyers from methanol spot volatility while spot purchases concentrate among retail consumers facing seasonal price swings. Price differentiation hinges on freeze-point certification grade and volume scale, with municipal contracts commanding standard-tier rates and private-label discount retailers absorbing the steepest cost compression. Pricing pressure stems from private-label concentration at mass merchants, eroding branded premia in ready-to-use segments. Fleet operators exhibit the lowest price sensitivity due to uptime penalties, while individual retail buyers switch brands readily on promotional pricing.
Supply Chain Analysis
Upstream feedstock production concentrates methanol manufacturing in China, the United States, and Trinidad and Tobago, with surfactant additive synthesis clustering in Germany and Japan. Formulators draw from methanol, ethylene glycol, and petroleum-derived surfactant chemistries, with bio-based alternatives gaining trial volume in European municipal contracts. Single-source vulnerability in German surfactant production exposes blenders to logistics disruptions during Rhine shipping constraints. Distribution runs through dedicated bulk tanker networks for fleet accounts and third-party logistics providers for retail replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation through vendor-managed inventory programs is shifting bargaining power toward large commercial buyers and fragmenting incumbent supplier relationships.
For Market Incumbents: Pre-empt margin erosion by securing captive methanol supply through backward integration into Chinese or U.S. production assets, and accelerate Safer Choice certification investment to defend shelf position against private-label encroachment at discount retailers. Channel control through telematics-integrated replenishment platforms represents the priority defensive lever against third-party logistics capture of fleet accounts. For New Entrants and Emerging Players: Pursue Latin American mining and agriculture fleet segments where concentrated bulk demand lacks established corrosion-inhibitor specifications, and exploit bio-based surfactant partnerships with European blenders facing REACH compliance deadlines. Direct-to-fleet sales models bypassing traditional distributor markups offer the most penetrable go-to-market angle against entrenched regional incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-enabled replenishment platforms serving long-haul trucking fleets, where route-mileage data automates consumption forecasting and locks in multi-year supply agreements. Acquisition targets should prioritize regional blenders with additive sourcing relationships and existing EPA Safer Choice certifications. Monitor ECHA methanol restriction timelines as the inflection signal for bio-based formulation asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Production | Captive feedstock supply insulates margin pools from natural gas price volatility in North American winter blend manufacturing. |
| Safer Choice Certification Investment | EPA aquatic toxicity benchmarks differentiate premium formulations from private-label competitors at automotive retailers. |
| Telematics-Integrated Replenishment Platform | Predictive maintenance data from fleet operators automates scheduling and locks in recurring revenue streams. |
| Bio-Based Surfactant Partnership | European municipal contracts reward ECHA-compliant formulations with freeze-point performance equivalent to petroleum-derived alternatives. |
| Latin American Distribution Acquisition | Regional density in Brazil and Chile captures mining fleet demand for concentrated bulk formulations with corrosion inhibitors. |
Study Parameters
A spread of perspectives from fleet procurement managers, formulation chemists at regional blenders, automotive retailer category buyers, and additive supplier technical directors converged on the working assumptions around methanol substitution timelines and fleet digitization adoption curves. Secondary validation drew from EPA Safer Choice certified product registries, ECHA REACH registration databases, U.S. customs trade data on methanol imports, and automotive aftermarket sales audit data. Bottom-up volume estimates by formulation type and end-use segment were triangulated against top-down chemical industry production capacity assessments.
Demand-supply balance modeling across the projection horizon incorporated vehicle parc expansion trajectories, fleet maintenance interval extensions, and regulatory restriction phase-ins without specifying implementation years. Segmentation dimensions included formulation complexity, end-use procurement structure, packaging configuration, and regional climate severity. CAGRs were derived from fitted growth curves anchored to historical consumption patterns and elasticity-adjusted price response functions. Industry-specific inputs encompassed methanol feedstock cost indices and winter temperature anomaly forecasts.
Sensitivities concentrate around ECHA methanol substitution deadlines, EPA Safer Choice program expansion scope, and fleet telematics platform penetration rates that could accelerate or delay subscription-based replenishment adoption. Cross-checking against ACC chemical production surveys and automotive fleet operating statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Motorcycle Carbon Ceramic Brake Rotors Market
Automotive Parts
Automotive Central Lubrication System Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Philippines Automotive Engine Oils Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Automotive Steering System Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Global Automotive Selective Catalytic Reduction System Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market