
 Tire Tread Cutting Machines Market | 2026-2036
Tire Tread Cutting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Tread Cutting Machines Market Analytics
Aftermarket maintenance contracts is hardening as a discrete revenue layer alongside equipment sales, with vendors bundling predictive blade-wear monitoring and remote diagnostics into multi-year service agreements. Eldan Recycling A/S leverages its European installed base to anchor long-term service retention. CM Shredders sustains competitive differentiation through specialized configurations for off-the-road tire processing. Granutech-Saturn Systems dominates the North American replacement parts channel, controlling access to proprietary cutter geometries that lock in customer loyalty.
Tire tread cutting machines are precision industrial systems that sever worn tread sections from tire carcasses using mechanical shears, water jets, or laser-guided CNC heads, operating at tolerances that preserve casing integrity for subsequent retreading or recycling. Automatic systems lead the product type category due to throughput requirements at high-volume retread plants, while water jet technology represents the fastest-growing segment as retreaders adopt cold-cutting methods that eliminate thermal degradation of rubber compounds. Light vehicle applications remain the largest application pool, though heavy vehicle retreading commands superior margins per unit processed.
EPA emissions standards and OSHA machine guarding requirements shape equipment specifications in the United States, while REACH chemical compliance and CE machinery directives govern European market access. China's GB standards and MIIT industrial equipment certifications create parallel compliance pathways for domestic and export-oriented manufacturers. Stakeholders must monitor how evolving extended producer responsibility frameworks for tire waste alter the economics of retreading versus shredding, as this calculus directly determines replacement demand for cutting equipment.
Market Dynamics
Water jet cold-cutting technology is compressing thermal degradation risks while OSHA machine guarding mandates force capital refresh cycles at North American retread plants.
Growth Catalysts
- EPA Emissions Standards:Tier 4 final rules for off-road equipment compel retreaders to replace aging mechanical shear systems with lower-emission alternatives.
- Commercial Fleet Lifecycle Management:Long-haul trucking operators in the United States prioritize casing preservation to extend tire service intervals and reduce total cost of ownership.
- Laser-Guided CNC Heads:Precision cutting tolerances below 0.5 millimeters enable higher-yield carcass recovery rates at high-volume processing facilities.
Market Restraints
- Tungsten Carbide Blade Supply Concentration:Chinese suppliers control 70% of global superhard material output, exposing Western equipment manufacturers to export restriction risks.
- REACH Chemical Compliance:ECHA substance restrictions on cobalt-based cutting fluids force European retreaders into costly formulation changes or equipment retrofits.
- Pyrolysis Substitution:Whole-tire thermal decomposition technologies bypass tread cutting entirely for certain recycling streams, capping replacement equipment demand.
Strategic Opportunities
- India Retreading Infrastructure:BIS certification requirements for commercial vehicle tires create compliance-driven equipment procurement windows at domestic retread plants.
- Predictive Blade-Wear Monitoring:IoT sensor integration with cloud-based analytics enables vendors to monetize recurring service revenue alongside hardware sales.
- Extended Producer Responsibility Frameworks:EU Green Deal circular economy mandates increase tire collection volumes and retreading economics across Germany, France, and Italy.
Industry Challenges
- CNC Programming Expertise Shortage:Retread plants struggle to recruit operators capable of calibrating multi-axis laser cutting heads for complex tread patterns.
- CE Machinery Directive Certification Timelines:Third-party conformity assessment delays average 14 months for novel water jet systems, compressing product launch windows.
- Legacy Mechanical System Integration:Hybrid facilities running 1990s-era shears face control architecture mismatches when retrofitting modern diagnostic modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Tread Cutting Machines Market |
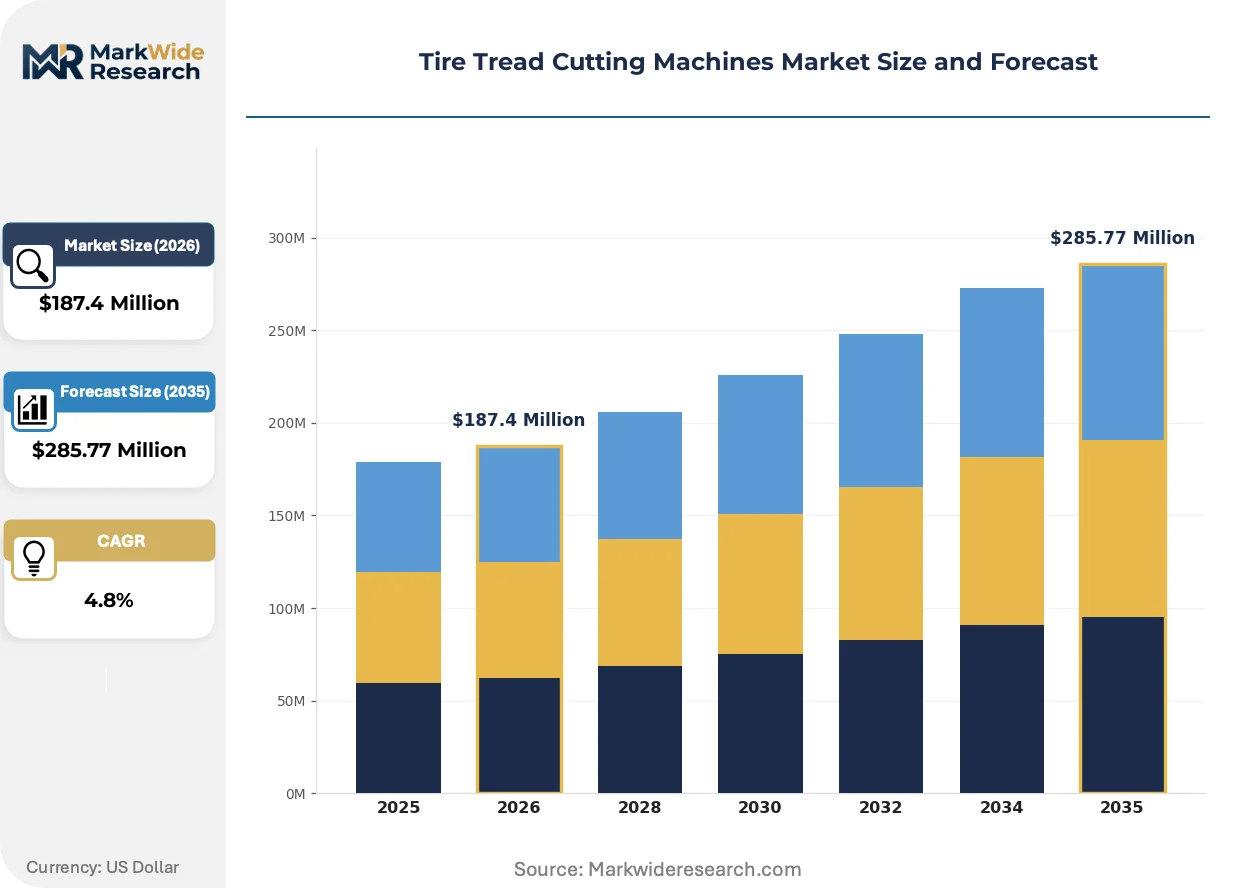
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Hybrid End User: Tire Retreaders, Manufacturing Plants, Service Centers, OEMs Technology: Water Jet, Laser, Mechanical, CNC Application: Light Vehicles, Heavy Vehicles, Agricultural Equipment, Others |
| Companies Covered | Eldan Recycling A/S, CM Shredders, Granutech-Saturn Systems, SUMAC Auto Recycling Equipment Co., Ltd., Bandit Industries, Inc., Vecoplan LLC, SSI Shredding Systems, Guilin Zhonghao Mechanical & Electrical Equipment Co Ltd, MESNAC Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Tread Cutting Machines Market Evolving Landscape
Equipment architecture is fragmenting into configurable subsystems as retreaders demand site-specific adaptations without full custom engineering.
Water jet cutting heads with abrasive garnet feed systems is modularizing across retread plant configurations. High-volume operators in Germany and the United States deploy these units as swappable tool stations on common gantry frames. The approach compresses capital deployment timelines by allowing phased capacity expansion without line shutdowns.
REACH authorization requirements for chromium(VI) compounds in hardfacing alloys are forcing cutter geometry redesigns at European manufacturers. The industrial consequence is accelerated adoption of plasma-transferred arc welding alternatives using cobalt-based matrices. Heavy vehicle retreaders face the steepest compliance costs due to larger cutter surface areas requiring protective coatings.
Service contract unbundling is separating predictive maintenance from traditional break-fix agreements. Independent retreaders in the United States now procure blade-wear analytics as standalone SaaS subscriptions rather than bundled OEM packages. The shift is most visible among multi-site fleet operators running centralized procurement functions.
Tire Tread Cutting Machines Market Segmentation
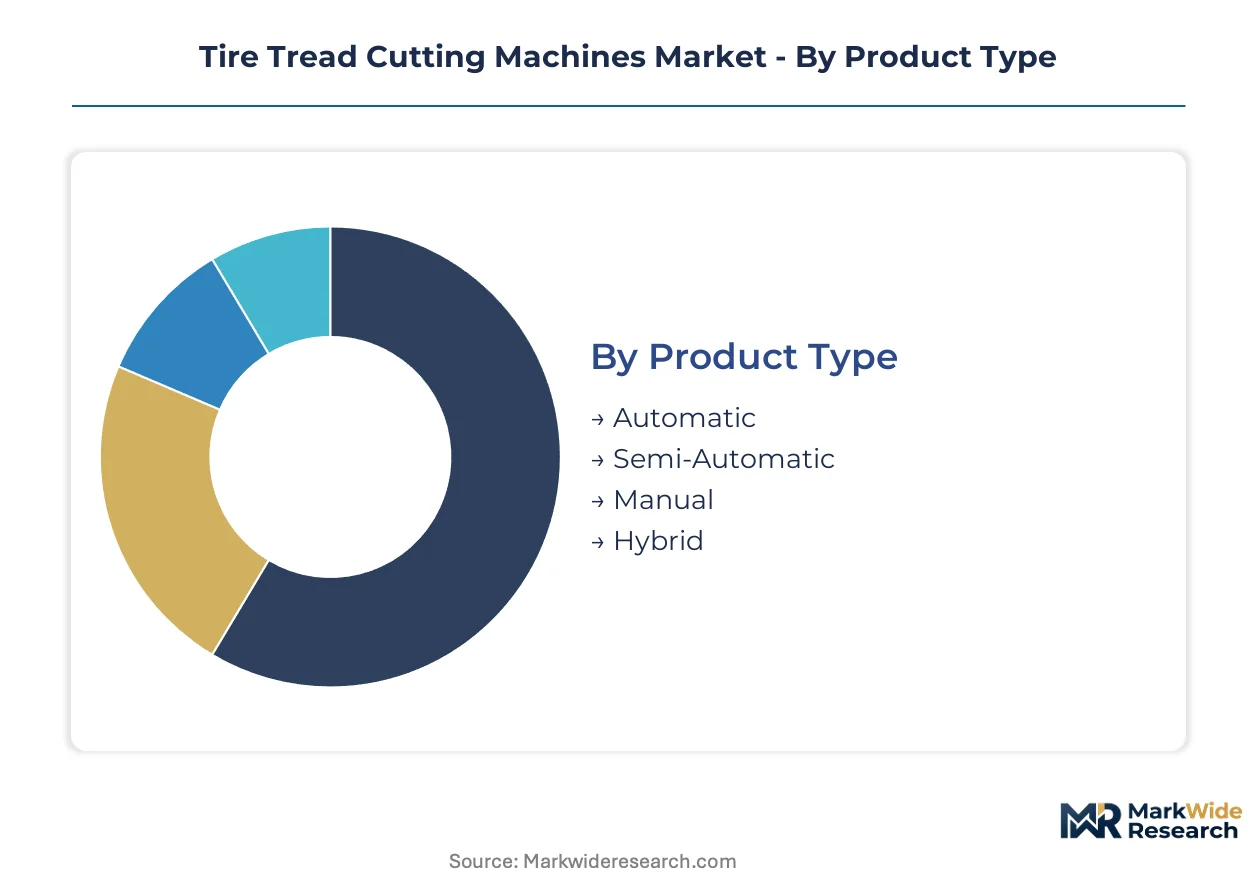
Segmentation in tire tread cutting machines determines capital allocation thresholds, compliance burdens, and service contract structures. Equipment specification varies sharply across automation tiers and cutting technologies, with certification requirements from EPA, OSHA, REACH, and CE machinery directives applying differentially by product type and end-use configuration.
Product Type:
CE machinery directives and OSHA machine guarding mandates apply most stringently to automatic systems, while manual configurations face lighter conformity assessment timelines in Europe and the United States.
- Automatic:Systems integrate multi-axis CNC heads with continuous feed mechanisms operating at throughput rates exceeding 120 casings per hour. Demand concentrates at high-volume retread plants in Germany and the United States where labor cost arbitrage justifies capital intensity. OSHA machine guarding requirements for automated shear systems compel quarterly safety audits.
- Semi-Automatic:Hybrid control architectures blend operator oversight with programmable cutting sequences, reducing calibration complexity for mid-scale retreaders. Plants in China and India favor this tier where technician training pipelines remain underdeveloped. MIIT equipment certifications in China add 6-8 weeks to procurement cycles for this category.
- Manual:Lever-actuated mechanical shears serve low-volume service centers with minimal maintenance overhead.
- Hybrid:Configurable platforms allow phased automation upgrades without full line replacement.
Leading the category by volume: Automatic systems at high-volume retread plants. Growing fastest: Hybrid configurations enabling incremental capacity expansion.
End User:
Customer procurement authority determines pricing structure and contract duration, with fleet-affiliated retreaders commanding superior service terms versus independent operators.
- Tire Retreaders:Dedicated casing processing facilities represent the core demand pool, operating cutting equipment as primary production assets. Independent retreaders in the United States prioritize predictive blade-wear monitoring bundled into multi-year service agreements. EPA emissions compliance for off-road equipment drives replacement cycles at Tier 4 final deadlines.
- Manufacturing Plants:Integrated tire producers deploy cutting systems for scrap recovery and R&D prototyping rather than commercial retreading. Facilities in Germany face REACH chemical compliance costs for cobalt-based cutting fluids that elevate operating expenditure.
- Service Centers:Mobile and fixed-site maintenance providers serve fleet customers with rapid turnaround requirements.
- OEMs:Original equipment manufacturers procure cutting systems for warranty casing recovery programs.
Retreaders dominate procurement volume. Manufacturing plants show steepest expansion trajectory as integrated producers verticalize into casing recovery.
Technology:
Capital intensity and operating cost profiles diverge sharply across thermal versus cold-cutting methodologies, with water jet systems commanding premium pricing but eliminating rubber compound degradation.
- Water Jet:Cold-cutting systems using abrasive garnet feed eliminate thermal damage to tire carcasses, preserving casing integrity for premium retread applications. German and United States operators lead adoption where precision tolerances below 0.5 millimeters justify higher capital outlay. CE machinery directive certification timelines average 14 months for novel water jet configurations.
- Laser:CNC-guided laser heads deliver sub-millimeter cutting precision for complex tread patterns on heavy vehicle casings. Demand concentrates at specialized retreaders serving long-haul trucking fleets where casing recovery rates directly impact total cost of ownership calculations.
- Mechanical:Shear-based systems using tungsten carbide blades remain prevalent at legacy facilities.
- CNC:Computer numerical control architectures enable programmable cutting paths across all tool types.
Mechanical systems retain largest installed base. Water jet technology climbs fastest as cold-cutting economics improve.
Application:
Vehicle class determines cutter geometry specifications and margin structure, with heavy vehicle applications commanding superior per-unit processing economics.
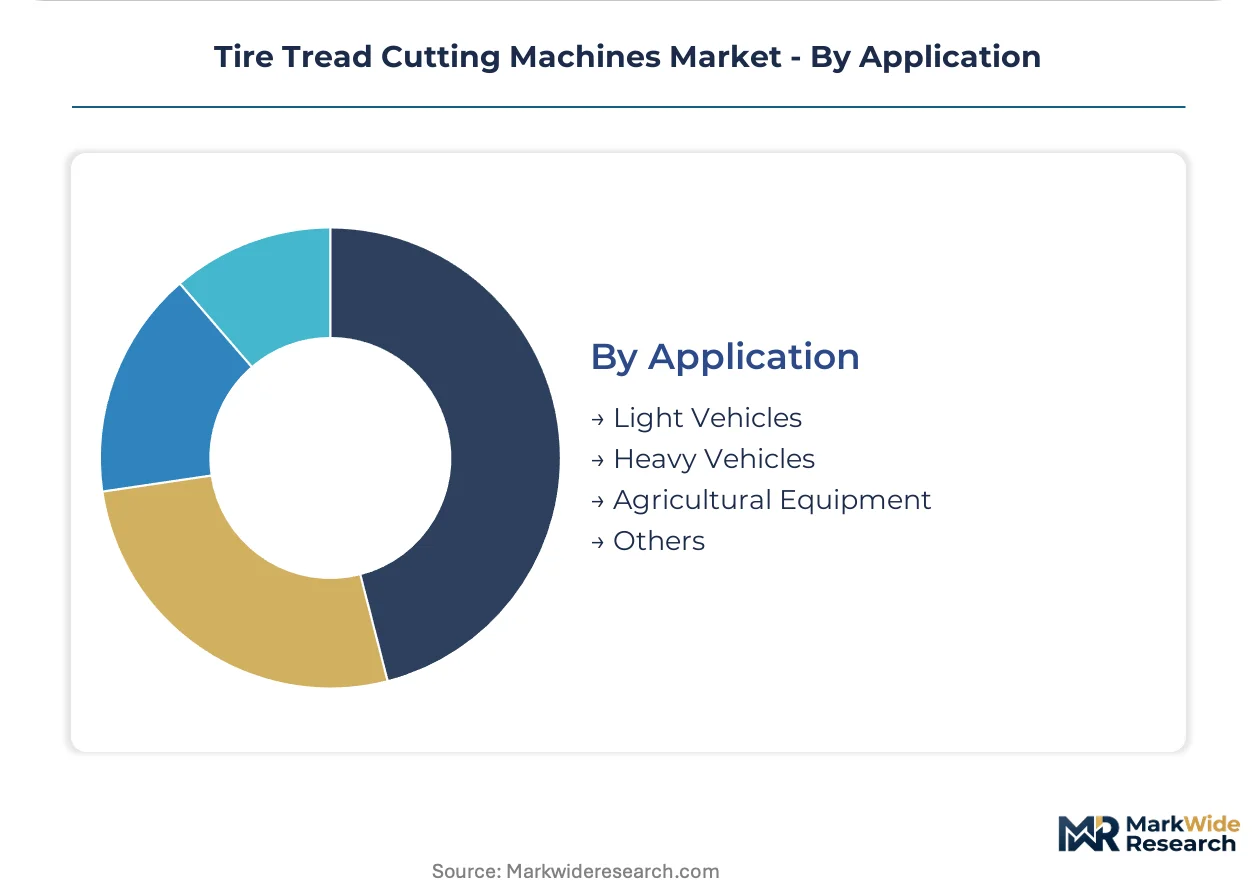
- Heavy Vehicles:Commercial truck and bus tire retreading requires larger cutter surface areas and hardened blade coatings to sever thick tread sections. Plants in the United States serving long-haul fleets prioritize casing preservation to extend service intervals. REACH authorization requirements for chromium(VI) compounds in hardfacing alloys force European retreaders into costly cutter redesigns.
- Light Vehicles:Passenger tire processing represents the highest volume application pool despite thinner margins per casing. High-throughput automatic systems dominate this segment where throughput efficiency outweighs precision requirements.
- Agricultural Equipment:Off-the-road tire cutting demands specialized configurations for oversized casings.
- Others:Industrial and specialty tire categories including aviation and mining applications.
Light vehicles process highest casing volumes. Heavy vehicle retreading delivers steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production concentrates in Germany and China while consumption tilts toward the United States and India where retreading infrastructure expansion outpaces domestic manufacturing capacity. This asymmetry shapes trade flows and localization strategies across the forecast window.
United States
Commercial fleet operators drive replacement demand as EPA Tier 4 final rules compel retreaders to retire aging mechanical shear systems. OSHA machine guarding mandates force quarterly safety audits at high-volume plants. The Ohio-Michigan industrial corridor hosts the densest concentration of retread facilities upgrading to water jet cold-cutting platforms.
Germany
Precision engineering standards and REACH chemical compliance on cobalt-based cutting fluids elevate operating costs for retreaders. CE machinery directive certification timelines stretch to 14 months for novel water jet configurations. The Ruhr Valley and Bavaria anchor equipment manufacturing clusters serving export markets across Europe.
China
MIIT industrial equipment certifications and GB standards create parallel compliance pathways for domestic and export-oriented manufacturers. The Yangtze River Delta and Pearl River Delta concentrate both cutting machine production and tire retreading capacity. Domestic retreaders favor semi-automatic configurations where technician training pipelines remain underdeveloped.
India
BIS certification requirements for commercial vehicle tires create compliance-driven procurement windows at domestic retread plants. Tamil Nadu and Maharashtra host expanding retreading infrastructure serving long-haul trucking corridors. Mid-scale operators prioritize hybrid control architectures that balance automation with operational flexibility.
Tire Tread Cutting Machines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the tire tread cutting machines market. The vendor base separates into integrated machinery builders with captive foundry capacity and specialized subsystem suppliers outsourcing fabrication to contract manufacturers. Three archetypes dominate: European precision engineering houses, North American aftermarket service integrators, and Chinese scale-oriented fabricators. Competitive moves center on predictive maintenance service contracts and modular equipment architectures that enable phased customer upgrades.
Within the European precision tier, Eldan Recycling A/S anchors long-term service retention through aftermarket maintenance contracts. CM Shredders and Granutech-Saturn Systems occupy positions in the North American market, with the latter controlling access to proprietary replacement parts channels. SUMAC Auto Recycling Equipment Co., Ltd. represents the Chinese fabrication archetype, supplying cost-competitive configurations to emerging market retreaders.
| Leading Market Players |
|---|
| Eldan Recycling A/S |
| CM Shredders |
| Granutech-Saturn Systems |
| SUMAC Auto Recycling Equipment Co., Ltd. |
| Bandit Industries, Inc. |
| Vecoplan LLC |
| SSI Shredding Systems |
| Guilin Zhonghao Mechanical & Electrical Equipment Co Ltd |
| MESNAC Co Ltd |
| Others |
Value Network & Pricing Analysis
Water jet cold-cutting platform adoption simultaneously elevates capital expenditure thresholds and concentrates procurement leverage among German and United States retreaders capable of absorbing premium equipment costs. This technology transition fragments pricing power across buyer tiers while tethering margin performance to abrasive garnet feed system availability.
Pricing Analysis
Cost-down pressure on automatic system tiers accelerates because Chinese fabricators introduce semi-automatic configurations at disruptive price points. Three-tier pricing structure across premium water jet, standard mechanical shear, and economy manual configurations stratifies by CE certification grade and bundled predictive maintenance scope. Fleet-affiliated retreaders exhibit lowest price sensitivity due to total cost of ownership calculations, while independent operators in India and China prioritize capital efficiency over precision tolerances.
Supply Chain Analysis
Single-source vulnerability sits with Chinese suppliers controlling superhard material output for tungsten carbide blade production. Manufacturing concentration spans Germany for precision engineering, China for scale fabrication, and the United States for aftermarket integration. Raw material dependencies encompass abrasive garnet deposits, cobalt-based cutting fluid formulations, and chromium(VI) compounds for hardfacing alloys. Distribution runs through authorized OEM service channels and independent aftermarket parts distributors serving legacy mechanical system operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA machine guarding mandates and EPA Tier 4 final rules erect compliance moats that favor incumbent vendors with established certification track records, raising effective barriers for unproven entrants.
For Market Incumbents: Hedge against pyrolysis substitution threats by deepening service contract penetration at fleet-affiliated retreaders. Anchor customer retention through proprietary cutter geometry lock-in and predictive blade-wear analytics. Prioritize backward integration into tungsten carbide sourcing to offset Chinese supply concentration risks. For New Entrants and Emerging Players: Laser-guided CNC head precision capabilities offer technology-first wedge positioning against legacy mechanical shear incumbents. Target mid-scale independent retreaders in India and Southeast Asia where BIS certification requirements create procurement windows. Pursue modular equipment architectures enabling phased automation upgrades without full line replacement. For Investors and Strategic Acquirers: Re-rating potential sits with European precision engineering houses given REACH authorization timelines extending competitive protection for compliant cutter designs. Long-term viability hinges on service revenue monetization rather than pure equipment sales. Monitor extended producer responsibility framework implementation across EU member states as inflection indicator for retreading economics versus shredding substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Contract Expansion | Recurring revenue streams from IoT-enabled blade-wear monitoring lock in fleet-affiliated retreaders across the Ohio-Michigan corridor. |
| CE Machinery Directive Pre-Certification Investment | Early conformity assessment completion compresses 14-month approval timelines for novel water jet configurations entering German plants. |
| Abrasive Garnet Supply Agreement | Long-term offtake contracts with Australian and Indian mineral suppliers secure cold-cutting platform production continuity. |
| Hybrid System Architecture Development | Configurable platforms enable Indian mid-scale operators to balance automation with technician training constraints. |
| REACH-Compliant Cutter Geometry Redesign | Plasma-transferred arc welding alternatives using cobalt-based matrices preserve European market access amid chromium(VI) restrictions. |
Research Methodology
Independent corroboration across retread plant engineering directors, OEM procurement teams, and aftermarket service heads underwrites the qualitative findings. Primary fieldwork encompassed maintenance directors at high-volume United States facilities, technical R&D directors at German precision engineering houses, and distribution channel partners serving legacy mechanical system operators. Secondary validation drew from EPA enforcement databases, CE marking registries, MIIT equipment certification filings, and customs trade records. Bottom-up equipment shipment tallies triangulated against top-down retreading capacity estimates.
Comparable-period anchoring to historical replacement cycle data informed projection horizon construction across automatic, semi-automatic, manual, and hybrid automation tiers. Segmentation dimensions encompassed cutting technology type, vehicle application class, end-user procurement authority, and regional regulatory cluster. CAGRs derived from installed base turnover rates and compliance-driven refresh timelines. Industry-specific inputs included OSHA audit frequency mandates, REACH authorization sunset dates, and BIS certification rollout schedules.
Several conditions sit outside the modeled scope, including unannounced pyrolysis technology breakthroughs, export restriction impositions on superhard materials, and abrupt extended producer responsibility framework revisions. Forecasts reflect documented assumptions regarding technician training pipeline development and fleet operator casing preservation preferences. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Undercarriage Systems Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Automotive Electric Vacuum Pump Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Brake Lathe Machine Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
VVT and Start-Stop Systems Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Weatherstrips Market