
 Windshield Lifters Market | 2026-2036
Windshield Lifters Market Size, Share, and Industry Trends Forecast 2026-2036
Windshield Lifters Market Analytics
Aftermarket maintenance contracts and software-enabled calibration services are broadening what suppliers monetize beyond hardware sales. Schmalz GmbH leverages its vacuum technology heritage to anchor premium positioning in automated glass handling. WOOD'S POWR-GRIP sustains brand recognition across North American repair shop channels through specialized suction-cup engineering. Dalmec S.p.A. competes on pneumatic manipulator integration for high-cycle automotive assembly environments.
Windshield lifters are material-handling devices engineered to grip, transport, and position automotive glass panels using vacuum suction, mechanical clamping, or hydraulic actuation, typically rated for loads between 50 kg and 300 kg depending on vehicle class. Their primary function is to eliminate manual lifting injuries while ensuring precise alignment during bonding or sealing operations. Electric lifters now command the fastest expansion within product type segmentation as factories phase out pneumatic infrastructure, while vacuum-based systems retain the dominant installed base due to compatibility with curved and coated glass surfaces. Among end users, automotive manufacturers represent the deepest margin pool because they specify custom integration with robotic sealing lines, whereas repair shops drive volume through standardized portable units.
Germany's KBA enforces type-approval standards for vehicle glass installation equipment used in certified repair networks, while OSHA in the United States mandates ergonomic load limits that directly specify maximum manual handling thresholds for automotive glass. The EU Machinery Directive, transposed through national regulators across member states, requires conformity assessment for all powered lifting appliances deployed in production facilities. Stakeholders must monitor how regional safety enforcement intensity affects replacement cycles and whether emerging battery-electric vehicle architectures with heavier laminated glass panels force recalibration of existing lifter capacity ratings.
Market Dynamics
Automotive OEMs are phasing out pneumatic glass-handling infrastructure in favor of electric actuation systems, forcing incumbent suppliers to retool product portfolios and recalibrate service networks around battery-powered platforms.
Growth Catalysts
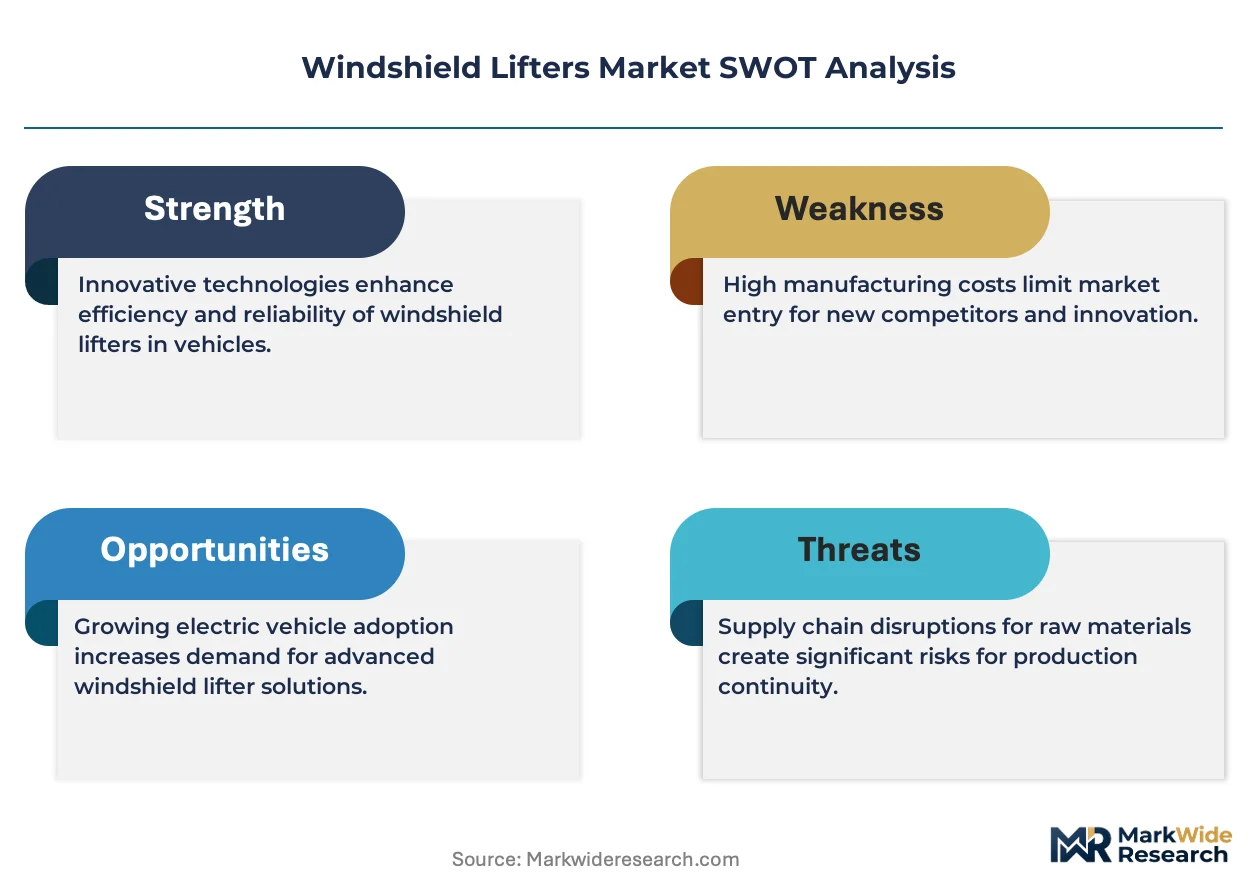
- EU Machinery Directive compliance mandates:CE marking requirements for industrial lifting machinery are tightening safety standards, compelling European automotive plants to upgrade aging pneumatic lifters with certified electric alternatives.
- Battery-electric vehicle glass weight escalation:Laminated acoustic panels and panoramic roofs on premium EVs now exceed 200 kg, creating demand for higher-capacity vacuum systems rated beyond traditional thresholds.
- Germany's automotive manufacturing corridor:Premium vehicle producers in Baden-Württemberg and Bavaria operate high-throughput windshield installation facilities that specify custom robotic integration.
Market Restraints
- Aluminum and rare-earth magnet cost volatility:Electric lifter motors depend on neodymium pricing, which fluctuates with Chinese export quotas and mining output constraints.
- Pneumatic infrastructure lock-in:Existing assembly lines in Eastern European plants carry sunk costs in compressed-air distribution that delay electric conversion timelines.
- Manual handling substitution persistence:Low-volume repair shops in price-sensitive markets continue using mechanical suction cups for jobs below 80 kg.
Strategic Opportunities
- Software-enabled calibration services:Aftermarket maintenance contracts now bundle ADAS alignment verification with hardware leases, expanding recurring revenue beyond equipment sales.
- India's PLI scheme for automotive component manufacturing:Domestic production incentives are attracting glass-handling equipment suppliers to establish local assembly for export to ASEAN markets.
- Vision-guided robotics convergence:Machine-vision integration with vacuum lifters enables real-time surface defect detection during panel positioning.
Industry Challenges
- Mechatronics technician scarcity:Electric lifter deployment requires specialists fluent in both pneumatic legacy systems and servo-drive programming, a skill combination concentrated in German and Japanese industrial training programs.
- KBA type-approval certification timelines:Germany's Federal Motor Transport Authority enforces extended validation protocols for glass installation equipment used in certified repair networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Windshield Lifters Market |
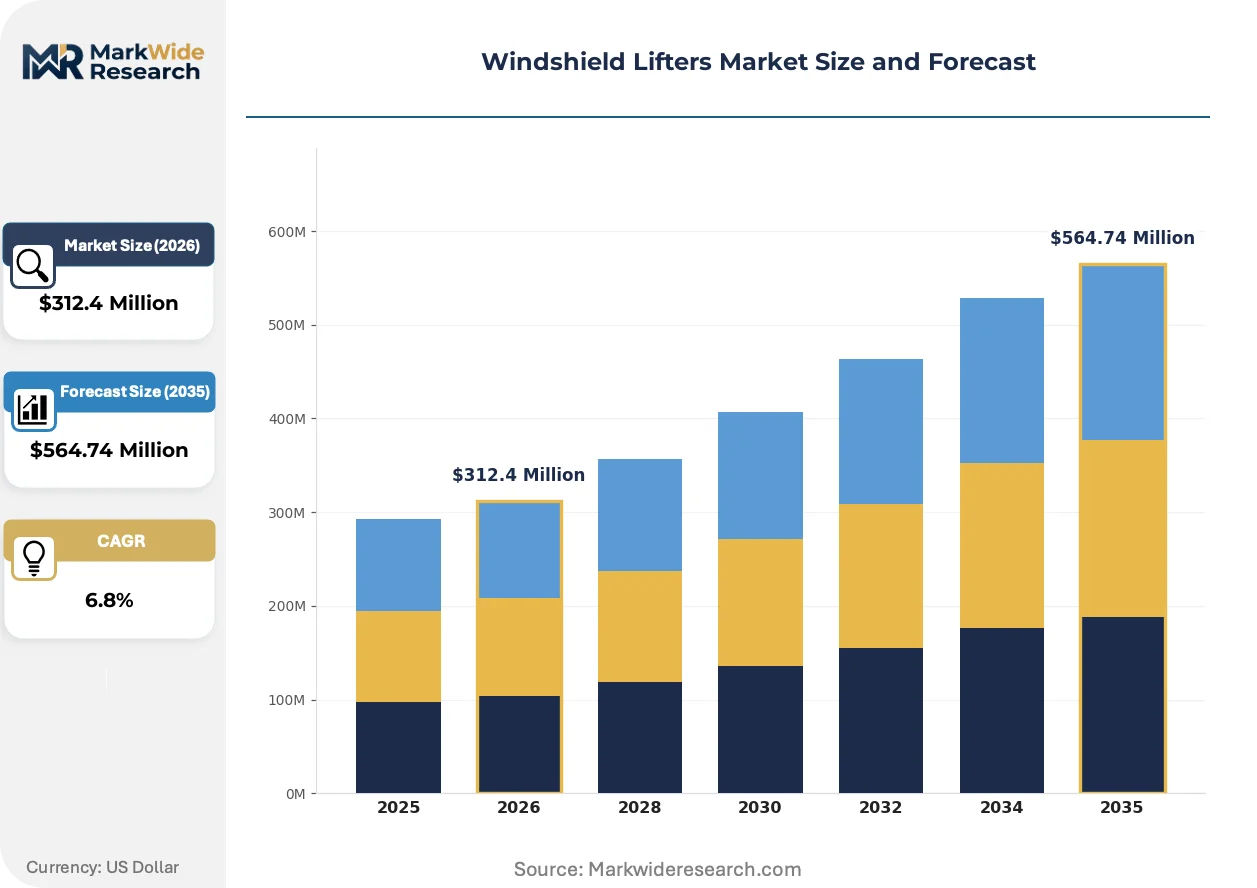
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Lifters, Electric Lifters, Hydraulic Lifters, Vacuum Lifters End User: Automotive Manufacturers, Repair Shops, Aftermarket Providers, OEMs Installation Type: Fixed Installation, Portable Installation, Semi-Permanent, Temporary Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Pannkoke Flachglastechnik GmbH, WOOD'S POWR-GRIP, Dalmec S.p.A, Lifts All AB, Anver Corp., Xinology Co., Ltd., Schmalz GmbH, TAWI AB, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Windshield Lifters Market Evolving Landscape
Active sensor integration and predictive maintenance architectures are redefining how windshield lifters communicate with factory control systems, shifting competitive advantage from mechanical reliability to data-enabled uptime guarantees.
Servo-electric vacuum lifters is converging with torque-sensing feedback loops to enable real-time grip-force adjustment on curved glass surfaces. Tier 1 automotive suppliers in Germany and Japan are specifying these systems for new EV platform launches. The technology is converging with robotic sealing lines to compress cycle times by eliminating manual alignment verification steps.
OSHA's ergonomic load limit enforcement is hardening thresholds for manual glass handling in US automotive assembly plants. The regulation now triggers mandatory powered-assist requirements for panels above 23 kg single-person limits. Final assembly operators in Michigan and Tennessee are responding by retrofitting stations with electric vacuum lifters ahead of scheduled compliance audits.
Glass supplier consolidation is compressing procurement leverage for windshield lifter OEMs. Saint-Gobain and AGC now specify approved handling equipment brands for warranty-validated installations. Tier 2 equipment vendors in North America are responding by pursuing direct certification relationships with glass manufacturers rather than automaker tiering systems.
Windshield Lifters Market Segmentation
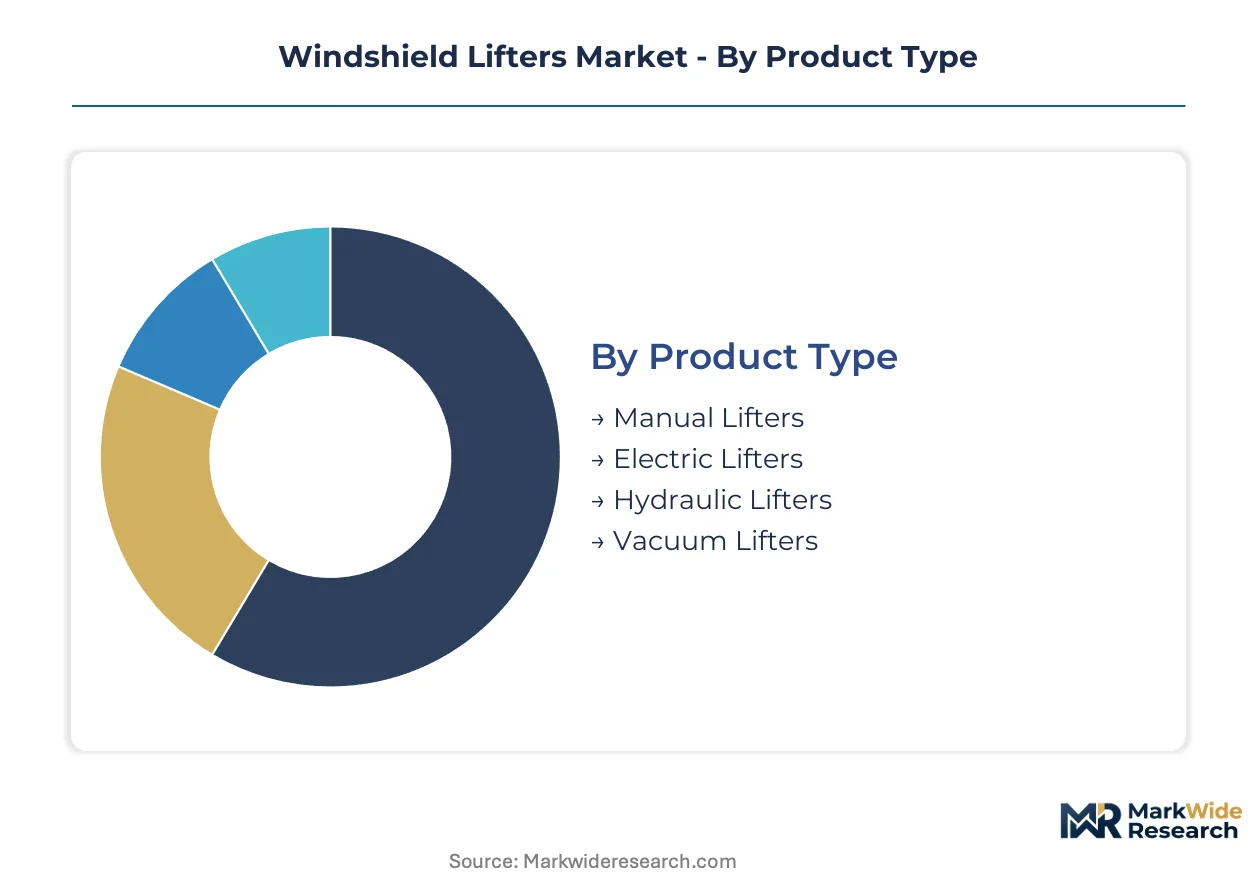
Windshield lifter segmentation reveals how procurement priorities diverge between high-volume automotive assembly and fragmented repair networks. Equipment specifications, mobility requirements, and channel economics each reshape supplier strategies across distinct buyer clusters.
Product Type:
Power source selection separates facilities with compressed-air infrastructure from those prioritizing precision control and energy efficiency.
- Manual Lifters:Mechanical suction-cup systems requiring operator muscle power for loads under 80 kg. Repair shops in price-sensitive Eastern European markets continue specifying these units to avoid capital expenditure on powered alternatives.
- Electric Lifters:Servo-driven vacuum systems with programmable grip-force modulation and battery-powered mobility. Germany's Baden-Württemberg automotive corridor specifies these for EV platforms with 200 kg+ laminated acoustic panels.
- Hydraulic Lifters:Fluid-actuated heavy-duty units rated for 300 kg industrial glass handling. Legacy installations in North American truck manufacturing persist where pneumatic conversion costs remain prohibitive.
- Vacuum Lifters:Suction-based systems dominating curved and coated glass applications through adjustable pad configurations. Retain the largest installed base due to surface compatibility advantages.
Vacuum lifters lead volumes today; electric lifters are gaining share fastest.
End User:
Integration depth and customization tolerance distinguish buyers along the value chain from certified repair networks to final assembly robotics.
- Automotive Manufacturers:Tier 1 suppliers demanding robotic sealing line integration with vision-guided positioning. Bavarian premium OEMs specify custom torque-feedback systems for panoramic roof installation cycles.
- Repair Shops:Independent service providers prioritizing portability and rapid calibration for ADAS-equipped windshields. OSHA ergonomic mandates in Michigan and Tennessee are accelerating powered-assist adoption above 23 kg thresholds.
- Aftermarket Providers:Mobile service fleets requiring lightweight battery-powered units for on-site glass replacement. KBA type-approval requirements constrain equipment selection in Germany's certified networks.
- OEMs:Original equipment manufacturers integrating lifters into vehicle assembly system packages. Specify durability ratings aligned with 10-year production line lifecycles.
Automotive manufacturers command the deepest margins; repair shops drive absolute unit volumes.
Installation Type:
Mobility requirements reflect production line permanence versus service flexibility demands across manufacturing and maintenance contexts.
- Fixed Installation:Permanently mounted overhead rail systems integrated into assembly line architecture. High-throughput facilities in Japan's Aichi prefecture deploy these for sub-60-second windshield cycle times.
- Portable Installation:Wheeled or handheld units enabling repositioning across multiple service bays. Aftermarket providers in India's emerging automotive service sector favor these for capital efficiency.
- Semi-Permanent:Floor-mounted systems with modular relocation capability for production line reconfiguration. Eastern European plants use these to accommodate model mix flexibility.
- Temporary:Short-term rental or lease arrangements for surge capacity or facility maintenance. Peak seasonal demand in collision repair networks drives utilization.
Fixed installation dominates automotive OEM procurement; portable systems show the steepest expansion trajectory in aftermarket channels.
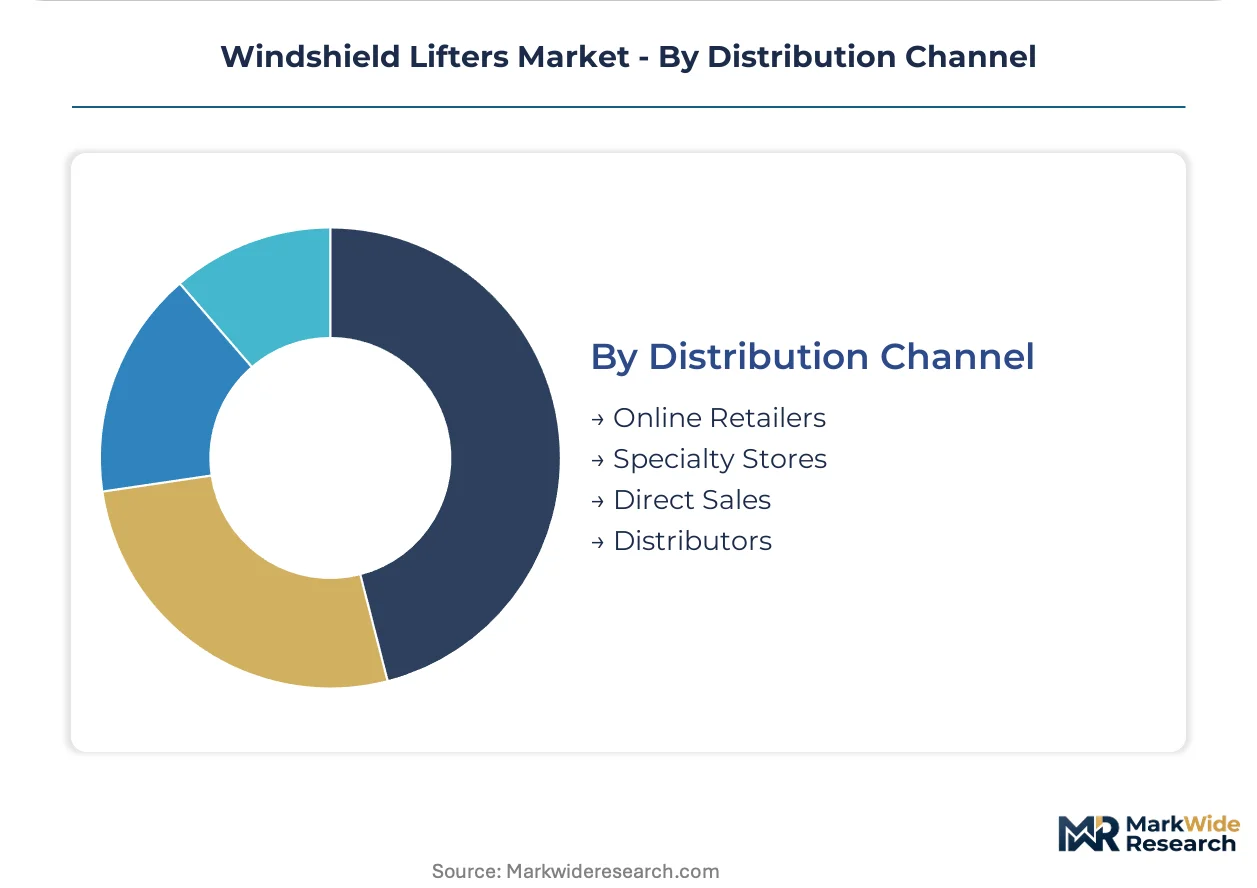
Distribution Channel:
Channel selection tracks buyer sophistication, with direct technical collaboration separating industrial purchasers from transactional retail acquisition.
- Online Retailers:E-commerce platforms serving price-transparent procurement for standardized portable units. Repair shops in North American rural markets increasingly specify equipment through digital catalogs.
- Specialty Stores:Physical distributors with demonstration capabilities and local service networks. Persist in regions where hands-on equipment evaluation precedes purchase decisions.
- Direct Sales:Manufacturer-to-OEM relationships involving engineering collaboration and custom integration. Schmalz GmbH and Dalmec S.p.A. maintain dedicated technical sales teams for Tier 1 automotive accounts.
- Distributors:Regional intermediaries stocking inventory and providing maintenance contract fulfillment. WOOD'S POWR-GRIP leverages these relationships across North American repair shop channels.
Direct sales capture the highest-value automotive manufacturer contracts; online retailers are expanding fastest among independent repair shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium-tier procurement volumes for robotic glass-handling integration, while the United States drives aftermarket equipment replacement cycles through OSHA ergonomic enforcement. China's EV production surge and India's component manufacturing incentives are reshaping regional supply footprints.
Germany
Baden-Württemberg and Bavaria host high-throughput windshield installation facilities serving premium vehicle producers. KBA type-approval standards enforce extended validation protocols for certified repair network equipment. Stuttgart's automotive manufacturing corridor specifies custom torque-feedback systems for panoramic roof installation cycles on battery-electric platforms.
United States
Michigan and Tennessee final assembly operators retrofit stations with electric vacuum lifters ahead of OSHA compliance audits. The agency's ergonomic load limits now mandate powered-assist for panels above 23 kg single-person thresholds. Detroit's automotive cluster drives replacement demand as legacy pneumatic infrastructure phases out.
China
Yangtze River Delta and Pearl River Delta EV manufacturers specify higher-capacity vacuum systems for laminated acoustic panels exceeding 200 kg. MIIT industrial equipment standards govern powered lifting appliance conformity in production facilities. Shanghai's automotive manufacturing base accelerates servo-electric adoption for new energy vehicle platform launches.
Japan
Aichi prefecture facilities deploy fixed overhead rail systems for sub-60-second windshield cycle times. METI industrial machinery directives align with ISO standards for automated material handling equipment. Nagoya's automotive manufacturing concentration sustains demand for precision-integrated glass positioning systems.
India
Maharashtra and Tamil Nadu component manufacturing zones attract glass-handling equipment suppliers establishing local assembly. PLI scheme incentives target domestic production for ASEAN export markets. Chennai's emerging automotive service sector favors portable installation units for capital-efficient aftermarket deployment.
Windshield Lifters Market Competitive Landscape
Top-tier vendors anchor high-value automotive OEM contracts, while mid-scale specialists populate aftermarket repair channels. The vendor base stratifies across three tiers: integrated system suppliers with robotic sealing line partnerships, pneumatic heritage firms retooling for electric platforms, and portable equipment fabricators serving price-sensitive service networks. Dominant competitive moves include portfolio diversification into software-enabled calibration services and geographic expansion through India's PLI-attracted assembly facilities.
Within the integrated system tier, Schmalz GmbH and Dalmec S.p.A. exemplify European engineering-led positioning for Tier 1 automotive accounts. WOOD'S POWR-GRIP occupies a position among North American suction-cup specialists sustaining brand recognition across repair shop distribution channels. These three entities represent distinct archetypes: German vacuum technology heritage, Italian pneumatic manipulator integration, and US aftermarket channel penetration.
| Leading Market Players |
|---|
| Pannkoke Flachglastechnik GmbH |
| WOOD'S POWR-GRIP |
| Dalmec S.p.A |
| Lifts All AB |
| Anver Corp. |
| Xinology Co., Ltd. |
| Schmalz GmbH |
| TAWI AB |
| Denso Corporation |
| Others |
Value Network & Pricing Analysis
Neodymium magnet feedstock flows from Chinese mining operations through Tier 1 motor suppliers to electric lifter assemblers, with price volatility in rare-earth markets cascading through three-tier equipment pricing stratified by automation grade and CE certification tier.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for servo-electric vacuum systems. Three-tier pricing structure across premium, standard, and economy levels separates robotic-integrated OEM contracts from portable repair shop units. Price differentiation stems from KBA type-approval certification and software-enabled calibration bundling. Cost compression in the economy tier is intensifying because manual lifter substitution persists in Eastern European aftermarket channels. Independent repair shops exhibit the highest price sensitivity, while German automotive OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
Vacuum pump and servo motor supply rests on German, Japanese, and Chinese precision component manufacturers. Raw material dependencies include neodymium-iron-boron magnets, aluminum structural extrusions, and specialized pneumatic seals. Single-source vulnerability concentrates in rare-earth magnet refining capacity. Distribution runs through direct technical sales for automotive OEM accounts and regional distributor networks for aftermarket repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Windshield lifters constitute a late-cycle quality story as battery-electric vehicle platforms drive specification upgrades toward 200 kg+ capacity ratings with integrated ADAS calibration capabilities.
For Market Incumbents: Acquire software calibration service capabilities to anchor recurring revenue streams beyond hardware cycles. Defensive consolidation should prioritize pneumatic-to-electric retrofit expertise as Eastern European plants delay infrastructure conversion. Capacity addition in India's PLI-attracted manufacturing zones offers geographic hedge against Chinese rare-earth supply concentration. Certification investment in KBA and OSHA compliance protocols preserves premium tier access. For New Entrants and Emerging Players: Vision-guided torque feedback systems offer technology-first wedge into the robotic sealing line integration segment. India's emerging automotive service sector presents the most penetrable geography for portable electric lifter deployment. Battery-powered mobility for on-site glass replacement represents the optimal go-to-market angle for aftermarket provider channels. For Investors and Strategic Acquirers: Consolidation pressure builds where pneumatic heritage firms lack electric platform engineering depth and service network coverage. Long-term viability favors suppliers with backward integration into vacuum technology IP and software-defined maintenance architectures. Acquisition target archetype: mid-scale European specialists with CE marking credibility and underdeveloped Asian distribution. Watch ADAS windshield penetration rates as inflection indicator for calibration service attach rates.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Platform Migration | Phasing out pneumatic infrastructure aligns with EU Machinery Directive compliance mandates. |
| Software-Enabled Calibration Services | ADAS alignment verification bundling expands recurring revenue beyond equipment sales. |
| India PLI Scheme Manufacturing Footprint | Domestic assembly for ASEAN export markets reduces tariff exposure and logistics costs. |
| Vision-Guided Robotics Integration | Machine-vision convergence enables real-time defect detection during panel positioning. |
| Rare-Earth Magnet Supply Diversification | Alternative sourcing from Australian and Vietnamese deposits mitigates Chinese quota volatility. |
Research Methodology
Multiple input streams — primary interviews with Tier 1 supplier procurement teams and aftermarket service heads, secondary validation through SEC filings and automotive production databases, and technical specification analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement encompassed OEM platform engineers, glass manufacturer handling equipment specialists, and pneumatic-to-electric conversion contractors. Secondary sources included IHS Markit vehicle registration data, KBA type-approval registries, and OSHA ergonomic enforcement documentation.
Historical shipment patterns were cross-referenced against panel-based industry expert assessments to model volume trajectories across the projection horizon. Segmentation dimensions encompassed power source architecture, end-user integration depth, installation mobility requirements, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized adoption curves, with specific weighting applied to EV platform glass weight escalation and CE marking replacement cycle timing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth commodity volatility and mechatronics technician training pipeline constraints. Forecasts reflect documented assumptions regarding OEM electric conversion timelines and aftermarket ADAS penetration curves. A small set of named triggers — OSHA enforcement intensity, KBA certification backlog duration, and Chinese export quota policy shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Carbon Canister Market
Automotive Parts
Italy Passenger Vehicles Lubricants Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Canada Automotive Parts Die Casting Market
Automotive Parts
Automotive Air Flow Meter Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Automotive AC Compressor Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Automotive Paint Robots Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Tow Bar Market
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Europe Roll Forming Body in White Market