
 Global Automotive Cup Holder Market | 2026-2036
Global Automotive Cup Holder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Cup Holder Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is restructuring material procurement for interior components, favoring suppliers with transparent supply chains. Faurecia leverages its expertise in sustainable materials to meet OEM requirements for recycled content. Lear Corporation differentiates through integrated interior systems that incorporate multi-functional holders. Magna International sustains its market position through its extensive global manufacturing footprint.
Automotive cup holders are vehicle interior components designed to securely store beverage containers. These devices often feature spring-loaded tabs or adjustable grips to accommodate varying container diameters and prevent spills during vehicle motion. While fixed cup holders remain the volume standard, demand for multi-functional and heated cup holders is rising in premium passenger vehicles. Plastic remains the dominant material due to cost and moldability, but aluminum and stainless steel are gaining share in luxury applications.
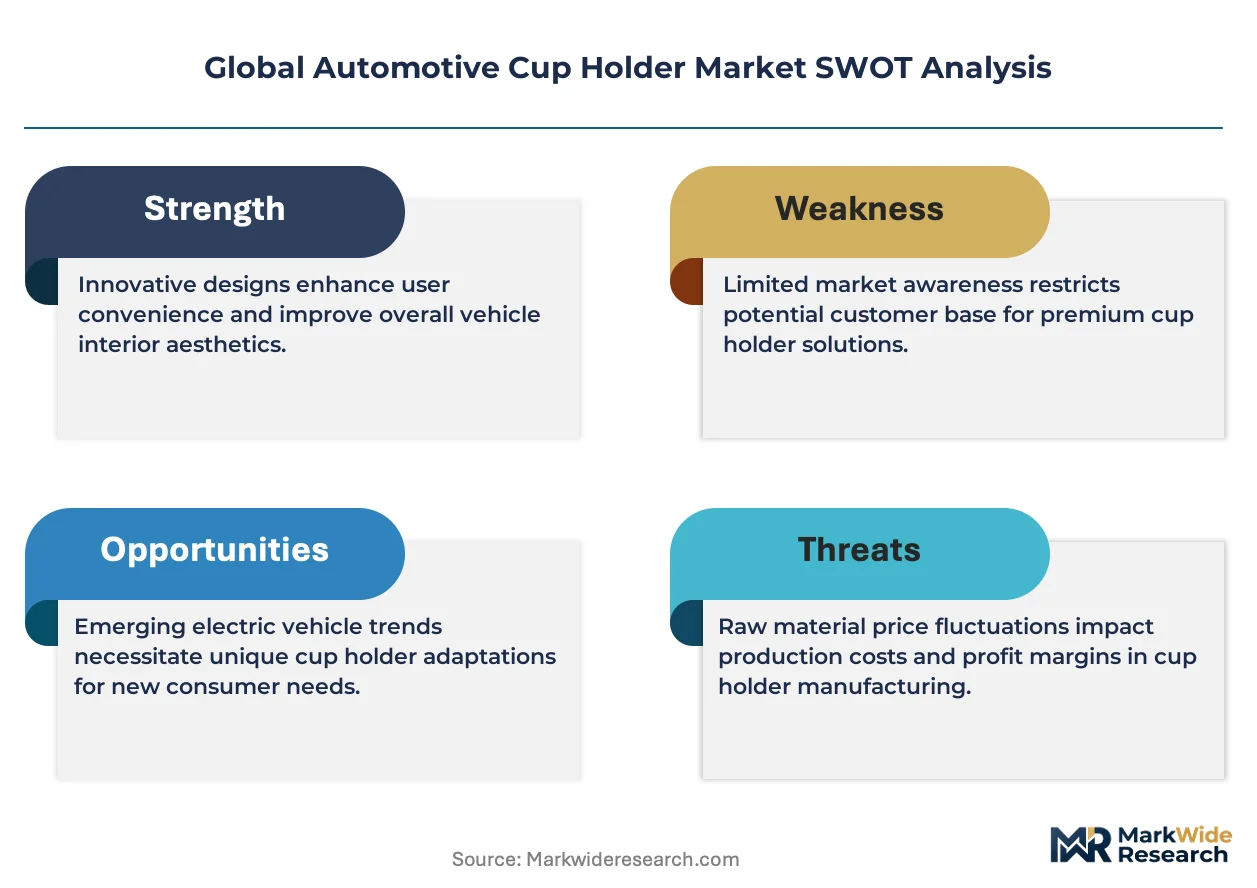
Product design must adhere to safety and material standards set by bodies like the US NHTSA for crash performance and Europe's REACH regulation for chemical content. In China, GB standards dictate material properties and durability for all automotive components. These regulations influence material selection and testing protocols for suppliers. Stakeholders must now decide how to balance cost-effective production with the rising investment required for smart, feature-rich holder designs.
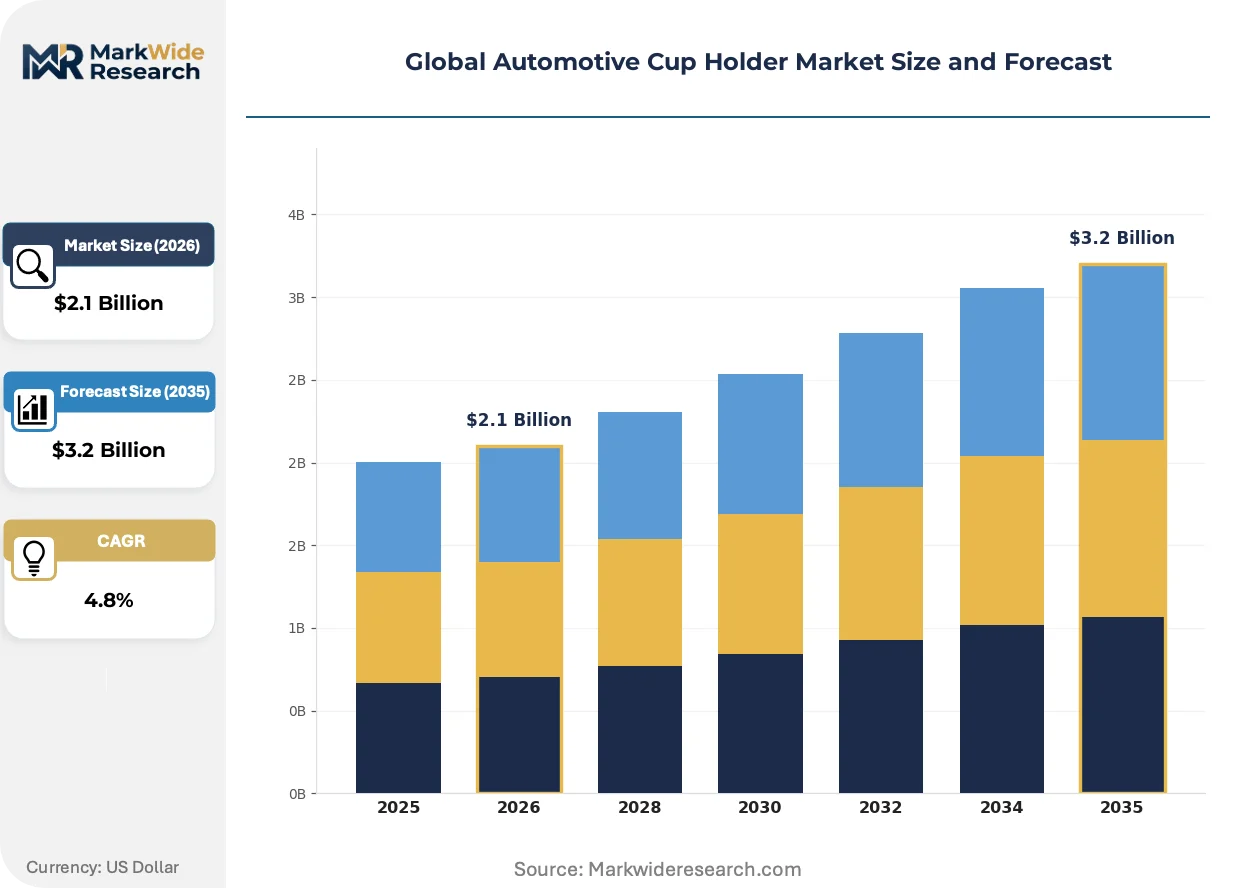
Market Dynamics
The convergence of electric vehicle interior design philosophy and circular economy regulations is the central force reshaping the automotive cup holder market. This shifts the component's value proposition from a simple commodity to a key element of brand differentiation and sustainability compliance for original equipment manufacturers.
Growth Catalysts
- Electric Vehicle Adoption:The rapid expansion of the EV segment, where cabin design and user experience are primary differentiators, creates strong demand for advanced, feature-rich cup holders that complement modern interiors.
- Sustainable Material Mandates:Regulatory frameworks like the EU Green Deal and its associated directives compel automakers to increase the use of recycled and bio-based plastics, creating a direct pull for innovative polymer formulations in interior components.
- Demand Concentration in China:China's status as the world's largest vehicle production hub and leading EV market creates a massive, concentrated source of demand for both standard and premium cup holder configurations.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of engineering-grade polymers and metals like aluminum directly impact the manufacturing cost base, squeezing margins, particularly for suppliers of more advanced, material-intensive designs.
- Technical Integration Complexity:Integrating features such as heating, cooling, or smart device charging into a compact, durable, and cost-effective unit that meets stringent automotive safety and electromagnetic compatibility standards remains a significant engineering hurdle.
- Divergent Global Standards:Conflicting requirements between regulations like the US NHTSA's crash safety standards and Europe's REACH chemical substance rules complicate product design and necessitate expensive, region-specific testing and validation protocols.
Strategic Opportunities
- Multi-Functional Module Integration:The convergence of electronics and interior components enables the development of integrated modules that combine cup holding with wireless charging, ambient lighting, and biometric sensors.
- Solutions for Autonomous Mobility:The emergence of autonomous vehicle concepts with reconfigurable interiors creates white-space for modular, movable, and adaptable cup holder systems that cater to flexible cabin layouts for work or leisure.
- Bio-Composite Commercialization:There is a clear opportunity for material suppliers to commercialize new bio-based polymers and natural fiber composites that satisfy both OEM sustainability goals and automotive-grade performance criteria.
Industry Challenges
- Software and Electronics Integration:Ensuring the seamless functional integration of smart cup holders with a vehicle's core electrical architecture and infotainment systems presents a significant software and hardware engineering challenge for traditional component suppliers.
- High Capital Investment:The shift toward complex, feature-rich holders and new sustainable materials necessitates substantial capital expenditure in advanced molding machinery, assembly automation, and cleanroom facilities for electronics integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Cup Holder Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Cup Holders, Fixed Cup Holders, Foldable Cup Holders, Multi-functional Holders, Heated Cup Holders Material: Plastic, Stainless Steel, Aluminum, Silicone, Wood Application: Passenger Vehicles, Commercial Vehicles, Recreational Vehicles, Electric Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Dealerships |
| Companies Covered | Magna International, Faurecia, Continental AG, Lear Corporation, Denso Corporation, Toyota Boshoku Corporation, Gentex Corporation, Aisin Seiki, OPmobility SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Cup Holder Market Strategic Shifts & Innovations
Component functionality is evolving beyond simple beverage retention toward integrated user-experience systems. This transformation is driven by technological advancements in materials and electronics, new regulatory pressures on sustainability, and a fundamental shift in how automakers source and integrate interior systems.
Technology and Product Evolution
Embedded electronics for active thermal management and smart notifications define the next generation of product design. The premium passenger vehicle and EV segments are the primary early adopters of these heated and cooled systems. The integration of active features is rewriting the cup holder's function from a passive storage accessory to an interactive element within the vehicle's broader comfort and user experience ecosystem.
Regulatory and Policy Shifts
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a pivotal policy shift. This regulation forces OEMs and their suppliers to provide transparent, audited data on supply chain sustainability and material circularity. Interior component manufacturers are now compelled to invest heavily in material traceability and life-cycle assessment capabilities to secure and maintain business with automakers selling into the EU market.
Demand-Side and Behavioral Shifts
Automotive OEMs are increasingly sourcing complete, pre-integrated interior modules rather than procuring discrete components. This procurement model disrupts the market by favoring large, Tier-1 suppliers capable of delivering entire center consoles or cockpit systems, which can marginalize smaller specialists. The trend is most visible within the global electric vehicle sector, where simplified assembly and accelerated speed-to-market are decisive competitive factors.
Global Automotive Cup Holder Market Segmentation
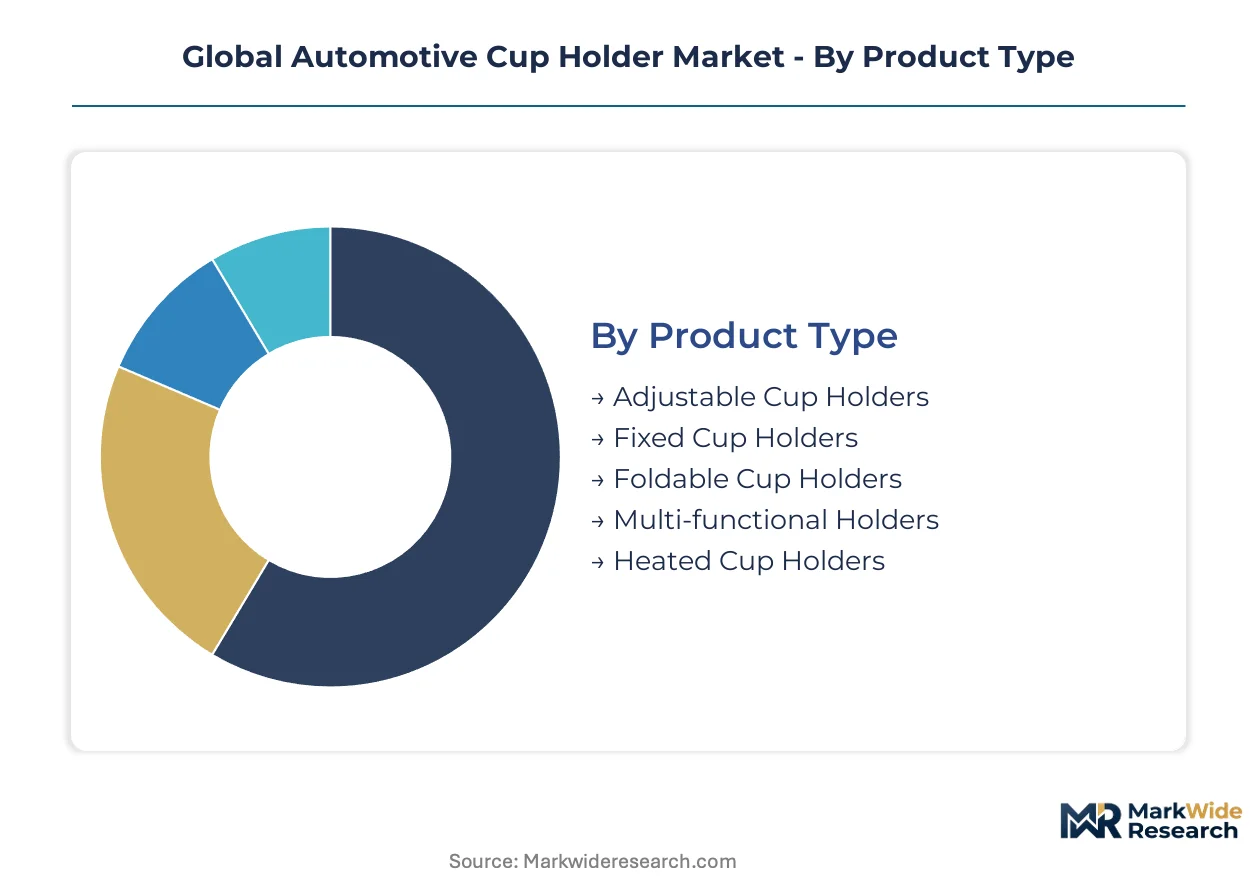
Segmentation provides a granular view of the global automotive cup holder market, revealing how product types, materials, applications, and end-users shape demand. This analysis highlights distinct value propositions and growth trajectories across various market dimensions.
Product Type:
The product type segmentation delineates the market from basic volume solutions to advanced premium offerings, reflecting diverse consumer preferences and vehicle class requirements.
- Heated Cup Holders:These units actively maintain beverage temperature, often incorporating thermoelectric elements for both heating and cooling functions. Demand is particularly strong in premium passenger vehicles and luxury electric vehicles, driven by enhanced user comfort expectations.
- Multi-functional Holders:These advanced designs integrate features beyond simple beverage retention, such as wireless charging pads, ambient lighting, or biometric sensors. Their adoption is accelerating in autonomous vehicle concepts and high-end EVs, where cabin versatility is paramount.
- Fixed Cup Holders:Permanently mounted structures provide basic beverage storage, representing the foundational and highest volume segment.
- Adjustable Cup Holders:These holders feature movable components to secure various container sizes, enhancing versatility for consumers.
- Foldable Cup Holders:Designs that retract or fold away when not in use optimize interior space in smaller vehicles or multi-purpose cabins.
Today's leader: Fixed Cup Holders. Tomorrow's challenger: Multi-functional Holders.
Material:
Material choices for automotive cup holders span a spectrum from cost-effective polymers to high-end metals, influencing both aesthetic appeal and durability across vehicle segments.
- Plastic:Polypropylene and ABS plastics dominate this segment due to their excellent moldability, low cost, and sufficient strength for standard applications. High volume demand concentrates in entry-level and mid-range passenger vehicles globally, driven by manufacturing efficiency.
- Aluminum:Lightweight and corrosion-resistant, aluminum offers a premium aesthetic and improved thermal conductivity for advanced systems. Its adoption is increasing in luxury vehicle interiors and performance-oriented EVs, where material sophistication is a brand differentiator.
- Stainless Steel:Used for its robust durability and sleek appearance, stainless steel finds application in select premium and heavy-duty vehicle interiors.
- Silicone:Flexible and non-slip, silicone components often serve as inserts or liners, improving grip and reducing rattling.
- Wood:Primarily featured in ultra-luxury and bespoke vehicle interiors, wood provides an exclusive, artisanal finish.
The market is witnessing a material shift towards sustainable plastics and bio-composites, driven by regulatory pressures like the EU Green Deal.
Application:
The application segment differentiates cup holder requirements based on vehicle type and intended usage, from daily commuting to specialized transport needs.
- Electric Vehicles:EVs often feature unique interior layouts and prioritize advanced cabin technology, creating specific demand for smart and integrated cup holder solutions. This segment represents the fastest-growing trajectory, particularly in China and Germany, reflecting rapid EV adoption.
- Passenger Vehicles:This broad category includes sedans, SUVs, and hatchbacks, forming the largest volume segment for both fixed and adjustable cup holders. Demand for these vehicles remains consistently high across mature markets like the US and Japan.
- Commercial Vehicles:Durability and practicality are paramount for cup holders in trucks, vans, and buses, often requiring robust, easy-to-clean designs.
- Recreational Vehicles:RV interiors demand versatile and secure cup holders that can withstand motion and provide convenience for extended travel.
Innovation in cup holder design is heavily influenced by the evolving cabin ergonomics within electric and autonomous vehicle platforms.
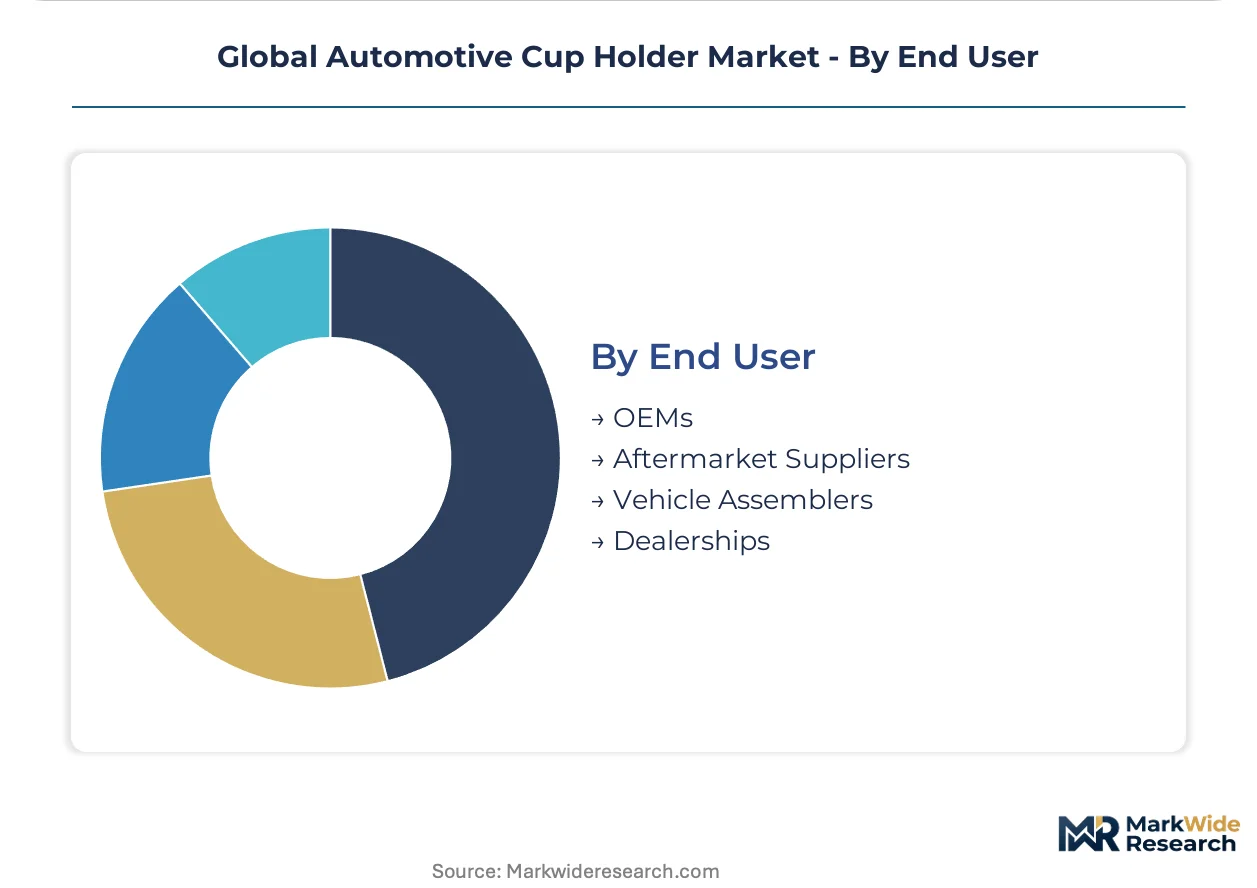
End User:
The end-user segmentation clarifies the primary procurement channels and supply chain dynamics for automotive cup holders, from vehicle manufacturing to post-sale customization.
- OEMs:Original Equipment Manufacturers integrate cup holders directly into new vehicle designs, prioritizing cost-efficiency, safety compliance, and aesthetic integration with the overall interior. This channel accounts for the vast majority of volume, especially in large manufacturing hubs like Germany and South Korea.
- Aftermarket Suppliers:These entities provide replacement, upgrade, or accessory cup holders, catering to consumer demands for customization and added functionality. The aftermarket thrives on product innovation and accessibility, particularly in the US market.
- Vehicle Assemblers:Assemblers procure components for final vehicle construction, often working closely with Tier-1 suppliers for integrated interior modules.
- Dealerships:Dealerships primarily offer branded accessories and replacement parts, serving as a direct point of sale for vehicle owners.
OEMs dictate fundamental design and material specifications, while aftermarket channels drive product diversification and feature enhancements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive cup holder manufacturing initially scaled with the mass production of vehicles in industrialized nations. The component's evolution now aligns with advanced vehicle design and global supply chains. This market's regional dynamics reflect the geographic concentration of major automotive production and electric vehicle adoption.
China
China's vast automotive production base and rapid electric vehicle adoption create immense demand for cup holders. GB standards mandate rigorous material properties and durability for all automotive components. Shanghai's automotive manufacturing cluster actively integrates advanced cup holder designs into new EV platforms.
Germany
Germany's focus on premium passenger vehicles and luxury electric vehicles generates strong demand for sophisticated cup holder systems. The EU Green Deal and CSRD compel manufacturers to adopt sustainable materials and transparent supply chains. Stuttgart's engineering hubs prioritize integrating advanced thermal management and smart features into interior components.
United States
United States demand stems from its large passenger vehicle market and expanding electric vehicle segment. NHTSA regulations dictate stringent safety and crash performance standards for interior components. Michigan's automotive manufacturing centers prioritize robust and versatile cup holder solutions for various vehicle platforms.
Japan
Japanese automotive manufacturers prioritize compact and efficient interior designs, influencing cup holder development. JIS standards ensure material properties and testing protocols meet stringent quality requirements. Toyota City's extensive automotive industry drives demand for durable and space-saving cup holder solutions across its vehicle lines.
South Korea
South Korea's robust electric vehicle market and emphasis on integrated cabin technology create specific demand for advanced cup holders. National automotive regulations influence material selection and design for interior components. Ulsan's major automotive production facilities focus on delivering high-volume, technologically advanced cup holder systems for global markets.
Global Automotive Cup Holder Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the automotive cup holder market. This market exhibits a tiered structure, with large Tier-1 suppliers dominating OEM procurement. Strategic archetypes include integrated system providers, specialized component manufacturers, and material innovators. Companies pursue geographic expansion and portfolio diversification to secure market share.
At the scale-driven end of the market, Magna International, a Canadian-based multinational, exemplifies extensive global manufacturing footprints and diversified automotive component offerings. French-based Faurecia, another Tier-1 giant, represents expertise in sustainable materials and integrated interior systems. Lear Corporation, a US-based entity, occupies a position focused on delivering complete seating and E-systems, where multi-functional cup holders are integrated elements. These companies anchor the supply chain for major automotive OEMs.
| Leading Market Players |
|---|
| Magna International |
| Faurecia |
| Continental AG |
| Lear Corporation |
| Denso Corporation |
| Toyota Boshoku Corporation |
| Gentex Corporation |
| Aisin Seiki |
| OPmobility SE |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and its Corporate Sustainability Reporting Directive (CSRD) gate access to qualified automotive suppliers, compelling investment in sustainable materials and justifying premium-tier pricing for compliant components. This regulatory pressure reshapes procurement for interior systems.
Pricing Analysis
Contract-based long-term offtake agreements define the dominant pricing model for automotive cup holders. Price differentiation stems from material innovation, complex feature integration, and stringent safety certifications like US NHTSA and China's GB standards. Upward pricing pressure arises from the substantial R&D required for smart features and sustainable material development. While OEMs for basic fixed holders remain highly price-sensitive, luxury EV manufacturers demonstrate lower sensitivity for advanced, feature-rich units.
Supply Chain Analysis
Engineering-grade polymer and aluminum supply primarily rests on producers concentrated in China, Germany, and South Korea. These regions also provide critical electronic modules for advanced cup holder systems. A significant supply chain risk involves input cost volatility, directly impacting manufacturing margins. Distribution predominantly runs through a direct-to-OEM model, with Tier-1 suppliers integrating components into larger interior modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive cup holder market functions as a stable compounder, with sustained growth driven by the continuous expansion of the electric vehicle segment. This segment prioritizes advanced interior designs and integrated user experiences.
For Market Incumbents: Deepen R&D investment into bio-composites and advanced sustainable plastics to meet evolving EU Green Deal and CSRD mandates. Expand global manufacturing footprints, particularly in China and Germany, to mitigate supply chain disruptions and serve major EV production hubs. Prioritize investment in advanced molding machinery and electronics integration capabilities to counter technical integration complexity. Secure certifications for new materials and smart features to maintain competitive advantage.
For New Entrants and Emerging Players: Autonomous mobility developers represent an underserved buyer archetype, seeking flexible interior solutions. Target white-space opportunities in modular, movable, and adaptable cup holder systems for reconfigurable cabin layouts. Niche luxury EV startups in Germany and the US offer penetrable segments for design-led innovation and rapid prototyping. Focus on commercializing bio-based polymers to align with sustainability goals of these forward-thinking OEMs.
For Investors and Strategic Acquirers: Roll-up economics work for Tier-1 suppliers seeking to consolidate specialized capabilities because of the market's fragmented innovation landscape. The long-term viability, spanning a 5-10 year window, is underpinned by sustained electric vehicle growth and increasing demand for feature-rich interiors. Identify acquisition targets among specialized component manufacturers possessing material science IP or advanced electronics integration expertise. Successful commercialization of bio-composites by smaller innovators serves as a key inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Manufacturing Footprint in China | This move addresses the concentrated demand from China's dominant vehicle production and EV adoption. |
| Invest in Sustainable Material R&D | Meeting EU Green Deal and CSRD mandates requires innovative bio-based plastics and recycled content. |
| Develop Integrated Electronics Modules | Enables active thermal management and smart features critical for premium EV user experience. |
| Commercialize Modular Cup Holder Systems | Provides adaptable interior solutions for emerging autonomous vehicle concepts and flexible cabins. |
| Pursue Advanced Safety Certifications | Ensures compliance with US NHTSA and China GB standards, securing market access and OEM trust. |
Research Approach
Multiple input streams—primary interviews, secondary data, and proprietary databases—were reconciled to construct a robust market view. Primary interviews engaged OEM procurement managers, Tier-1 R&D leads, material suppliers, and aftermarket distributors across key regions. Secondary validation utilized vehicle production databases, IHS Markit registration data, SEC 10-K filings, and regulatory reports from NHTSA and REACH. A bottom-up and top-down triangulation approach ensured data consistency.
Data-stream reconciliation established the analytical framework for volume and value outputs across the analysis window. Segmentation dimensions modeled included product type, material, application, end-user, and regional production clusters. Compound annual growth rates were derived from historical trends, market drivers, and expert consensus. Key industry-specific forecast inputs included electric vehicle adoption rates and regulatory compliance costs for sustainable materials.
Inputs from market reports and company filings were available through the study window; gaps in rapidly evolving material science and nascent smart feature adoption introduce uncertainty bands. Forecasts reflect assumptions concerning future geopolitical shifts and raw material price volatility. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Slack Adjuster Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
Automotive Washer System Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
South Africa Electric Power Steering Market
Automotive Parts
Germany Automotive Parts Die Casting Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Engine Oil Market
Automotive Parts
Wiper Blade Market