
 South America Automotive Engine Oils Market | 2026-2036
South America Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
South America Automotive Engine Oils Market Analytics
API SP and ILSAC GF-6 lubricant specifications is tilting formulation chemistry toward lower-viscosity grades with enhanced deposit control. Petrobras leverages captive refinery access to anchor supply chains across Brazilian distribution networks. ExxonMobil competes through technology leadership in synthetic base stock production for high-performance segments. Royal Dutch Shell Plc dominates premium branding through channel control at major service station networks.
South America automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines, typically meeting SAE viscosity grades ranging from 0W-20 to 15W-50 and API service categories. Their primary commercial purpose is to extend engine operational life while maintaining fuel economy compliance under varied climatic and duty-cycle conditions. Synthetic formulations lead margin pools due to extended drain intervals and OEM fill specifications, while mineral oils sustain volume leadership in price-sensitive aftermarket segments. Passenger vehicles anchor application demand, though commercial vehicle fleets generate higher per-unit lubricant consumption with stricter maintenance protocols.
Brazil's ANP regulates fuel and lubricant quality standards, while Argentina's Secretaría de Energía enforces comparable product specifications; both frameworks mandate additive disclosure and performance testing that shape importer compliance costs. REACH-aligned chemical restrictions through Mercosur technical committees are forcing reformulation of zinc dialkyldithiophosphate and other conventional anti-wear additives. Stakeholders must monitor regulatory divergence between Brazilian PROCONVE emission tiers and Argentine equivalent standards, as diverging lubricant performance requirements will fragment product portfolio strategies across the customs union.
Market Dynamics
ANP biofuel blending mandates in Brazil are forcing additive package reformulations across the entire lubricant value chain, compressing product development cycles while elevating technical compliance costs for all market participants.
Growth Catalysts
- PROCONVE Emission Tier Alignment:Stricter Brazilian emission standards are accelerating demand for low-viscosity lubricants that reduce friction losses and support fuel economy targets in passenger vehicle fleets.
- Fleet Preventive Maintenance Expansion:Commercial vehicle operators in São Paulo state are extending drain intervals through synthetic formulations, creating pull-through demand for higher-margin product categories.
- Group II/III Base Oil Upgrades:Regional refinery investments in hydrocracking capacity are improving domestic supply quality, enabling formulators to meet API SP specifications without import dependency.
Market Restraints
- Additive Import Concentration:Brazil's lubricant industry relies on imported detergent and dispersant packages from US and European specialty chemical suppliers, exposing margins to currency volatility and freight cost spikes.
- Mineral Oil Price Sensitivity:Aftermarket consumers in Argentina's interior provinces prioritize cost over performance, capping premium product penetration and compressing formulation flexibility for local blenders.
- REACH-Aligned Chemical Restrictions:Mercosur technical committees are phasing out conventional zinc dialkyldithiophosphate anti-wear chemistries, forcing costly reformulation of proven additive systems without immediate performance substitutes.
Strategic Opportunities
- Colombian Andean Corridor Penetration:Bogotá's altitude-driven engine stress conditions create demand for high-performance synthetics currently underserved by regional distribution networks focused on coastal markets.
- Used Oil Collection Infrastructure:ANP re-refining incentives are creating closed-loop supply opportunities for integrated operators capable of managing collection logistics across Brazil's southeastern industrial corridor.
- Dual-Fuel Engine Lubrication:Natural gas-diesel hybrid powertrains in Argentine long-haul fleets require specialized soot-handling formulations that existing product portfolios do not adequately address.
Industry Challenges
- Formulation Chemist Scarcity:Brazilian universities produce insufficient lubricant science graduates, forcing blenders to compete for talent against pharmaceutical and specialty chemical sectors with superior compensation structures.
- API Certification Timeline Compression:Sequential specification updates from API SP to forthcoming categories are straining testing laboratory capacity, delaying product launches and freezing development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Automotive Engine Oils Market |
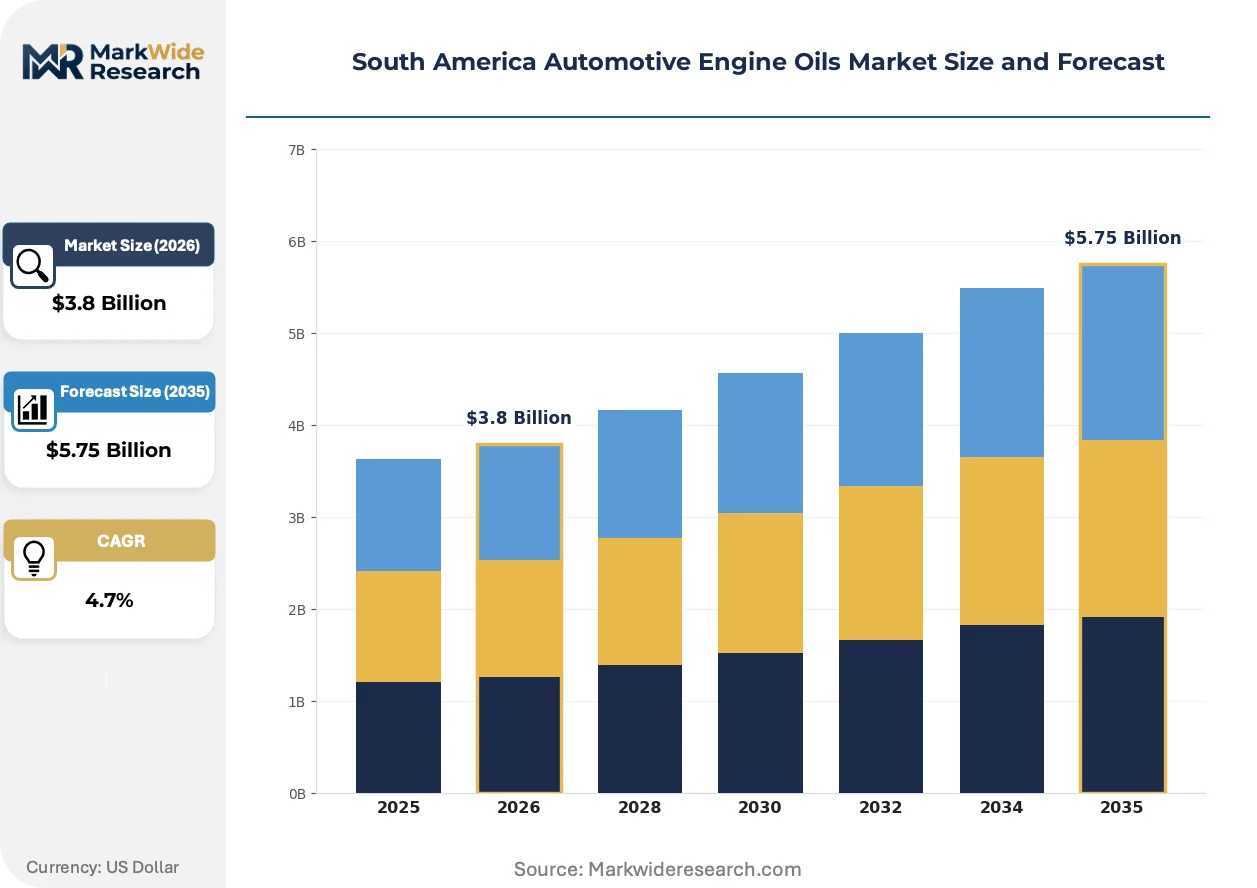
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral, Semi-synthetic, Bio-based Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Distribution Channel: Retail Stores, Online Platforms, Wholesale, Service Stations Application: Passenger Vehicles, Commercial Vehicles, Heavy Machinery, Motorcycles |
| Companies Covered | BP PLC (Castrol), Iconic Lubrificantes, Petrobras, TotalEnergies, Terpel, ExxonMobil Corporation, Chevron Corporation, Gulf Oil International, Royal Dutch Shell Plc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Automotive Engine Oils Market Evolving Landscape
Biofuel compatibility requirements and electrification pressures are converging to redefine lubricant performance benchmarks, with formulation chemistry racing to address combustion byproduct chemistry shifts and thermal management demands in hybrid architectures.
Polyalkylene glycol base stocks are hybridizing conventional hydrocarbon lubricant architectures to manage ethanol-induced fuel dilution and acidic byproduct accumulation. Brazilian flex-fuel vehicle owners operating on E100 blends are adopting these formulations at accelerating rates in São Paulo's urban corridors. The technology is hybridizing margin structures by creating a mid-tier product category between mineral and full synthetic segments.
ANP Resolution 784 established mandatory biofuel content thresholds that cascade into lubricant oxidative stability requirements. The regulation forces reformulation of antioxidant packages to counteract increased acid number elevation from ethanol combustion residues. Argentine lubricant importers face parallel pressure from Secretaría de Energía specifications that diverge on testing protocols, fragmenting product strategies across Mercosur.
Service station networks in Brazil's southeastern states are unbundling oil change services from mechanical repair, creating standalone quick-lube formats with inventory turns that favor high-volume synthetic SKUs. Fleet procurement departments in Argentina are consolidating supplier relationships to capture volume rebates, displacing fragmented distributor relationships that previously dominated commercial channels. Chilean mining corridor operators are piloting condition-based drain interval programs using oil analysis subscriptions, shifting from calendar-based to predictive maintenance economics.
South America Automotive Engine Oils Market Segmentation
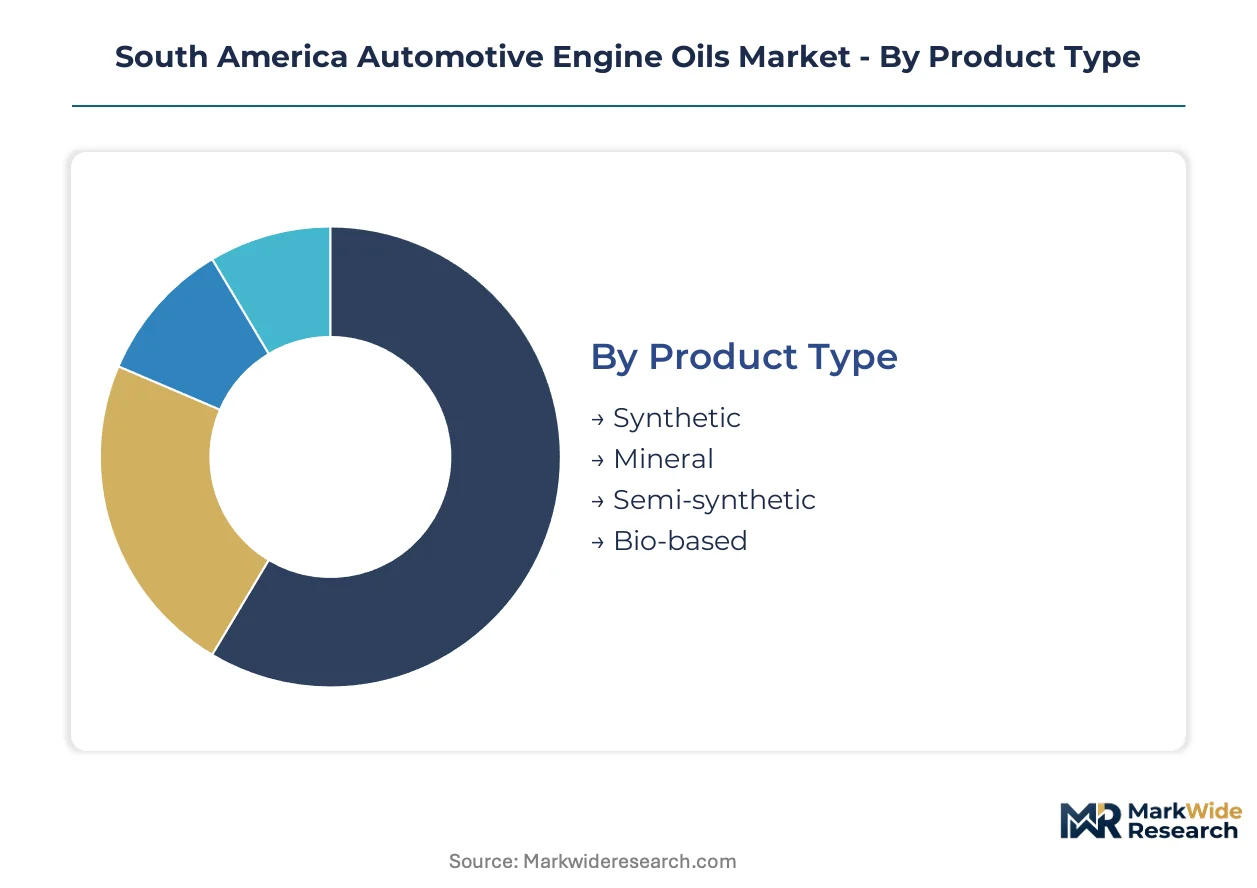
South America automotive engine oils segment along four dimensions that shape formulation priorities, channel economics, and customer procurement patterns. Product chemistry and viscosity specifications determine technical compliance costs, while distribution architecture and end-use application define margin capture and volume concentration across Brazil, Argentina, and Chile.
Product Type:
Mature mineral formulations coexist with emerging synthetic and bio-based chemistries as refinery investments and ANP biofuel mandates reshape the maturity spectrum.
- Synthetic:Formulations built on Group III or polyalphaolefin base stocks deliver extended drain intervals and API SP compliance for OEM fill specifications. Demand concentrates in São Paulo's fleet maintenance corridors where operators calculate total cost of ownership across longer service cycles.
- Mineral:Conventional Group I and II base oil formulations dominate price-sensitive aftermarket volumes through established retail and wholesale channels. Argentina's interior provinces sustain this segment as cost-conscious independent workshops prioritize unit price over performance metrics.
- Semi-synthetic:Hybrid formulations blend mineral and synthetic base stocks to bridge performance and price positioning for mid-market consumers.
- Bio-based:Renewable feedstock lubricants emerging under ANP sustainability incentives and PROCONVE alignment pressures.
Mineral oils handle the majority of throughput; synthetics are expanding most quickly on share as fleet operators recalibrate maintenance economics.
Viscosity Grade:
Cost tier stratification runs from premium low-viscosity grades to economy-weight higher viscosities as OEM specifications and climate conditions segment demand.
- 0W-20:Ultra-low viscosity formulations engineered for friction reduction and fuel economy compliance in modern passenger vehicle engines. Brazilian PROCONVE Tier alignment accelerates specification adoption among São Paulo's urban vehicle fleets.
- 5W-30:Versatile mid-viscosity grade balancing cold-start protection and high-temperature stability across varied duty cycles. Argentina's Secretaría de Energía fuel economy testing protocols favor this grade for import compliance.
- 10W-40:Conventional multi-grade serving older vehicle parc and commercial applications with moderate thermal stress tolerance.
- 15W-50:High-viscosity formulations for severe-service conditions including Chilean mining corridor operations and high-mileage engine protection.
5W-30 commands the largest installed base; 0W-20 is climbing the fastest as emission standards tighten.
Distribution Channel:
Customer type fragmentation separates individual consumers from institutional procurement as channel control determines brand access and pricing power.
- Retail Stores:Hypermarket and auto parts chains serve DIY consumers with packaged lubricants, capturing volume through promotional pricing and brand visibility.
- Online Platforms:E-commerce channels emerging for technical buyers seeking specification transparency and bulk pricing flexibility.
- Wholesale:Distributor networks supply independent workshops and regional resellers across Brazil's southeastern industrial corridor and Argentina's provincial markets.
- Service Stations:Branded quick-lube formats unbundling oil change from mechanical repair, concentrating synthetic SKU turnover in São Paulo state.
Service stations are gaining share fastest; wholesale retains the deepest volume foundation.
Application:
Volume-massive passenger segments diverge from margin-rich commercial and specialized machinery as duty cycle severity segments formulation requirements.
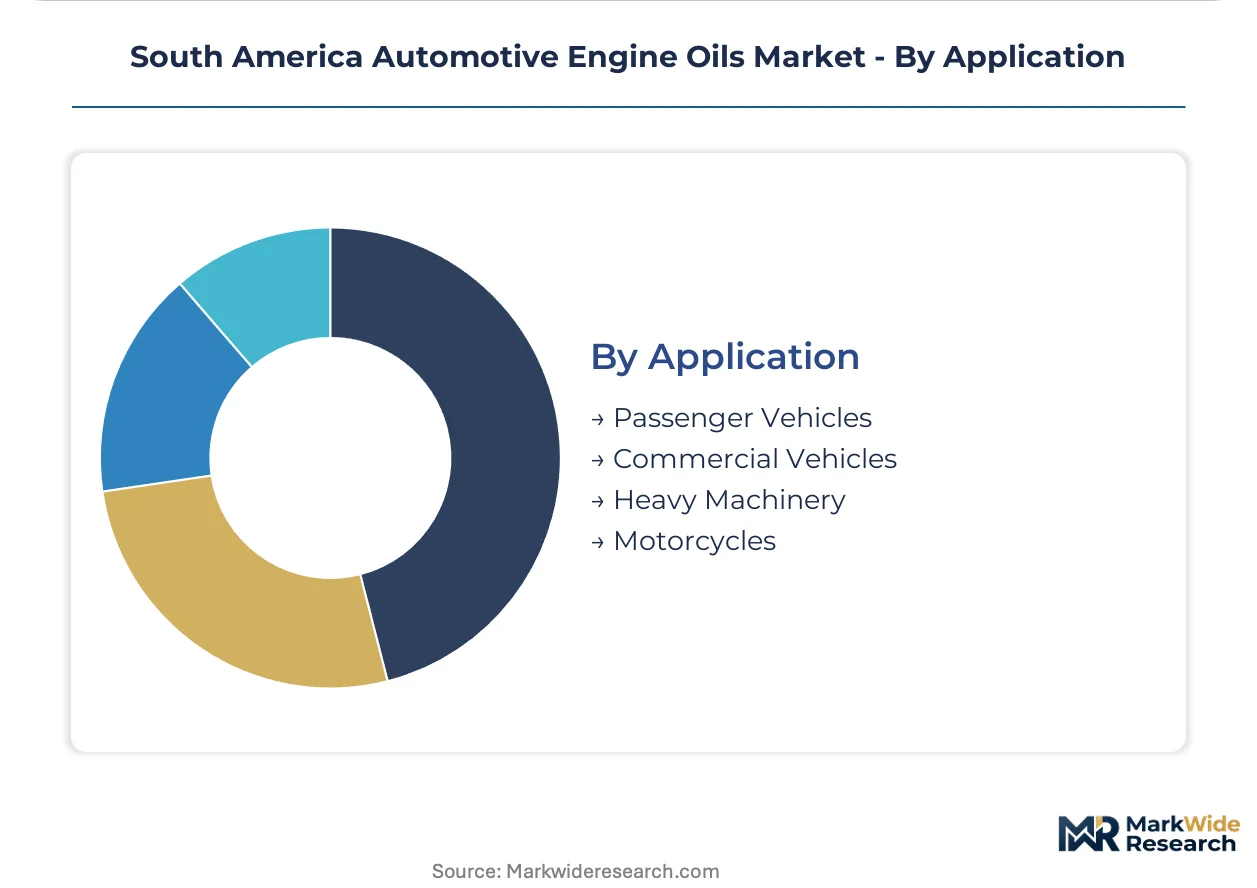
- Passenger Vehicles:Light-duty gasoline and flex-fuel engines generating highest absolute lubricant consumption across Brazil's vehicle parc. E100 ethanol compatibility demands drive antioxidant package reformulation under ANP Resolution 784.
- Commercial Vehicles:Heavy-duty diesel fleets in Argentine long-haul and Brazilian distribution operations consume higher per-unit volumes with stricter maintenance protocols. Natural gas-diesel hybrid powertrains create unmet demand for specialized soot-handling formulations.
- Heavy Machinery:Mining and construction equipment in Chile's northern corridor requiring severe-service lubrication with extended drain interval programs.
- Motorcycles:Two-stroke and four-stroke lubricants for personal transportation and delivery fleet applications across Andean urban centers.
Passenger vehicles anchor absolute volume; commercial vehicles are gaining share fastest as fleet consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports formulated lubricants to Argentina and Chile through Mercosur trade corridors, while Colombia and Peru import base stock components from Gulf Coast refineries. Argentine blenders source additive packages from US specialty chemical suppliers, exposing procurement costs to currency volatility. Chilean mining operators in the northern corridor drive demand for severe-service formulations that regional supply chains struggle to fulfill.
Brazil
São Paulo state's vehicle assembly density anchors lubricant consumption across the southeastern industrial corridor. ANP Resolution 784 mandates biofuel blending thresholds that cascade into oxidative stability requirements for engine oils. Petrobras operates captive refinery capacity in São Paulo and Rio de Janeiro states, enabling domestic Group II/III base oil production.
Argentina
Long-haul freight fleets in Buenos Aires province generate concentrated demand for heavy-duty diesel lubricants with extended drain intervals. The Secretaría de Energía enforces fuel economy testing protocols that favor 5W-30 viscosity grades for import compliance. Córdoba's automotive parts manufacturing cluster sustains aftermarket distribution networks serving interior provinces.
Chile
Copper mining operations in Antofagasta Region consume severe-service lubricants for haul trucks operating in high-altitude, high-dust conditions. The Ministry of Mining's environmental compliance frameworks pressure operators toward condition-based maintenance programs. Santiago's metropolitan fleet operators pilot predictive oil analysis subscriptions, shifting procurement from calendar-based to usage-based models.
Colombia
Bogotá's altitude-driven engine stress creates demand for high-performance synthetics currently underserved by coastal-focused distribution networks. The Ministry of Mines and Energy regulates fuel quality standards that indirectly shape lubricant additive requirements. Medellín's manufacturing corridor hosts emerging quick-lube service formats targeting mid-market consumers.
Peru
Lima's commercial vehicle parc generates lubricant demand concentrated in mineral formulations for price-sensitive independent workshops. The Organismo Supervisor de la Inversión Privada en Telecomunicaciones oversees fuel quality enforcement that affects lubricant compatibility specifications. Arequipa's mining and construction equipment operators require specialized severe-service products with limited local formulation capacity.
South America Automotive Engine Oils Market Competitive Landscape
On the supply side, the industry is structured around three distinct competitive tiers anchored by integrated energy majors, national oil companies, and specialized regional blenders. International energy majors leverage global base stock supply chains and technology licensing networks to serve premium synthetic segments. National oil companies exploit captive refinery access to dominate domestic volume distribution. Regional specialists compete on formulation flexibility and local regulatory compliance speed. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players investing in hydrocracking upgrades and additive technology licensing to meet API SP specifications.
Among integrated energy majors, BP PLC (Castrol), ExxonMobil Corporation, and Royal Dutch Shell Plc exemplify the technology-licensing archetype, occupying positions defined by synthetic base stock production capabilities and premium branding through controlled service station networks. Petrobras anchors the national oil company tier, representing backward integration into refinery operations that supply Brazilian distribution corridors. Regional specialists including Iconic Lubrificantes and Terpel sit within the formulation-flexibility segment, serving price-sensitive aftermarket channels with mineral and semi-synthetic portfolios tailored to local duty cycles.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| Iconic Lubrificantes |
| Petrobras |
| TotalEnergies |
| Terpel |
| ExxonMobil Corporation |
| Chevron Corporation |
| Gulf Oil International |
| Royal Dutch Shell Plc |
| Others |
Value Network & Pricing Analysis
Currency volatility between Brazilian real and US dollar determines both the spread between synthetic and mineral oil pricing tiers and the geographic shape of additive sourcing networks across the Mercosur trade corridor. ANP import dependency for detergent packages forces blenders to absorb exchange rate swings or push cost escalation downstream into service station quick-lube formats.
Pricing Analysis
The technology-generation pricing gap separates API SP-compliant synthetic formulations from legacy mineral grades and emerging bio-based chemistries. Three-tier pricing structure across premium, standard, and economy levels reflects base stock quality, OEM certification status, and drain interval claims. Pricing pressure stems from Argentine interior provinces where independent workshops prioritize unit cost over performance specifications. Fleet operators in São Paulo state exhibit lowest price sensitivity due to total cost of ownership calculations across extended service cycles.
Supply Chain Analysis
Tariff exposure between Brazil and US Gulf Coast specialty chemical suppliers dominates supply chain risk calculations for detergent and dispersant procurement. Brazil, Argentina, and Chile concentrate lubricant formulation capacity, while additive packages draw from US and European chemical majors. Raw material dependencies center on Group II/III base oils, polyalphaolefin stocks, and zinc dialkyldithiophosphate anti-wear chemistries. Distribution runs through Petrobras-controlled refinery networks in the southeastern industrial corridor, supplemented by wholesale distributor channels serving Argentina's provincial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ANP biofuel mandates and PROCONVE emission tier alignment create compliance barriers that favor incumbents with established testing laboratory relationships and reformulation capabilities.
For Market Incumbents: Pre-empt margin compression in mineral oil segments by accelerating Group III base oil capacity additions at captive Brazilian refineries. Defend against specialty chemical entrants by locking exclusive additive package licensing agreements with US and European suppliers before REACH-aligned Mercosur restrictions force industry-wide reformulation cycles.
For New Entrants and Emerging Players: Pursue white-space penetration in Colombia's Andean corridor where Bogotá altitude-driven engine stress creates demand for high-performance synthetics currently underserved by coastal-focused distribution networks. Target quick-lube service format partnerships in Medellín's manufacturing corridor as the most penetrable go-to-market angle bypassing established wholesale distributor relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated operators with backward refinery access and re-refining capabilities. Long-term viability hinges on closed-loop supply economics as ANP incentives for used oil collection infrastructure mature. Watch condition-based maintenance program adoption in Chilean mining corridors as the signal indicating predictive procurement model inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive Group II/III supply from Petrobras refineries eliminates import dependency and currency exposure. |
| Additive Package Technology Licensing | Exclusive agreements with US specialty chemical suppliers secure reformulation capabilities ahead of regulatory deadlines. |
| Quick-Lube Service Format Expansion | Standalone oil change unbundling in São Paulo accelerates synthetic SKU turnover and brand control. |
| Used Oil Collection Infrastructure Buildout | ANP re-refining incentives reward integrated operators managing logistics across southeastern industrial corridors. |
| Dual-Fuel Engine Formulation Development | Natural gas-diesel hybrid powertrains in Argentine long-haul fleets require specialized soot-handling chemistries. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with lubricant formulators, refinery operations managers, fleet procurement directors, and aftermarket distributor principals; and secondary validation against ANP regulatory filings, Secretaría de Energía import compliance records, customs trade data, and PROCONVE emission tier documentation. Bottom-up volume modeling triangulated with top-down value estimates derived from refinery capacity disclosures and service station network expansion plans.
Forecast inputs incorporated base stock supply evolution, biofuel blend ratio trajectories under ANP Resolution 784, and fleet maintenance protocol shifts across passenger, commercial, and heavy machinery applications. Segmentation dimensions spanned product chemistry tier, viscosity grade specification, distribution channel control, and end-use duty cycle severity. CAGRs were derived from elasticity modeling of lubricant consumption against vehicle parc growth and drain interval extension trends.
Sensitivities concentrate around Brazilian real exchange rate volatility, additive import tariff adjustments, and divergent Mercosur regulatory harmonization timelines. Forecasts reflect assumptions about refinery upgrade completion schedules and fleet operator synthetic adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Smart Adaptive Headlights Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market
Automotive Parts
Germany Automotive Hydraulic Actuators Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Saudi Arabia Passenger Vehicles Lubricants Market
Automotive Parts
Air Brake Market
Automotive Parts
Automotive Thermal Management Systems for Electric Vehicles Market
Automotive Parts
Suspension Spring Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Canada Automotive Actuators Market